
 Europe Paper Cone Market | 2026-2036
Europe Paper Cone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paper Cone Market Foresight
Digital printing integration is fragmenting traditional paper cone specification workflows across European converters. Smurfit Kappa Group leverages its integrated containerboard and converting network to control large-format industrial cone supply. Sonoco Alcore anchors Nordic and Benelux demand through its recycled fiber-based production platform. Pirro S.r.l. specializes in precision custom cones for Italian textile machinery OEMs.
A paper cone is a tapered cylindrical form manufactured from wound paper layers, typically featuring wall thicknesses between 1.5 mm and 4 mm and internal diameters calibrated to textile bobbin or food packaging specifications, engineered to provide structural rigidity for winding, storage, or dispensing applications. Single-Wall Cones dominate high-volume textile winding across Eastern Europe where cost sensitivity shapes procurement, while Double-Wall Cones capture margin pools in industrial coating and adhesive applications requiring crush resistance. Kraft Paper grades sustain leadership in food-contact segments governed by EFSA migration limits, whereas Recycled Paper feeds the EU Green Deal-driven circular packaging mandates gaining traction in France and the Netherlands.
EMA food-contact frameworks, REACH chemical compliance obligations, and the EU Green Deal packaging sustainability targets collectively elevate barrier-coated and fiber-certified cone specifications above commodity alternatives. ECHA substance restrictions on perfluorinated compounds are forcing coating reformulations across specialty paper grades used in grease-resistant food packaging cones. Stakeholders must monitor evolving Extended Producer Responsibility schemes and fiber traceability certification requirements as gatekeepers for premium segment access.
Market Dynamics
EU Green Deal packaging mandates and REACH chemical restrictions are compressing specification cycles across European paper cone converters, forcing rapid material transitions from conventional coatings to fiber-certified alternatives.
Growth Catalysts
- EU Green Deal packaging targets:Mandatory recycled content thresholds for food-contact packaging redirect procurement toward kraft and post-consumer fiber grades across France and the Netherlands.
- Textile machinery OEMs in Italy:Precision custom cone demand from Lombardy-based equipment manufacturers sustains premium specification volumes despite broader industrial slowdown.
- ECHA perfluorinated compound restrictions:Coating reformulation requirements grease-resistant food packaging cones accelerate barrier innovation and certified fiber adoption.
Market Restraints
- Pulp input cost volatility:Nordic kraft pulp price swings compress converter margins and destabilize long-term contract pricing.
- Benelux coating chemical supply concentration:Three specialty chemical suppliers control barrier formulation inputs, creating bottleneck risk for EFSA-compliant food-contact grades.
- Recycled fiber technical ceiling:Mechanical strength degradation limits recycled content ratios above 80% in high-speed textile winding applications.
Strategic Opportunities
- Polish and Romanian textile clusters:Underpenetrated Eastern European winding operations present volume expansion paths for cost-optimized single-wall specifications.
- Digital printing integration:Short-run customization capabilities enable converter-direct relationships with mid-tier food brands, bypassing traditional specification intermediaries.
- Extended Producer Responsibility schemes:France and Italy's advancing EPR frameworks reward fiber traceability certification with preferential market access.
Industry Challenges
- Coating chemist talent scarcity:REACH-compliant barrier formulation expertise concentrates in German and Dutch technical centers, creating recruitment bottlenecks for Southern European converters.
- EFSA migration testing timelines:Extended certification cycles for novel food-contact coatings delay product launches by 12-18 months.
- Legacy winding equipment incompatibility:Retrofitting Italian and Spanish textile mills for precision double-wall cones requires mechanical adaptation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paper Cone Market |
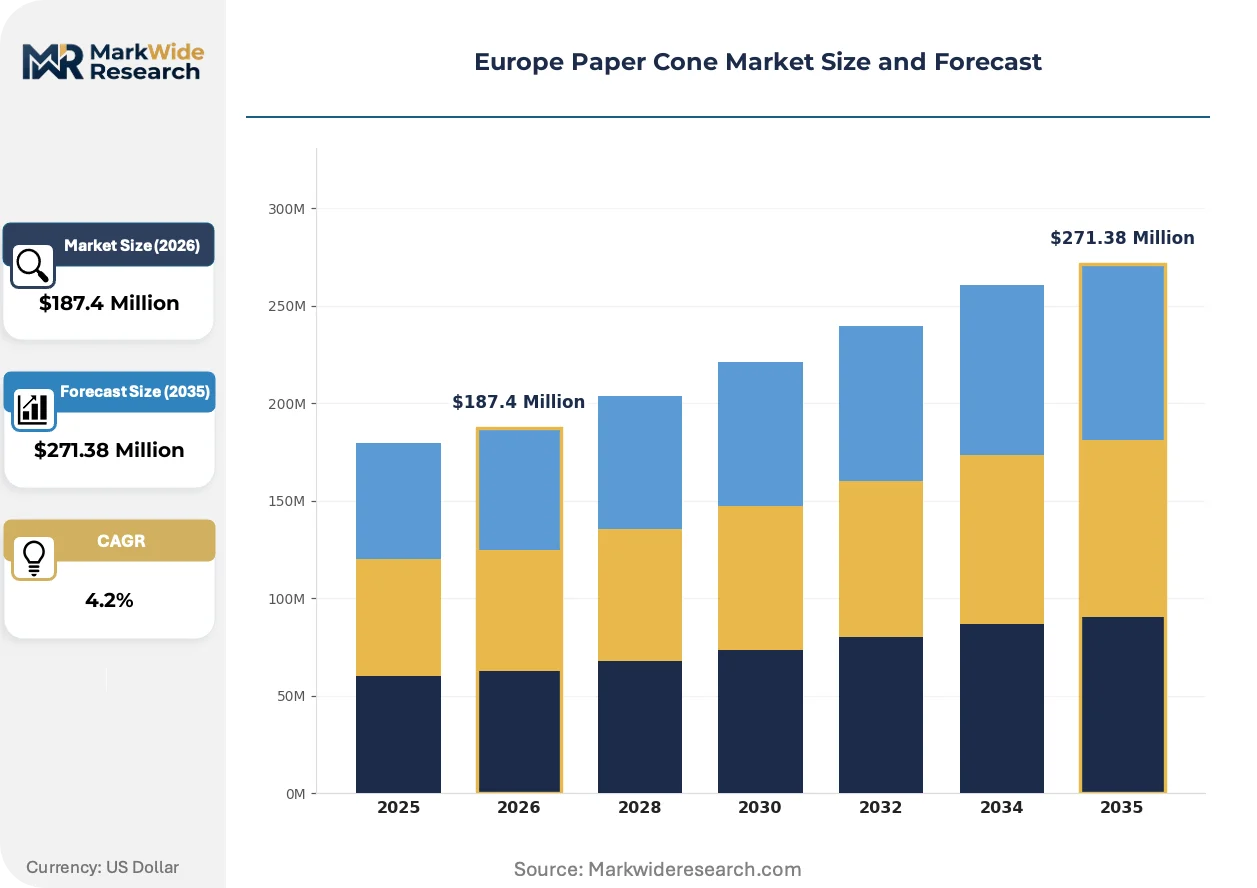
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall Cones, Double-Wall Cones, Custom Cones, Printing Cones Application: Food Packaging, Textile Industry, Industrial Uses, Decorative Purposes Material: Kraft Paper, Recycled Paper, Coated Paper, Specialty Paper Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Yasar Group, Smurfit Kappa Group, Conitex Sonoco, Sonoco Alcore, Paul & Co, FAVRETTO, Corex Group, Pirro S.r.l., Tubettificio Senese S.r.l., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paper Cone Market Shifts & Advancements
Digital specification workflows and barrier coating chemistry are converging to compress traditional paper cone procurement cycles, while regulatory compliance automation reshapes supplier-buyer relationships across European industrial corridors.
Water-based barrier coatings are collapsing the performance gap between conventional polyethylene-lined cones and fiber-certified alternatives for grease-resistant food packaging. German and Dutch food packaging converters are adopting these formulations at accelerated pilot scales. The technology is collapsing specification lead times from 18-month certification cycles to 6-month validation windows.
REACH Article 33 substance disclosure obligations now mandate granular chemical composition reporting across all packaging tiers entering EU circulation. Industrial converters face expanded documentation burdens for coating additives and fiber treatments. Food-contact cone specifications in France and Italy are responding with pre-certified supply chain partnerships that front-load compliance verification.
Direct-to-converter digital procurement platforms are fragmenting traditional distributor channels for standard-grade textile cones. Mid-volume winding operations in Poland and the Czech Republic now source through online specification tools that bypass regional paper merchants. This channel shift is most visible in Eastern Europe where price transparency pressures legacy distribution markups.
Europe Paper Cone Market Segmentation
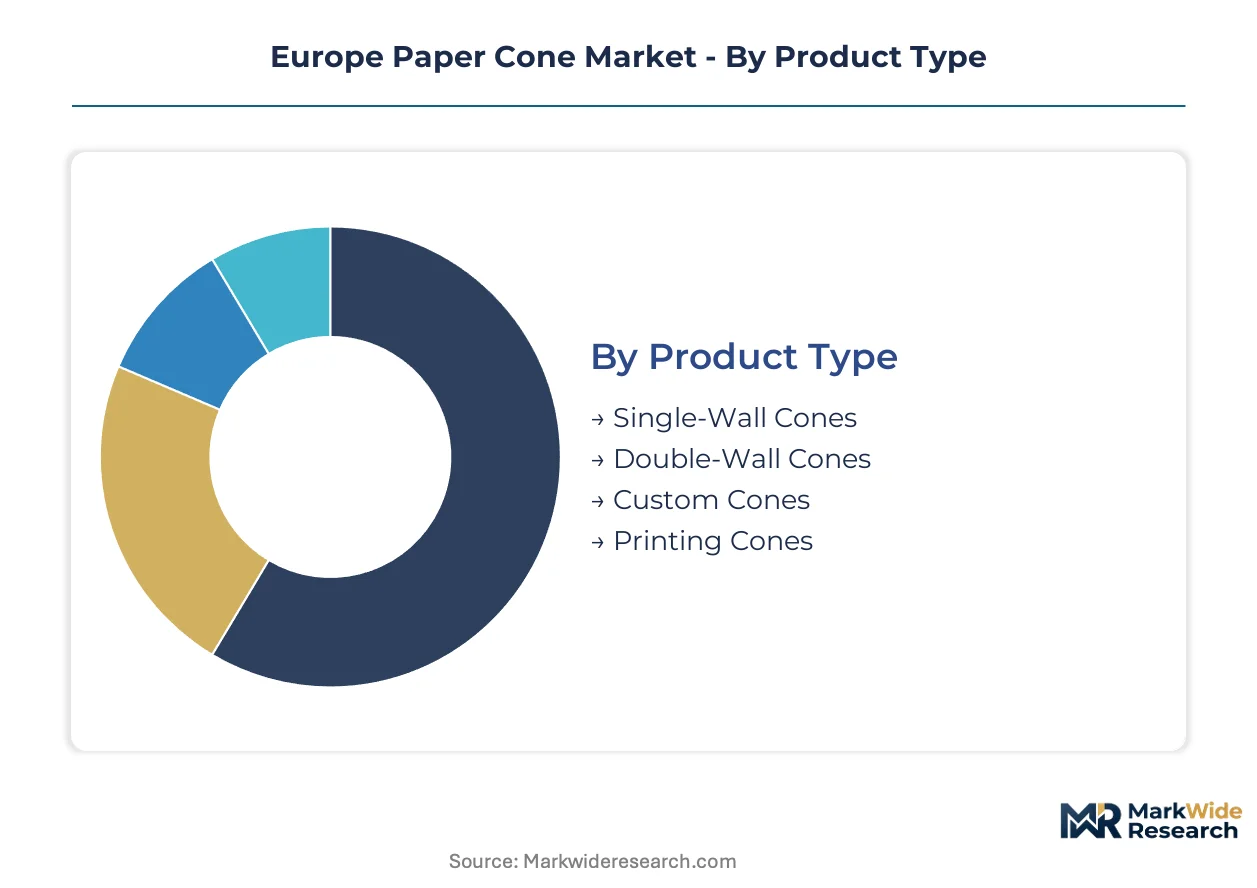
Structural variation across Europe's paper cone market reflects divergent compliance burdens and performance requirements. Specification tiers separate commodity textile winding from precision food-contact applications governed by EFSA migration limits. Understanding segment boundaries clarifies where margin pools concentrate versus where volume scales.
Product Type:
Wall construction and dimensional precision define cost tiers and application suitability across converter procurement workflows.
- Single-Wall Cones:Wound from single-ply kraft or recycled fiber layers with wall thicknesses of 1.5–2.5 mm. Demand concentrates in Poland and Romania's high-speed textile winding corridors where cost sensitivity dominates procurement decisions and equipment compatibility favors lighter specifications.
- Double-Wall Cones:Engineered with dual-ply construction delivering 3–4 mm wall thickness and superior crush resistance. Italian industrial coating operations and German adhesive applications specify these for structural integrity under mechanical load and chemical exposure.
- Custom Cones:Precision-machined to textile machinery OEM tolerances for Lombardy-based equipment manufacturers.
- Printing Cones:Surface-optimized substrates for digital and flexographic decoration in premium food packaging.
Single-Wall Cones command the established base. The steepest expansion runs through Custom Cones.
Application:
End-use specifications fragment procurement patterns across regulatory intensity and performance thresholds.
- Food Packaging:Grease-resistant and moisture-barrier cones for dairy, confectionery, and fast-casual dispensing. France and the Netherlands drive specification volumes under EU Green Deal recycled content mandates and EFSA compliance frameworks.
- Textile Industry:Yarn winding, spinning, and weaving support across Eastern European manufacturing clusters. Poland's underpenetrated winding operations present volume expansion paths for cost-optimized specifications despite mechanical strength constraints at high recycled content ratios.
- Industrial Uses:Coating, adhesive, and film winding applications requiring dimensional stability.
- Decorative Purposes:Seasonal and gift packaging with printed surface requirements.
Textile Industry absorbs the highest shipment volumes. Food Packaging climbs the fastest on regulatory tailwinds.
Material:
Fiber provenance and treatment chemistry determine compliance pathways and end-market access.
- Kraft Paper:Virgin fiber grades meeting EFSA migration limits for direct food contact. German and Dutch converters prioritize these for dairy and fat-containing applications where barrier performance and regulatory certainty outweigh cost premiums.
- Recycled Paper:Post-consumer fiber grades advancing under EU Green Deal circular packaging mandates. Technical ceilings at 80% recycled content constrain high-speed textile applications, but France and Italy's Extended Producer Responsibility schemes reward fiber traceability certification.
- Coated Paper:Water-based and conventional barrier treatments for grease resistance.
- Specialty Paper:Engineered substrates with customized mechanical or surface properties.
Kraft Paper holds the premium position. Recycled Paper gains share fastest on circular economy policy.
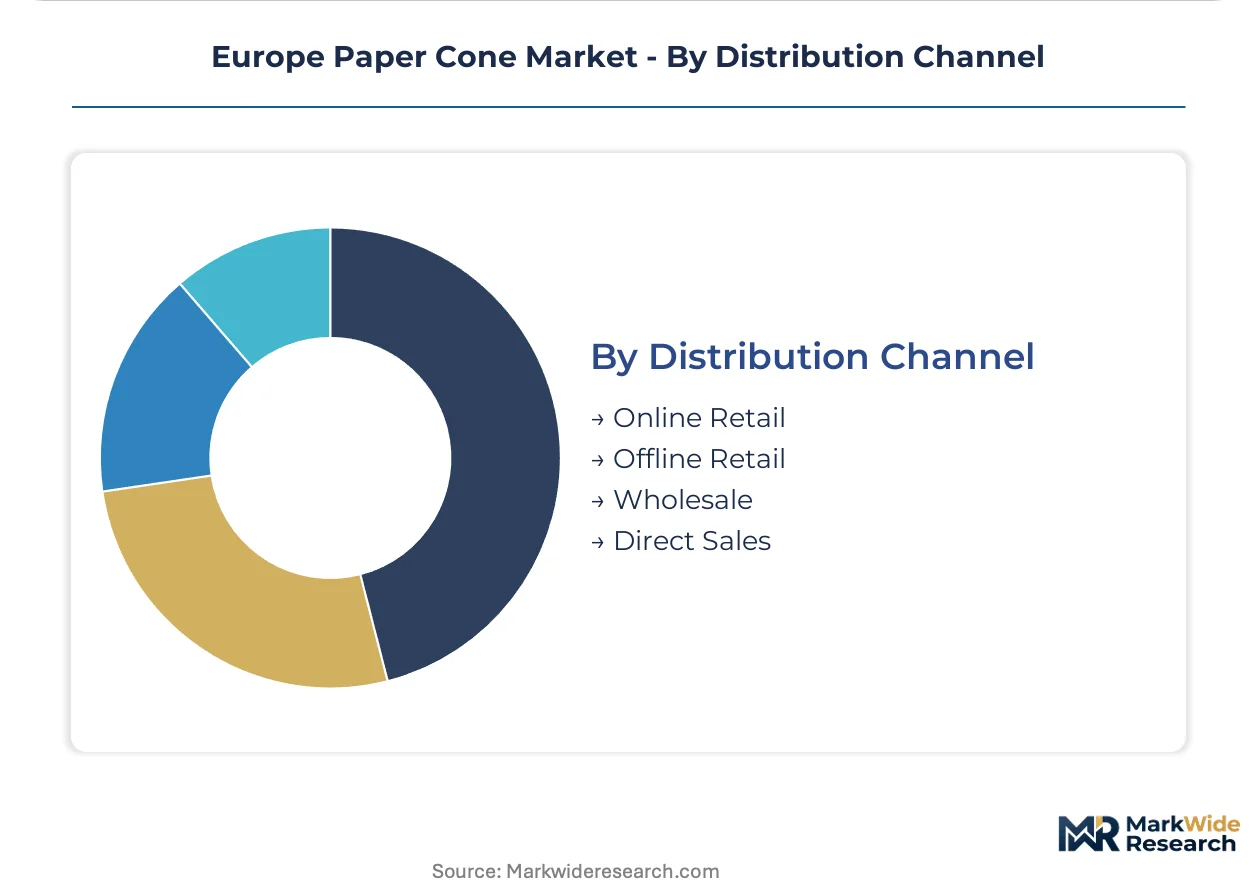
Distribution Channel:
Channel selection reflects order scale, specification complexity, and geographic market maturity.
- Online Retail:Digital procurement platforms fragmenting traditional distributor channels for standard-grade textile cones. Mid-volume winding operations in the Czech Republic and Poland now source through specification tools that bypass regional paper merchants and compress legacy markups.
- Direct Sales:Converter-direct relationships for high-volume food packaging and precision custom specifications. Smurfit Kappa and Sonoco Alcore leverage integrated networks to control large-format industrial supply and anchor Nordic-Benelux demand.
- Offline Retail:Regional paper merchants and specialty distributors for fragmented small-lot demand.
- Wholesale:Aggregated procurement for standard specifications across multi-site textile operations.
Direct Sales dominates premium contract value. Online Retail expands most quickly on price transparency pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food packaging converters and textile machinery OEMs concentrate procurement power across Germany's industrial corridor and Italy's manufacturing clusters, with Eastern European winding operations emerging as volume expansion targets for cost-optimized specifications.
Germany
Dairy and fat-containing food packaging applications drive kraft paper cone specifications from converters prioritizing EFSA compliance certainty. REACH Article 33 substance disclosure mandates granular chemical composition reporting across all packaging tiers entering circulation. The North Rhine-Westphalia industrial packaging corridor hosts integrated containerboard networks controlling large-format industrial cone supply.
Italy
Precision custom cone demand from Lombardy-based textile machinery OEMs sustains premium specification volumes despite broader industrial slowdown. Extended Producer Responsibility frameworks advancing in national legislation reward fiber traceability certification with preferential market access. The Piedmont and Veneto textile manufacturing clusters require precision-machined cones calibrated to equipment manufacturer tolerances.
France
EU Green Deal recycled content thresholds redirect procurement toward post-consumer fiber grades for food-contact packaging applications. ECHA perfluorinated compound restrictions force coating reformulations across grease-resistant food packaging cone specifications. The Île-de-France region concentrates converter operations serving fast-casual dispensing and confectionery segments.
Poland
High-speed textile winding corridors absorb single-wall cone volumes where cost sensitivity dominates procurement decisions and equipment compatibility favors lighter specifications. Technical ceilings at 80% recycled content constrain mechanical strength in demanding applications. The Łódź textile manufacturing basin presents underpenetrated volume expansion paths for cost-optimized specifications.
Netherlands
Water-based barrier coating pilot programs accelerate adoption of fiber-certified alternatives collapsing specification lead times from 18-month certification cycles to 6-month validation windows. EU Green Deal circular packaging mandates gain traction among Dutch food packaging converters. The Randstad logistics hub facilitates distribution of certified fiber grades across Benelux industrial corridors.
Europe Paper Cone Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification tiers defined by compliance intensity and dimensional precision. The vendor base organizes around integrated containerboard networks, recycled fiber production platforms, and precision custom fabricators serving machinery OEMs. Three strategic archetypes dominate: scale-driven integrated converters, fiber-certified specialists, and precision custom engineers. Capacity expansion in Eastern European corridors and coating chemistry partnerships represent the dominant competitive moves reshaping supply relationships.
Among integrated converters, Smurfit Kappa Group exemplifies channel control through captive containerboard supply, while Sonoco Alcore anchors Nordic and Benelux demand through recycled fiber-based production positioning. Pirro S.r.l. occupies the precision custom tier serving Italian textile machinery OEMs with tolerance-critical specifications. These three represent the archetype spectrum from scale-driven integration through fiber certification to precision engineering.
| Leading Market Players |
|---|
| Yasar Group |
| Smurfit Kappa Group |
| Conitex Sonoco |
| Sonoco Alcore |
| Paul & Co |
| FAVRETTO |
| Corex Group |
| Pirro S.r.l. |
| Tubettificio Senese S.r.l. |
| Others |
Supply & Pricing Matrix
Undercapacity in Nordic kraft pulp production compresses converter margins and forces rapid contract renegotiation across German and Dutch food packaging corridors. Suppliers leverage tight fiber markets to push through quarterly price adjustments indexed to PIX Pulp Europe benchmarks.
Pricing Analysis
Cost-plus contracts with PIX Pulp Europe indexation dominate long-term supply agreements between Nordic producers and continental converters. Three-tier pricing structure across EFSA-certified premium, REACH-compliant standard, and economy recycled grades separates compliance tiers. Pricing pressure stems from pulp input volatility as Swedish and Finnish mills run at 90% capacity utilization. Small-lot textile winders in Poland exhibit highest price sensitivity; German dairy packaging converters absorb premiums for migration-certain kraft specifications.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize supplier relationships as mills finance working capital through supply-chain facilities. Geographic supply concentrates in Sweden, Finland, and Germany for virgin kraft fiber; Benelux coating chemical suppliers control barrier formulation inputs. Raw material dependencies rest on Nordic softwood pulp, water-based barrier chemistries, and post-consumer fiber streams. Single-source vulnerability concentrates in Benelux specialty chemical supply for EFSA-compliant food-contact grades. Distribution runs through converter-direct contracts for premium specifications and digital platforms fragmenting Eastern European textile channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German and Dutch food packaging converters as Smurfit Kappa and Sonoco Alcore consolidate channel control through integrated supply networks. Fragmentation among mid-tier Polish textile winders weakens collective negotiation leverage against upstream pulp suppliers.
For Market Incumbents: Harden EFSA migration certification as a switching-cost barrier against recycled-fiber entrants targeting Dutch and French food-contact segments. Deepen backward integration into Nordic kraft pulp supply through long-term offtake agreements with Finnish and Swedish mills. Prioritize water-based barrier coating R&D partnerships with Benelux chemical specialists to defend margin pools against coating reformulation mandates. For New Entrants and Emerging Players: Build out digital procurement platforms targeting underpenetrated Polish and Romanian textile winding corridors where price transparency pressures legacy distribution markups. Capture volume expansion in single-wall specifications for high-speed winding applications. Lead with 6-month validation windows against incumbent 18-month certification cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fiber-certified specialists with pre-qualified EFSA supply chain partnerships serving French and Italian food packaging converters. Long-term viability favors acquisition targets with captive coating chemistry capabilities and traceability certification under advancing Extended Producer Responsibility frameworks. Watch for ECHA substance restriction announcements as inflection indicators for barrier innovation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Kraft Pulp | Finnish and Swedish fiber supply locks in EFSA-compliant raw material security for German converters. |
| Water-Based Barrier Coating Scale-Up | Dutch pilot programs collapse certification timelines from 18-month cycles to 6-month validation windows. |
| Fiber Traceability Certification Investment | France and Italy's Extended Producer Responsibility schemes reward certified supply with preferential market access. |
| Digital Procurement Platform Launch | Polish and Czech textile winders bypass regional paper merchants through online specification tools. |
| REACH-Compliant Coating Partnership | Benelux chemical collaboration secures barrier formulation expertise against ECHA perfluorinated compound restrictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with paper cone procurement managers at German dairy packaging converters, Italian textile machinery OEMs, and Polish winding operation directors. Secondary validation drew from EFSA migration limit documentation, REACH Article 33 substance disclosure filings, EU Green Deal packaging mandate progress reports, and PIX Pulp Europe price indices. Bottom-up volume modeling across product type, application, material grade, and distribution channel segments was triangulated against top-down macroeconomic absorption rates.
Calibration against historical pulp price volatility and regulatory implementation timelines anchored projection frameworks across the analysis window. Segmentation dimensions modeled include wall construction tier, end-use regulatory intensity, fiber provenance certification, and channel control structure. CAGRs were derived from elasticity-adjusted demand curves incorporating EU Green Deal recycled content threshold compliance trajectories and Eastern European textile capacity expansion pipelines.
Stress conditions across Nordic pulp supply disruptions, ECHA coating reformulation acceleration, and Polish zloty-euro exchange rate volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and fiber substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Die Cut Box Market
Paper & Paperboard Packaging
Kraftliner Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Paper Cups Market