
 Pharmaceutical Printed Cartons Market | 2026-2036
Pharmaceutical Printed Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Printed Cartons Market Analytics
Biologics manufacturers is rotating toward high-barrier printed cartons as their share of pharmaceutical packaging procurement expands. WestRock Company leverages its integrated paperboard supply chain to serve temperature-sensitive drug portfolios. Amcor plc anchors its position through specialized barrier coatings for moisture-critical formulations. DS Smith Plc competes via modular carton architectures that accommodate serial aggregation requirements.
Pharmaceutical printed cartons are paperboard or composite-based secondary packaging structures engineered with specified grammage, fold endurance, and print registration tolerance to carry regulatory labeling, anti-counterfeiting features, and patient instructions. Folding cartons lead volume due to their adaptability across blister and bottle formats, while rigid boxes command premium positioning for injectable and orphan drug presentations. Composite materials represent the fastest-expanding material segment as multi-layer structures integrate child-resistance and senior-friendly opening mechanisms.
FDA DSCSA traceability mandates and EU MDR serialization requirements are reshaping carton design specifications, forcing investments in integrated coding and verification infrastructure. India's CDSCO and China's NMPA are tightening secondary packaging standards for export-bound pharmaceuticals, narrowing market access for non-compliant converters. Stakeholders must monitor evolving serialization deadlines and material sustainability thresholds to align capital allocation with regulatory compliance trajectories.
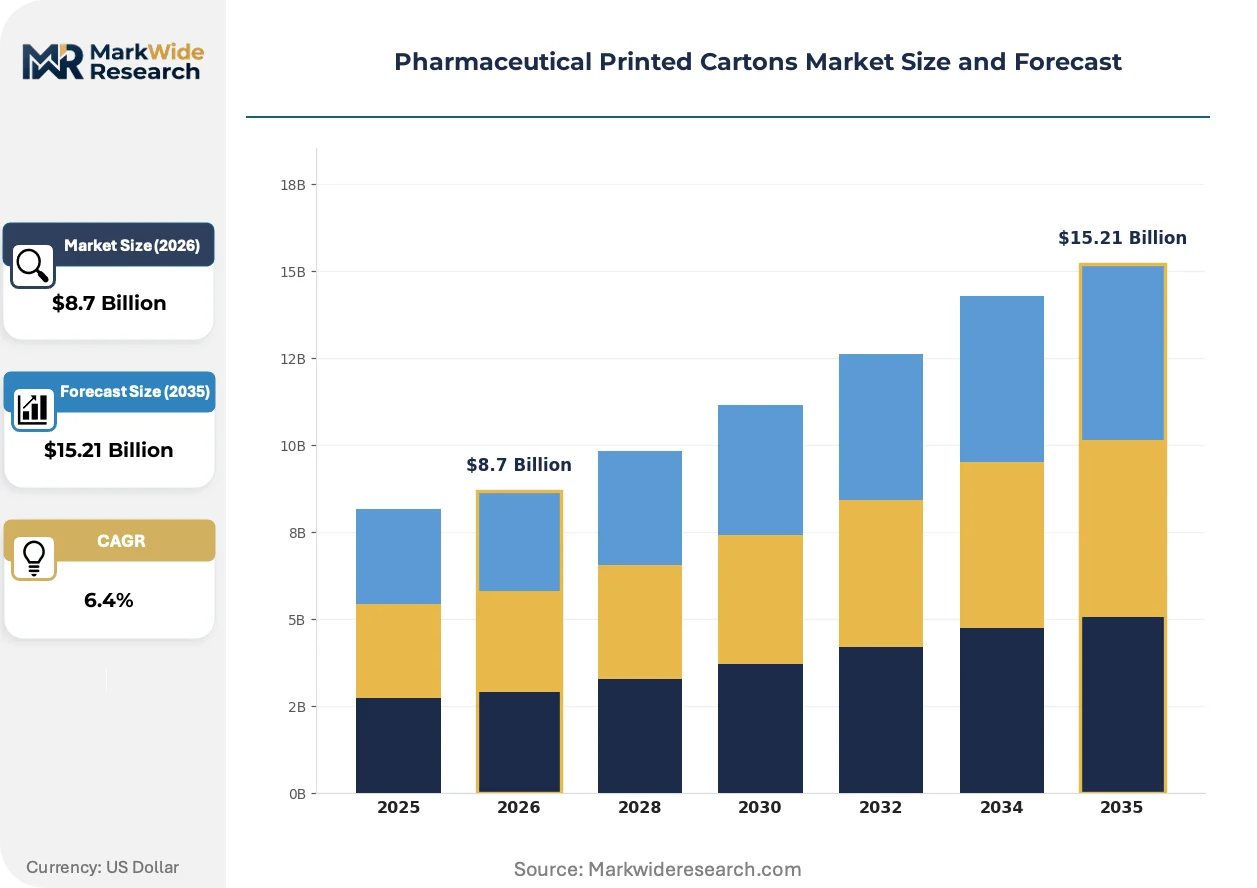
Market Dynamics
Serialization mandates from FDA and EU MDR are forcing carton converters to rebuild production lines around integrated coding infrastructure. This regulatory compression is concentrating procurement among converters with verified aggregation capabilities.
Growth Catalysts
- Biologics expansion:Temperature-sensitive protein therapies require high-barrier cartons with validated cold-chain stability. Manufacturers are qualifying multi-layer structures for mRNA and monoclonal antibody portfolios.
- EU MDR serialization:The mandate for unique device identifiers on secondary packaging is pulling investment toward track-and-trace-ready carton designs across European export supply chains.
- India CDSCO export standards:Tightened secondary packaging requirements for pharmaceuticals bound for regulated markets are upgrading domestic converter capabilities in Ahmedabad and Hyderabad clusters.
Market Restraints
- Pulp cost volatility:Kraft linerboard and folding boxboard prices fluctuate with energy costs and fiber availability, compressing converter margins on fixed-price pharmaceutical contracts.
- Specialty coating supply concentration:Moisture-barrier and heat-seal coatings depend on concentrated European and Japanese chemical suppliers, creating single-source risk for high-performance cartons.
- Aluminum-plastic substitution ceiling:Rigid aluminum tubes and cold-form blisters retain share in ultra-high-barrier applications, limiting paperboard penetration in certain injectable formats.
Strategic Opportunities
- Brazil ANVISA alignment:Export-oriented converters can capture share by pre-qualifying cartons for Brazil's evolving traceability requirements ahead of local capacity buildout.
- Connected packaging convergence:Near-field communication chips and printed electronics integration with pharmaceutical cartons enables adherence monitoring and authentication at unit level.
- Direct-to-pharmacy distribution:Hospital and specialty pharmacy networks are shortening supply chains, creating demand for carton formats optimized for small-lot, high-velocity fulfillment.
Industry Challenges
- Serialization engineering talent scarcity:Converters struggle to hire vision system engineers and aggregation software specialists capable of integrating line-level coding with enterprise traceability platforms.
- Legacy equipment retrofit burden:Existing folder-gluer and die-cutting assets require substantial modification to accommodate camera verification and reject systems, straining capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Printed Cartons Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carton Boxes, Folding Cartons, Rigid Boxes, Blister Packs Material: Paperboard, Plastics, Aluminum, Composite Materials Application: Prescription Drugs, Over-the-Counter Medications, Nutraceuticals, Vaccines End User: Pharmaceutical Companies, Contract Packaging Organizations, Clinics, Hospitals |
| Companies Covered | WestRock Company, Amcor plc, DS Smith Plc, Smurfit Kappa Group, Graphic Packaging International, Sonoco Products Company, Mondi Group, Huhtamaki Oyj, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Printed Cartons Market Evolving Landscape
Active and intelligent packaging technologies are penetrating pharmaceutical secondary packaging, driven by patient adherence mandates and supply chain visibility requirements. Material science advances are simultaneously addressing sustainability targets and barrier performance needs.
Water-based barrier coatings are supplanting solvent-based polyethylene and extruded polymer layers in moisture-critical applications. Biologics manufacturers are qualifying these coatings for stability chambers at accelerated rates. This shift is compressing the regulatory approval timeline for sustainable carton formats while maintaining USP <661> compliance.
EU MDR's unique device identifier requirements are mandating two-dimensional Data Matrix codes on every secondary package sold in European Economic Area markets. Converters must install thermal inkjet or laser marking systems with OCR verification. Folding carton lines serving Germany's Rhine-Main cluster are retrofitting fastest due to concentration of pharmaceutical headquarters.
Hospital systems and specialty pharmacies are consolidating carton procurement through group purchasing organizations, displacing fragmented distributor buying. This concentration favors converters with validated quality systems and dedicated pharmaceutical capacity. The shift is most pronounced in US integrated delivery networks and German hospital pharmacy alliances.
Pharmaceutical Printed Cartons Market Segmentation
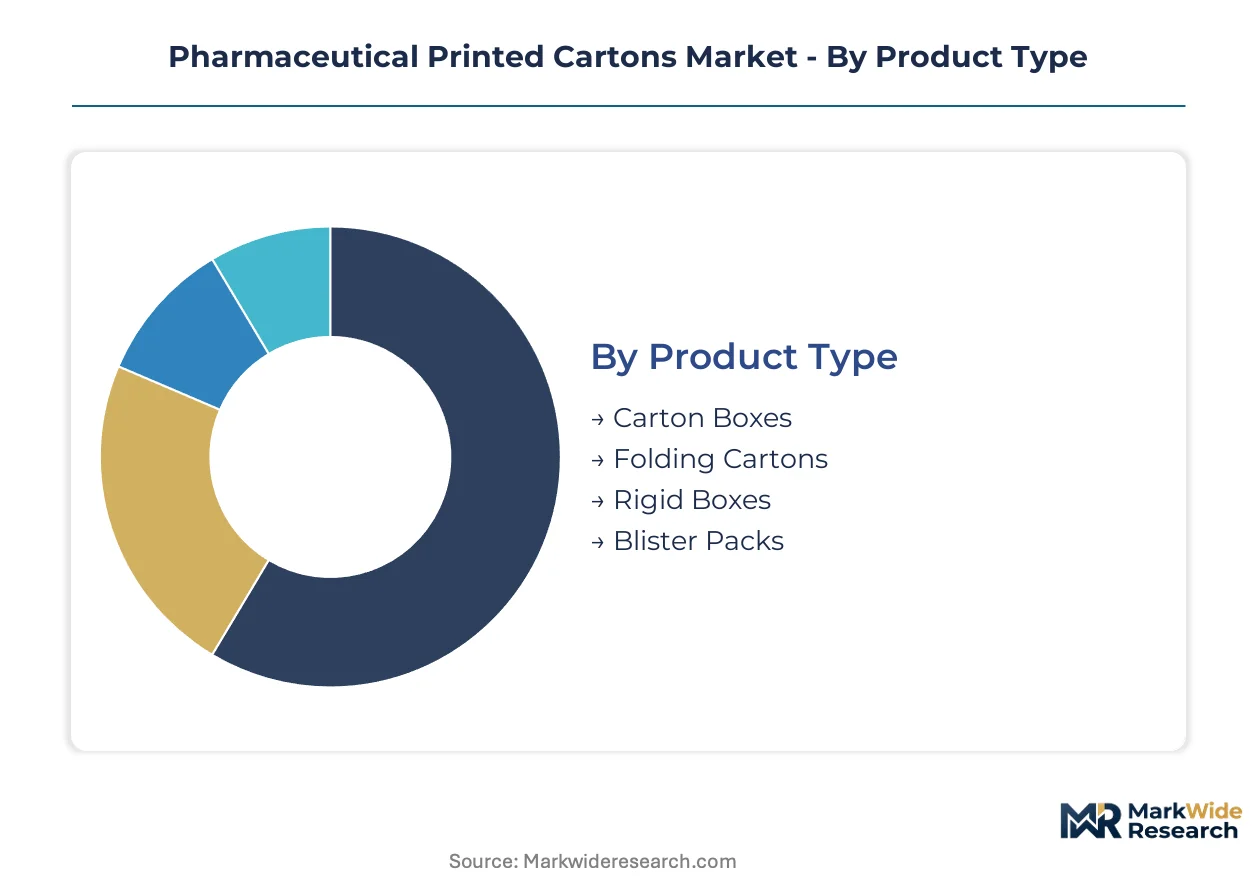
Carton format selection directly determines serialization infrastructure investment and cold-chain qualification pathways. Material and application segments carry divergent regulatory footprints across FDA, EMA, and NMPA jurisdictions.
Product Type:
Domestic pharmaceutical markets favor folding cartons for blister and bottle formats, while export-oriented biologics production drives rigid box demand for cold-chain stability.
- Folding Cartons:Multi-point glued paperboard structures with specified fold endurance accommodate unit-dose blister packs and oral solid bottles. Demand concentrates in India's Ahmedabad cluster for export to regulated markets, pressured by CDSCO's tightening secondary packaging standards.
- Carton Boxes:Straight-line or crash-lock bottom constructions serve high-volume oral solid dosages with automated packaging line compatibility. German Rhine-Main pharmaceutical headquarters specify these for pan-European distribution under EU MDR aggregation requirements.
- Rigid Boxes:Set-up boxes with structural integrity for temperature-sensitive injectables.
- Blister Packs:Thermoformed cavities with printed lidding and backing card integration.
Folding cartons command the established base. The steepest expansion runs through rigid boxes.
Material:
Cost tiers separate commodity paperboard from engineered composites requiring specialized coating supply chains.
- Composite Materials:Multi-layer structures integrating paperboard substrates with aluminum or polymer barriers achieve validated moisture and oxygen resistance for biologics. FDA DSCSA traceability mandates accelerate converter investment in these substrates across US domestic supply chains.
- Paperboard:Bleached kraft or recycled fiber folding boxboard with specified grammage and stiffness properties carries primary labeling and anti-counterfeiting features. China's NMPA export standards are upgrading specifications for paperboard sourced from Shandong and Guangdong mill clusters.
- Plastics:PET or PP-based cartons for moisture-critical tropical markets.
- Aluminum:Cold-form or strip-laminated structures for ultra-high-barrier applications.
Paperboard commands the established base. Composite materials are climbing the fastest.
Application:
Volume concentration sits with chronic disease oral solids, while margin accrues to temperature-validated biologic presentations.
- Vaccines:High-barrier cartons with validated cold-chain stability indicators and tamper-evident closures protect temperature-sensitive immunization products. mRNA platform expansion drives qualification of multi-layer structures with integrated temperature loggers.
- Prescription Drugs:Branded and generic oral solids requiring child-resistant and senior-friendly compliance packaging. Brazil's ANVISA traceability pre-qualification programs are reshaping export carton specifications for this segment.
- Over-the-Counter Medications:High-velocity retail formats with prominent shelf presence and multilingual labeling.
- Nutraceuticals:Dietary supplement cartons with structure-function claim compliance.
Prescription drugs command the established base. Vaccines are gaining share fastest.
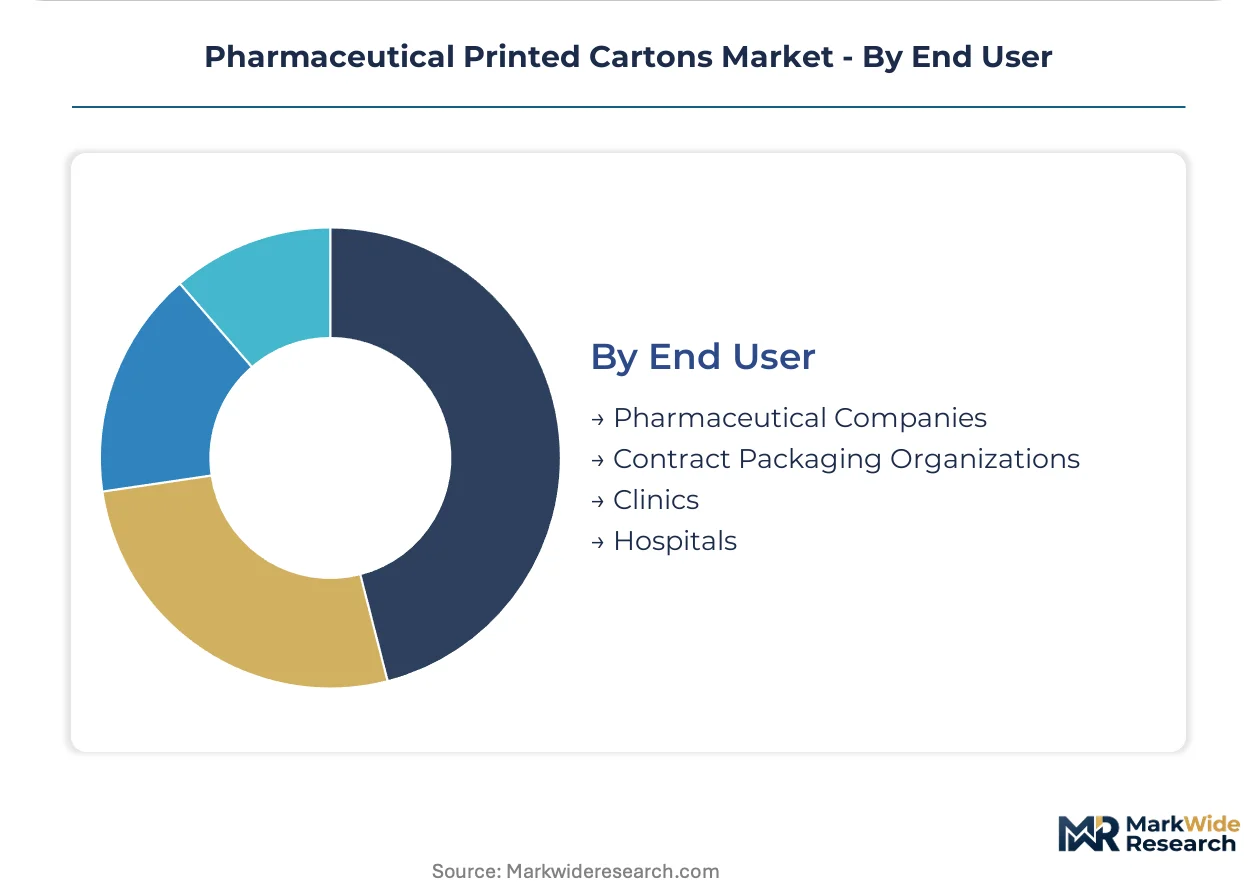
End User:
Customer type determines order pattern fragmentation versus consolidation, with direct pharmaceutical procurement favoring validated quality systems.
- Pharmaceutical Companies:In-house packaging operations and direct converter relationships with dedicated pharmaceutical capacity requirements. Integrated delivery networks in the US are consolidating procurement through group purchasing organizations, displacing fragmented distributor buying.
- Contract Packaging Organizations:Multi-client facilities requiring rapid changeover flexibility and serialization aggregation capabilities. Hyderabad and Bangalore CPO clusters serve export markets with CDSCO-compliant infrastructure.
- Hospitals:Specialty pharmacy and inpatient formulary cartons with unit-dose compliance.
- Clinics:Small-lot fulfillment formats for outpatient dispensing.
Pharmaceutical companies command the established base. Contract packaging organizations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical printed carton procurement concentrates among biologics manufacturers in Germany's Rhine-Main corridor, generic exporters in India's western states, and cold-chain specialists in the US Northeast. These buyer archetypes drive divergent specifications around serialization infrastructure and barrier performance.
United States
FDA DSCSA traceability mandates are accelerating converter investment in aggregation-ready production lines. Boston-Cambridge biologics clusters demand high-barrier cartons with validated temperature stability for mRNA therapies. New Jersey and Pennsylvania pharmaceutical headquarters specify folding cartons with integrated coding infrastructure for domestic distribution compliance.
Germany
EU MDR serialization requirements are reshaping carton specifications across the Rhine-Main pharmaceutical corridor. EMA guidance on unique device identifiers is forcing secondary packaging redesigns for export-bound medical devices. Heidelberg and Mannheim converter facilities are retrofitting fastest to serve Merck KGaA and Boehringer Ingelheim aggregation requirements.
India
CDSCO export standards are upgrading secondary packaging capabilities in Ahmedabad and Hyderabad clusters. Generic pharmaceutical exporters to regulated markets must demonstrate compliance with USP <661> and EU pharmacopoeia standards. Mumbai-Pune pharmaceutical belt is concentrating procurement among converters with dedicated pharmaceutical capacity and serialization verification systems.
China
NMPA export certification requirements are narrowing market access for non-compliant carton converters. Shandong and Guangdong paperboard mill clusters are upgrading specifications for pharmaceuticals bound for FDA and EMA jurisdictions. Yangtze River Delta biopharma manufacturing is driving demand for multi-layer composite cartons with moisture-barrier validation.
Brazil
ANVISA traceability pre-qualification programs are reshaping export carton specifications for Latin American pharmaceutical distribution. São Paulo state pharmaceutical manufacturing is consolidating procurement through validated converters ahead of local serialization deadline alignment. Campinas and Osasco industrial corridors are attracting investment from export-oriented carton specialists.
Pharmaceutical Printed Cartons Market Competitive Landscape
Player mix skews toward integrated paperboard producers with captive fiber supply and specialized coating capabilities. The vendor base separates into three tiers: multinational converters with pharmaceutical-dedicated capacity, regional specialists with serialization aggregation expertise, and commodity folding carton producers exiting regulated segments. Competitive dynamics center on backward integration into barrier coating supply and geographic pre-qualification for emerging market regulators.
Within the integrated multinational tier, WestRock Company and Amcor plc exemplify divergent strategic positions. WestRock leverages its North American paperboard supply chain to serve temperature-sensitive drug portfolios. Amcor anchors its positioning through specialized barrier coating capabilities for moisture-critical formulations. DS Smith Plc occupies a distinct position via modular carton architectures designed for serial aggregation requirements. These three entities collectively represent the competitive archetypes shaping procurement consolidation: fiber-integrated supply security, coating technology differentiation, and serialization-ready design flexibility.
| Leading Market Players |
|---|
| WestRock Company |
| Amcor plc |
| DS Smith Plc |
| Smurfit Kappa Group |
| Graphic Packaging International |
| Sonoco Products Company |
| Mondi Group |
| Huhtamaki Oyj |
| Stora Enso Oyj |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with pulp price indexation lock in fiber supply security and cost predictability for pharmaceutical carton converters serving FDA DSCSA and EU MDR compliance mandates. These arrangements tether pricing to kraft linerboard futures while guaranteeing dedicated capacity for biologics manufacturers requiring validated cold-chain stability documentation.
Pricing Analysis
Cost-plus contracts with monthly pulp price indexation dominate procurement between converters and pharmaceutical buyers. Three-tier pricing structure across serialization-ready, barrier-coated, and standard folding grades separates premium qualification tiers. Cost compression in standard paperboard grades is intensifying because Indian and Chinese export converters are absorbing margin erosion to secure CDSCO and NMPA pre-qualification contracts. Generic pharmaceutical exporters in Ahmedabad exhibit highest price sensitivity; Boston-Cambridge biologics clusters show lowest sensitivity due to cold-chain validation requirements.
Supply Chain Analysis
Inventory buffers for specialty barrier coatings extend lead times beyond standard paperboard cycles. Supply concentrates in Finland and Sweden for bleached kraft pulp, Germany and Japan for moisture-barrier chemical coatings, and China's Shandong province for folding boxboard feedstock. Raw material dependencies span northern European softwood fiber, Japanese acrylic coating resins, and aluminum strip laminates from South Korean rolling mills. Single-source vulnerability sits with heat-seal adhesive suppliers concentrated in Osaka and Rotterdam chemical corridors. Distribution runs through pharmaceutical contract packaging organizations in Hyderabad and direct-to-manufacturer fulfillment from Rhine-Main converter facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical printed cartons sit in early-cycle expansion as mRNA platform proliferation and monoclonal antibody pipeline growth accelerate demand for temperature-validated secondary packaging. Biologics penetration into chronic disease management creates sustained tailwinds for high-barrier carton qualification.
For Market Incumbents: Shield serialization aggregation capabilities through captive vision system engineering talent pools in Mannheim and Boston-Cambridge corridors. Backward integration into water-based barrier coating formulation reduces exposure to Osaka and Rotterdam chemical supplier concentration. Prioritize capacity expansion in Ahmedabad to capture CDSCO export standard upgrades before regional competitors achieve pharmaceutical-dedicated certification. For New Entrants and Emerging Players: Differentiate on rapid serialization line qualification for Brazil ANVISA pre-certification programs ahead of local deadline alignment. Target São Paulo state pharmaceutical manufacturing with modular carton architectures designed for small-lot, high-velocity hospital pharmacy fulfillment. Pursue white-space in connected packaging integration by partnering with near-field communication chip specialists for adherence monitoring applications. For Investors and Strategic Acquirers: Regional specialists with verified EU MDR aggregation capabilities and established relationships with German Rhine-Main pharmaceutical headquarters represent the most defensible acquisition profile. Long-term viability hinges on converter positioning within biologics cold-chain validation workflows rather than commodity oral solid dosage formats. Monitor FDA DSCSA enforcement escalation against non-compliant imports as inflection indicator for procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Retrofit | Folder-gluer line upgrades with OCR verification satisfy EU MDR aggregation mandates for Merck KGaA and Boehringer Ingelheim supply contracts. |
| Water-Based Barrier Coating Qualification | USP <661> compliant sustainable formats compress regulatory approval timelines for biologics stability chamber validation. |
| Backward Integration into Coating Chemistry | In-house acrylic formulation production mitigates single-source risk from concentrated Japanese and European chemical suppliers. |
| Geographic Pre-Qualification for ANVISA | Pre-certified carton specifications capture Brazilian pharmaceutical distribution ahead of local serialization infrastructure buildout. |
| Connected Packaging Partnership | Near-field communication integration enables unit-level authentication and patient adherence monitoring for specialty pharmacy networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EMA unique device identifier specifications, and CDSCO export packaging circulars. Primary interviews with pharmaceutical packaging procurement directors, serialization engineering leads at carton converters, regulatory affairs specialists at biologics manufacturers, and group purchasing organization contract managers informed demand-side validation. Secondary sources span USP <661> compliance databases, EU MDR implementation timelines, and trade flow data from India's DGFT pharmaceutical export registrations. Bottom-up volume estimates triangulate against top-down pharmaceutical production forecasts across the analysis window.
Segmentation dimensions modeled include carton format type, material substrate tier, application by drug class, and end-user procurement channel across the projection horizon. CAGRs derive from regression analysis of historical pharmaceutical packaging intensity ratios applied to biologics pipeline expansion trajectories. Forecast inputs incorporate cold-chain validation adoption curves for mRNA therapies and serialization infrastructure investment cycles tied to regulatory deadline phasing.
Material uncertainties — pulp cost volatility, specialty coating supply disruptions, and regulatory deadline extensions — sit outside the modeled envelope. Forecasts reflect assumptions around continued biologics platform expansion and unenforced regulatory harmonization across FDA, EMA, and NMPA jurisdictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market