
 Paper Band Market | 2026-2036
Paper Band Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Band Market Outlook
Project finance for automated bundling lines is tilting competitive dynamics toward mid-scale converters with capital discipline. Bandall leverages its Dutch engineering heritage to sustain premium positioning in heat-sealable banding systems. Packaging Corp Of America anchors North American volume through integrated paperboard-to-band capabilities and mill-direct logistics.
Paper bands are narrow strips of kraft, recycled, or coated paper, typically 20–100 mm wide, used to unitize, label, or decorate products without adhesives; they are applied by friction or heat-sealing equipment to secure items ranging from corrugated boxes to textile bundles. Flat bands dominate industrial packaging for cost-sensitive volume applications, while printed bands capture margin pools in branding and promotional use cases where four-color flexography adds perceptible value. Reinforced bands, incorporating glassine or filament layers, occupy a technical niche in heavy-goods bundling where tensile strength thresholds exceed standard paper limits.
EU REACH compliance and the F-Gas Regulation shape material sourcing decisions for European converters, while FDA food-contact substance notifications govern bands deployed in US retail food packaging. ISO 186 and TAPPI T 494 standards define tensile and grammage baselines that differentiate export-grade from commodity supply. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize coating and printing capabilities or outsource to certified specialty mills.
Market Dynamics
The EU Green Deal and single-use plastic restrictions across member states are accelerating material substitution decisions among food and beverage manufacturers, forcing converters to retool coating and heat-sealing capabilities ahead of compliance deadlines.
Growth Catalysts
- EU Green Deal plastic bans:Single-use plastic directives in Germany, France, and Italy mandate fiber-based alternatives for bundling applications, creating immediate specification pull from retail chains and food processors.
- Heat-sealable coating advances:Water-based barrier coatings eliminate polyethylene lamination while maintaining tensile strength, opening banding applications to moisture-sensitive product categories previously reserved for plastic.
- Packaging machinery clusters:Concentrated equipment manufacturing in Baden-Württemberg and Bavaria enables rapid prototyping and shorter validation cycles for banding system integrations.
Market Restraints
- Kraft pulp cost volatility:Input fiber prices fluctuate with Nordic pulp mill operating rates and energy costs, compressing converter margins during supply tightness.
- Coating chemical supply concentration:Specialty barrier chemistries for heat-sealable bands source from a limited German and Swiss supplier base, creating single-source vulnerability.
- Tensile strength ceiling:Standard paper bands fail above 50 kg unitized load, ceding heavy-goods bundling to steel strapping and woven polypropylene regardless of sustainability preferences.
Strategic Opportunities
- Indian food retail modernization:Organized retail expansion and FSSAI packaging guidelines create first-mover positioning for banding systems in spice and snack unitization.
- Printed band promotional applications:Four-color flexography on bands enables brand messaging without secondary labels, capturing margin pools in premium chocolate and cosmetics gifting segments.
- Extended producer responsibility frameworks:France's Citeo and Germany's VerpackG fee structures reward mono-material fiber solutions with lower compliance costs versus plastic alternatives.
Industry Challenges
- Heat-sealing technician scarcity:Equipment calibration and maintenance require specialized knowledge of temperature-pressure dwell parameters that few packaging engineers possess.
- REACH compliance documentation:Coating substance dossiers and SVHC screening impose 12-18 month certification timelines that delay product launches.
- Legacy strapping system replacement:Steel and plastic strapping infrastructure in logistics centers requires complete line reconfiguration to accommodate paper band tension specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Band Market |
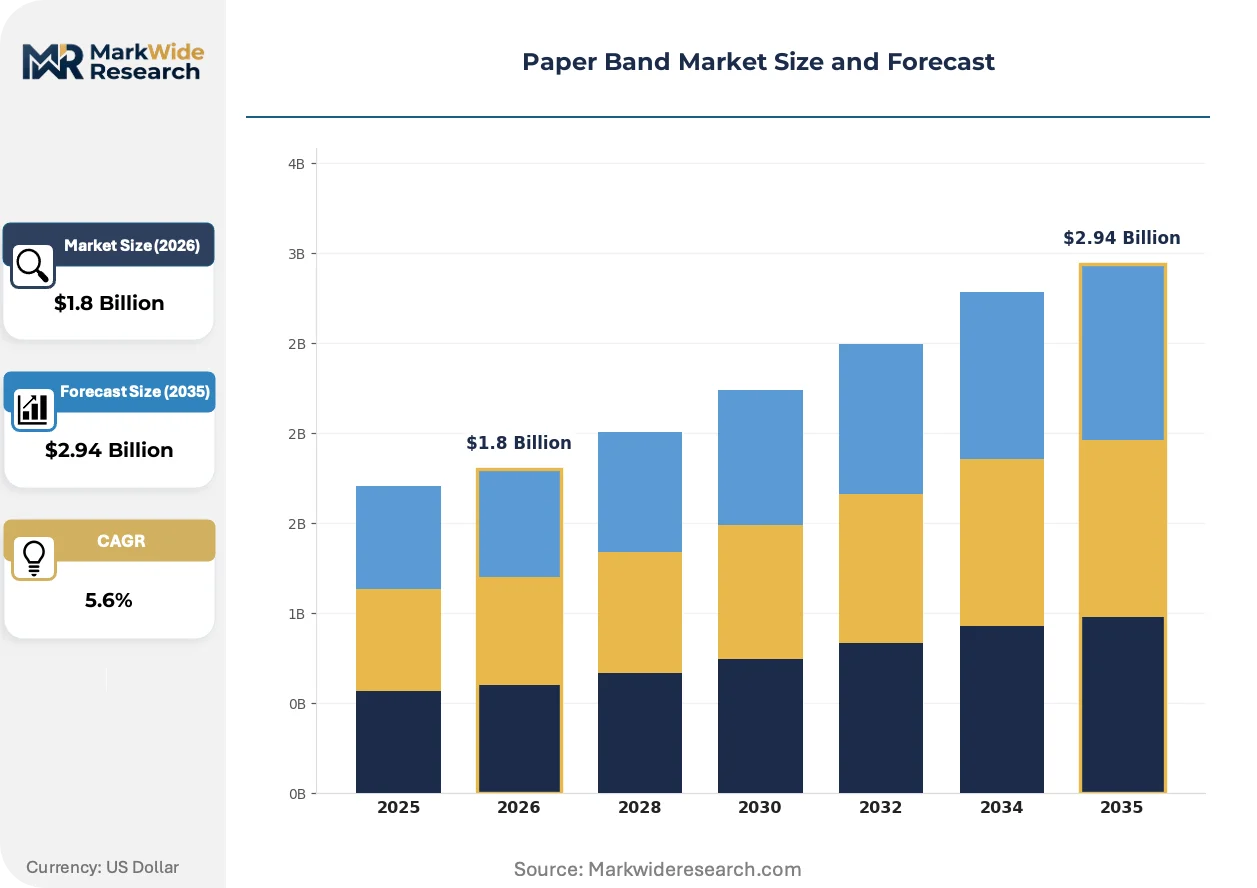
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bands, Printed Bands, Reinforced Bands, Decorative Bands End User: Retailers, Manufacturers, Distributors, Event Organizers Material: Recycled Paper, Kraft Paper, Coated Paper, Specialty Paper Application: Packaging, Branding, Event Management, Textile Industry |
| Companies Covered | Extra Packaging Corporation, SANDAR Industries Inc., Bandall, Cohesion Paper Products LLC, Graphic Arts Equipment, Brown & Pratt, Inc., American Printpack, Economy Tablet & Paper, Packaging Corp Of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Band Market Strategic Shifts
Active innovation centers on coating chemistry breakthroughs, regulatory-driven material validation protocols, and procurement model compression as buyers consolidate supplier panels around certified mono-material solutions.
Filament-reinforced paper banding is hybridizing kraft fiber substrates with glassine or synthetic yarn layers to achieve tensile thresholds exceeding 80 kg without sacrificing recyclability claims. Heavy-appliance and furniture manufacturers in Germany and Poland are piloting these constructions for pallet unitization. The technology is compressing the historical performance gap between fiber and synthetic strapping in mid-weight applications.
REACH SVHC screening and F-Gas Regulation compliance documentation now precede commercial qualification for any coating chemistry deployed in European retail food packaging. Converters must maintain substance dossiers and supply chain attestations that extend three tiers upstream. Banding equipment OEMs in the Netherlands and Italy are responding by pre-certifying material combinations to accelerate customer validation cycles.
Consolidated supplier panels now dominate procurement for multinational food and beverage manufacturers, with sustainability scorecards weighted at 30-40% of vendor selection criteria. Direct mill relationships are displacing distributor intermediaries for volume banding supply. This pattern is most pronounced in German retail private-label supply chains, where Aldi and Lidl specifications require chain-of-custody documentation from pulp source to finished band.
Paper Band Market Segmentation
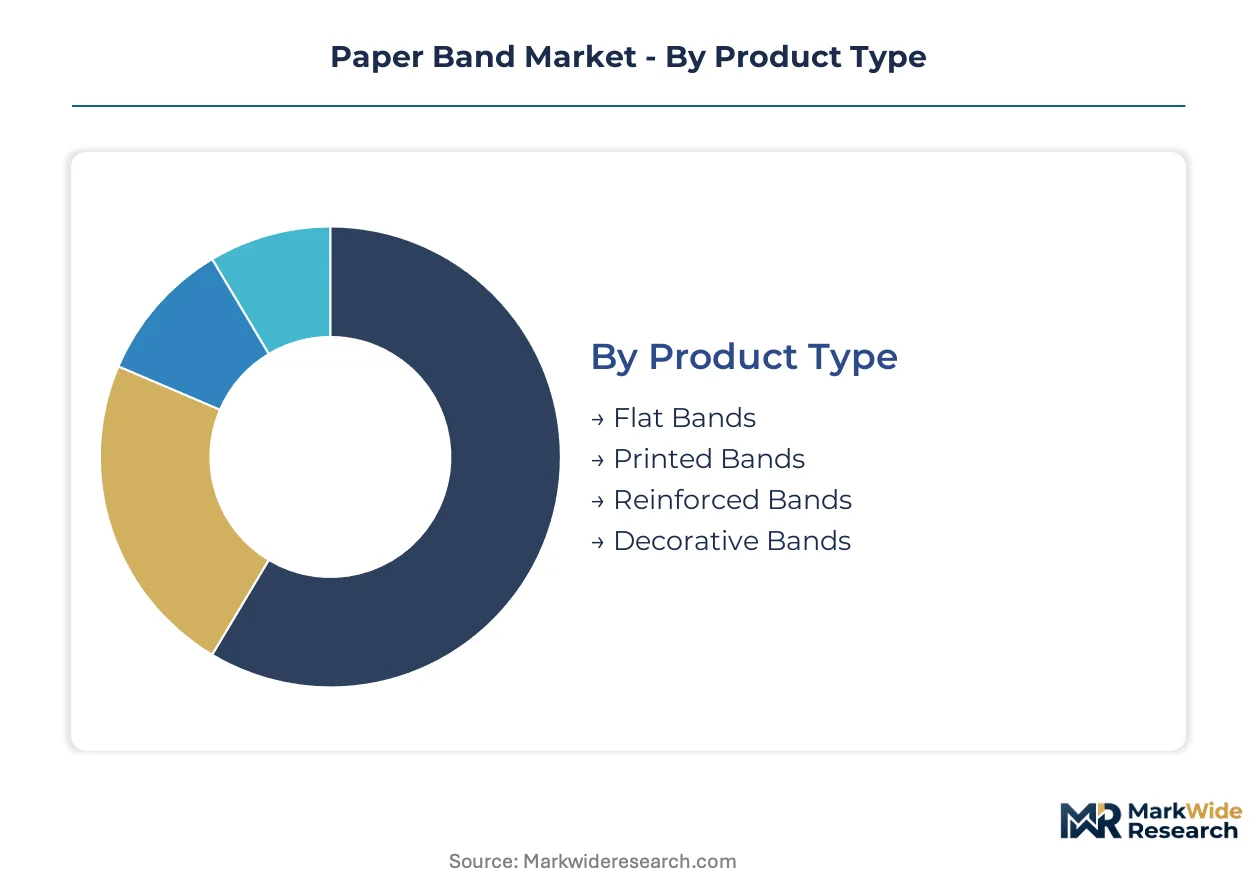
Paper band segmentation reveals distinct performance tiers across material engineering and application requirements. Product type and end-user concentration drive margin stratification, while material sourcing decisions increasingly hinge on regulatory compliance documentation.
Product Type:
Use cases span industrial unitization through premium gift presentation, with technical specifications determining equipment compatibility and coating chemistry requirements.
- Flat Bands:Unprinted kraft constructions in 20-80 mm widths serve high-volume corrugated box bundling and agricultural produce unitization. German discount retail chains specify these for cost-sensitive private-label packaging where mono-material recyclability lowers extended producer responsibility fees.
- Printed Bands:Four-color flexography transforms functional bands into brand communication surfaces for chocolate gifting and cosmetics promotional sets. French and Italian luxury confectioners dominate specification development, driving coating advances that eliminate polyethylene lamination while maintaining print fidelity.
- Reinforced Bands:Glassine or filament layers boost tensile thresholds for mid-weight pallet unitization in Polish furniture manufacturing.
- Decorative Bands:Embossed and foil-stamped variants target event management and artisanal food presentation segments.
The dominant share belongs to Flat Bands, while Printed Bands are closing the gap fastest.
End User:
Procurement sophistication varies sharply across customer categories, with compliance documentation requirements separating qualified suppliers from commodity vendors.
- Retailers:Organized chains in Germany and France mandate chain-of-custody certification and REACH-compliant coatings, consolidating supplier panels around vertically integrated converters with in-house laboratory testing.
- Manufacturers:Food and beverage producers drive heat-sealable coating validation for moisture-sensitive applications, with Baden-Württemberg packaging machinery clusters enabling rapid prototyping cycles.
- Distributors:Wholesale intermediaries face margin compression as direct mill relationships displace traditional stocking roles in volume banding supply.
- Event Organizers:Seasonal demand concentration favors flexible digital printing capabilities over coating technical sophistication.
Retailers command the largest procurement volumes, though Manufacturers are expanding specifications most aggressively.
Material:
Fiber sourcing and barrier performance define competitive positioning across sustainability certification tiers.
- Recycled Paper:Post-consumer fiber content satisfies Aldi and Lidl sustainability scorecards, though tensile variability limits deployment in automated high-speed banding lines.
- Kraft Paper:Virgin Nordic pulp delivers consistent grammage and strength for industrial bundling applications where equipment calibration tolerances are tight.
- Coated Paper:Water-based barrier formulations from German and Swiss chemical suppliers enable heat-sealability without compromising recyclability claims under EU Green Deal frameworks.
- Specialty Paper:Glassine and greaseproof substrates serve niche food-contact applications requiring FDA notification or EFSA compliance documentation.
Kraft Paper retains the dominant position, yet Coated Paper is gaining share fastest as water-based barrier technology matures.
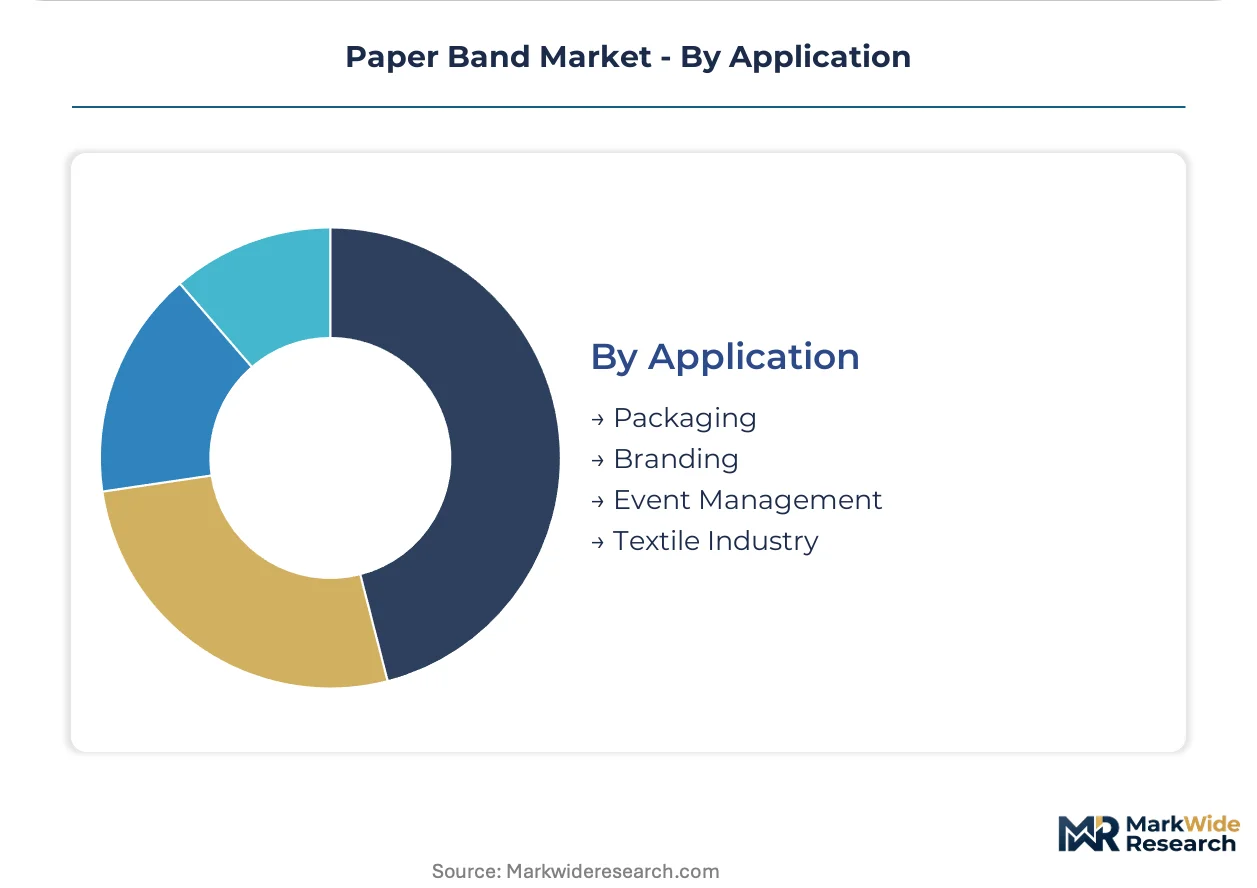
Application:
Functional requirements separate commodity bundling from value-added branding deployments.
- Packaging:Industrial unitization of corrugated cases and textile bundles represents the volume foundation, with tensile strength specifications capping paper band applicability below 50 kg loads.
- Branding:Promotional banding for premium confectionery and cosmetics captures margin pools through four-color reproduction and metallic effects, with French Citeo fee structures rewarding mono-material fiber solutions.
- Event Management:Short-run customization for corporate gifting and wedding favors favors digital printing workflows over coating technical complexity.
- Textile Industry:Bundle identification and size marking for garment distribution centers require heat-sealable constructions compatible with high-throughput friction banding equipment.
Packaging accounts for the dominant application share, while Branding is climbing the fastest as sustainability-driven material substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal plastic bans and extended producer responsibility fee structures are accelerating specification upgrades across food retail supply chains. Germany, France, and Italy mandate fiber-based bundling alternatives, while machinery clusters in Baden-Württemberg and Bavaria enable rapid validation cycles for heat-sealable coating advances.
Germany
Discount retail chains Aldi and Lidl drive mono-material fiber specifications through private-label packaging mandates. VerpackG fee structures reward recyclability claims with lower compliance costs versus plastic alternatives. Packaging machinery manufacturers concentrate in Baden-Württemberg, enabling converter prototyping for moisture-sensitive banding applications.
France
Luxury confectioners and cosmetics brands dominate four-color flexography specification development for promotional banding. Citeo extended producer responsibility frameworks penalize multi-material constructions, pushing mono-material fiber solutions. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes anchor coating chemistry validation for heat-sealable barrier formulations.
United States
FDA food-contact substance notifications govern bands deployed in retail food packaging, creating documentation barriers for European imports. Packaging Corp Of America leverages integrated paperboard-to-band capabilities and mill-direct logistics to anchor North American volume. Midwest packaging corridors in Illinois and Wisconsin concentrate converter capacity for corrugated bundling applications.
India
FSSAI packaging guidelines and organized retail expansion create first-mover positioning for banding systems in spice and snack unitization. Maharashtra and Gujarat industrial corridors concentrate food processing capacity requiring moisture-barrier banding specifications. Domestic converter investments in water-based coating capabilities are accelerating ahead of compliance deadlines.
Poland
Furniture and heavy-appliance manufacturers pilot filament-reinforced constructions for pallet unitization exceeding standard paper tensile limits. EU Green Deal alignment pressures drive substitution from plastic strapping in export-oriented manufacturing zones. Silesian and Greater Poland industrial basins concentrate mid-weight bundling demand from German supply chain integration.
Paper Band Market Competitive Environment
On the supply side, the industry is structured around three distinct capability tiers. Vertically integrated paperboard producers with captive fiber sourcing occupy the volume foundation. Specialized bundling equipment OEMs with coating chemistry partnerships capture premium positioning in heat-sealable applications. Regional converters with digital printing flexibility serve short-run promotional and event management segments. Dominant competitive moves include backward integration into coating formulation capabilities and strategic equipment-service bundling contracts.
Within the integrated paperboard tier, Packaging Corp Of America exemplifies North American scale positioning through mill-direct logistics and captive kraft pulp supply. Bandall represents European engineering-centric specialization in heat-sealable banding systems, leveraging Dutch equipment heritage for premium market positioning. Extra Packaging Corporation and SANDAR Industries Inc. anchor diversified packaging portfolios where banding serves as a component within broader protective solutions.
| Leading Market Players |
|---|
| Extra Packaging Corporation |
| SANDAR Industries Inc. |
| Bandall |
| Cohesion Paper Products LLC |
| Graphic Arts Equipment |
| Brown & Pratt, Inc. |
| American Printpack |
| Economy Tablet & Paper |
| Packaging Corp Of America |
| Others |
Value Chain & Pricing Dynamics
Coating chemical supply concentration in German and Swiss specialty chemical suppliers determines both pricing tier spreads and supply chain shape, compressing converter margins when barrier formulation costs spike while rewarding integrated players with captive coating capabilities.
Pricing Analysis
Certification level under EU REACH and FDA food-contact notification creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels anchors on compliance documentation depth, with volume scale and after-sales service bundling as secondary differentiators. Pricing pressure stems from kraft pulp cost volatility linked to Nordic mill energy expenses. Food and beverage manufacturers show highest price sensitivity due to margin compression in private-label retail, while luxury confectioners absorb premium coatings for brand differentiation.
Supply Chain Analysis
Contract manufacturing for heat-sealable coating formulations concentrates among BASF, Clariant, and specialized Swiss chemical houses serving the banding sector. Raw material sourcing draws from Nordic kraft pulp mills, German coating chemical suppliers, and Italian flexographic ink specialists. Single-source vulnerability in barrier chemistry creates structural risk if REACH SVHC screening disrupts qualified supplier lists. Distribution runs through direct mill relationships displacing wholesale intermediaries, particularly in German retail private-label supply chains demanding chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as EU Green Deal compliance deadlines force rapid specification upgrades across food retail supply chains, splintering demand across certified converters and specialized coating innovators.
For Market Incumbents: Build regulatory documentation moats by internalizing REACH dossier maintenance and F-Gas Regulation compliance attestation capabilities ahead of competitor certification timelines. Packaging Corp Of America and Bandall should anchor backward integration into water-based barrier coating formulation to offset specialty chemical supplier concentration risk. Capacity expansion in Baden-Württemberg machinery corridors captures prototyping demand from moisture-sensitive application validation. For New Entrants and Emerging Players: Mid-scale converters in Maharashtra and Gujarat industrial corridors represent the most penetrable entry point for water-based coating capabilities ahead of FSSAI packaging guideline enforcement. Indian spice and snack unitization offers first-mover positioning before organized retail consolidation hardens supplier panels. A go-to-market angle anchored on rapid equipment-service bundling contracts with local packaging machinery distributors bypasses entrenched mill-direct relationships. For Investors and Strategic Acquirers: The market sits at a regulatory acceleration phase that favors vertically integrated converters with in-house coating laboratories and certified fiber sourcing. Long-term viability across the projection horizon rests on extended producer responsibility framework alignment and mono-material recyclability claims. Acquisition targets should demonstrate pre-certified material combinations with Bandall or equivalent OEM equipment partners. The signal to watch is Citeo and VerpackG fee structure revisions that penalize multi-material constructions more severely.| Strategic Initiative | Industry Significance |
|---|---|
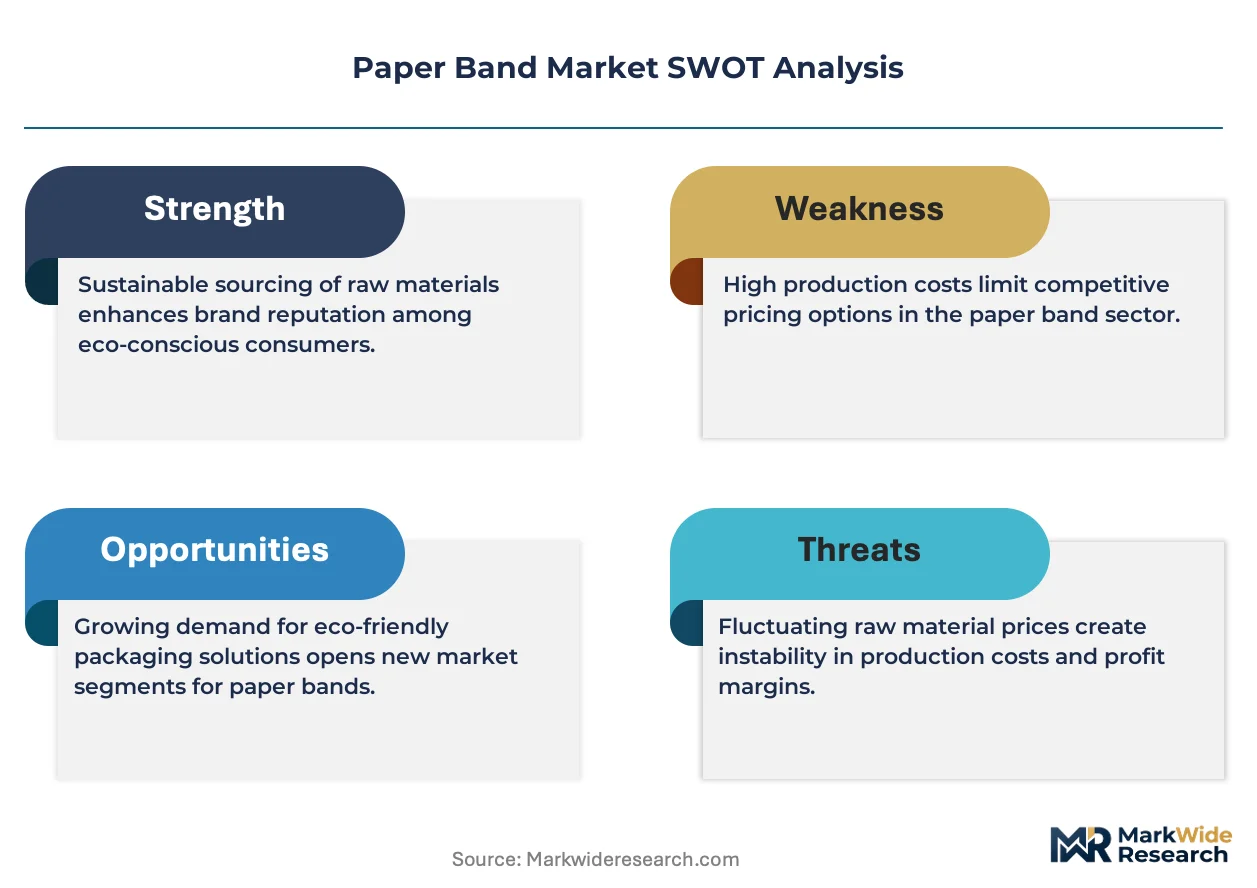
| Backward Integration into Coating Formulation | Captive barrier chemistry supply insulates margins from German-Swiss supplier concentration risk. |
| Equipment-Service Bundling Contracts | Bandall-style system partnerships lock in converter loyalty through pre-certified material combinations. |
| REACH Pre-Certification Investment | Accelerated SVHC dossier maintenance opens specification access to Aldi and Lidl private-label mandates. |
| Direct Mill Relationship Expansion | Eliminates distributor intermediaries in volume banding supply to German retail chains. |
| Filament-Reinforced Product Line Launch | Glassine-layer constructions capture Polish furniture pallet unitization above standard paper tensile limits. |
Study Parameters
Desk research of EU regulatory filings, TAPPI technical standards, and Nordic pulp mill production disclosures preceded structured interviews with packaging machinery OEM engineers, converter procurement leads, and retail private-label specification managers. Secondary validation drew from SEC 10-K filings of integrated paperboard producers, German packaging machinery association trade data, and French Citeo extended producer responsibility fee schedules. Bottom-up volume modeling across product type and end-user segments triangulated against top-down market sizing from trade flow analysis.
Forecast assumptions held EU Green Deal implementation timelines and REACH SVHC candidate list expansion as fixed regulatory drivers, while varying kraft pulp price scenarios and coating chemical supply disruption probabilities across sensitivity cases. Segmentation dimensions modeled include product type, end-user category, material certification tier, and regional machinery cluster adoption patterns. CAGRs derived from equipment installation rates and converter capacity expansion announcements, with heat-sealable coating penetration curves and filament-reinforced construction adoption as industry-specific inputs.
Practitioners should monitor REACH SVHC candidate list revisions and F-Gas Regulation enforcement intensity for early signals of compliance cost acceleration that would revise converter margin assumptions. Forecasts reflect documented assumptions about regulatory timeline adherence and Nordic pulp mill operating rate stability. Quarterly review of German packaging machinery order backlogs and Citeo fee structure amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market