
 Ultraflute Paper Market | 2026-2036
Ultraflute Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Ultraflute Paper Market Analytics
REACH compliance is shifting the cost-of-entry calculus for European ultraflute paper entrants, forcing investment in certified recycled fiber streams and chemical disclosure protocols. Smurfit Kappa leverages its integrated recycling network across the continent to pre-certify feedstock. DS Smith anchors its competitive position through closed-loop paper recovery partnerships with major grocery retailers. Mondi Group differentiates via lightweighting R&D that reduces grammage without sacrificing box compression strength.
Ultraflute paper denotes a corrugated medium with a distinctive narrow-flute geometry, typically measuring 1.0–1.5 mm in flute height and manufactured from semi-chemical or recycled kraft pulp to achieve high stiffness-to-weight ratios for protective packaging applications. The single wall segment dominates volume throughput in e-commerce shipping, though triple wall configurations command premium positioning in heavy-duty industrial transport where palletized loads demand superior stacking performance. Recycled paper material leads on cost, yet virgin fiber grades capture margin pools in food-grade and moisture-resistant applications where FDA and EU food contact compliance requirements exclude post-consumer content.
FDA food contact regulations and the EU Packaging and Packaging Waste Regulation jointly reshape product formulation and end-market access, with compliance costs diverging sharply between virgin and recycled material pathways. ECHA substance restrictions on certain fluorinated treatments further constrain barrier coating options for moisture-sensitive segments. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through contract renegotiations with brand owners.
Market Dynamics
The EU Packaging and Packaging Waste Regulation tightens recycled content mandates, forcing corrugated packaging producers to reengineer fiber sourcing and certification protocols. This regulatory compression is reshaping competitive positioning across the entire value chain.
Growth Catalysts
- E-commerce fulfillment surge:Retail fulfillment operators demand lightweight protective packaging that reduces dimensional weight shipping costs. Ultraflute's stiffness-to-weight ratio meets this specification precisely.
- REACH compliance protocols:Chemical disclosure requirements for recycled fiber streams create first-mover advantages for producers with pre-certified supply networks. Early certifiers capture locked-in brand relationships.
- Germany's corrugated cluster density:Concentrated converting infrastructure in the Rhine-Ruhr and Bavaria regions enables just-in-time supply to automotive and electronics manufacturers.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container (OCC) prices swing with municipal collection disruptions and export demand fluctuations. Input cost instability compresses margin predictability.
- Fluorinated barrier restrictions:ECHA substance limitations on PFAS-based moisture treatments eliminate standard coating options for food-contact applications. Technical substitution gaps persist.
- Single-wall commoditization:Standard flute configurations face price pressure from Asian imports and domestic overcapacity in basic grades.
Strategic Opportunities
- Triple-wall industrial transport:Heavy-duty palletized loads in machinery and chemical sectors demand superior stacking performance. Premium positioning remains underdeveloped outside Germany.
- Closed-loop grocery partnerships:Retailers with captive waste streams seek circular packaging supply agreements. Fiber recovery integration creates defensible supply positions.
- Lightweighting R&D convergence:Nanocellulose reinforcement and advanced forming technologies enable further grammage reduction without compression strength loss.
Industry Challenges
- Food-contact certification timelines:FDA and EU food contact compliance for recycled-content grades requires extensive migration testing. Approval cycles stretch 18-24 months.
- Specialized corrugator engineering:Ultraflute's narrow 1.0-1.5 mm flute geometry demands precision tooling and flute roll maintenance. Technical workforce scarcity constrains capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultraflute Paper Market |
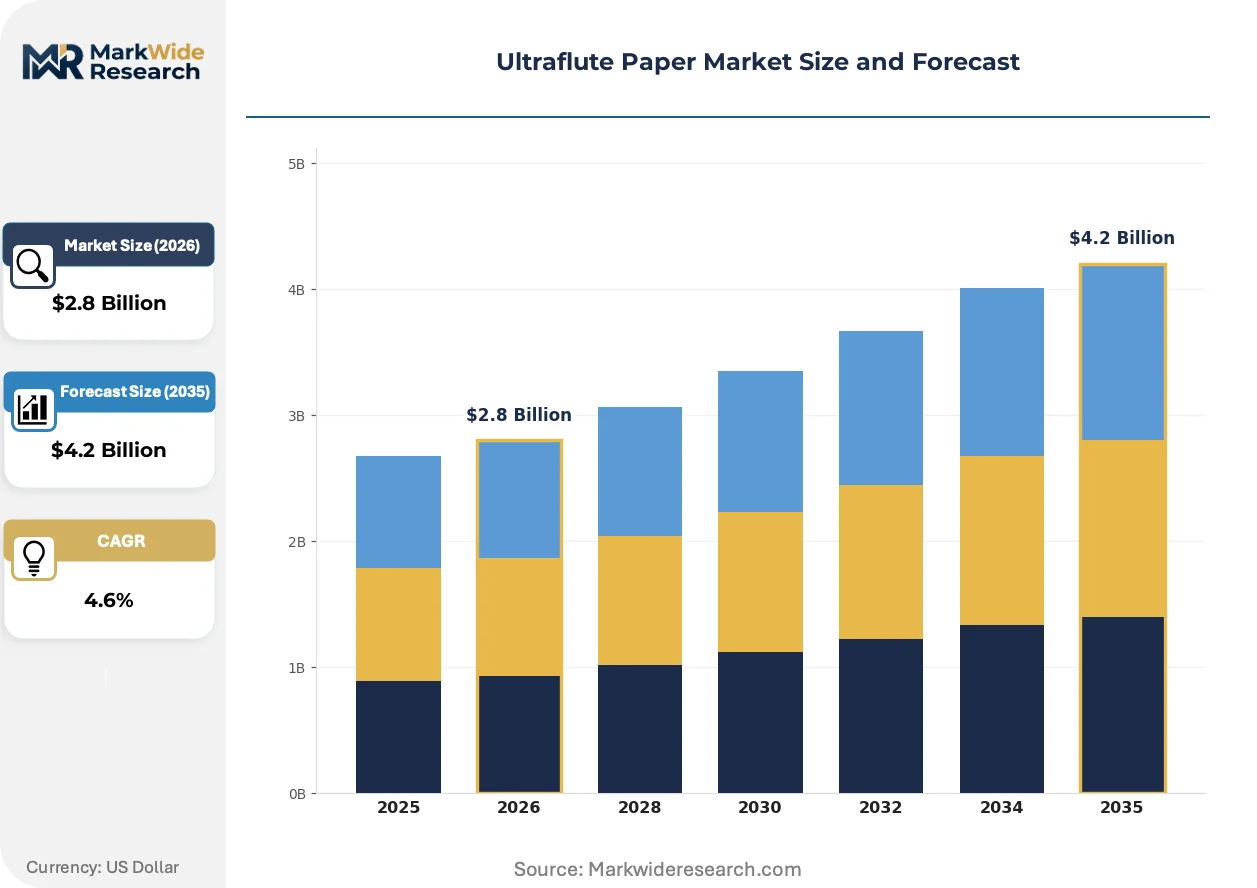
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Custom Flute Application: Packaging, Decoration, Displays, Transport End User: Retail, Food & Beverage, Electronics, Cosmetics Material: Recycled Paper, Virgin Fiber, Coated Paper, Kraft Paper |
| Companies Covered | Smurfit Kappa, DS Smith, WestRock Company, Mondi Group, International Paper Company, Stora Enso Oyj, Huhtamaki Oyj, Sappi Group, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultraflute Paper Market Evolving Landscape
Active experimentation across material science, regulatory compliance architecture, and buyer procurement models is compressing product development cycles and reconfiguring supplier relationships.
Barrier coating innovation is expanding into moisture-sensitive segments previously reserved for plastic alternatives. Water-based polymer and bio-wax formulations now achieve grease resistance sufficient for chilled food applications. European converters with pilot lines are qualifying these coatings for retail ready packaging. The technology is expanding into frozen food and fresh produce segments where condensation resistance determines shelf appeal.
Extended producer responsibility frameworks in France and the Netherlands impose packaging fee modulation based on recyclability scores. Producers with Design for Recycling certification receive fee discounts of 10-20 percent. This incentive structure accelerates mono-material packaging adoption. Ultraflute grades with compatible adhesive and ink systems capture preferential positioning in brand owner sustainability scorecards.
Brand owners now specify recycled content percentages in packaging procurement tenders rather than accepting supplier averages. Major grocery retailers in Scandinavia and the Benelux require 80-90 percent post-consumer fiber minimums. This behavior compresses spot-market sourcing and locks producers into long-term recovered paper supply agreements. The shift is most visible in private-label food packaging where sustainability claims directly influence consumer purchase decisions.
Ultraflute Paper Market Segmentation
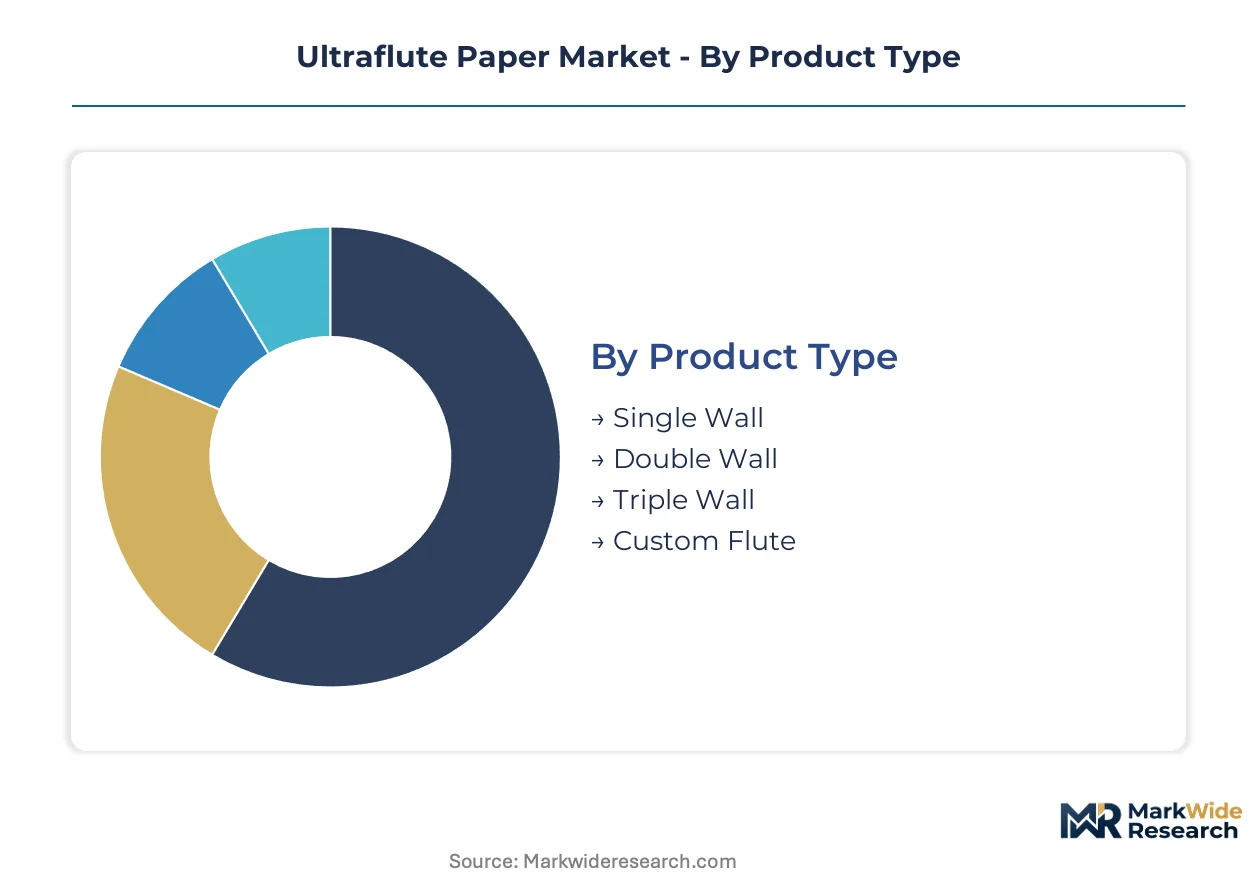
Ultraflute paper segmentation reflects divergent technical requirements across protective packaging, display aesthetics, and regulatory compliance boundaries. Each dimension carries distinct margin profiles and capital intensity thresholds that reshape supplier specialization.
Product Type:
Flute geometry and wall construction determine compression strength, stacking height limits, and corrugator line configuration requirements.
- Single Wall:One corrugated medium bonded between two flat liners delivers the baseline stiffness-to-weight ratio for e-commerce shipping cartons. Retail fulfillment operators in Germany's Rhine-Ruhr corridor specify this grade for dimensional weight cost reduction on parcel networks.
- Triple Wall:Three corrugated mediums separated by four linerboards achieve exceptional stacking performance for palletized machinery and chemical loads. Bavarian automotive parts distributors specify this configuration for export container optimization where floor loading limits constrain unit density.
- Double Wall:Two flute layers provide intermediate protection for mid-weight consumer goods where single-wall compression fails but triple-wall cost overruns budget.
- Custom Flute:Non-standard 0.8-2.0 mm height variations accommodate specialized display fixtures or unique box geometries for premium unboxing experiences.
Single Wall leads on scale; Triple Wall leads on momentum.
Application:
End-use functional requirements split the market between protective logistics and brand-facing presentation surfaces.
- Packaging:Protective containment for product shipment dominates volume throughput across all flute configurations. E-commerce carton demand concentrates in automated fulfillment centers requiring consistent case erecting performance.
- Transport:Heavy-duty industrial dunnage and pallet boxes command premium positioning through superior stacking strength certification. Chemical sector buyers in the Netherlands specify moisture-resistant coatings for this segment.
- Displays:Point-of-purchase fixtures exploit ultraflute's printability and structural rigidity for temporary retail installations.
- Decoration:Interior design and event staging applications leverage lightweight panel construction for temporary architectural elements.
Packaging absorbs the highest absolute volume; Transport commands the steepest expansion trajectory.
End User:
Buyer procurement sophistication varies sharply between compliance-driven food contact applications and specification-flexible general merchandise.
- Food & Beverage:Chilled and frozen food packaging demands FDA and EU food contact migration compliance that excludes certain recycled fiber streams. Scandinavian grocery retailers impose 80-90 percent post-consumer minimums that compress supplier qualification timelines.
- Electronics:Static-dissipative coatings and precision die-cutting specifications serve high-value device protection where damage rates directly impact brand reputation.
- Retail:Private-label packaging procurement emphasizes sustainability scorecard alignment over technical performance differentiation.
- Cosmetics:Premium unboxing experiences drive custom flute geometries and high-fidelity print surfaces for brand differentiation.
Food & Beverage leads on compliance stringency; Electronics leads on specification premium capture.
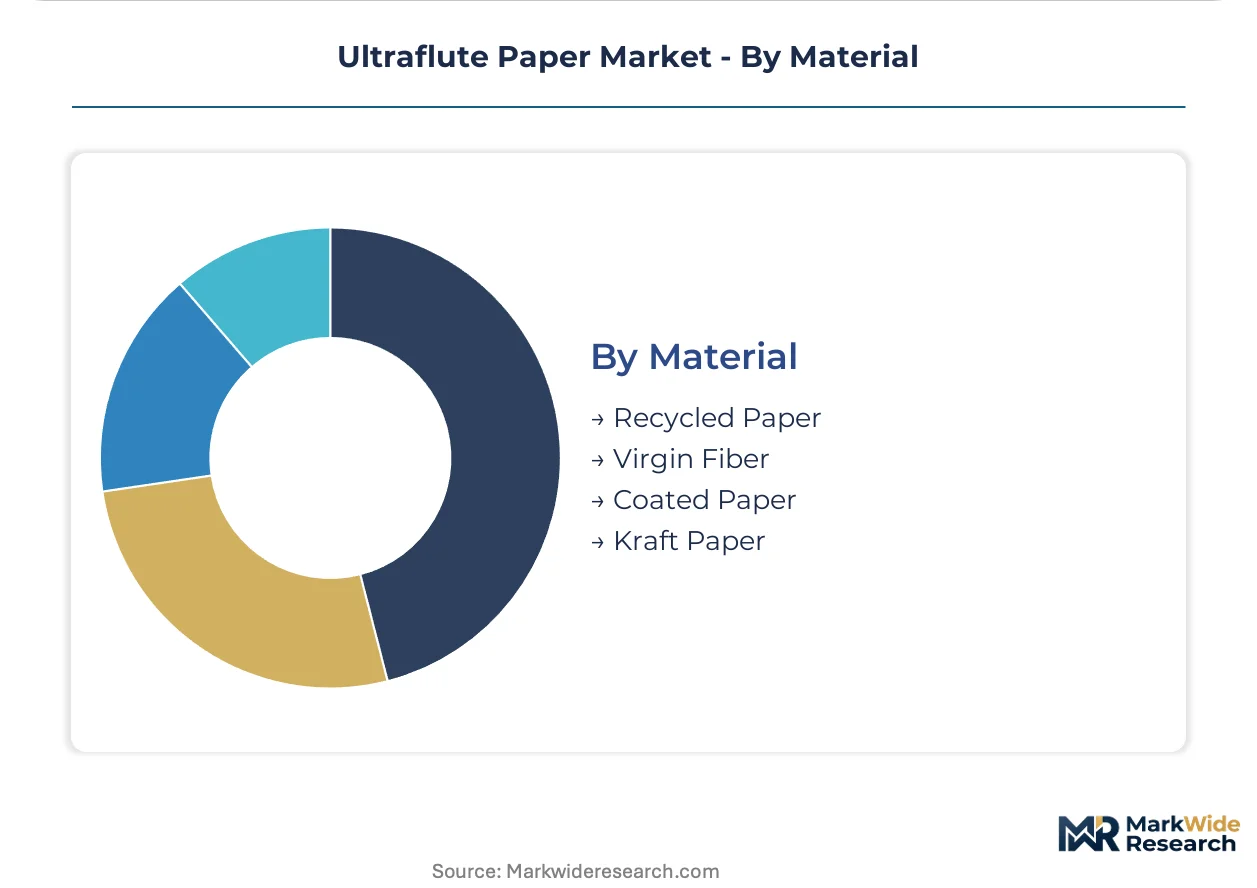
Material:
Fiber sourcing pathways determine regulatory access, cost volatility exposure, and end-market eligibility boundaries.
- Recycled Paper:Old corrugated container (OCC) based production achieves lowest unit cost but faces ECHA substance disclosure requirements and food contact exclusion constraints. REACH compliance protocols favor producers with pre-certified supply networks.
- Virgin Fiber:Semi-chemical kraft pulp delivers consistent strength properties and full food contact regulatory access. FDA and EU compliance timelines favor this pathway for 18-24 month certification cycles.
- Coated Paper:Barrier treatments for moisture and grease resistance expand addressable market into chilled food segments previously reserved for plastic alternatives.
- Kraft Paper:Unbleached natural fiber grades serve sustainability-positioned brands seeking visible environmental credentials without recycled content uncertainty.
Recycled Paper leads on volume throughput; Virgin Fiber leads on margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized corrugator technicians and precision tooling engineers concentrate in Germany's Rhine-Ruhr corridor, anchoring Europe's ultraflute paper technical workforce. This talent density shapes regional supply capabilities and certification timelines.
Germany
Automotive parts distributors and electronics fulfillment operators in Bavaria and North Rhine-Westphalia drive specification-grade demand. REACH compliance protocols from ECHA enforce chemical disclosure for recycled fiber streams. The Düsseldorf-Dortmund corridor hosts Europe's densest converting infrastructure, with just-in-time supply lines serving machinery exporters.
United States
E-commerce fulfillment centers in the Midwest and Southeast specify lightweight cartons for dimensional weight cost reduction. FDA food contact regulations govern barrier coating approvals for chilled and frozen applications. The Chicago-Indianapolis corridor concentrates automated case erecting operations demanding consistent flute geometry.
France
Extended producer responsibility frameworks modulate packaging fees based on recyclability scores, favoring mono-material designs. ANSM and environmental agencies administer fee discount programs for Design for Recycling certification. The Île-de-France region anchors retail ready packaging innovation for grocery private-label contracts.
Netherlands
Chemical sector buyers specify moisture-resistant triple-wall configurations for palletized export loads. National extended producer responsibility schemes impose recyclability scoring that rewards compatible adhesive systems. The Rotterdam-Antwerp port cluster enables fiber import logistics for integrated paper mills.
China
Cross-border e-commerce platforms and consumer electronics manufacturers demand high-volume single-wall output for parcel networks. GB standards and MIIT guidelines shape food contact and export compliance pathways. The Yangtze River Delta concentrates corrugator capacity serving Shanghai-based fulfillment operators.
Ultraflute Paper Market Competitive Landscape
The competitive structure tilts toward integrated paper-packaging conglomerates with captive recycling networks. European producers dominate specification-grade segments through pre-certified fiber streams, while North American operators leverage scale in standardized e-commerce grades. Three archetypes prevail: vertically integrated recycling-to-boxboard operators, specialty coating innovators, and regional scale converters. Capacity expansion and closed-loop partnership formation represent the dominant competitive moves reshaping supply positions.
Among European-based integrated operators, Smurfit Kappa, DS Smith, and Mondi Group exemplify distinct strategic postures. Smurfit Kappa occupies a position anchored by continent-wide recycling infrastructure. DS Smith represents the closed-loop partnership archetype through grocery retailer fiber recovery integration. Mondi Group sits within the lightweighting R&D tier, emphasizing grammage reduction without compression strength degradation. These three collectively illustrate how regulatory pre-certification, circular supply agreements, and material science investment differentiate positioning in a compliance-intensive market.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| WestRock Company |
| Mondi Group |
| International Paper Company |
| Stora Enso Oyj |
| Huhtamaki Oyj |
| Sappi Group |
| Packaging Corporation of America |
| Others |
Value Network & Pricing Analysis
Narrow-flute corrugator tooling upgrades across Germany's Rhine-Ruhr corridor simultaneously compress unit production economics and concentrate supply leverage among integrated operators with captive fiber recovery networks. REACH chemical disclosure mandates for recycled fiber streams amplify cost divergence between pre-certified incumbents and spot-market dependent converters, locking in tiered supply positions that reshape pricing power across the value chain.
Pricing Analysis
Contract-based long-term offtake dominates specification-grade segments while spot-market transactions govern commodity single-wall volumes. Price differentiation separates virgin fiber food-contact grades from recycled-content industrial packaging, with FDA and EU compliance tiers commanding substantial premiums over basic grades. Cost compression in standard single-wall configurations is intensifying because Asian import competition and domestic overcapacity erode margin buffers. Retail fulfillment operators exhibit highest price sensitivity due to dimensional weight shipping cost optimization mandates, whereas chemical sector buyers in the Netherlands prioritize stacking performance certification over unit cost.
Supply Chain Analysis
Old corrugated container supply rests on municipal collection systems in Germany, France, and the Benelux region, with export demand fluctuations to Asian markets creating periodic tightness. Semi-chemical kraft pulp, precision flute rolls, and water-based barrier coatings constitute critical input dependencies with concentrated supplier bases. Single-source vulnerability in specialized corrugator engineering talent constrains capacity expansion timelines. Distribution runs through just-in-time converting clusters serving automotive and electronics manufacturers, with integrated paper-packaging conglomerates controlling upstream fiber access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ultraflute Paper Market functions as a stable compounder anchored by e-commerce packaging demand that sustains volume throughput regardless of macroeconomic cyclicality. Regulatory compliance intensity creates durable competitive moats that protect incumbent returns.
For Market Incumbents: Deepen closed-loop fiber recovery partnerships with grocery retailers to lock in defensible OCC supply positions against export market competition. Prioritize lightweighting R&D investment in nanocellulose reinforcement to capture premium positioning in dimensional weight-sensitive e-commerce segments. Pre-certify recycled fiber streams under REACH protocols before regulatory deadlines tighten, converting compliance cost into relationship lock-in with brand owners. For New Entrants and Emerging Players: Barrier coating innovation offers a technology-first wedge into moisture-sensitive food segments where fluorinated treatment restrictions have eliminated incumbent solutions. Target triple-wall industrial transport configurations in machinery and chemical sectors outside Germany's saturated converting cluster. Pursue pilot line partnerships with European converters to qualify water-based polymer coatings for retail ready packaging applications. For Investors and Strategic Acquirers: Valuations sit cheapest among regional scale converters lacking integrated recycling infrastructure but possessing specialized corrugator engineering capabilities. The five-to-ten year viability thesis rests on extended producer responsibility framework expansion that rewards mono-material packaging investments. Watch ECHA substance restriction announcements on remaining barrier chemistries as the inflection indicator for coating substitution technology acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Recovery | Captive OCC supply insulates margin from export demand volatility to Asian markets. |
| Lightweighting R&D Investment | Nanocellulose reinforcement enables grammage reduction for dimensional weight cost optimization. |
| REACH Pre-Certification Program | Early chemical disclosure compliance locks in brand relationships before regulatory deadlines. |
| Closed-Loop Retail Partnership | Grocery retailer waste stream integration creates circular supply agreements with volume guarantees. |
| Barrier Coating Pilot Scale-Up | Water-based polymer qualification expands addressable market into chilled food segments. |
Research Methodology
Multiple input streams — corrugator operations managers, procurement leads at grocery retailers, technical R&D directors at integrated paper mills, and distribution channel partners — were reconciled against secondary validation from ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation filings, and SEC 10-K disclosures from packaging conglomerates. Bottom-up volume modeling across flute geometries and wall constructions was triangulated against top-down demand aggregation from e-commerce fulfillment operator procurement data.
Historical capacity utilization patterns were cross-referenced against panel input from industry participants to derive expansion trajectories across the projection horizon. Segmentation modeling incorporated product type, application, end user, and material pathways with regional production hub clustering. CAGRs were computed from reconciled baseline and terminal value estimates, with fiber cost volatility and regulatory compliance timeline assumptions serving as key sensitivity inputs.
The model holds under stable OCC collection rates and gradual REACH implementation; deviation in sudden export demand surges or accelerated fluorinated substance bans would shift volume and value outputs. Forecasts reflect documented assumptions about e-commerce growth persistence and regulatory enforcement intensity. A small set of named triggers — ECHA substance restriction announcements, extended producer responsibility fee modulation changes, and municipal collection system disruptions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Paperboard Protectors Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
South Africa Paper Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market