
 Paper Coaster Market | 2026-2036
Paper Coaster Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Coaster Market Insights
Independent craft breweries and specialty coffee roasters are rotating share away from mass-market quick-service chains in paper coaster procurement. Huhtamaki Oyj leverages its molded fiber expertise to dominate European foodservice supply. International Paper Company anchors North American volume through integrated pulp-to-converting operations. Yangzhou Ecoway Hotel Supply Co., Ltd. competes on custom-printed hospitality formats for boutique hotel chains across Asia-Pacific.
Paper coasters are flat, absorbent disks manufactured from pressed wood pulp, recycled paperboard, or molded fiber, typically measuring 3.5 to 4.5 inches in diameter and designed to protect surfaces from condensation and heat while serving as printable branding vehicles. The printed segment commands premium positioning as breweries and distilleries commission full-color lithographic runs for promotional campaigns, while the biodegradable segment accelerates fastest as operators seek compostable alternatives to plastic-lined options. Bars and restaurants remain the core application channel, though events procurement is expanding as corporate sponsors replace disposable napkins with logoed coasters at trade shows and festivals.
FDA food-contact substance regulations govern paperboard coatings and ink formulations in the United States, while the EU Packaging and Packaging Waste Directive sets recovery targets that favor recyclable single-use tabletop items across member states. ISO 22000 food safety management standards shape supplier qualification protocols for coasters used in direct beverage contact. Stakeholders must monitor evolving extended producer responsibility schemes and ink chemistry restrictions to anticipate specification changes before contract renewal cycles.
Market Dynamics
Single-use plastic bans across the United States and European Union member states are structurally redirecting foodservice procurement toward cellulose-based tabletop accessories, compressing substitution timelines for operators previously reliant on laminated or polystyrene alternatives.
Growth Catalysts
- VerpackG packaging waste laws:Germany's extended producer responsibility framework mandates recyclable recovery targets that favor pressed-pulp coasters in brewery and hospitality supply chains.
- Specialty coffee chains:Boutique roasting operations commission branded coasters as experiential marketing touchpoints, expanding SKU counts beyond generic white-label formats.
- FDA food-contact substance regulations:Compliance requirements for direct beverage contact are filtering out non-certified imports, creating specification pull for ISO 22000-qualified suppliers.
Market Restraints
- Pulp price volatility:Northern bleached softwood kraft pulp contracts fluctuate with energy and logistics costs, squeezing converter margins on fixed-price hospitality contracts.
- Supplier concentration in Nordic regions:Integrated pulp-to-converting operations cluster in Finland and Sweden, exposing buyers to single-source risk during transport disruptions.
- Plastic-lined substrate substitution:PE-coated paperboard retains moisture barrier advantages for high-humidity environments, slowing complete displacement in tropical markets.
Strategic Opportunities
- Corporate events procurement:Trade show sponsors replace disposable napkins with logoed coasters, opening volume contracts outside traditional bar and restaurant channels.
- Compostable certification tailwind:ASTM D6400 and EN 13432 standards create premium positioning for molded-fiber formats in zero-waste venue mandates.
- Digital print convergence:On-demand inkjet systems enable short-run customization for craft distilleries, collapsing minimum order quantities from tens of thousands to hundreds.
Industry Challenges
- Food-safe ink chemistry expertise:Converters lack in-house toxicology assessment capabilities to validate migration limits for direct-contact lithographic formulations.
- Extended certification timelines:FDA food-contact notification reviews stretch six to eighteen months, delaying new coating introductions past contract renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Coaster Market |
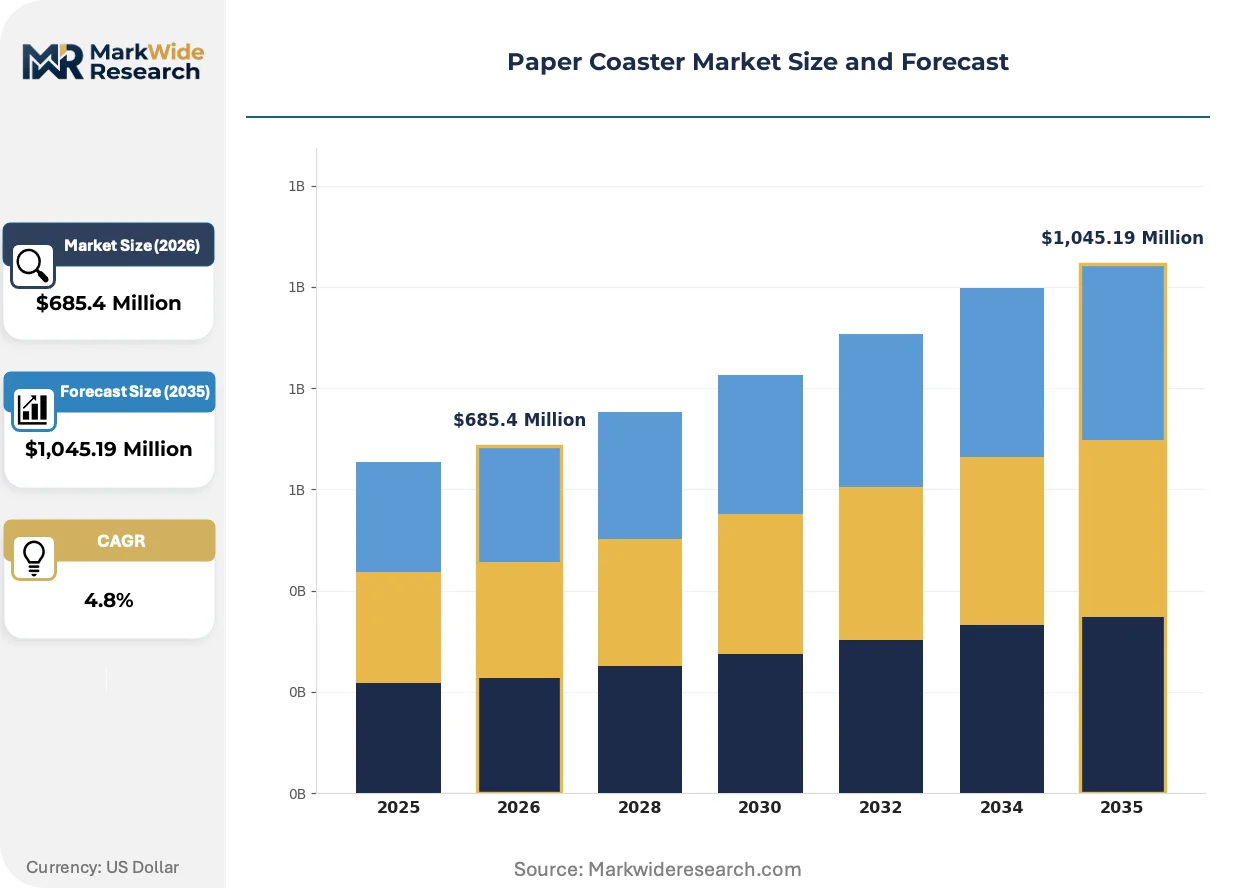
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Bleached, Unbleached, Printed Application: Bars, Restaurants, Events, Home Use Size: Standard, Custom, Mini, Large Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | Dart Container Corporation, Huhtamaki Oyj, Graphic Packaging International, International Paper Company, Novolex Holdings, Mondi Group, Pactiv Evergreen Inc., WestRock Company, Yangzhou Ecoway Hotel Supply Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Coaster Market Trends and Innovations
Active innovation in the paper coaster market clusters around three vectors: manufacturing process compression, regulatory specification tightening, and procurement model fragmentation that rewards agile customization over long-run economies.
Molded fiber forming technology is miniaturizing production footprints for custom-shaped coasters. Small-batch craft breweries in Portland and Copenhagen now deploy tabletop presses for seasonal design rotations. This distributed manufacturing model compresses lead times from overseas container schedules to same-week turnaround.
EU Packaging and Packaging Waste Directive revision discussions are tightening recyclability definitions, explicitly targeting composite laminates. Foodservice operators in France and the Netherlands are pre-emptively specifying uncoated cellulose to avoid future compliance gaps. The printed segment faces reformulation pressure as member states debate ink migration thresholds.
Boutique hotel chains are consolidating coaster procurement with broader tabletop amenity programs, unbundling standalone supplier relationships. Independent hospitality groups in Tokyo and Melbourne now source coasters through integrated FFE (furniture, fixtures, equipment) platforms. This channel compression disadvantages single-product converters lacking cross-category bundling capability.
Paper Coaster Market Segmentation
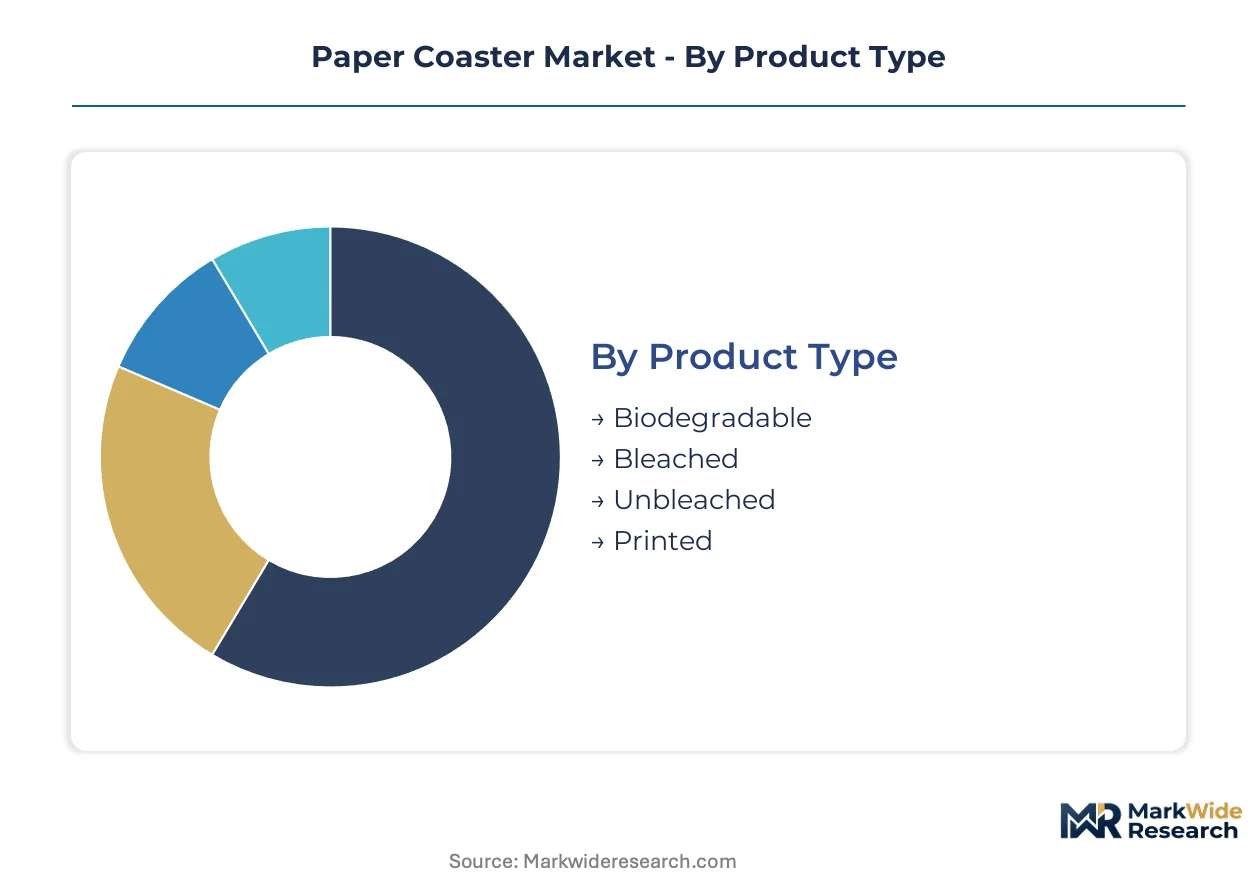
Paper coaster procurement flows through distinct channel architectures, with hospitality operators, event sponsors, and retail consumers each driving specification requirements. Understanding how product formats align with these pathways reveals where margin concentrates and where volume scales.
Product Type:
Bars and restaurants channel biodegradable and unbleached formats through wholesale distributors, while printed variants reach hospitality groups via direct converter relationships.
- Biodegradable:Molded-fiber or uncoated cellulose constructions certified to ASTM D6400 or EN 13432 standards. Zero-waste venues in Copenhagen and Portland mandate compostable formats, compressing substitution timelines for conventional substrates.
- Printed:Full-color lithographic or digital inkjet surfaces enabling brewery logo reproduction and promotional messaging. Craft distilleries in Kentucky and Scotland commission short-run seasonal designs, collapsing minimum order quantities through on-demand production systems.
- Bleached:Bright white sulfate board with optical brightness agents for premium tabletop presentation.
- Unbleached:Natural kraft-tone fiber retaining lignin content, favored by sustainability-positioned roasting operations.
By volume, printed coasters lead hospitality procurement. By growth pace, biodegradable formats are expanding most quickly.
Application:
Cost tiers separate disposable high-frequency consumption from durable branded deployments, with events commanding premium unit economics for logo visibility.
- Bars:High-turnover establishments consume standard-diameter pressed pulp in bulk pallet quantities, prioritizing absorbency and stackability over customization.
- Restaurants:Full-service operators specify thicker substrates or embossed edges for perceived quality, often bundling coaster procurement with napkin and menu programs.
- Events:Corporate sponsors and festival organizers replace disposable napkins with logoed coasters, opening volume contracts outside traditional foodservice channels. Trade show procurement in Las Vegas and Frankfurt runs through specialized event supply distributors.
- Home Use:Retail-packaged formats sold through supermarkets and online channels for domestic entertaining occasions.
Events generate the highest per-unit margins. Bars drive absolute volume throughput.
Size:
Volume concentration favors standard diameters for operational efficiency, while custom dimensions serve brand differentiation objectives.
- Standard:3.5 to 4.5 inch diameters matching glassware footprints across North American and European markets, produced on high-speed rotary presses for cost minimization.
- Custom:Non-circular shapes or oversized formats for brewery anniversary releases and hotel amenity programs, requiring dedicated cutting dies and extended lead times.
- Mini:Reduced-diameter formats for espresso cups and tasting flights.
- Large:Expanded surfaces for carafe or pitcher service in German beer gardens.
Standard sizes dominate procurement tonnage. Custom formats command the steepest expansion trajectory in specialty segments.
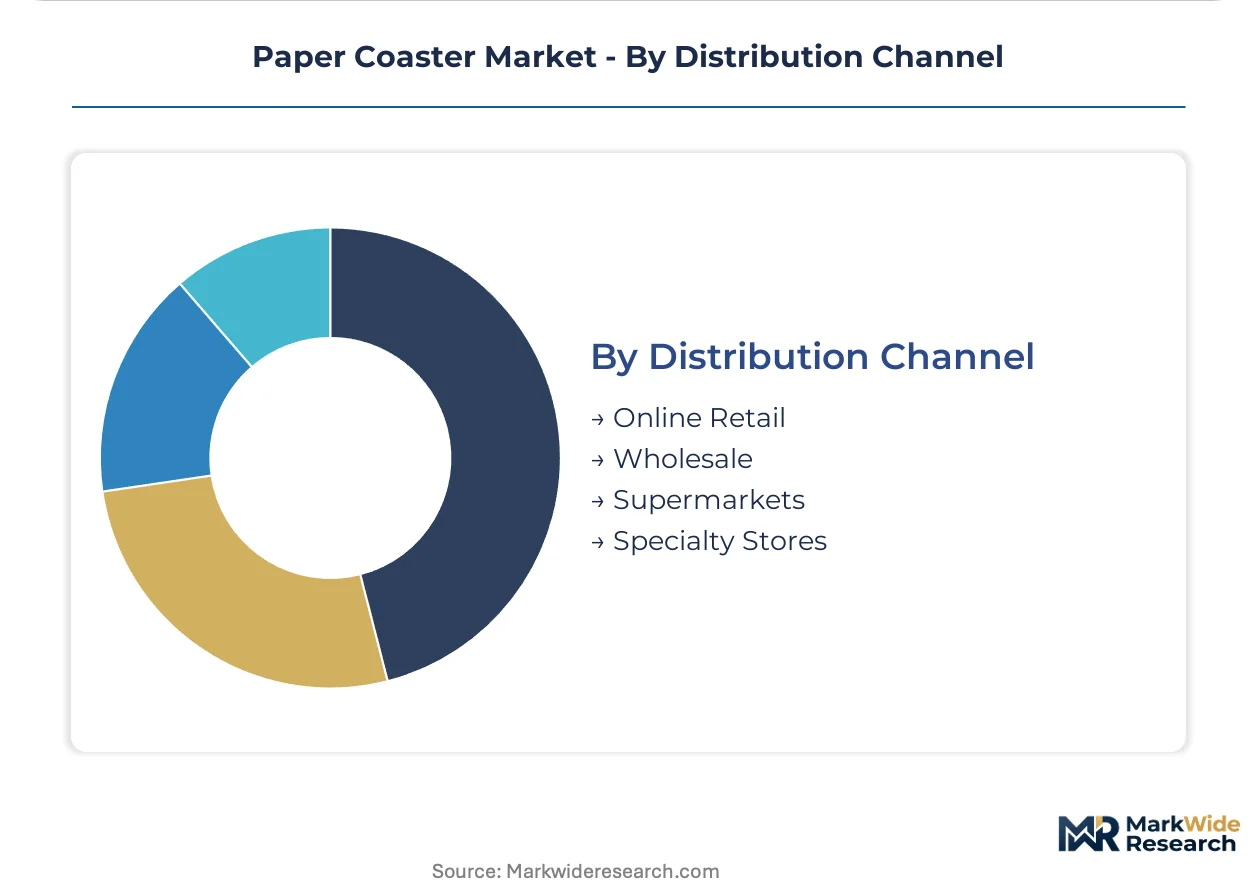
Distribution Channel:
Customer type determines channel selection, with institutional buyers favoring direct converter relationships and small operators defaulting to wholesale intermediaries.
- Wholesale:Distributors such as Sysco and Bidfood aggregate demand from independent bars and restaurants, stocking generic white-label inventory for immediate fulfillment.
- Online Retail:Amazon and Alibaba platforms serve home-use consumers and small event planners, enabling single-case purchases with printed customization options.
- Supermarkets:Mass-market retailers stock private-label coaster packs adjacent to party supply aisles, competing on price per unit against disposable napkin alternatives.
- Specialty Stores:Hospitality supply showrooms in Chicago and Milan showcase premium embossed and foil-stamped formats for boutique hotel procurement teams.
Wholesale channels move the greatest unit volume. Online retail is gaining share fastest among non-institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pulp-to-converting operations supply branded coaster volumes to hospitality operators across France, Italy, and the Netherlands. Nordic integrated fiber producers export molded-fiber substrates to North American craft brewery clusters. Yangzhou-based converters ship custom-printed hospitality formats to boutique hotel chains in Singapore, Melbourne, and Dubai.
United States
Specialty coffee roasters in Portland and Brooklyn commission short-run seasonal coaster designs as experiential marketing touchpoints. FDA food-contact substance regulations filter non-certified imports, creating specification pull for domestic converters with ISO 22000 protocols. Chicago hospitality supply distributors anchor Midwest procurement flows for independent bar and restaurant operators.
Germany
Brewery culture in Bavaria and North Rhine-Westphalia sustains per-capita consumption levels above European averages. VerpackG extended producer responsibility mandates recyclable recovery targets that favor pressed-pulp formats over plastic-lined alternatives. Hamburg and Munich industrial zones concentrate molded-fiber converting capacity for export to neighboring EU markets.
China
Yangzhou and Shanghai converters compete on custom-printed formats for Asia-Pacific boutique hotel procurement. GB standards for food-contact paperboard shape domestic ink chemistry specifications, though export-oriented suppliers dual-certify to FDA and EU frameworks. Pearl River Delta manufacturing clusters supply high-volume white-label inventory to wholesale distributors in Southeast Asia.
Japan
Tokyo and Osaka hospitality groups specify premium embossed and foil-stamped coasters for luxury hotel amenity programs. METI circular economy guidelines encourage uncoated cellulose procurement to align with 2030 packaging reduction targets. Kyoto craft distilleries commission limited-edition lithographic runs for seasonal beverage releases, collapsing traditional minimum order quantities.
United Kingdom
London specialty coffee chains rotate branded coaster designs quarterly to maintain Instagram-visible tabletop aesthetics. EU Packaging and Packaging Waste Directive alignment pressures post-Brexit domestic regulations toward recyclable single-use definitions. Manchester and Birmingham independent breweries source compostable ASTM D6400-certified formats for zero-waste venue mandates.
Paper Coaster Market Competitive Landscape
Player mix skews toward integrated pulp-to-converting specialists and regional hospitality-focused fabricators. Market structure concentrates volume among Nordic and North American fiber producers with captive raw material access, while Asia-Pacific competition fragments across custom-printing specialists. Two strategic archetypes dominate: vertically integrated multinational converters leveraging scale economies, and agile regional players competing on design turnaround velocity. Capacity expansion and compostable certification acquisition represent the dominant competitive moves as operators pre-empt regulatory tightening.
Among Nordic-based integrated producers, Huhtamaki Oyj exemplifies the multinational archetype with molded fiber expertise spanning European foodservice supply. International Paper Company anchors North American volume through pulp-to-converting operations. Yangzhou Ecoway Hotel Supply Co., Ltd. occupies a position within the Asia-Pacific custom-printing tier, serving boutique hospitality chains across the region. These three entities represent the geographic and capability span of competitive positioning in cellulose-based tabletop accessories.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Huhtamaki Oyj |
| Graphic Packaging International |
| International Paper Company |
| Novolex Holdings |
| Mondi Group |
| Pactiv Evergreen Inc. |
| WestRock Company |
| Yangzhou Ecoway Hotel Supply Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Nordic pulp producers and North American hospitality distributors lock in both supply access and price visibility, insulating converters from spot-market volatility in northern bleached softwood kraft contracts while compressing margin recovery during energy cost spikes.
Pricing Analysis
Digital print technology versus conventional lithography versus hand-finished specialty formats creates a three-tier pricing structure across premium, standard, and economy levels. Pricing stratifies across ASTM D6400 compostable certification tiers, uncoated cellulose grades, and volume scale commitments from boutique hotel chains. Cost compression in the standard tier is intensifying because pulp contracts fluctuate with Nordic energy markets. Independent craft breweries exhibit highest price sensitivity, while luxury hotel amenity programs demonstrate lowest sensitivity to unit cost differentials.
Supply Chain Analysis
Inventory cycles stretching from Finnish pulp mills to German converting plants and onward to hospitality distributors in France and the Netherlands expose operators to extended lead-time vulnerability. Raw material flows draw from Swedish softwood forests, recycled paperboard streams, and molded-fiber formulations. Single-source risk concentrates in Nordic integrated producers during Baltic Sea transport disruptions. Distribution runs through wholesale hospitality supply aggregators and direct converter relationships with large hospitality groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA food-contact notification requirements and ISO 22000 certification protocols create eighteen-month qualification barriers that shield qualified suppliers from import substitution.
For Market Incumbents: Compound certification depth by acquiring ASTM D6400 and EN 13432 compostable credentials ahead of EU Packaging Directive revisions. Add molded-fiber capacity in Germany to defend against Nordic transport disruption risks. Channel control through integrated FFE platform partnerships locks out single-product converters lacking cross-category bundling capability. For New Entrants and Emerging Players: Short-run digital customization services represent an underserved layer where incumbents under-serve craft distillery and seasonal hospitality procurement. Penetrate the Asia-Pacific boutique hotel segment through Yangzhou-style custom-printing agility with week-long turnaround. Deploy on-demand inkjet production systems to collapse minimum order quantities from container-load to pallet-scale. For Investors and Strategic Acquirers: Capital is best deployed toward converters with captive pulp supply and established FDA notification portfolios. Long-term viability centers on regulatory compliance infrastructure rather than commodity scale. Watch for EU ink migration threshold debates as the signal indicating specification overhaul and contract renewal cycle disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Certification Acquisition | ASTM D6400 and EN 13432 credentials unlock zero-waste venue procurement mandates in Copenhagen and Portland. |
| Digital Print System Deployment | On-demand inkjet infrastructure collapses minimum order quantities for Kentucky craft distillery seasonal campaigns. |
| Backward Integration into Pulp Supply | Captive softwood fiber access insulates margins from Nordic energy market volatility affecting contract pricing. |
| FFE Platform Partnership | Cross-category bundling with furniture and fixture suppliers locks out standalone coaster converters from Tokyo hotel procurement. |
| Regional Converting Capacity Addition | Localized production in Germany reduces Baltic Sea transport exposure for French and Dutch hospitality supply chains. |
Research Methodology
Cross-validation between converter production data and hospitality procurement records anchors the qualitative findings in this study. Primary interviews with molded-fiber plant managers, boutique hotel procurement directors, craft brewery operations leads, and foodservice distribution channel heads combined with secondary validation from FDA food-contact substance filings, EU Packaging Directive implementation reports, customs trade databases, and SEC disclosures from integrated pulp producers. Bottom-up volume aggregation and top-down market sizing triangulate demand estimates.
Sensitivity analysis across pulp price scenarios, regulatory timeline assumptions, and substitution elasticity parameters shapes the analytical framework. Segmentation dimensions include product certification tier, end-use channel, print technology type, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for policy inflection points. Forecast inputs incorporate VerpackG recovery target compliance rates and specialty coffee chain expansion trajectories.
Forecasts assume regulatory continuity in FDA food-contact regimes and EU Packaging Directive frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Clay Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Kraft Paper Bakery Bags Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Kitchen Roll Market