
 Indonesia Paper Packaging Market | 2026-2036
Indonesia Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Paper Packaging Market Foresight
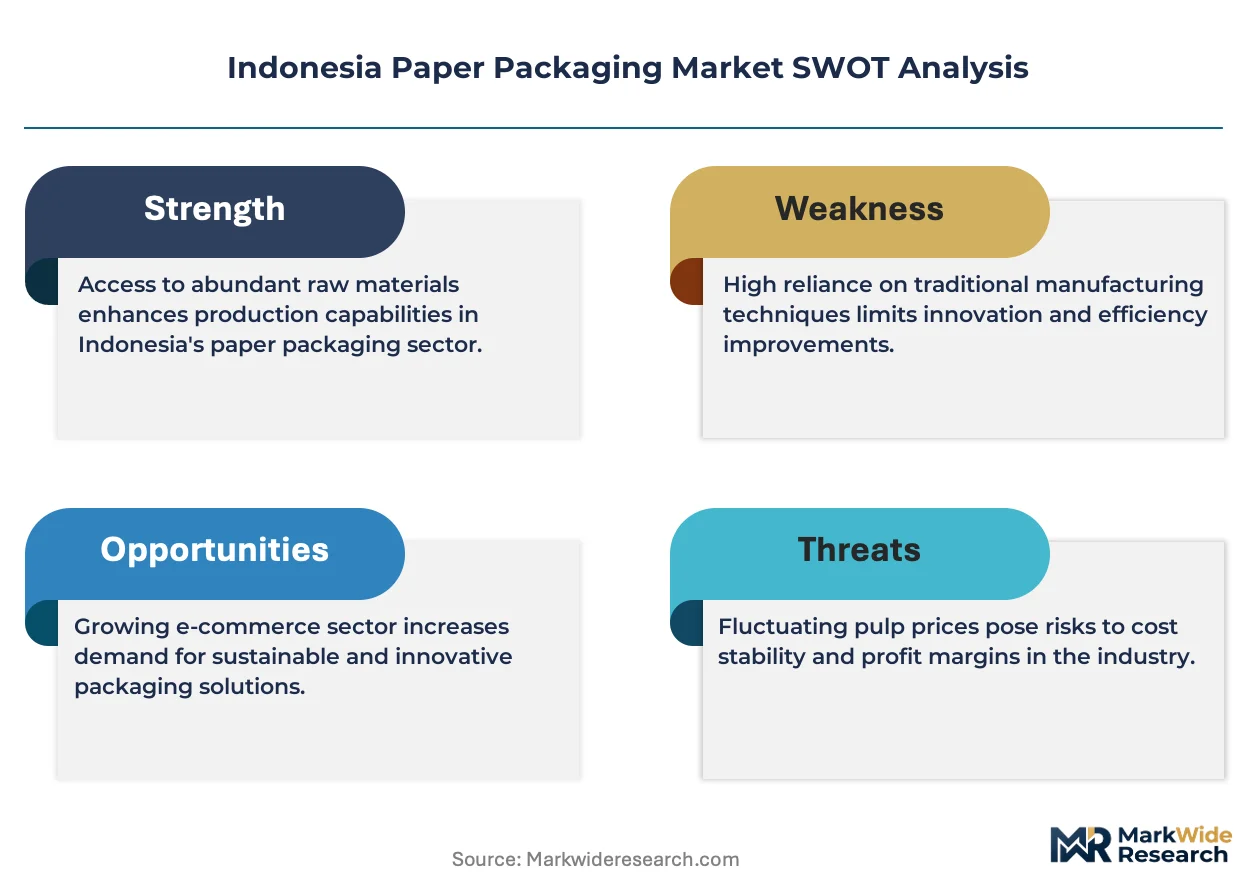
E-commerce fulfillment networks is reorganizing procurement patterns across the Indonesia paper packaging landscape, pulling volume away from traditional retail distributors toward direct-to-warehouse specifications. Asia Pulp and Paper (APP) Sinar Mas leverages its integrated pulp-to-box chain to dominate Java's corrugated supply. PT Indah Kiat Pulp and Paper Tbk anchors national capacity with virgin linerboard production at its Serang mill complex. Mondi plc competes through specialty kraft grades serving export-oriented food processors.
Indonesia paper packaging comprises containerboard, cartonboard, and flexible paper substrates engineered to specified burst strengths, moisture resistance, and printability thresholds for product protection and shelf presentation. Corrugated boxes and folding cartons lead volume, with specialty papers capturing margin pools in barrier-coated formats for humid tropical logistics. Recycled paper and kraft paper define the material mix, where recycled fiber supplies the cost-sensitive e-commerce segment and kraft underpins branded retail and export packaging requiring structural integrity.
BIS import certification, Indonesia's national standards body, restricts non-compliant foreign board entry and reinforces domestic mill expansion. The Ministry of Environment and Forestry enforces sustainable pulp sourcing audits that shape supplier qualification for multinational brand owners. Stakeholders must monitor regulatory alignment between domestic capacity expansion and evolving extended producer responsibility frameworks for post-consumer paper recovery.
Market Dynamics
E-commerce fulfillment networks are reorganizing procurement patterns across the archipelago, pulling volume away from traditional retail distributors toward direct-to-warehouse specifications. This structural shift concentrates demand in Java's manufacturing corridor while BIS certification requirements redirect sourcing toward domestic kraft paper mills.
Growth Catalysts
- Domestic mill expansion:BIS certification requirements for imported packaging materials redirect sourcing toward domestic kraft paper mills, reinforcing national capacity investment.
- E-commerce logistics:Direct-to-warehouse procurement specifications from fulfillment networks concentrate demand for corrugated and folding carton grades in Java's manufacturing corridor.
- Sustainable sourcing audits:The Ministry of Environment and Forestry enforces pulp sourcing verification that qualifies Indonesian suppliers for multinational brand owner contracts.
Market Restraints
- Recycled fiber cost volatility:Waste paper collection infrastructure gaps across the archipelago create input cost instability for cost-sensitive e-commerce packaging segments.
- Import certification friction:BIS compliance timelines for foreign board entry create supply bottlenecks during domestic mill capacity ramp-up periods.
- Barrier coating technical limitations:Humid tropical logistics requirements exceed standard moisture resistance thresholds, constraining adoption of uncoated recycled grades for export-oriented food processors.
Strategic Opportunities
- Eastern Indonesia penetration:Sulawesi and Papua manufacturing zones remain underdeveloped for corrugated conversion capacity relative to Java's saturation.
- Extended producer responsibility frameworks:Evolving post-consumer paper recovery mandates create white space for integrated collection-processing-conversion operators.
- Digital print convergence:Web-to-pack workflows combining inkjet personalization with short-run folding carton production open branded retail segments to mid-scale converters.
Industry Challenges
- Skilled technician scarcity:Barrier coating line operators and color management specialists for high-graphic retail packaging remain concentrated at APP Sinar Mas and Indah Kiat facilities.
- Capex intensity for compliance:BIS laboratory testing equipment and sustainable pulp chain-of-custody documentation systems require capital deployment ahead of contract qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Paper Packaging Market |
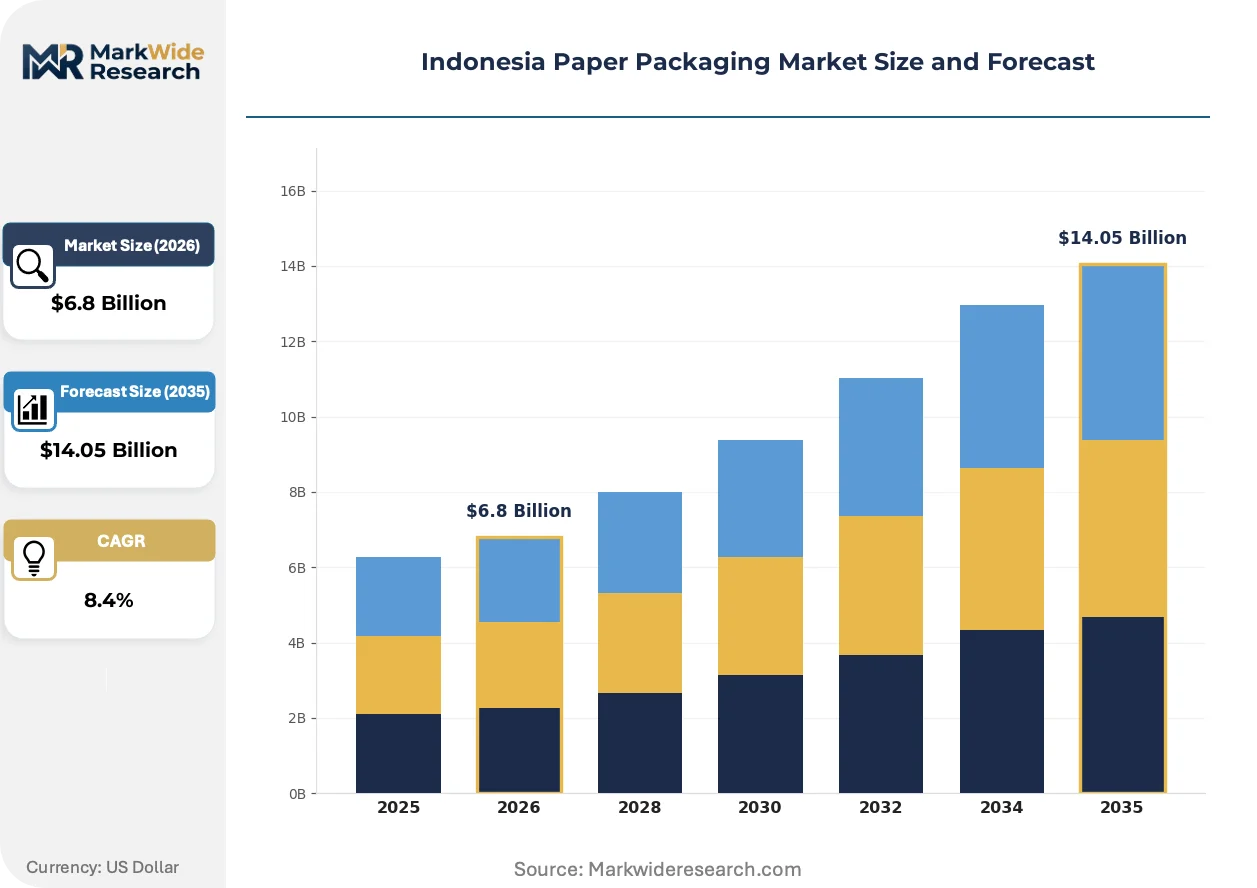
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Boxes, Paper Bags, Folding Cartons, Specialty Papers End User: Food & Beverage, Personal Care, Electronics, Healthcare Material: Recycled Paper, Virgin Paper, Kraft Paper, Coated Paper Application: Retail Packaging, Industrial Packaging, Protective Packaging, Shipping Packaging |
| Companies Covered | Asia Pulp and Paper (APP) Sinar Mas, PT Indah Kiat Pulp and Paper Tbk, PT Fajar Surya Wisesa Tbk, Mondi plc, Amcor plc, PT Industri Pembungkus Internasional, PT Pura Barutama, PT Surabaya Mekabox, PT Pabrik Kertas Indonesia (Pakerin), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Paper Packaging Market Shifts & Advancements
Water-based barrier coatings and digital print workflows are reshaping technical specifications across Indonesia's paper packaging value chain. These developments compress run lengths while elevating moisture performance requirements for tropical logistics.
Water-based barrier coatings engineered for grease and moisture resistance are supplanting conventional polyethylene extrusion laminates in food-contact folding carton applications. Export-oriented processors in Surabaya and Medan are adopting these substrates to meet EU Single-Use Plastics Directive alignment requirements from European retail buyers. The shift is compressing minimum order quantities while extending domestic coating line utilization rates.
BIS import certification protocols now mandate laboratory testing of burst strength, moisture resistance, and printability thresholds for all foreign-sourced containerboard and cartonboard. This regulatory friction is accelerating domestic linerboard investment at Serang and Perawang mill complexes. Small and mid-scale converters in Jakarta's Tangerang industrial zone are responding by consolidating purchase volumes through cooperative procurement arrangements.
Brand owners are unbundling graphic design from manufacturing procurement, contracting directly with Jakarta-based creative agencies before specifying converter execution. This disintermediation compresses traditional distributor margins while elevating technical dialogue between end-users and mill-direct sales teams. The pattern is most visible in premium personal care and confectionery verticals where shelf differentiation drives specification complexity.
Indonesia Paper Packaging Market Segmentation
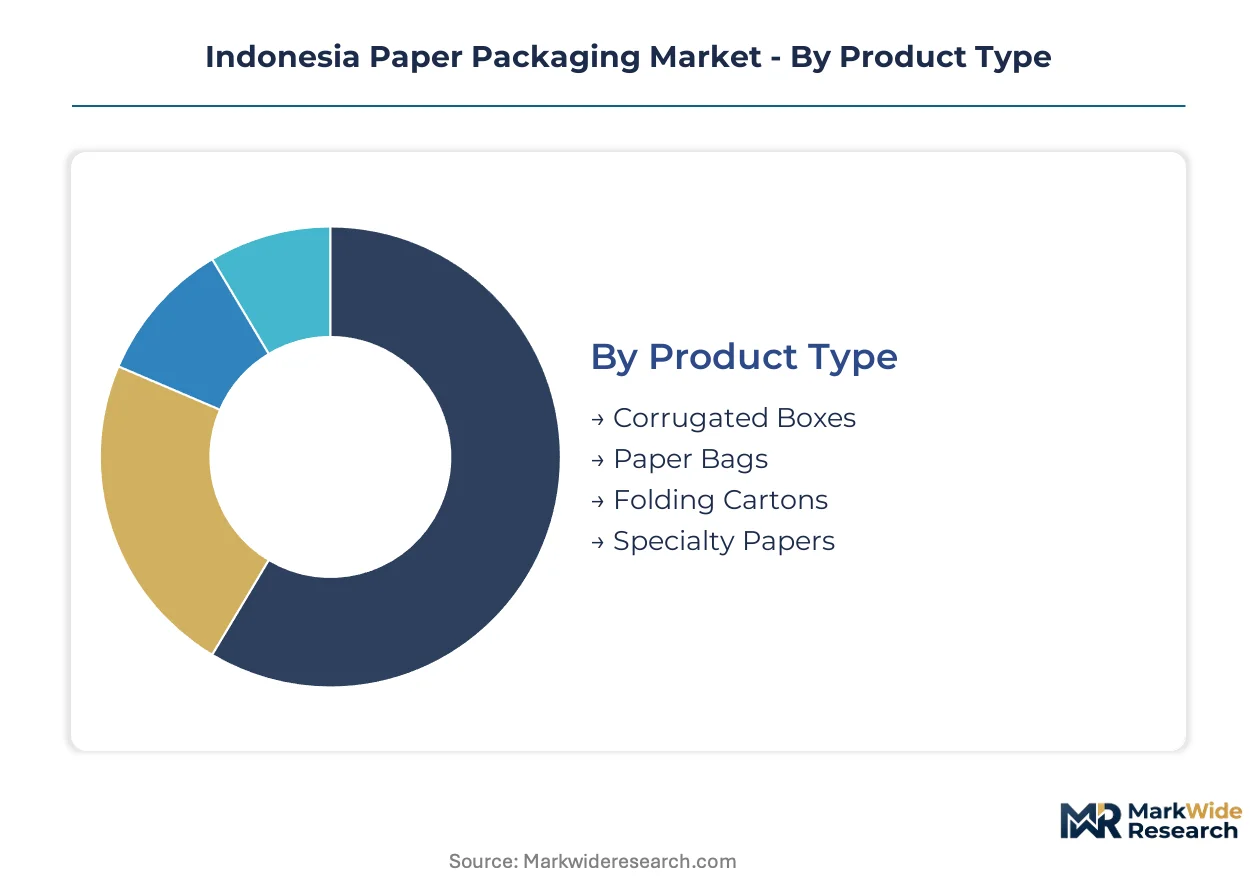
Segmentation in Indonesia's paper packaging market reveals how procurement specifications diverge between e-commerce fulfillment networks and traditional retail channels. Material choices and end-use requirements create distinct margin pools that favor integrated domestic producers over import-dependent converters.
Product Type:
Margin concentration follows corrugated capacity expansion in Java's manufacturing corridor, where e-commerce volume concentrates demand for standardized box specifications.
- Corrugated Boxes:Double-wall and single-wall flute configurations dominate Java's conversion capacity. Demand concentrates in Jakarta and Surabaya logistics hubs where direct-to-warehouse procurement from fulfillment networks compresses lead times.
- Folding Cartons:Coated and uncoated board grades engineered for high-graphic retail presentation. Premium personal care and confectionery verticals in Tangerang industrial zone drive specification complexity through direct brand owner engagement.
- Paper Bags:Twisted-handle and flat-handle formats for retail carryout applications.
- Specialty Papers:Grease-resistant and moisture-barrier substrates for food-contact applications.
Corrugated boxes hold installed capacity. Folding cartons are rotating up the share rankings.
End User:
Cost tier stratification separates multinational brand owner contracts from domestic SME procurement patterns.
- Food & Beverage:Processors in Surabaya and Medan specify barrier-coated folding cartons for export shipments. EU Single-Use Plastics Directive alignment requirements from European retail buyers accelerate water-based coating adoption.
- Personal Care:Premium shelf differentiation demands high-graphic cartonboard with registered color management. Jakarta-based creative agencies now contract directly with brand owners before specifying converter execution.
- Electronics:Anti-static corrugated and molded pulp formats for device protection.
- Healthcare:Sterile barrier systems and tamper-evident carton configurations.
Food & Beverage commands volume scale. Personal Care is expanding most quickly on premium positioning.
Material:
Supply concentration tilts toward domestic kraft paper mills as BIS certification redirects sourcing from import channels.
- Kraft Paper:Virgin fiber linerboard produced at Serang and Perawang mill complexes. Branded retail and export packaging requiring structural integrity specifies these grades for humid tropical logistics performance.
- Recycled Paper:Post-consumer fiber supplies cost-sensitive e-commerce segments. Waste paper collection infrastructure gaps across the archipelago create input cost instability for corrugated producers.
- Virgin Paper:Bleached hardwood pulp grades for high-brightness folding carton applications.
- Coated Paper:Clay-coated and barrier-coated substrates for moisture resistance and printability.
Kraft paper holds installed capacity. Recycled paper is rotating up the share rankings on sustainability mandates.
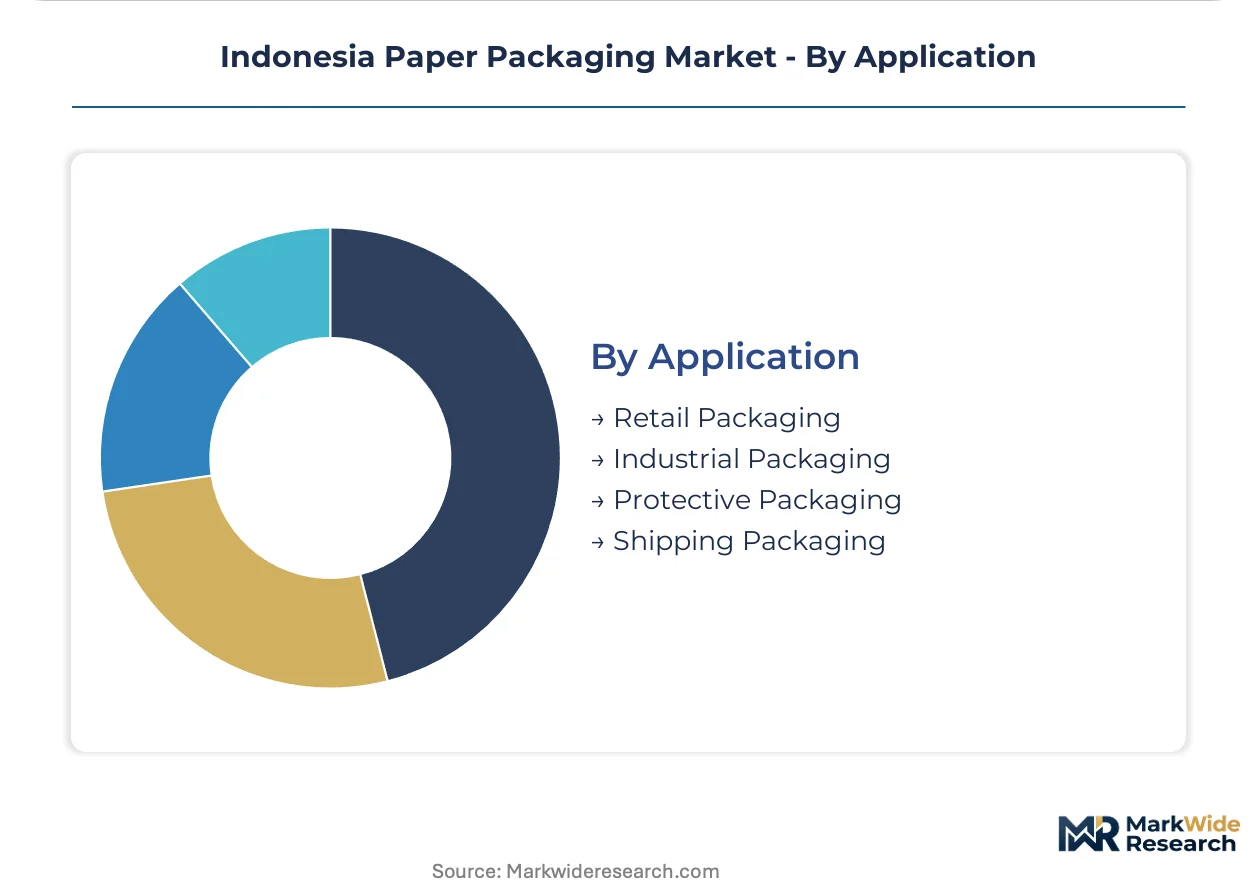
Application:
Customer type bifurcation separates fulfillment network specifications from conventional distributor-led procurement.
- Shipping Packaging:Corrugated case designs optimized for automated sortation and last-mile handling. E-commerce logistics networks concentrate demand in Java's manufacturing corridor with direct-to-warehouse specifications.
- Retail Packaging:Shelf-ready and display-ready carton configurations. Brand owners unbundle graphic design from manufacturing procurement, elevating technical dialogue with mill-direct sales teams.
- Industrial Packaging:Heavy-duty corrugated and multiwall sack formats for bulk commodity shipment.
- Protective Packaging:Die-cut inserts and molded pulp cushioning for fragile goods transport.
Shipping packaging holds installed capacity. Retail packaging is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration splits between e-commerce fulfillment networks demanding standardized corrugated specifications and brand owners pursuing premium folding carton differentiation. Domestic mill capacity anchors Java's manufacturing corridor while regulatory friction redirects import-dependent sourcing. Archipelago logistics create distinct procurement patterns across Indonesia's major economic zones.
Java
E-commerce fulfillment networks concentrate corrugated demand in Jakarta and Surabaya logistics hubs with direct-to-warehouse procurement specifications. BIS certification requirements redirect containerboard sourcing toward domestic kraft paper mills at Serang and Perawang complexes. Tangerang industrial zone hosts mid-scale converters consolidating purchase volumes through cooperative arrangements.
Sumatra
Pulp plantation feedstock supplies virgin fiber linerboard production for export-oriented packaging grades. Ministry of Environment and Forestry sustainable sourcing audits shape supplier qualification for multinational brand owner contracts. Medan processing clusters adopt water-based barrier coatings to meet EU Single-Use Plastics Directive alignment requirements.
Sulawesi
Underdeveloped corrugated conversion capacity relative to Java saturation creates white space for manufacturing zone expansion. Extended producer responsibility frameworks for post-consumer paper recovery remain nascent across the island. Makassar industrial corridor presents opportunity for integrated collection-processing-conversion operators.
Kalimantan
Resource extraction logistics drive demand for heavy-duty multiwall sack formats and industrial packaging substrates. Waste paper collection infrastructure gaps create input cost instability for recycled fiber-dependent producers. Balikpapan manufacturing clusters serve mining and palm oil export packaging requirements.
Papua
Remote logistics challenge last-mile distribution of standardized box specifications from Java-based converters. Barrier coating technical limitations for humid tropical logistics constrain adoption of uncoated recycled grades. Jayapura zone remains dependent on inter-island shipping for specialty kraft paper supply.
Indonesia Paper Packaging Market Competitive Landscape
Player mix skews toward integrated pulp-to-box conglomerates controlling virgin fiber supply chains alongside mid-scale converters dependent on cooperative procurement. Market structure concentrates around three strategic archetypes: integrated domestic producers with captive pulp supply, multinational specialty substrate suppliers, and regional conversion specialists serving single-island markets. Dominant competitive moves include backward integration into kraft linerboard production and capacity expansion at Perawang and Serang mill complexes.
Within the integrated domestic tier, Asia Pulp and Paper (APP) Sinar Mas and PT Indah Kiat Pulp and Paper Tbk exemplify scale-driven positioning through mill-direct sales engagement with fulfillment networks. Among specialty substrate specialists, Mondi plc occupies a position representing export-oriented barrier-coated grade supply. PT Fajar Surya Wisesa Tbk sits within the mid-scale conversion archetype, illustrating cooperative procurement responses to BIS certification timelines.
| Leading Market Players |
|---|
| Asia Pulp and Paper (APP) Sinar Mas |
| PT Indah Kiat Pulp and Paper Tbk |
| PT Fajar Surya Wisesa Tbk |
| Mondi plc |
| Amcor plc |
| PT Industri Pembungkus Internasional |
| PT Pura Barutama |
| PT Surabaya Mekabox |
| PT Pabrik Kertas Indonesia (Pakerin) |
| Others |
Supply & Pricing Matrix
Forty-five-day containerboard lead times from Perawang to Tangerang converters compress pricing power for import-dependent mid-scale operators while amplifying margin capture at Serang's integrated kraft linerboard complexes. This inventory-to-supply geometry concentrates procurement leverage among domestic mill-direct sellers serving Jakarta's e-commerce fulfillment networks.
Pricing Analysis
Conventional polyethylene extrusion laminates command premium spreads over water-based barrier coating generations entering Surabaya and Medan food-processor specifications. Contract-based long-term offtake dominates procurement for virgin linerboard grades, with price differentiation anchored in BIS certification tier and volume scale commitments. Cost compression in recycled corrugated segments intensifies because waste paper collection infrastructure gaps amplify input volatility. Domestic SME converters exhibit highest price sensitivity, while multinational brand owners prioritize moisture-resistance performance over unit economics.
Supply Chain Analysis
Strait of Malacca transit chokepoints amplify inventory risk for specialty kraft paper shipments bound for Papua and eastern Sulawesi manufacturing zones. Domestic supply concentrates in Java and Sumatra, with raw material dependencies centering on acacia plantation pulp feedstock, post-consumer waste paper streams, and clay coating minerals. Single-source vulnerability characterizes barrier-coated substrate supply for export-oriented food processors. Distribution runs through mill-direct sales teams for large-volume fulfillment network contracts, while cooperative procurement arrangements aggregate mid-scale converter demand in Tangerang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier coating line operators and color management specialists remain concentrated at APP Sinar Mas and Indah Kiat facilities, constraining technical execution capacity across Indonesia's mid-scale conversion tier.
For Market Incumbents: Compound captive pulp supply advantages through capacity expansion at Perawang and Serang mill complexes while accelerating water-based coating line deployment ahead of EU Single-Use Plastics Directive enforcement. Defend against specialty substrate specialists by locking multi-year direct-to-warehouse contracts with fulfillment networks. For New Entrants and Emerging Players: Differentiate on digital print convergence capabilities for short-run folding carton production serving Jakarta-based creative agencies. Target Sulawesi and Papua manufacturing zones where corrugated conversion capacity remains underdeveloped relative to Java saturation. Pursue cooperative procurement arrangements with Tangerang industrial zone converters as entry mechanism. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core Southeast Asian folding carton assets. Long-term viability hinges on integrated collection-processing-conversion positioning within extended producer responsibility frameworks. Monitor BIS certification timeline enforcement as inflection indicator for domestic mill valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Linerboard | Captive pulp supply at Serang and Perawang insulates APP Sinar Mas and Indah Kiat from import certification friction. |
| Water-Based Barrier Coating Line Deployment | Surabaya and Medan processors adopt these substrates to retain EU export market access under Single-Use Plastics Directive. |
| Digital Print Workflow Investment | Web-to-pack capabilities open premium personal care and confectionery segments to mid-scale Tangerang converters. |
| Cooperative Procurement Consolidation | Volume aggregation arrangements enable smaller Jakarta converters to meet BIS laboratory testing equipment capex requirements. |
| Eastern Indonesia Manufacturing Footprint | Makassar and Jayapura zones present white space for integrated operators serving resource extraction logistics demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ministry of Environment and Forestry sustainable sourcing audit records, BIS certification compliance databases, and customs/trade flow documentation. Interviews with mill procurement directors, corrugated plant managers, e-commerce fulfillment network supply planners, and barrier coating line operators combined with SEC filings of listed packaging conglomerates and pulp plantation production disclosures. Bottom-up volume aggregation across Java's Tangerang industrial zone and top-down demand validation from national e-commerce logistics expansion trajectories anchor triangulation integrity.
Segmentation dimensions modeled span product type, material grade tier, end-use vertical, and regional manufacturing cluster across the analysis window. CAGRs derive from installed capacity expansion timelines at Perawang and Serang complexes correlated with e-commerce fulfillment network procurement specifications. Forecast inputs incorporate BIS certification enforcement velocity and EU Single-Use Plastics Directive alignment requirements from European retail buyers.
Material uncertainties — recycled fiber cost volatility from waste paper collection infrastructure gaps, BIS compliance timeline delays for foreign board entry, and barrier coating technical performance thresholds — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as extended producer responsibility framework mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Cone Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Paper Wrap Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
South East Asia Corrugated Packaging Market
Paper & Paperboard Packaging
Paperboard Protectors Market