
 Recycled Paper Packaging Market | 2026-2036
Recycled Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Paper Packaging Market Outlook
Modular box configurations with variable depth and fold-to-size features is shifting how e-commerce and retail buyers specify orders, reducing void fill needs and dimensional weight charges. DS Smith leverages in-house recycling and papermaking to control fiber quality from collection through finished containerboard. Mondi competes through integrated kraft paper and corrugated operations across Central and Eastern Europe. Stora Enso anchors its position with renewable packaging materials and pilot-scale molded fiber innovations for food contact applications.
Recycled paper packaging comprises containers, wraps, and protective structures manufactured from repulped post-consumer or post-industrial fiber sources, typically requiring de-inking, screening, and refining to achieve target burst strength and cleanliness levels for direct product contact or secondary shipment use. The primary commercial purpose centers on substituting virgin fiber with recovered material to lower Scope 3 emissions while maintaining stackability and printability. Corrugated boxes within the product type category dominate volume due to their structural utility in omnichannel fulfillment, though molded containers and custom-formed solutions capture expanding margin pools in temperature-sensitive and fragile-goods segments. Post-consumer grade material commands attention from brand owners publishing recycled content claims, while post-industrial streams offer more predictable fiber length and contamination profiles for high-speed converting lines.
The EPA promotes recovered fiber utilization through recycled content procurement guidelines for federal agencies, while the EU Green Deal and Packaging and Packaging Waste Regulation set binding reuse and recycling targets that reshape material specifications across export-bound production. FDA food contact notifications and state-level extended producer responsibility laws in California and Maine further constrain allowable additives and require chain-of-custody documentation for recycled fiber used in direct food applications. Stakeholders must monitor how diverging national recycled content thresholds and harmonization efforts under ISO standards affect cross-border sourcing strategies and capital allocation for de-inking and cleaning equipment.
Market Dynamics
Post-consumer corrugated fiber procurement is tightening across European retail and logistics networks as binding recycled content mandates under the EU Packaging and Packaging Waste Regulation force specification changes at the buyer level.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding recycled content thresholds for secondary packaging redirect procurement volumes toward post-consumer fiber sources across member states.
- E-commerce fulfillment expansion:Omnichannel retailers specify modular box designs with variable depth to cut dimensional weight charges and void fill costs.
- Molded fiber innovation:Temperature-sensitive food contact applications drive pilot-scale capacity additions for protective structures in direct product packaging.
Market Restraints
- Contamination volatility in post-consumer streams:De-inking and cleaning capex requirements rise as fiber quality inconsistency forces redundant processing stages.
- Post-industrial supply concentration:Predictable fiber length from manufacturing scrap concentrates with integrated paperboard producers, limiting merchant market availability.
- Plastic substitution threat in barrier applications:Grease-resistant and moisture-blocking requirements in protein packaging favor multi-material laminates over pure paper solutions.
Strategic Opportunities
- Extended Producer Responsibility tailwinds:California and Maine EPR laws create compliance-driven demand for chain-of-custody documentation and certified recycled content.
- Pharmaceutical cold chain expansion:Insulated molded fiber containers for temperature-sensitive biologics open premium-margin segments beyond food contact.
- Industrial IoT convergence with packaging design:Embedded sensors in corrugated structures enable track-and-trace compliance for high-value electronics shipments.
Industry Challenges
- De-inking chemistry skill gaps:Specialized operators for enzymatic and flotation-based contaminant removal command wage premiums as capacity scales.
- FDA food contact notification timelines:Recycled fiber additives and processing aids face 12-18 month review cycles that delay product launches.
- Legacy converting line retrofit costs:High-speed folder-gluers require tension and adhesive adjustments to handle variable-strength recycled board without jam rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Paper Packaging Market |
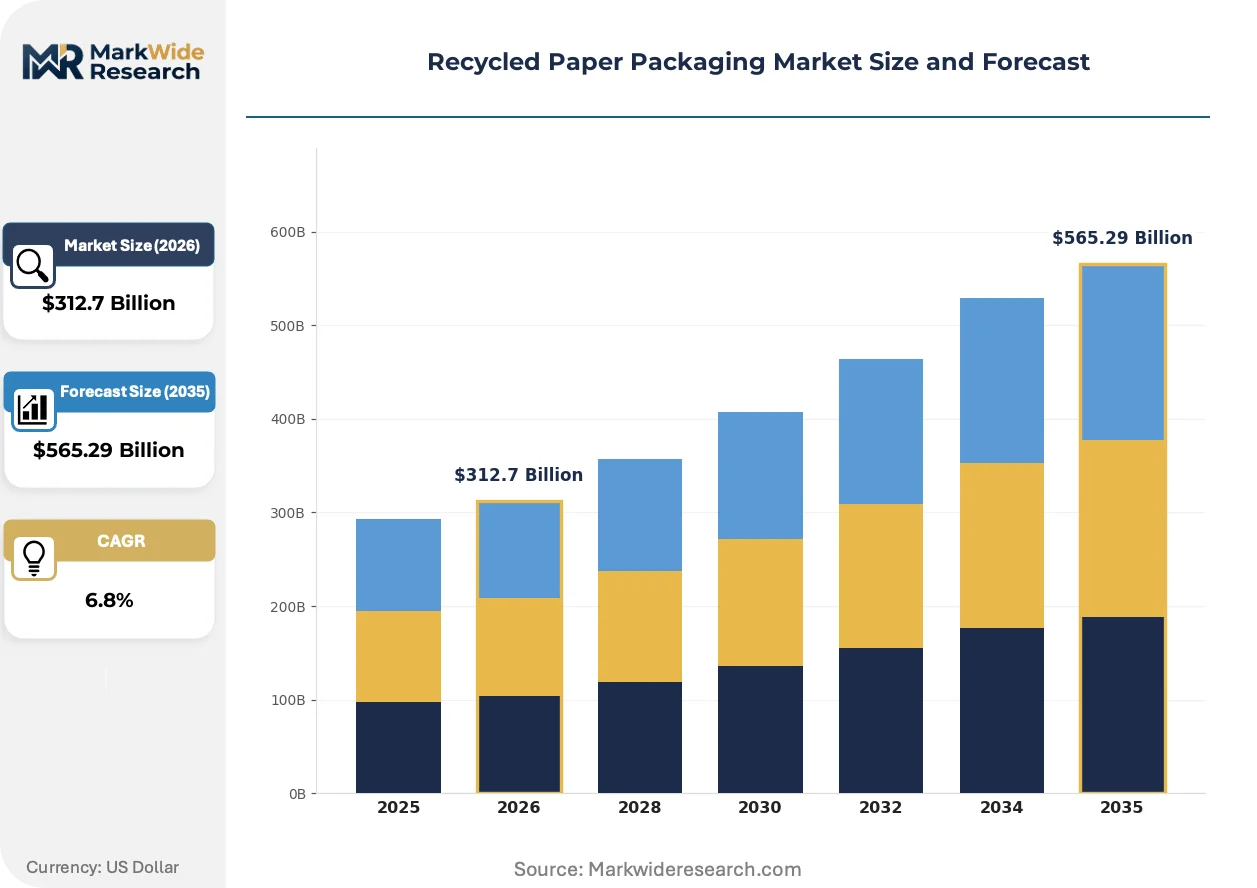
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Sheets, Containers End Use Industry: Food & Beverage, Personal Care, Electronics, Retail Grade/Purity: Post-Consumer, Post-Industrial, Corrugated, Bleached Packaging Type: Flexible, Rigid, Specialty, Custom |
| Companies Covered | WestRock Company, DS Smith, Smurfit Westrock, UPM, Packaging Corporation of America, International Paper Company, Mondi, Oji Holdings, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Paper Packaging Market Strategic Shifts
Digital printing integration with short-run corrugated production is collapsing minimum order quantities and enabling mass customization for regional brand variants.
Enzymatic de-inking systems recover fiber from mixed post-consumer streams at lower energy intensity than conventional flotation methods. European containerboard mills adopt these systems to meet EU Green Deal carbon intensity benchmarks. The technology is expanding into North American operations as EPA procurement guidelines for federal agencies tighten recycled content specifications.
The EU Packaging and Packaging Waste Regulation mandates reuse targets and harmonized extended producer responsibility schemes across member states. Industrial converters redesign box specifications to qualify for reuse loops in closed supply chains between manufacturers and retail distribution centers. German retail chains now specify minimum recycled fiber thresholds that exceed baseline compliance, compressing virgin fiber demand in secondary packaging.
Brand owners consolidate supplier relationships around integrated recyclers with captive pulp mills. Food and beverage procurement teams audit chain-of-custody documentation for Scope 3 emissions reporting. This concentration is most visible in German-speaking markets where logistics operators bundle corrugated specifications across multiple retail accounts.
Recycled Paper Packaging Market Segmentation
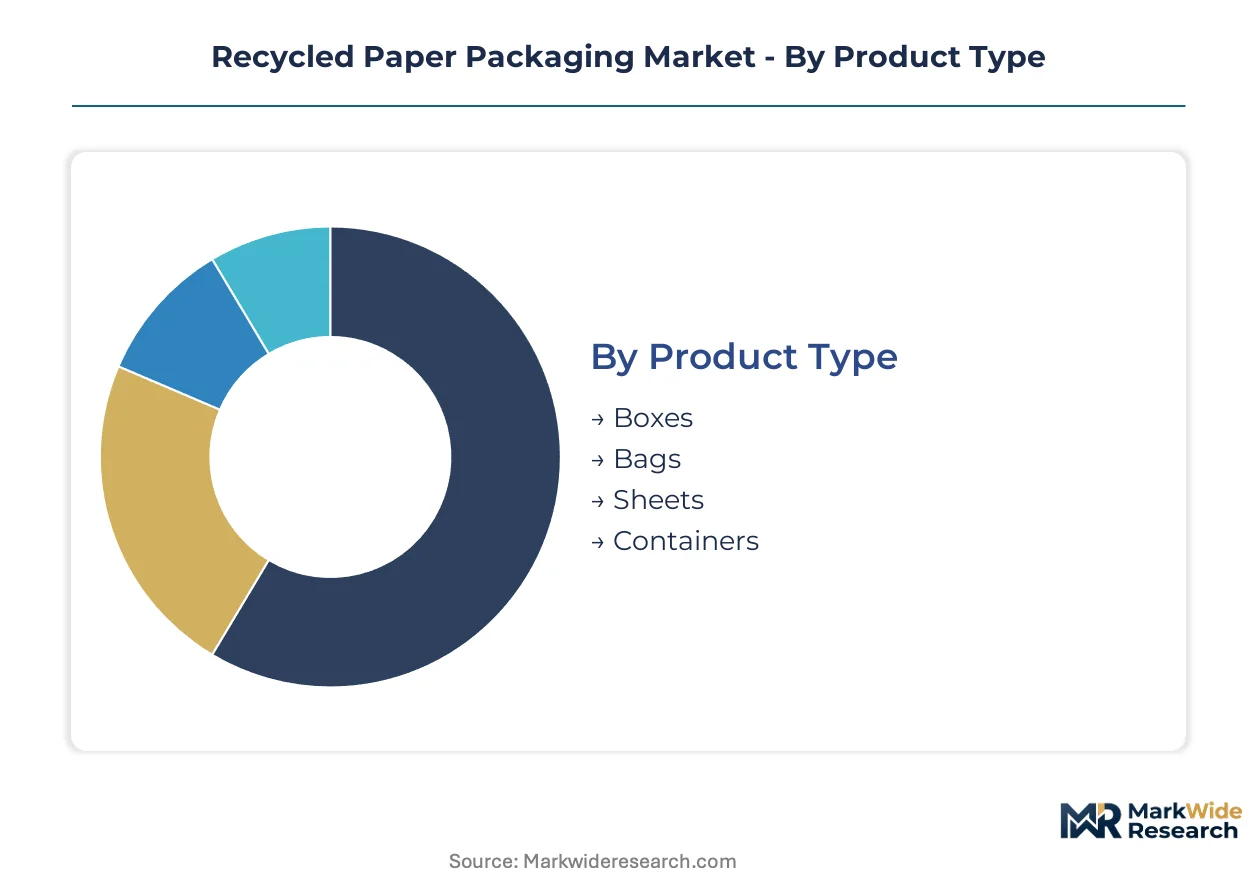
Segmentation in recycled paper packaging reveals how fiber sourcing, structural requirements, and end-use compliance demands split procurement budgets across incompatible specifications. Buyers optimize for either carbon accounting visibility or line-speed compatibility, rarely both.
Product Type:
Structural complexity and void-fill economics separate buyers selecting between commodity corrugated and precision-formed alternatives.
- Boxes:Corrugated containers with variable-depth scoring dominate omnichannel fulfillment specifications. German retail chains and logistics operators mandate minimum post-consumer fiber thresholds that compress virgin board demand in secondary packaging.
- Containers:Molded fiber structures for temperature-sensitive applications require controlled density and food-contact certification. Pilot-scale capacity additions target biologics cold chain and prepared meal segments where insulation performance commands premium positioning.
- Bags:Multi-wall constructions with recycled kraft outer plies serve agricultural and construction bulk packaging where tear resistance outweighs print quality requirements.
- Sheets:Interlayer and protective wrap formats from repulped furnish absorb shock in electronics and glassware shipment, competing against plastic bubble alternatives on Scope 3 metrics.
Boxes lead volumes today; containers are gaining share fastest.
End Use Industry:
Regulatory exposure and chain-of-custody documentation intensity vary sharply across buyer categories.
- Food & Beverage:Direct contact applications face FDA notification timelines and EU Packaging and Packaging Waste Regulation recycled content mandates. De-inking chemistry and additive compliance absorb disproportionate quality assurance resources.
- Electronics:Anti-static and moisture-barrier specifications favor coated papers and hybrid laminates over pure recycled fiber solutions, though molded fiber corner protectors gain traction in unboxing experience design.
- Personal Care:Premium positioning through tactile finishes and embossing drives specification of higher-grade bleached recycled furnish with controlled contamination profiles.
- Retail:Omnichannel fulfillment demands modular box configurations with digital print compatibility for regional variant customization at short run lengths.
Food & Beverage absorbs the largest procurement volumes; Electronics shows the steepest expansion trajectory in protective applications.
Grade/Purity:
Fiber provenance determines both emissions accounting credibility and converting line compatibility.
- Post-Consumer:Mixed office paper and residential collection streams require enzymatic de-inking and flotation cleaning to meet brightness targets. California and Maine EPR laws create compliance-driven demand for certified chain-of-custody documentation.
- Post-Industrial:Manufacturing scrap from converting operations offers predictable fiber length and low contamination, concentrating supply with integrated producers who capture captive pulp streams.
- Corrugated:Old containerboard repulped without de-inking suits non-contact outer layers and void fill where printability is secondary to structural performance.
- Bleached:Hydrogen peroxide or chlorine-free brightening of recycled furnish enables food contact and premium cosmetic packaging with visual parity to virgin fiber.
Post-Industrial dominates merchant availability; Post-Consumer is climbing fastest under mandate pressure.
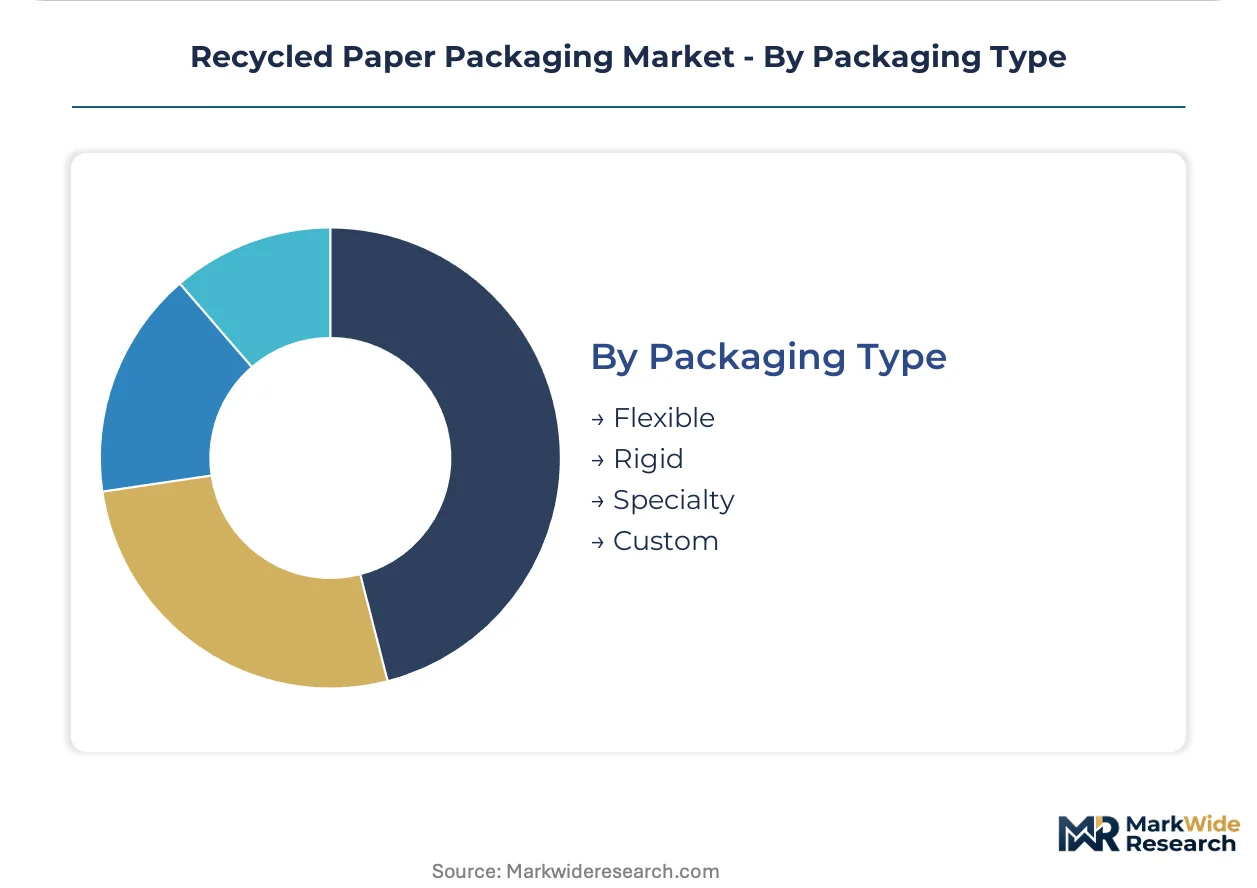
Packaging Type:
Capital equipment compatibility and automation readiness shape buyer selection between format categories.
- Rigid:Corrugated and solid fiberboard structures with defined edge crush test specifications integrate with automated case erectors and palletizing systems in high-volume distribution centers.
- Flexible:Kraft paper wraps, pouches, and multi-wall sacks require tension control on form-fill-seal lines but reduce material intensity for dry bulk and agricultural products.
- Specialty:Temperature-controlled and moisture-barrier constructions combine recycled fiber substrates with functional coatings for protein and pharmaceutical segments.
- Custom:Short-run digital print integration with die-cut formats enables regional brand variant launches without plate costs or inventory risk.
Rigid formats command current procurement volumes; Custom solutions are expanding most quickly alongside digital converting investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled paper packaging industrialized first in Germany during the post-war reconstruction era, when fiber scarcity drove systematic recovery systems. The sector subsequently scaled through Nordic pulp-to-packaging integration and North American corrugated consolidation.
Germany
Retail chains and logistics operators mandate minimum post-consumer fiber thresholds exceeding baseline EU compliance. The country's national packaging regulator enforces extended producer responsibility schemes with harmonized fee modulation. The Rhine-Ruhr industrial corridor hosts integrated containerboard mills converting old corrugated containers into secondary packaging for automotive and consumer goods distribution.
United States
E-commerce fulfillment networks specify modular box designs with variable depth scoring to minimize dimensional weight charges. The EPA maintains recycled content procurement guidelines for federal agency purchasing that redirect volumes toward post-consumer sources. The Southeast manufacturing belt from Georgia to Tennessee concentrates corrugated converting capacity serving omnichannel retailers with short-run digital print integration.
China
Domestic e-commerce platforms accelerate demand for lightweight corrugated solutions in last-mile delivery networks. The Ministry of Ecology and Environment implements dual carbon goals that constrain virgin pulp expansion and favor recovered fiber utilization. The Yangtze River Delta cluster around Shanghai integrates wastepaper collection with containerboard production for export-bound electronics packaging.
India
Organized retail and quick-commerce platforms adopt corrugated shipper boxes for temperature-sensitive food delivery. The national food safety regulator mandates chain-of-custody documentation for recycled fiber in direct food contact applications. The Maharashtra-Gujarat industrial corridor develops molded fiber capacity for pharmaceutical cold chain packaging serving domestic biologics distribution.
Japan
Precision electronics manufacturers specify anti-static corrugated structures with controlled moisture barriers for semiconductor shipment. The Ministry of Economy, Trade and Industry promotes circular economy roadmaps that set voluntary recycled content targets for industrial packaging. The Kansai region around Osaka maintains legacy integrated pulp-to-box operations serving machinery and automotive component exporters.
Recycled Paper Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across food-contact certification and cold-chain performance tiers. The market structure consolidates around integrated producers with captive pulp mills and merchant converters sourcing fiber on spot markets. Three archetypes dominate: Nordic forest products groups with renewable materials positioning, North American corrugated specialists with e-commerce fulfillment scale, and Asian integrated paperboard producers with cost-advantaged recovered fiber access. Competitive moves concentrate on backward integration into wastepaper collection networks and enzymatic de-inking technology licensing.
Within the integrated producer tier, DS Smith exemplifies European containerboard consolidation with in-house recycling and papermaking control. Mondi occupies a position bridging Central and Eastern European kraft paper operations with corrugated converting scale. WestRock Company anchors North American corrugated capacity serving omnichannel retail and industrial distribution networks.
| Leading Market Players |
|---|
| WestRock Company |
| DS Smith |
| Smurfit Westrock |
| UPM |
| Packaging Corporation of America |
| International Paper Company |
| Mondi |
| Oji Holdings |
| Stora Enso |
| Others |
Value Chain & Pricing Dynamics
Enzymatic de-inking adoption across European containerboard mills compresses processing costs while concentrating supply among technology-licensed producers. This production-method transition simultaneously lowers energy intensity per ton and tightens merchant market availability as integrated players capture efficiency gains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by food-contact certification grade and chain-of-custody documentation completeness. Price differentiation hinges on FDA notification status and EU Packaging and Packaging Waste Regulation compliance tier. Cost compression in post-consumer fiber grades is intensifying because de-inking capex requirements outpace yield improvements. Quick-commerce platforms and agricultural bulk buyers exhibit highest price sensitivity; pharmaceutical cold-chain purchasers show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German integrated containerboard producers who control Rhine-Ruhr collection-to-converting corridors. Geographic supply concentration centers on Germany, the United States, and China as dominant production clusters. Raw material dependencies rest on old corrugated containers, mixed office wastepaper, and enzymatic processing chemicals. Tariff exposure on recovered fiber imports into Asian markets poses structural risk. Distribution runs through mill-direct contracts to retail chains and logistics operators, with spot market volumes serving smaller converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
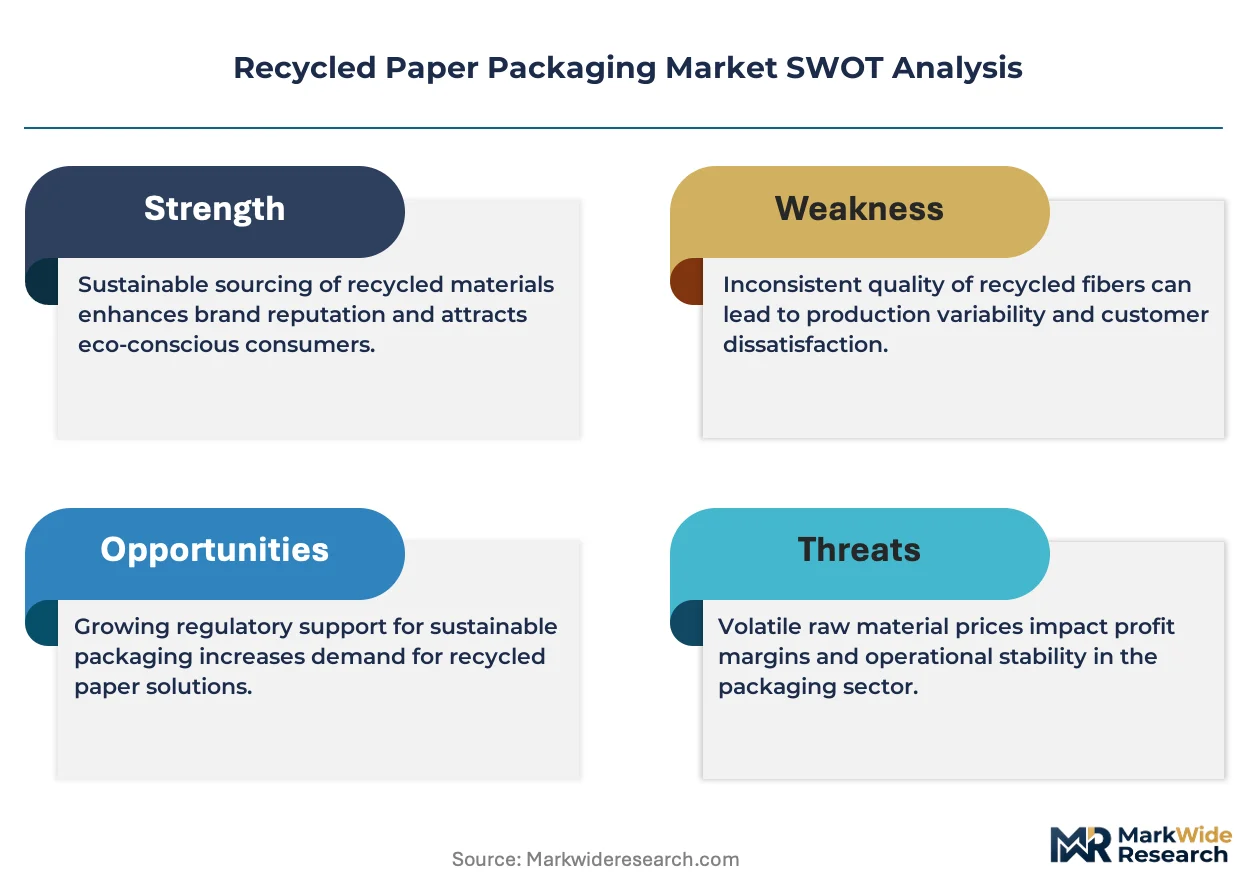
The recycled paper packaging market functions as a regulatory compounder where the EU Packaging and Packaging Waste Regulation mandates reshape procurement specifications and pricing power simultaneously.
For Market Incumbents: Anticipate margin compression from plastic substitution in barrier applications by accelerating molded fiber capacity for temperature-sensitive segments. Defensive consolidation through enzymatic de-inking technology licensing locks in fiber quality control. Captive wastepaper collection network expansion in Germany and the United States secures post-consumer supply against merchant market tightening. For New Entrants and Emerging Players: California and Maine EPR laws open a window for compliance-focused service models targeting chain-of-custody documentation gaps. White-space concentration sits with pharmaceutical cold-chain molded fiber where certification barriers filter competition. Direct-to-brand sales bypassing integrated producer hierarchies offers the most penetrable go-to-market angle for mid-scale enzymatic operations. For Investors and Strategic Acquirers: Valuations sit cheapest among merchant converters without captive pulp mills or de-inking assets. Long-term viability across the next decade favors backward integration into collection networks and enzymatic technology positions. The signal to watch is FDA food contact notification approval timelines shortening for recycled fiber additives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive post-consumer fiber supply secures EU Packaging and Packaging Waste Regulation compliance thresholds. |
| Enzymatic De-inking Technology Licensing | Energy intensity reductions align with EU Green Deal carbon benchmarks while filtering competition. |
| Molded Fiber Capacity Expansion | Temperature-sensitive food contact and pharmaceutical cold-chain applications command premium positioning. |
| Chain-of-custody Certification Investment | California and Maine EPR laws create compliance-driven demand for documented recycled content. |
| Digital Print Integration with Corrugated Converting | Short-run regional variant production collapses minimum order quantities for omnichannel retailers. |
Study Parameters
Direct dialogue with containerboard mill operations directors, retail procurement managers, logistics specification engineers, and enzymatic de-inking technology providers grounded qualitative findings. Secondary validation drew from EPA procurement guideline documents, EU Packaging and Packaging Waste Regulation filings, FDA food contact notification databases, and trade association recovered fiber utilization reports. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Bottom-up segment analysis tracked product type, end-use industry, fiber grade purity, and packaging format dimensions across the projection horizon. CAGRs derived from production capacity expansion schedules, regulatory mandate implementation timelines, and substitution elasticity estimates for plastic alternatives. Forecast inputs incorporated e-commerce fulfillment growth trajectories and enzymatic de-inking yield improvement curves.
Revisions become necessary when EU member state recycled content thresholds diverge, FDA notification timelines extend materially, or post-consumer fiber contamination rates spike unexpectedly. Forecasts reflect documented assumptions about regulatory harmonization progress and technology diffusion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Middle East Corrugated Packaging Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Secondary Paper and Paperboard Luxury Packaging Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market