
 Self-Sealing Paper Bands Market | 2026-2036
Self-Sealing Paper Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Sealing Paper Bands Market Analytics
Subscription-based maintenance programs for banding equipment is restructuring how packaging converters purchase fastening solutions. Brown & Pratt Inc. leverages its geographic footprint across North American industrial corridors. Wexler Packaging Products Inc. anchors its position through specialized machinery integration services. Amcor plc competes by extending its materials science expertise into fiber-based sealing formats.
Self-sealing paper bands are pre-gummed paper strips, typically 20-50 mm wide, that activate adhesive upon pressure application without additional heat or moisture, designed for bundling documents, currency, retail products, and lightweight parcels. Kraft paper bands dominate unit volumes due to tensile strength compatibility with automated banding equipment, while recycled paper variants capture sustainability-driven procurement mandates from corporate buyers. Flat bands lead in industrial shipping applications where throughput speed matters, whereas decorative bands command margin pools in premium retail branding segments.
The EPA guides recycled content thresholds for paper products in the United States, while the EU Green Deal and REACH framework govern chemical adhesive disclosures and circularity claims across European supply chains. FDA indirect food contact regulations shape material selection for bands used in food-adjacent packaging applications. Stakeholders must monitor evolving extended producer responsibility schemes that will determine which material grades retain cost-competitive market access.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing compliance timelines for paper-based fasteners, forcing converters to accelerate material certification cycles and reconfigure adhesive formulations ahead of enforcement deadlines.
Growth Catalysts
- E-commerce fulfillment velocity:Parcel bundling operations in automated distribution centers demand pressure-activated bands that eliminate heat-sealing equipment. Germany's industrial packaging clusters supply Central European networks with pre-gummed formats optimized for high-throughput lines.
- REACH chemical disclosure mandates:The EU framework requires granular adhesive component reporting, advantaging converters with pre-certified supply chains. Corporate buyers now specify REACH-compliant bands for retail packaging to preempt downstream liability.
- Kraft paper tensile compatibility:Automated banding equipment from food processing to currency handling requires specific strength-to-weight ratios. Equipment manufacturers validate kraft formulations, locking in material specifications across installed machinery bases.
Market Restraints
- Pulp input cost volatility:Kraft paper pricing tracks softwood pulp futures, exposing converters to margin compression when energy costs spike in Nordic production regions. Long-term supply agreements with Scandinavian mills partially hedge this exposure.
- Adhesive supply concentration:Pressure-sensitive hot-melt formulations depend on specialized tackifier resins produced by a limited set of German and US chemical suppliers. Any disruption to rosin ester or hydrocarbon resin output propagates through banding material lead times.
- Polypropylene strap substitution:Synthetic banding retains cost advantages for heavy-load industrial bundling above 50 kilograms. Paper bands face technical ceiling constraints in construction materials and metal coil applications where elongation recovery matters.
Strategic Opportunities
- India's organized retail expansion:Modern trade formats in Mumbai and Delhi NCR are adopting standardized packaging for private-label goods. Local converters can capture share by developing humidity-stable adhesive formulations suited to monsoon distribution cycles.
- FDA indirect food contact pathways:Bands adjacent to packaged foods require specific substrate and adhesive clearances. Converters achieving FDA compliance unlock placement in bakery, confectionery, and prepared meal segments previously served by plastic clips.
- Digital printing convergence:Variable-data decoration on paper bands enables batch-level traceability and promotional customization. Pharmaceutical serialization requirements in the EU and US create demand for band-integrated QR codes and tamper-evident features.
Industry Challenges
- Adhesive formulation chemist scarcity:Pressure-sensitive adhesive expertise concentrates in tape and label industries, not paper converting. Band manufacturers compete for talent against better-capitalized packaging segments.
- Legacy equipment retrofit complexity:Converting lines designed for plain paper bands require mechanical and control system modifications to handle printed or reinforced variants. Downtime costs deter mid-cap converters from capability upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Sealing Paper Bands Market |
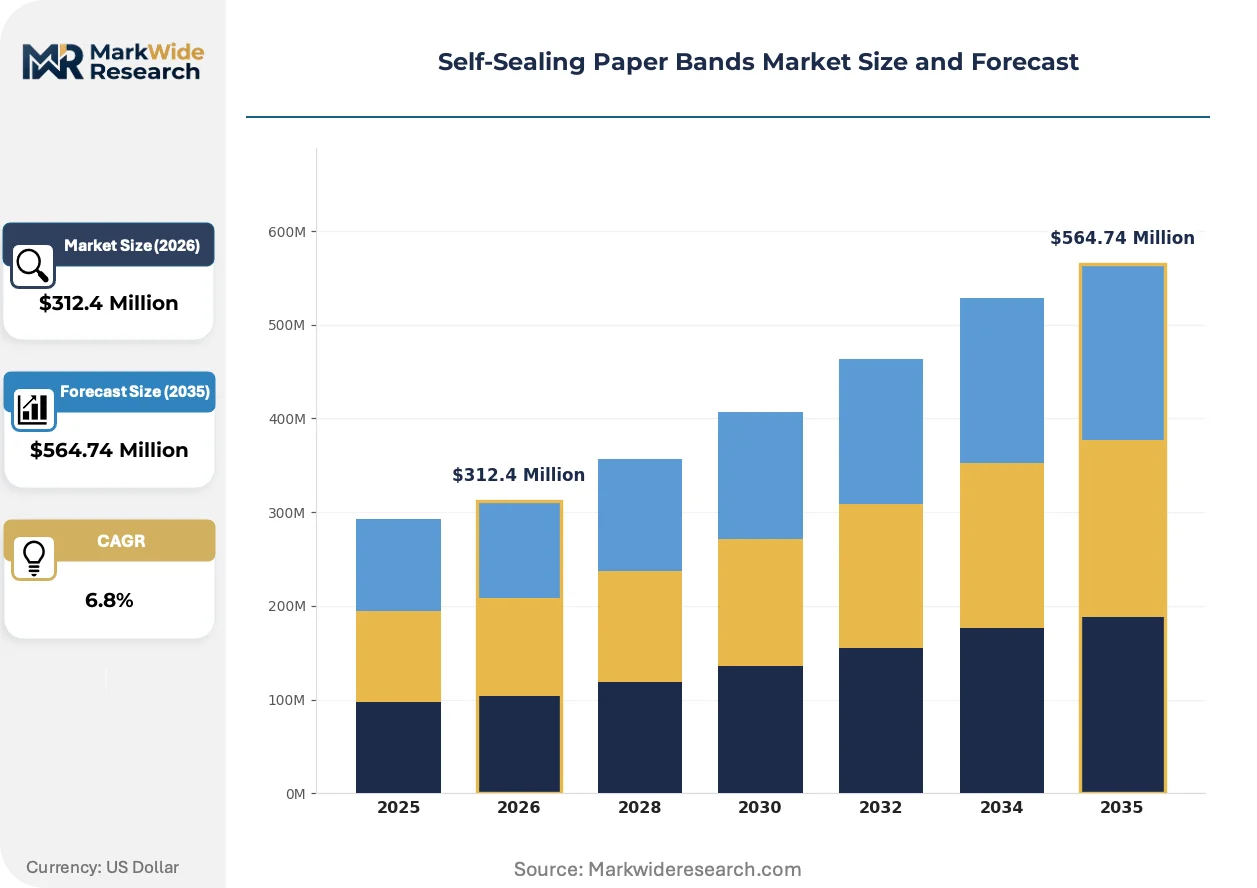
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bands, J-Hook Bands, gusseted Bands, Decorative Bands Application: Packaging, Shipping, Branding, Retail Material: Recycled Paper, Kraft Paper, Coated Paper, Natural Fiber Size: Small, Medium, Large, Custom |
| Companies Covered | Graphic Arts Equipment Co., Brown & Pratt Inc., POPOVA, Extra Packaging Corp., American Printpak Inc., Economy Tablet & Paper Co., Wexler Packaging Products Inc., BGR: Packaging Supplies & Packaging Equipment, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Sealing Paper Bands Market Evolving Landscape
Material science advances and regulatory disclosure requirements are reshaping how self-sealing paper bands are formulated, decorated, and specified across end-use verticals.
Water-based pressure-sensitive adhesives are expanding into high-humidity applications previously reserved for solvent-based systems. Southeast Asian logistics operators in Singapore and Vietnam are piloting these formulations for tropical parcel bundling. The technology is expanding into markets where synthetic adhesive bans are anticipated, compressing the timeline for converter R&D investment.
REACH Annex XVII restrictions on specific phthalate plasticizers are forcing adhesive reformulation across European supply chains. Industrial consequence includes accelerated validation cycles for alternative tackifier systems. Food-adjacent packaging segments in France and the Netherlands are most affected, with buyers now requiring third-party certification of adhesive migration profiles.
Subscription-based equipment maintenance is displacing outright machinery purchases among North American packaging converters. Mid-scale fulfillment operations in Ohio and Pennsylvania prefer bundled service agreements that include band supply and automated line optimization. This pattern is most visible in third-party logistics providers managing multi-tenant distribution centers where capital flexibility outweighs ownership economics.
Self-Sealing Paper Bands Market Segmentation
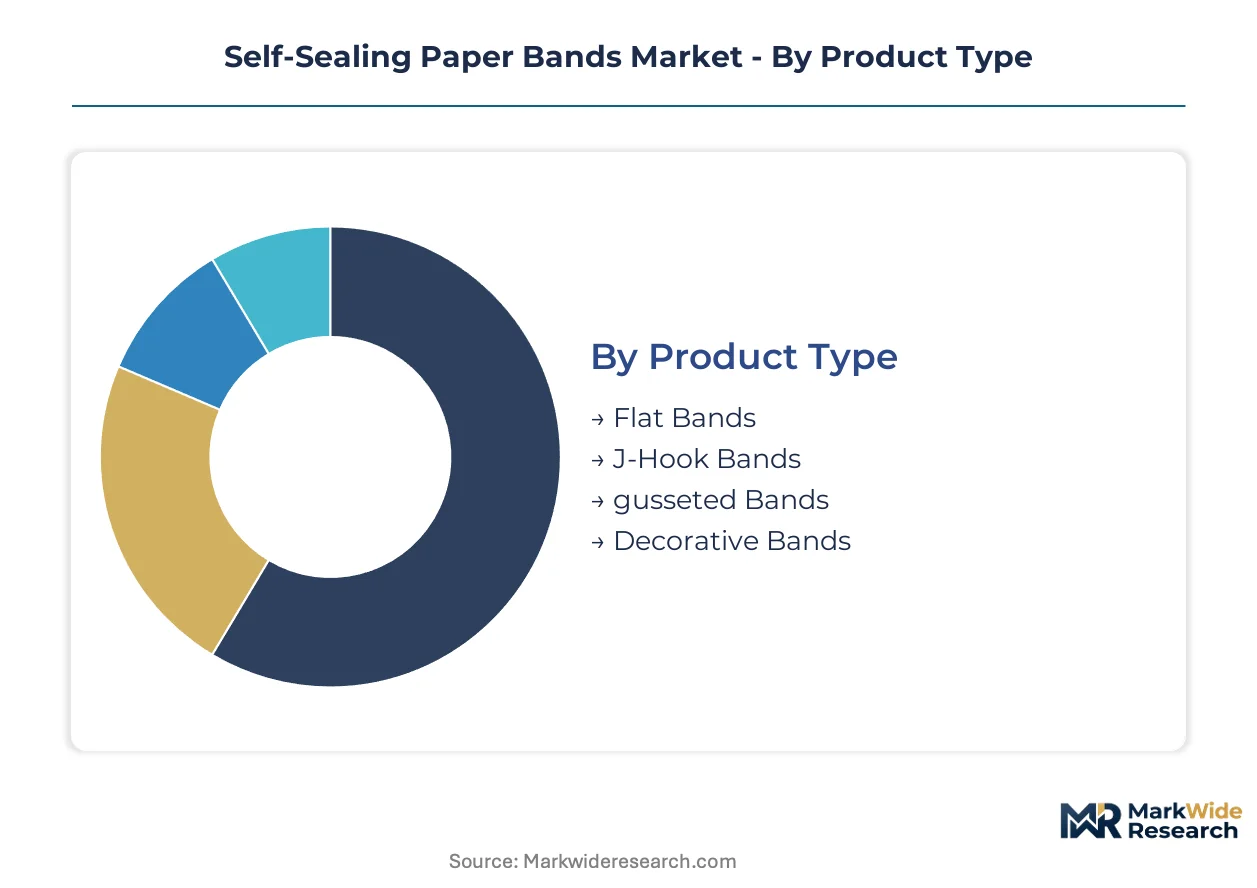
Segmentation in the self-sealing paper bands market determines equipment compatibility, adhesive formulation requirements, and procurement specifications across automated banding lines. Material choices and dimensional standards cascade into regulatory compliance pathways and end-use accessibility.
Product Type:
Integration depth varies sharply — flat bands operate as standalone consumables in high-throughput logistics, while J-hook and gusseted formats embed into specialized retail fixtures and currency handling systems.
- Flat Bands:Pre-gummed strips with uniform width and adhesive coating across the entire surface. German industrial packaging clusters deploy these formats for Central European e-commerce fulfillment centers where automated banding equipment demands consistent tensile properties and pressure-activated sealing without heat application.
- J-Hook Bands:Configured with terminal hooks that interlock around bundled items, eliminating full adhesive contact. Currency handling operations in Frankfurt and Munich specify J-hook variants for banknote strapping where clean release and re-banding cycles reduce processing friction.
- Gusseted Bands:Pleated construction expands to accommodate irregular bundle profiles. Bakery and confectionery applications in France leverage gusseted formats for artisan product presentation where dimensional variability exceeds standard band capacity.
- Decorative Bands:Pre-printed or foil-stamped variants serving premium retail branding requirements. Margin pools concentrate in decorative segments despite lower unit volumes.
Volume placements concentrate in flat bands; the faster expansion belongs to decorative bands as premium retail branding demands intensify.
Application:
Cost tier differentiation separates high-frequency logistics deployments from low-volume, high-margin branding exercises.
- Packaging:Primary bundling function for consumer goods aggregation. FDA indirect food contact regulations govern material selection when bands adjoin edible products, restricting adhesive migration profiles for bakery and prepared meal segments in the United States.
- Shipping:Parcel consolidation in automated distribution centers. Ohio and Pennsylvania third-party logistics providers specify pressure-activated bands that eliminate heat-sealing equipment capital expenditure.
- Branding:Variable-data decoration enables batch-level traceability and promotional customization. Pharmaceutical serialization requirements in the EU create demand for band-integrated QR codes.
- Retail:Point-of-sale presentation for private-label goods. Mumbai and Delhi NCR modern trade formats drive standardization.
Procurement volume clusters in shipping applications; branding segments climb the fastest as traceability mandates expand.
Material:
Supply concentration in Nordic pulp regions and certified adhesive supply chains governs material accessibility and compliance positioning.
- Kraft Paper:Unbleached wood pulp construction delivering tensile strength-to-weight ratios validated by automated banding equipment manufacturers. Equipment validation locks in kraft specifications across installed machinery bases from food processing to currency handling.
- Recycled Paper:Post-consumer fiber content meeting EPA recycled content thresholds in the United States and EU circularity claims. Corporate sustainability procurement mandates accelerate recycled material specification.
- Coated Paper:Surface-treated substrates enabling high-resolution printing for decorative and branding applications.
- Natural Fiber:Alternative cellulose sources including bamboo and agricultural residues for specialized sustainability positioning.
Unit volume concentrates in kraft paper; recycled variants gain share fastest under tightening extended producer responsibility schemes.
Size:
Customer type stratification separates standardized industrial procurement from customized retail and pharmaceutical specifications.
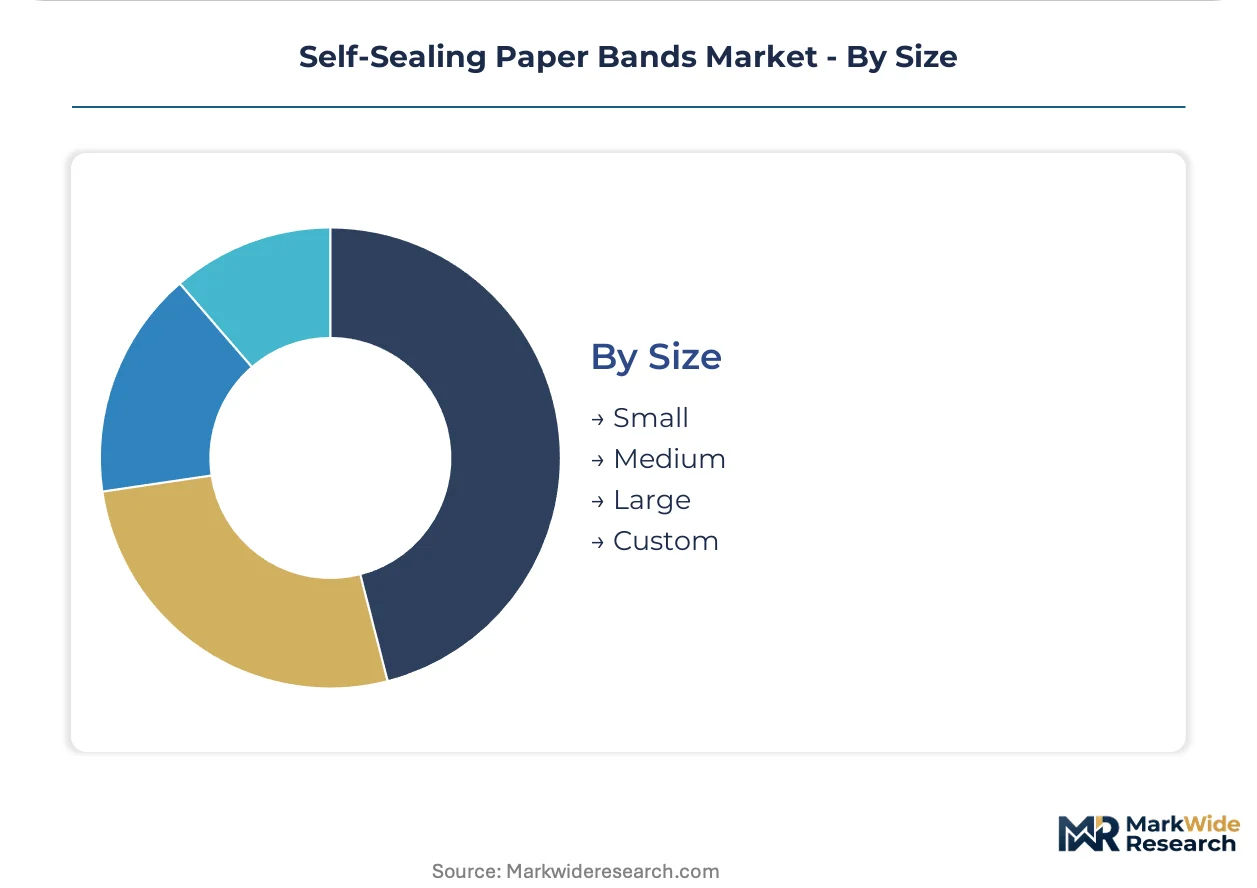
- Medium:30-40mm width range dominating automated banding equipment specifications. Industrial throughput lines in Germany and the United States standardize on medium formats for document and lightweight parcel bundling.
- Custom:Dimensional tailoring for pharmaceutical serialization bands, tamper-evident features, and irregular product profiles. EU pharmaceutical traceability requirements drive specification complexity.
- Small:Narrow formats for currency handling and small-item retail bundling.
- Large:Extended width for heavy-document archival and industrial coil applications where tensile load increases.
Equipment-standard medium sizes capture volume placement; custom formats expand most quickly alongside serialization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian pulp mills supply raw material to converters across multiple continents, while consumption concentrates in e-commerce corridors and industrial packaging clusters. This production-consumption divide shapes trade flows and regional specialization patterns.
Germany
Industrial packaging clusters in the Rhine-Ruhr and Bavaria regions serve Central European distribution networks with high-throughput banding formats. REACH chemical disclosure mandates from ECHA pressure converters to validate adhesive formulations ahead of enforcement deadlines. Frankfurt and Munich currency handling operations specify J-hook band variants for banknote strapping where clean release cycles reduce processing friction.
United States
Third-party logistics providers in Ohio and Pennsylvania prefer subscription-based equipment maintenance bundled with band supply for capital flexibility. EPA recycled content thresholds govern post-consumer fiber specifications for corporate sustainability procurement. Automated fulfillment centers in the Midwest deploy pressure-activated bands to eliminate heat-sealing equipment expenditure.
France
Bakery and confectionery applications in Paris and Lyon drive demand for gusseted formats accommodating artisan product dimensional variability. ANSM and DGCCRF oversight of food-adjacent packaging restricts adhesive migration profiles for bands adjoining edible products. The Île-de-France region hosts converters developing humidity-stable formulations for premium retail presentation.
India
Modern trade formats in Mumbai and Delhi NCR are standardizing packaging for private-label goods, creating demand for medium-width flat bands. BIS certification requirements for paper products shape material specifications for domestic converters. Local producers are piloting monsoon-resistant adhesive formulations to address tropical distribution cycle challenges.
China
Yangtze River Delta manufacturing hubs produce banding equipment for export to Southeast Asian logistics operators. GB standards for packaging materials and MIIT industrial policy guide converter investment in automated production lines. Shanghai-based converters are expanding water-based pressure-sensitive adhesive capacity for anticipated synthetic adhesive restrictions.
Self-Sealing Paper Bands Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the self-sealing paper bands market. Integrated paper converters with captive pulp supply and in-house adhesive compounding occupy differentiated positions against specialized banding equipment manufacturers outsourcing substrate procurement. Three archetypes dominate: Nordic pulp-integrated conglomerates with downstream converting assets, North American regional converters serving industrial corridors, and Asian equipment specialists bundling machinery with consumable supply. M&A activity concentrates on adhesive formulation capabilities, while geographic expansion targets e-commerce fulfillment clusters in emerging markets.
Among North American regional converters, Brown & Pratt Inc. and Wexler Packaging Products Inc. exemplify the industrial corridor service model, while Amcor plc represents the materials science conglomerate archetype extending fiber-based expertise into sealing formats. These three occupy positions spanning the value chain from substrate supply through specialized machinery integration.
| Leading Market Players |
|---|
| Graphic Arts Equipment Co. |
| Brown & Pratt Inc. |
| POPOVA |
| Extra Packaging Corp. |
| American Printpak Inc. |
| Economy Tablet & Paper Co. |
| Wexler Packaging Products Inc. |
| BGR: Packaging Supplies & Packaging Equipment |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between REACH-compliant adhesive formulations and commodity kraft bands splits both pricing power and procurement geography. Premium tiers command sustained margins through validated supply chains serving EU pharmaceutical and food-adjacent segments, while standard grades face cost compression from pulp volatility and buyer consolidation in North American logistics.
Pricing Analysis
Margin tightening in standard kraft grades reflects softwood pulp futures exposure and buyer consolidation among third-party logistics providers. Three-tier pricing structure across premium, standard, and economy levels differentiates by REACH certification status and FDA indirect food contact clearance. Cost-down pressure accelerates in economy tiers as polypropylene strap substitution threatens paper band volumes above fifty-kilogram load thresholds. Third-party logistics providers exhibit highest price sensitivity due to capital-flexibility preferences and subscription-based equipment bundling.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian softwood pulp mills supplying kraft fiber to converters across Germany and the United States. Raw material dependencies center on Nordic bleached kraft pulp, German tackifier resins, and water-based pressure-sensitive adhesive polymers. Supply chain risk concentrates in rosin ester and hydrocarbon resin output from limited chemical suppliers. Distribution runs through industrial packaging clusters in Germany's Rhine-Ruhr region and automated fulfillment corridors in Ohio and Pennsylvania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adhesive formulation chemist scarcity props pricing for converters with in-house compounding capabilities, constraining capacity expansion across mid-tier producers.
For Market Incumbents: Deepen backward integration into Nordic pulp supply agreements to hedge input cost volatility from energy price spikes. Lock in REACH pre-certification cycles ahead of EU Packaging and Packaging Waste Regulation enforcement deadlines. Prioritize adhesive formulation talent retention against tape and label industry poaching. For New Entrants and Emerging Players: Equipment bundling partnerships with Southeast Asian logistics operators offer white-space access where water-based adhesive pilots are expanding. Target India's modern trade formats in Mumbai and Delhi NCR for humidity-stable formulation development. Pursue FDA indirect food contact pathway clearance to unlock bakery and confectionery segments previously served by plastic clips. For Investors and Strategic Acquirers: Re-rating potential sits with adhesive formulation specialists given REACH Annex XVII restriction enforcement accelerating validation demand. Five-to-ten year viability favors converters with captive pulp positions and pre-certified supply chains. Monitor EU extended producer responsibility scheme implementation as inflection indicator for recycled paper grade competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive Formulation Capability Acquisition | REACH compliance timelines compress validation cycles, advantaging pre-certified chemistries. |
| Water-Based Pressure-Sensitive Capacity Buildout | Southeast Asian tropical logistics pilots in Singapore and Vietnam expand addressable market. |
| Subscription Equipment Service Bundling | Ohio and Pennsylvania third-party logistics providers prefer capital-flexible procurement structures. |
| FDA Indirect Food Contact Certification | Bakery and prepared meal segments in the United States shift from plastic clip alternatives. |
| Monsoon-Stable Adhesive Development | India's Mumbai and Delhi NCR modern trade formats require humidity-resistant formulations. |
Research Methodology
Trade publications, customs filings, and SEC 10-K disclosures formed the secondary backbone for input cost and competitive positioning analysis. Primary interviews with packaging converters, adhesive formulation chemists, automated banding equipment manufacturers, and third-party logistics procurement officers validated demand assumptions. Bottom-up segment sizing triangulated against top-down pulp consumption and machinery installation data.
Historical trendline analysis of kraft paper pricing, adhesive resin indices, and e-commerce fulfillment center expansion informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, application vertical, material grade, and geographic regulatory cluster dimensions. CAGRs derived from equipment installation forecasts and pulp supply-demand balances.
Caveats apply where EU Packaging and Packaging Waste Regulation enforcement timing or Nordic pulp mill energy cost spikes could materially shift the outlook. Forecasts reflect assumptions about adhesive formulation substitution rates and polypropylene strap price parity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Fluting Paper Market
Paper & Paperboard Packaging
Middle East and Africa Corrugated Box Market
Paper & Paperboard Packaging
Coffee Filter Paper Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Paper Pleated Cups Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Ultraflute Paper Market