
 Insert Trays Market | 2026-2036
Insert Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Insert Trays Market Foresight
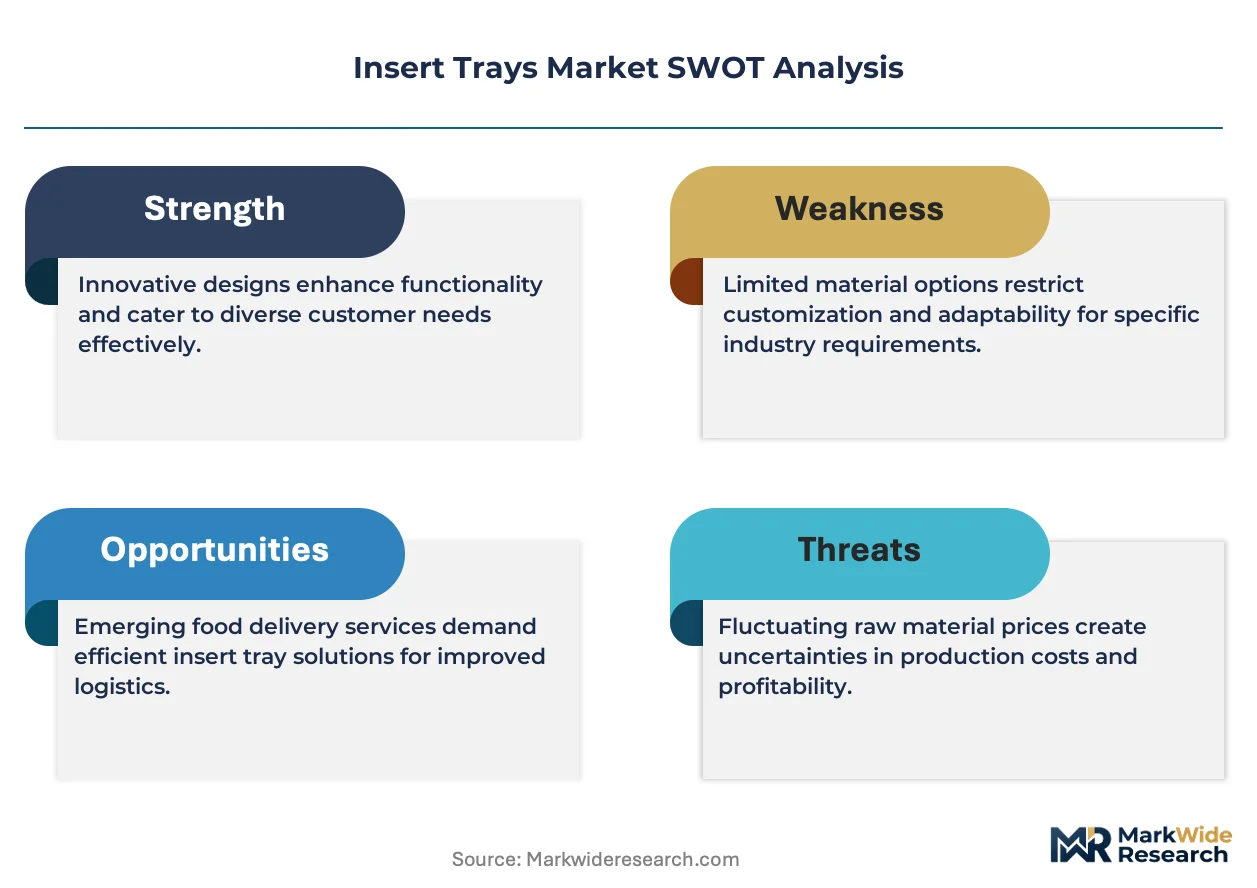
Polyethylene terephthalate is consolidating its position as the preferred substrate over expanded polystyrene in electronics-grade insert trays, driven by recyclability mandates and thinner-gauge performance parity. Sonoco Products Company leverages captive thermoforming capacity across North American plants to secure cost advantages in high-volume medical tray contracts. Amcor Limited anchors its competitive stance through pre-qualified pharmaceutical packaging lines that meet FDA submission requirements. Dordan Manufacturing Company specializes in custom-engineered PET trays with anti-static coatings for semiconductor shipping applications.
Insert trays are thermoformed or injection-molded receptacles engineered to cradle, orient, and protect discrete items during transit, storage, or point-of-sale presentation, typically specified by cavity count, draw ratio, and material gauge measured in mils. The food service application segment leads volume throughput globally, sustained by quick-service restaurant chains and meal-kit fulfillment operators that specify polypropylene for microwave-safe performance. Electronics packaging represents the fastest-expanding application pool, where electrostatic discharge protection and nesting density determine supplier selection. Biodegradable material formulations within the material segment command premium positioning as brand owners pursue packaging reduction commitments, though unit economics remain constrained by limited industrial composting infrastructure.
FDA 21 CFR Part 177 regulations govern indirect food-contact polymers in the United States, while the EU Packaging and Packaging Waste Directive with its Extended Producer Responsibility frameworks shapes material recovery obligations across member states. REACH compliance and RoHS substance restrictions further constrain additive packages and colorant chemistries available to tray converters serving multinational OEMs. Stakeholders must monitor evolving state-level packaging EPR legislation in the United States and pending EU harmonized labeling requirements for recycled content claims.
Market Dynamics
Recyclability mandates are compressing material substitution timelines across electronics and pharmaceutical packaging tiers, forcing converters to requalify substrate portfolios ahead of regulatory deadlines.
Growth Catalysts
- EU Extended Producer Responsibility frameworks:Packaging recovery obligations under the EU Packaging and Packaging Waste Directive are accelerating demand for mono-material PET trays that simplify sortation at material recovery facilities.
- Electrostatic discharge protection requirements:Semiconductor OEMs are specifying anti-static coated trays for wafer shipping, creating specification pull-through in precision manufacturing corridors.
- Biodegradable formulation advances:PLA and PHA blends are achieving thermoforming performance parity with conventional polymers in food service applications where industrial composting infrastructure exists.
Market Restraints
- Industrial composting infrastructure gaps:Limited regional availability of commercial composting facilities constrains end-of-life value realization for biodegradable tray formats.
- Petrochemical feedstock volatility:Crude oil price swings transmit directly to virgin PET and polypropylene resin costs, compressing converter margins on fixed-price contracts.
- RoHS substance restrictions:Additive packages containing legacy flame retardants or heavy metal colorants face phase-out timelines, forcing reformulation investments.
Strategic Opportunities
- Pharmaceutical serialization integration:Pre-qualified packaging lines meeting FDA 21 CFR Part 177 and EMA submission requirements can capture biologics cold-chain tray contracts.
- Meal-kit fulfillment channel expansion:Direct-to-consumer food operators are specifying custom cavity counts and microwave-safe polypropylene for portion-controlled packaging.
- REACH-compliant additive innovation:Bio-based nucleating agents and mineral fillers are opening pathways to reduced-carbon tray specifications for brand owner reduction commitments.
Industry Challenges
- Thermoforming tool steel lead times:Multi-cavity mold fabrication cycles are extending due to precision machining capacity constraints at specialized toolmakers.
- Cross-border material certification complexity:Dual FDA and EMA qualification pathways for pharmaceutical contact materials extend time-to-revenue for new tray specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insert Trays Market |
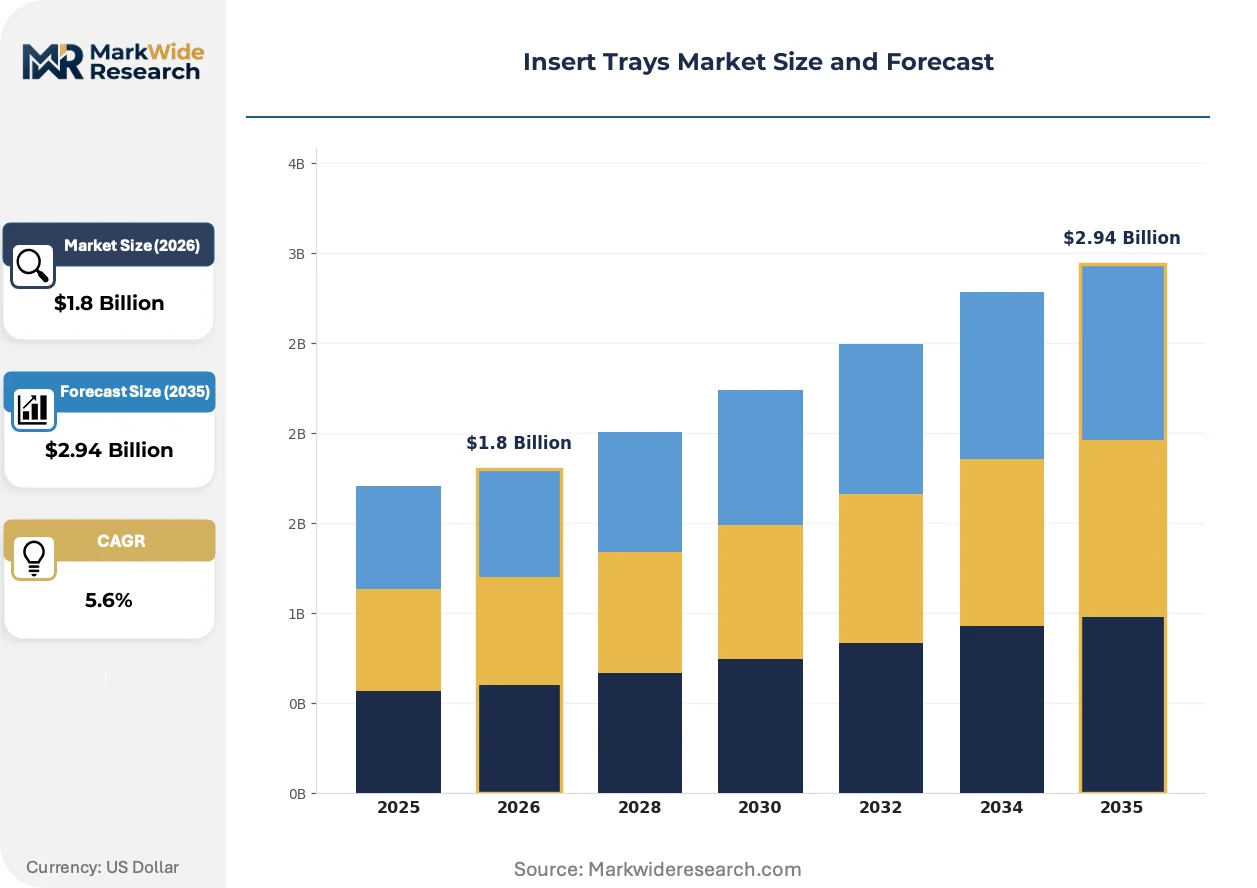
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Trays, Metal Trays, Paper Trays, Foam Trays Application: Food Service, Electronics Packaging, Medical Use, Retail Display Material: Polyethylene, Polypropylene, PVC, Biodegradable Material Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Sonoco Products Company, Amcor Limited, Dordan Manufacturing Company, Engineered Components Packaging, Durphy Packaging Company, UFP Technologies, USK Balaji Plast, Southpack, T.O. Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insert Trays Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are converging to redefine performance specifications and supplier qualification criteria across end-use verticals.
Anti-static PET formulations with carbon nanotube dispersions are absorbing market share in semiconductor shipping applications where electrostatic discharge protection determines supplier selection. Wafer foundries in Taiwan and South Korea are mandating these specifications for inbound component logistics. The technology is absorbing volume previously captured by conductive expanded polystyrene, compressing EPS converter margins in precision electronics packaging.
REACH substance restriction expansions are constraining additive packages available to tray converters serving multinational OEMs. ECHA candidate list updates are phasing out specific plasticizers and stabilizers used in food-contact applications. Pharmaceutical packaging lines serving European markets are responding with accelerated supplier audits and material qualification cycles to maintain compliance continuity.
Consolidated procurement by quick-service restaurant chains is compressing supplier bases and extending contract durations. Operators are specifying multi-year agreements with volume commitments in exchange for dedicated thermoforming capacity. This concentration is most visible in North American food service packaging, where three national chains control a substantial share of polypropylene tray demand.
Insert Trays Market Segmentation
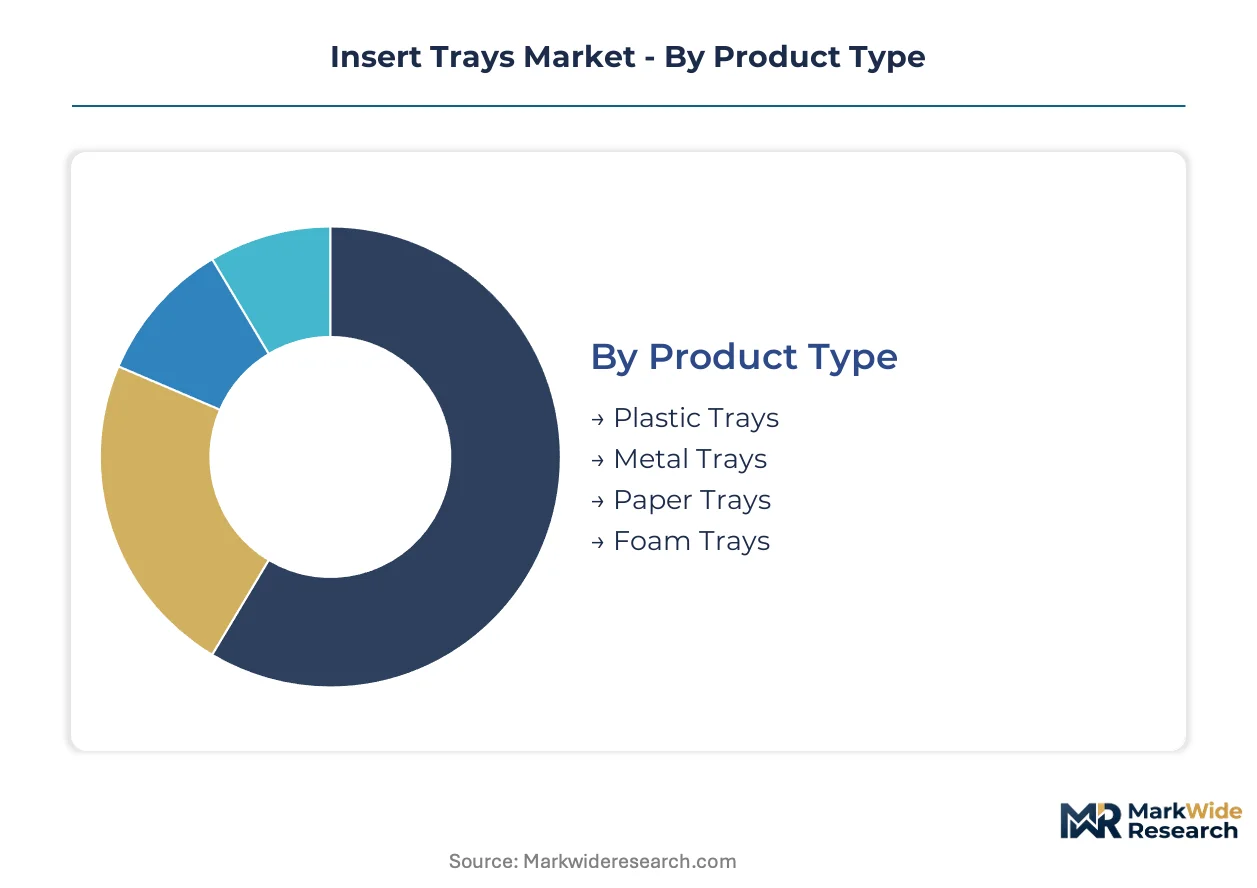
Insert tray specifications diverge sharply across end-use verticals, with cavity geometry, material gauge, and surface conductivity requirements dictating supplier qualification pathways. Each segmentation dimension carries distinct margin structures and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Integration depth varies substantially — plastic and foam formats dominate standalone protective applications, while metal trays embed into automated handling systems requiring magnetic or conductive properties.
- Plastic Trays:Thermoformed PET and polypropylene substrates deliver thin-gauge performance with recyclability compliance under EU Packaging and Packaging Waste Directive frameworks. Quick-service restaurant chains in the United States specify these for microwave-safe meal-kit fulfillment where nesting density reduces shipping cube.
- Metal Trays:Aluminum and stainless steel formats serve pharmaceutical cleanroom applications requiring autoclave sterilization compatibility and dimensional stability across temperature cycling. German precision manufacturers specify these for semiconductor component shipping where electrostatic discharge protection integrates with automated robotic handling systems.
- Paper Trays:Molded fiber substrates from recycled pulp serve single-use food service applications with limited grease resistance requirements.
- Foam Trays:Expanded polystyrene and polyurethane formats retain share in cost-sensitive produce packaging despite compression by recyclable alternatives.
Volume placements concentrate in Plastic Trays; the faster expansion belongs to Metal Trays.
Application:
Application segmentation maps directly to performance specification tiers, with pharmaceutical and electronics verticals commanding premium pricing against commoditized food service throughput.
- Food Service:Polypropylene trays with anti-fog lids dominate quick-service restaurant and meal-kit fulfillment channels where microwave-safe performance and portion-controlled cavity counts determine operator selection. FDA 21 CFR Part 177 compliance is mandatory for all indirect food-contact specifications in United States markets.
- Electronics Packaging:Anti-static PET formulations with carbon nanotube dispacements absorb specification pull-through from Taiwan and South Korea wafer foundries demanding electrostatic discharge protection for inbound component logistics.
- Medical Use:Pre-qualified pharmaceutical packaging lines meeting FDA and EMA submission requirements serve biologics cold-chain applications.
- Retail Display:Visual-grade clarity and print-receptive surfaces drive material selection for point-of-sale presentation formats.
Food Service captures the highest absolute volume; Electronics Packaging is climbing the fastest on semiconductor supply chain localization.
Material:
Material substitution timelines compress as recyclability mandates and biodegradable formulation advances reshape converter substrate portfolios.
- Polyethylene:HDPE and LDPE grades serve deep-draw thermoforming applications requiring chemical resistance and moisture barrier properties. United States converters leverage established resin supply chains for high-volume medical tray contracts.
- Polypropylene:Random copolymer formulations deliver microwave-safe performance with broader temperature tolerance than polyethylene alternatives. REACH-compliant additive packages are accelerating qualification cycles for European pharmaceutical packaging lines.
- PVC:Rigid vinyl retains niche presence in medical blister packaging despite regulatory pressure on plasticizer chemistries.
- Biodegradable Material:PLA and PHA blends achieve thermoforming performance parity where industrial composting infrastructure exists.
Polypropylene anchors current volume; Biodegradable Material is gaining share fastest on brand owner packaging reduction commitments.
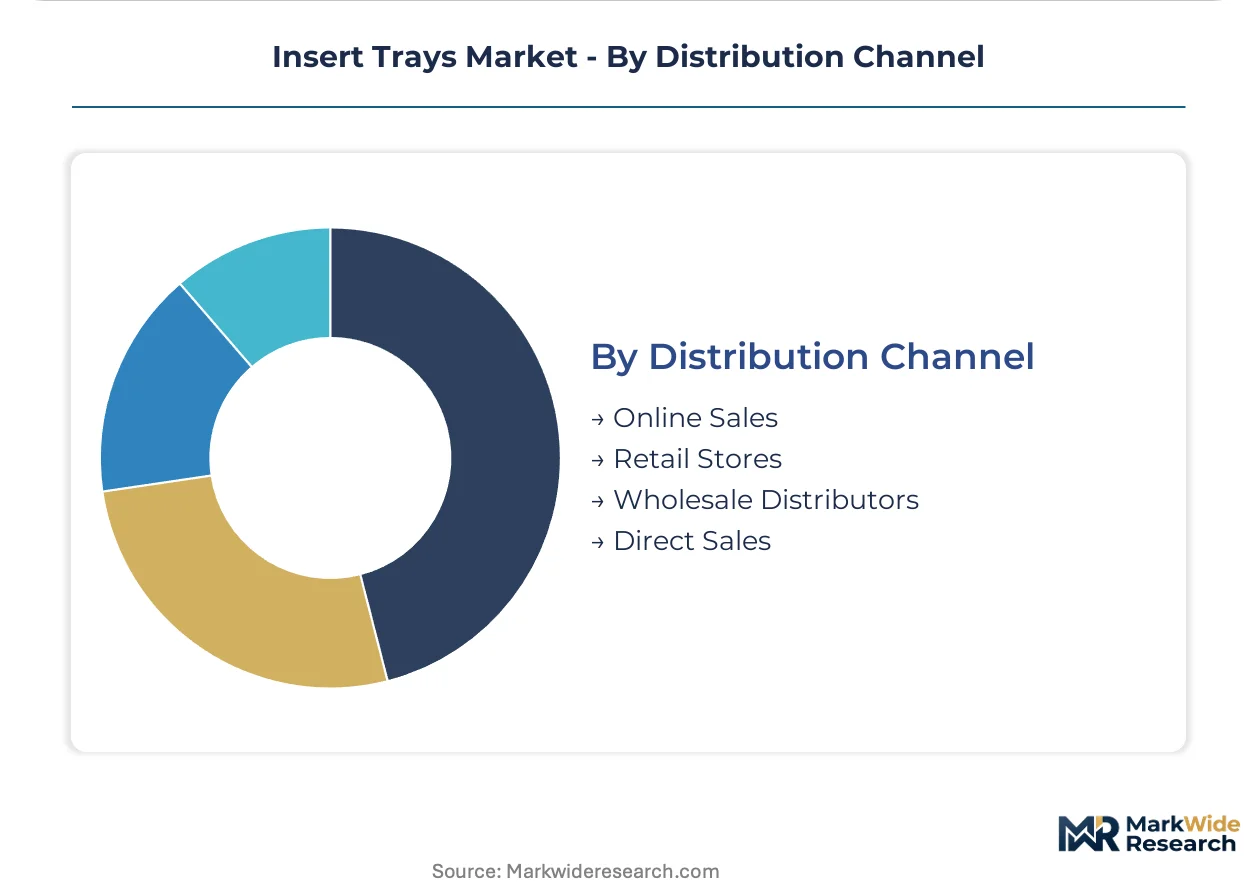
Distribution Channel:
Channel structure reflects customer scale and specification complexity, with direct sales capturing custom-engineered contracts and wholesale distributors serving standardized volume throughput.
- Online Sales:E-commerce platforms aggregate small-lot buyers requiring rapid prototyping and short lead times for custom cavity configurations. United States-based meal-kit startups leverage these channels for initial specification development before migrating to direct contracts.
- Retail Stores:Big-box and specialty packaging suppliers serve walk-up demand for standardized tray formats with immediate availability requirements.
- Wholesale Distributors:Regional inventory positioning supports quick-service restaurant chains with multi-location procurement consolidation.
- Direct Sales:Captive engineering resources and dedicated thermoforming capacity secure multi-year agreements with semiconductor OEMs and pharmaceutical manufacturers.
Wholesale Distributors handle the highest transaction volume; Direct Sales is expanding most quickly on pharmaceutical serialization integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor concentrates demand for semiconductor-grade insert trays, while quick-service restaurant chains in the United States drive food service volume. Regulatory frameworks in the European Union and Asia-Pacific are accelerating material substitution timelines.
United States
Quick-service restaurant chains specify polypropylene trays for microwave-safe meal-kit fulfillment, consolidating procurement through multi-year volume agreements. FDA 21 CFR Part 177 governs indirect food-contact polymers, mandating compliance for all food service specifications. California's Central Valley hosts thermoforming clusters serving agricultural produce packaging with anti-fog lid integration.
Germany
Wafer foundries and precision manufacturers demand anti-static coated PET trays for semiconductor component shipping, creating specification pull-through in the manufacturing corridor. Extended Producer Responsibility frameworks under the EU Packaging and Packaging Waste Directive mandate mono-material sortability. Bavaria's Munich-Stuttgart axis anchors captive thermoforming capacity for pharmaceutical cleanroom applications.
China
Domestic electronics OEMs are localizing semiconductor packaging supply chains, absorbing anti-static tray specifications from Taiwan and South Korea wafer foundries. GB standards and MIIT regulations shape material recovery obligations for packaging converters. The Yangtze River Delta thermoforming cluster serves Shanghai-based biologics cold-chain operators with pre-qualified pharmaceutical lines.
South Korea
Memory chip manufacturers specify carbon nanotube-dispersed PET formulations for wafer shipping, displacing conductive expanded polystyrene in precision logistics. MFDS pharmaceutical packaging regulations align with EMA submission requirements for export-bound biologics. The Seoul Capital Area concentrates tray engineering resources serving Samsung and SK Hynix inbound component networks.
India
Meal-kit startups and quick-service chains are scaling polypropylene tray procurement through e-commerce aggregation channels before migrating to direct contracts. FSSAI food-contact material regulations and BIS standards govern domestic manufacturing compliance. Maharashtra's Pune-Nashik industrial belt hosts emerging thermoforming capacity serving pharmaceutical serialization integration requirements.
Insert Trays Market Competitive Landscape
Capacity expansion dominates the current landscape as converters secure dedicated thermoforming lines for multi-year pharmaceutical and electronics contracts. The vendor base organizes around three strategic archetypes: diversified packaging conglomerates with captive resin supply, mid-scale specialists in custom-engineered formats, and regional fabricators serving standardized food service volume. M&A activity and strategic partnerships concentrate among conglomerates seeking pharmaceutical pre-qualification assets, while technology licensing accelerates anti-static formulation access for mid-tier players.
Within the diversified conglomerate tier, Sonoco Products Company and Amcor Limited exemplify scale-driven positioning through North American captive capacity and pre-qualified pharmaceutical lines respectively. Dordan Manufacturing Company occupies a specialist position, representing custom-engineered PET tray fabrication for semiconductor shipping applications.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Amcor Limited |
| Dordan Manufacturing Company |
| Engineered Components Packaging |
| Durphy Packaging Company |
| UFP Technologies |
| USK Balaji Plast |
| Southpack |
| T.O. Plastics |
| Others |
Supply & Pricing Matrix
Resin feedstock volatility transmits directly through converter pricing tiers, with virgin PET and polypropylene cost swings compressing margins on fixed-price pharmaceutical contracts while spot-market food service buyers absorb pass-through adjustments within quarterly renegotiation windows.
Pricing Analysis
Volume throughput concentrates in commoditized food service polypropylene trays where quick-service restaurant chains extract scale discounts, while premium electronics and pharmaceutical grades capture wider spreads through anti-static certification and FDA pre-qualification requirements. Price differentiation separates pharmaceutical serialization-ready tiers from standard food-contact specifications, with the former commanding substantial premiums for dual FDA-EMA compliance. Cost compression in standard-grade polypropylene intensifies as consolidated procurement by national restaurant operators extends contract durations in exchange for dedicated capacity commitments. Food service buyers exhibit highest price sensitivity due to standardized specifications and multi-source availability, whereas semiconductor OEMs prioritize electrostatic discharge performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and South Korea anchor hub-and-spoke fulfillment patterns for precision electronics and pharmaceutical grades, with inventory positioning tied to wafer foundry and biologics cold-chain proximity. Raw material supply draws from petrochemical complexes in the United States Gulf Coast, Middle Eastern feedstock exporters, and Asian resin producers serving thermoforming clusters. Single-source vulnerability concentrates in specialized anti-static additive formulations where carbon nanotube dispersions rely on limited qualified suppliers. Distribution runs through direct sales channels for custom-engineered contracts, while wholesale distributors handle standardized food service volume with regional inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tool steel machining capacity for multi-cavity thermoforming molds operates at extended lead times, propping pricing power for converters with captive engineering resources and pre-qualified pharmaceutical lines.
For Market Incumbents: Deepen captive thermoforming capacity in Germany's precision manufacturing corridor to defend semiconductor tray specifications against Asian converter expansion. Secure backward integration into anti-static additive compounding to reduce single-source exposure for carbon nanotube dispersions. Extend pharmaceutical pre-qualification assets through accelerated FDA submission support for biologics cold-chain customers. For New Entrants and Emerging Players: Enter via biodegradable PLA-PHA blend formulations for European food service applications where industrial composting infrastructure supports premium positioning against virgin polypropylene. Target India's meal-kit fulfillment channel through e-commerce aggregation platforms before scaling to direct contracts with quick-service chains. Lead with microwave-safe performance parity and REACH-compliant additive packages to bypass incumbent qualification barriers. For Investors and Strategic Acquirers: Extended thermoforming tool steel lead times are the leading indicator that mold fabrication capacity constraints will persist, favoring converters with established toolmaker relationships and in-house engineering resources. Over the medium-term horizon, acquisition targets should display pharmaceutical serialization integration capabilities and captive capacity in Taiwan-South Korea semiconductor supply corridors. Watch for anti-static PET formulation licensing agreements as signals of technology access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Thermoforming Capacity Expansion | Secures multi-year pharmaceutical contracts against tool steel lead time constraints. |
| Anti-Static Additive Backward Integration | Reduces single-source vulnerability for carbon nanotube dispersions in semiconductor grades. |
| Biodegradable Formulation Licensing | Accelerates PLA-PHA blend access for European EPR compliance positioning. |
| Pharmaceutical Serialization Integration | Captures biologics cold-chain demand through FDA-EMA dual qualification pathways. |
| Regional Distribution Hub Establishment | Positions inventory adjacent to German wafer foundries and South Korean memory chip manufacturers. |
Research Methodology
Multi-period observation of resin price indices, thermoforming capacity utilization rates, and pharmaceutical packaging qualification timelines anchored the trend analysis, supplemented by interviews with thermoforming plant managers, procurement leads at semiconductor OEMs, quick-service restaurant supply chain directors, and pharmaceutical packaging engineers. Secondary validation drew from FDA 21 CFR Part 177 filings, EMA submission databases, EU Packaging and Packaging Waste Directive implementation reports, and SEC disclosures by diversified packaging conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting approaches modeled product type, application vertical, material substrate, and distribution channel dimensions, with electronics packaging and pharmaceutical grades receiving higher weighting coefficients due to specification complexity and margin structures. CAGRs were derived through regression analysis of historical volume trends and forward projection of regulatory compliance timelines, feedstock cost assumptions, and end-use demand elasticity. Forecast inputs incorporated wafer foundry localization patterns, quick-service restaurant chain expansion plans, and biodegradable material composting infrastructure development curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock price shocks, accelerated EU packaging EPR implementation, or semiconductor demand cyclicality. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Modular Container Market
Containers
APAC Container Technology Market
Containers
Wet Wipes Canister Market
Containers
HDPE Crates Market
Containers
Bulk Containers Market
Containers
Dispensing Jug Market
Containers
In-Mold Labelled Containers Market
Containers
PET Containers Market
Containers
Foam Containers Market
Containers
Hinged Lid Tins Market
Containers
Lever Lid Tinplate Containers Market
Containers
Tin Containers Market
Containers
Injection Molding Containers Market
Containers
Thermoformed Containers Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Roll Containers Market