
 Japan Paper Packaging Market | 2026-2036
Japan Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Paper Packaging Market Foresight
Asset-light leasing arrangements for converting equipment is narrowing the capital barrier for mid-tier entrants in Japan's paper packaging sector. Rengo Co., Ltd. leverages its integrated pulp-to-box operations across western Japan to sustain cost advantages in corrugated production. Oji Holdings Corporation anchors national supply through extensive forestry holdings and coastal mill networks. Toppan Inc. differentiates via high-value printed folding cartons serving cosmetics and premium food brands.
Japan Paper Packaging encompasses engineered paperboard structures—typically 150–400 gsm kraft linerboard, fluted corrugated medium, or clay-coated folding boxboard—fabricated through die-cutting, flexographic printing, and hot-melt gluing for product containment, protection, and shelf presentation. Corrugated box formats dominate industrial and e-commerce flows, while folding box applications command premium margins in personal care and electronics end uses. Kraft paper grades see expanding demand in food service and retail carryout segments as operators abandon plastic alternatives.
METI's Green Growth Strategy, the Container Packaging Recycling Act, and JIS standards for recycled content collectively mandate higher fiber recovery rates and restrict non-recyclable laminates in domestic packaging. PMDA guidelines for pharmaceutical and food-contact materials further constrain barrier coating chemistries, pushing converters toward mineral-oil-free and water-based formulations. Stakeholders must track evolving extended producer responsibility fee structures and assess whether domestic mill capacity can absorb substitution-driven volume shifts without importing dependency.
Market Dynamics
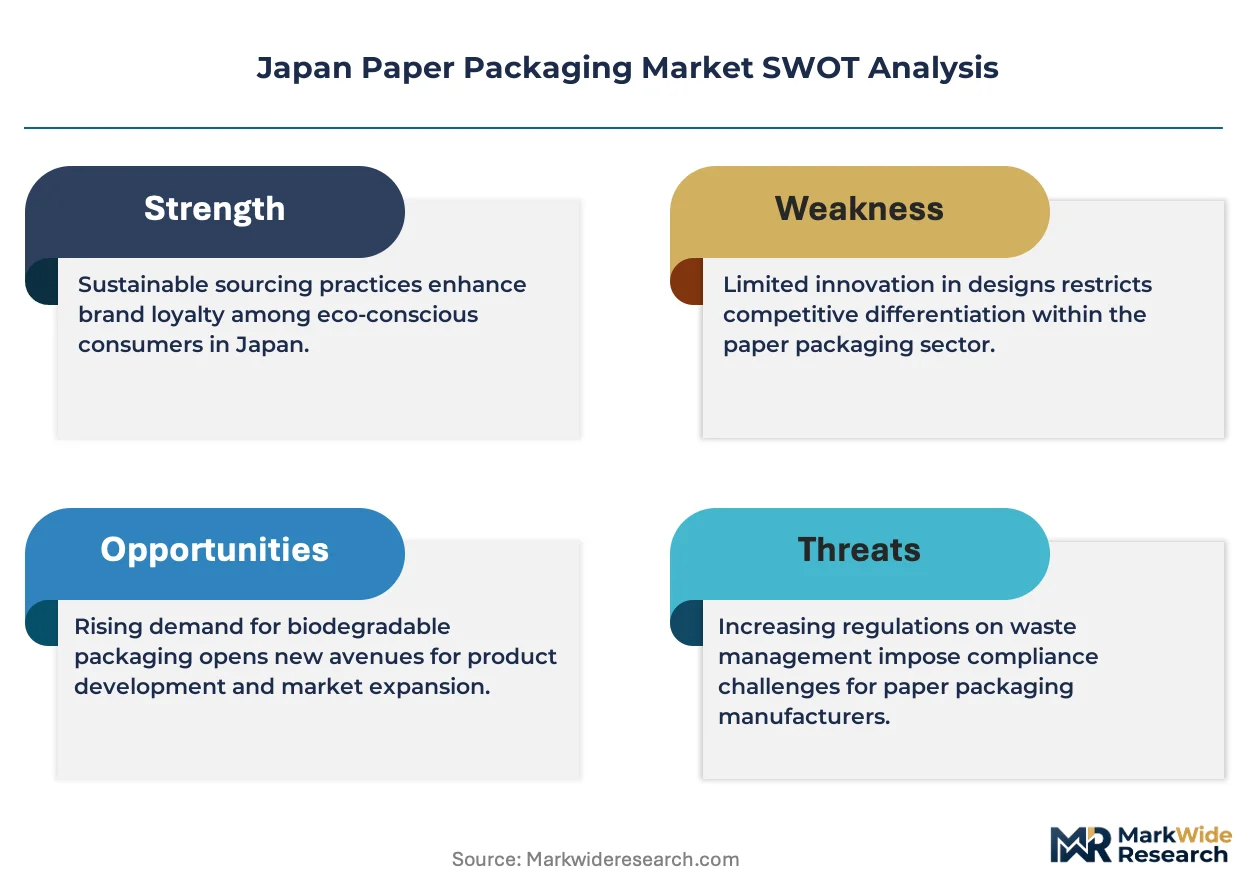
METI's resource circulation mandates and the Plastic Resource Circulation Act are forcing converters to retool lines for fiber-based barrier coatings, compressing lead times for compliant formats while elevating capital requirements across Japan's mill network.
Growth Catalysts
- E-commerce logistics corridors:Parcel volumes through Tokyo-Osaka distribution nodes sustain demand for B-flute and E-flute corrugated formats optimized for automated sortation.
- Container Packaging Recycling Act compliance:Brand owners face mandatory recycled-content thresholds, pulling fiber-based alternatives into food service and retail carryout segments.
- Kraft paper substitution:Food operators in Kanto and Kansai metropolitan zones are abandoning polyethylene-lined containers for uncoated and clay-coated kraft grades.
Market Restraints
- Pulp cost volatility:Softwood kraft pulp prices fluctuate with Canadian and Scandinavian supply disruptions, compressing converter margins on fixed-price annual contracts.
- Coastal mill concentration:Over half of Japan's containerboard capacity sits within 50 kilometers of Pacific ports, exposing logistics networks to seismic and typhoon disruption.
- Barrier performance gaps:Fiber-based grease and moisture barriers underperform against multilayer plastic laminates in extended-shelf-life food applications.
Strategic Opportunities
- Kyushu industrial corridor:Semiconductor and automotive component manufacturing in Fukuoka and Kumamoto generates underpenetrated demand for precision die-cut corrugated and anti-static folding cartons.
- Pharmaceutical serialization:PMDA track-and-trace mandates create white space for printed folding cartons with integrated RFID and tamper-evident features.
- Hot-melt adhesive formulation:Converters adopting bio-based ethylene vinyl acetate compounds access METI Green Innovation Fund subsidies while meeting JIS biodegradability standards.
Industry Challenges
- Flexographic prepress talent scarcity:Japan's aging converter workforce lacks operators trained in HD platemaking and expanded gamut color management.
- Die-board precision calibration:Tighter tolerances for electronics and cosmetics packaging require capital investment in laser-cutting and CNC routing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Paper Packaging Market |
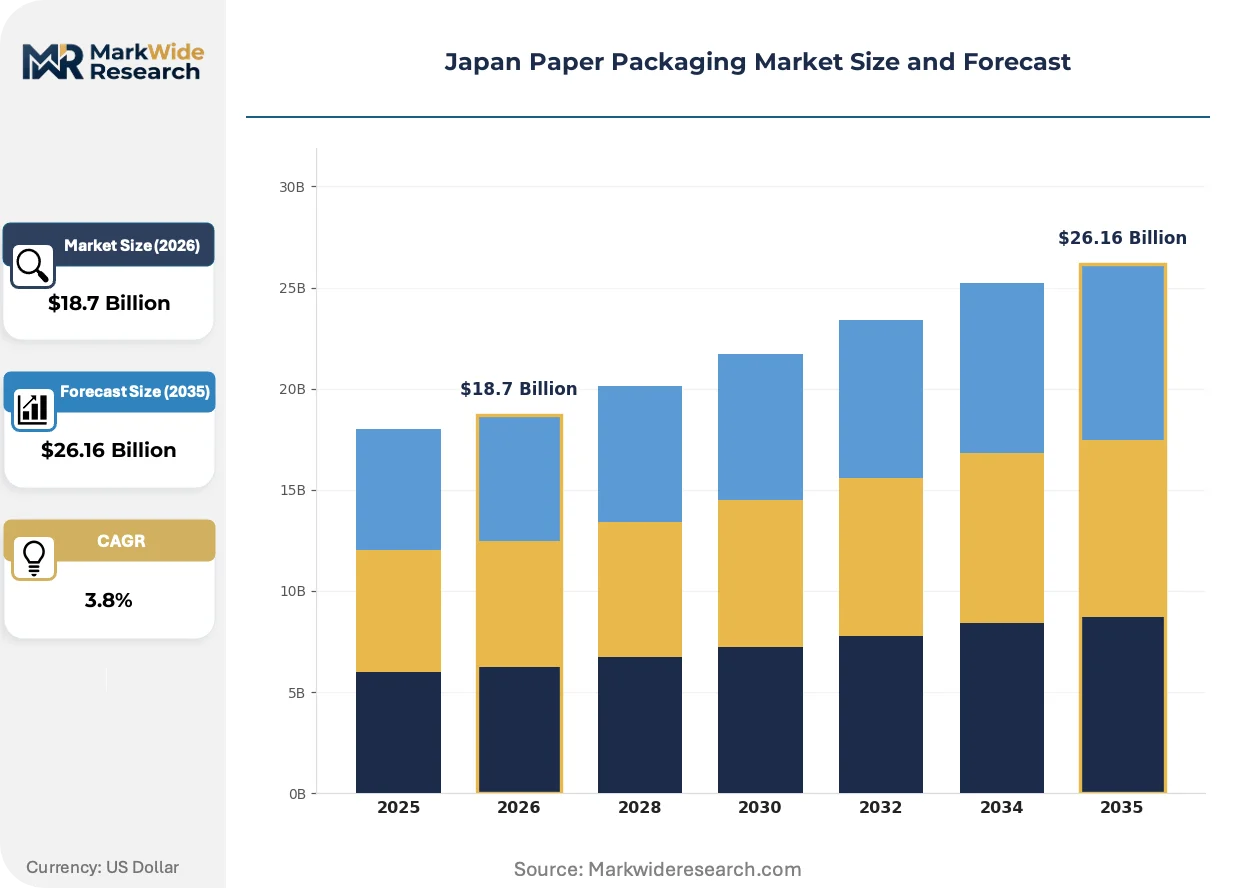
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Box, Folding Box, Paper Bag, Wrap End User: Food & Beverage, Personal Care, Electronics, Household Goods Material: Recycled Paper, Kraft Paper, Coated Paper, Specialty Paper Application: Retail Packaging, Industrial Packaging, Shipping Packaging, Storage |
| Companies Covered | Nippon Paper Industries Co., Ltd., Rengo Co., Ltd., Oji Holdings Corporation, Daio Paper Corporation, Toyoo Seikan Group Holdings, Ltd., Hokuetsu Corporation, Mitsubishi Paper Mills Limited, Toppan Inc., FP Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Paper Packaging Market Shifts & Advancements
Digital workflow integration and barrier coating chemistry advances are compressing product development cycles while METI enforcement tightens material compliance requirements across Japan's packaging value chain.
Inline spectrophotometry and closed-loop color control systems are digitizing quality assurance on corrugated and folding carton lines. Mid-tier converters in Aichi and Shizuoka prefectures deploy these systems to reduce make-ready waste and match brand color standards across multiple press platforms. Real-time density monitoring is digitizing the relationship between prepress departments and production floors, collapsing approval cycles from days to hours.
METI's Green Growth Strategy enforcement through fiscal 2025 tightens reporting on Scope 3 emissions from imported pulp and coating chemistries. Converters must document supply chain carbon intensity to retain preferred supplier status with multinational brand owners. Pharmaceutical and food-contact packaging segments face the steepest compliance burdens as PMDA aligns with EU REACH restrictions on mineral oil saturated hydrocarbons.
Consolidated procurement by e-commerce platform operators and nationwide convenience store chains concentrates volume with converters offering national fulfillment networks. Smaller regional players lose access to high-volume corrugated contracts as buyers consolidate supplier panels to three or fewer approved vendors. This concentration is most visible in Kanto, where Rakuten and Seven-Eleven Japan procurement teams negotiate multi-year supply agreements with integrated mill-to-box operators.
Japan Paper Packaging Market Segmentation
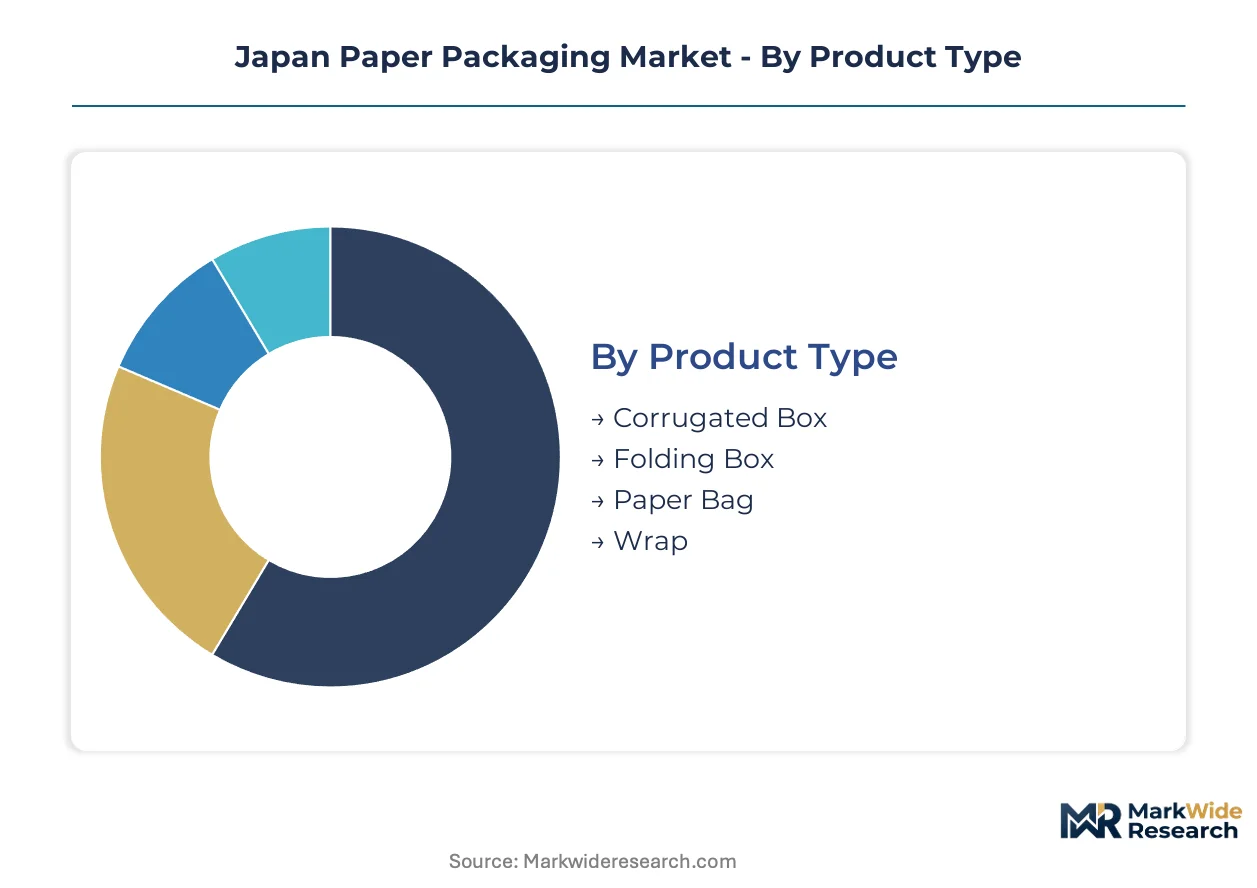
Segmentation in Japan's paper packaging sector reveals how regulatory pressure and e-commerce logistics reshape product mix across material grades and end-use applications. Understanding these divides exposes where capital flows and where margin compression threatens converter viability.
Product Type:
Mature formats dominate volume, while emerging structures capture substitution-driven expansion.
- Corrugated Box:Engineered from 150–400 gsm kraft linerboard with B-flute or E-flute profiles for automated sortation. Tokyo-Osaka logistics corridors sustain demand from Rakuten and Seven-Eleven Japan procurement consolidation. METI's recycled-content mandates force mills to certify post-consumer fiber ratios.
- Folding Box:Clay-coated folding boxboard structures for cosmetics and electronics shelf presentation. Premium personal care brands in Kanto demand high-fidelity flexographic reproduction and tamper-evident closures. Toppan Inc. anchors supply for this precision segment.
- Paper Bag:Uncoated and clay-coated kraft grades for food service carryout. Kanto metropolitan operators abandon polyethylene-lined containers under Plastic Resource Circulation Act pressure.
- Wrap:Lightweight kraft and tissue structures for protective cushioning and retail gift applications. Department store chains in Osaka and Nagoya drive seasonal volume spikes.
Corrugated box formats handle the majority of throughput; folding box applications are gaining share fastest on premium brand demand.
End User:
Customer concentration varies sharply by compliance burden and volume scale.
- Food & Beverage:The largest demand pool, spanning ready-meal containers, beverage carriers, and fresh produce trays. PMDA food-contact regulations constrain barrier coating chemistries toward mineral-oil-free formulations. Convenience store chains consolidate procurement with three or fewer approved corrugated suppliers.
- Electronics:Precision die-cut corrugated and anti-static folding cartons for semiconductor and automotive component shipment. Kyushu's Fukuoka-Kumamoto corridor generates underpenetrated demand as manufacturing capacity expands.
- Personal Care:High-value printed folding cartons serving cosmetics and premium skincare brands. Color consistency requirements drive adoption of inline spectrophotometry on production lines.
- Household Goods:Standard-grade corrugated for detergent, cleaning supplies, and home appliance containment. Price-sensitive procurement favors integrated mill-to-box operators with captive linerboard supply.
Food & beverage commands the volume base; electronics packaging is expanding most quickly on semiconductor reshoring.
Material:
Cost tiers separate commodity recovery grades from performance-engineered substrates.
- Recycled Paper:Post-consumer containerboard and deinked pulp grades meeting JIS recycled-content thresholds. Mandatory reporting under Container Packaging Recycling Act elevates traceability requirements across supply chains.
- Kraft Paper:Virgin and semi-bleached softwood kraft for uncoated food service and industrial wrap applications. Canadian and Scandinavian pulp price volatility compresses converter margins on annual contracts.
- Coated Paper:Clay-coated and pigment-coated grades for high-resolution printing on folding cartons. Barrier performance gaps against multilayer plastic laminates constrain extended-shelf-life food adoption.
- Specialty Paper:Grease-resistant, moisture-barrier, and anti-static engineered substrates. METI Green Innovation Fund subsidies accelerate bio-based ethylene vinyl acetate adhesive integration.
Recycled paper carries the volume load; specialty paper is climbing the fastest on barrier substitution requirements.
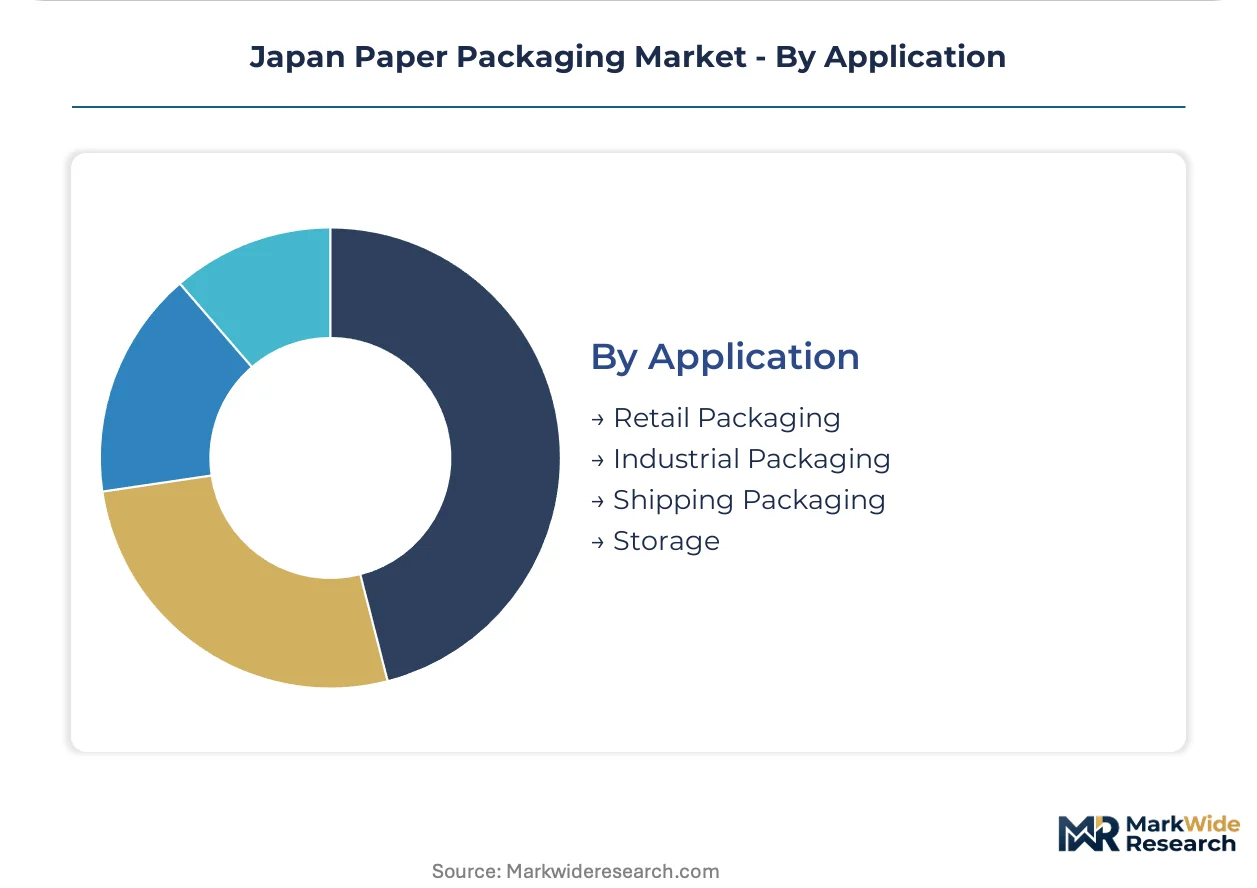
Application:
Distribution intensity separates high-frequency retail formats from capital-heavy industrial specifications.
- Shipping Packaging:Corrugated containers optimized for parcel sortation automation across e-commerce logistics networks. B-flute and E-flute profiles dominate Tokyo-Osaka distribution node throughput.
- Retail Packaging:Shelf-ready folding cartons and branded paper bags for consumer-facing presentation. Cosmetics and premium food brands in Kanto demand shortest lead times for promotional variant launches.
- Industrial Packaging:Heavy-duty triple-wall corrugated and protective wrap for machinery and automotive component export. Coastal mill concentration within 50 kilometers of Pacific ports sustains just-in-time delivery.
- Storage:Archive-grade corrugated and acid-free tissue for document preservation and long-term warehousing. Financial institutions and government agencies in Tokyo sustain steady demand.
Shipping packaging handles the majority of throughput; retail packaging is gaining share fastest on brand owner sustainability commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major e-commerce platforms and nationwide convenience chains concentrate procurement power with converters offering integrated mill-to-box networks across Japan's key industrial corridors.
Kanto/Tokyo
Tokyo's dense consumer base and port infrastructure sustain the highest per-capita consumption of retail and industrial paper packaging formats. METI's resource circulation policies enforce recycled-content thresholds on converters supplying the metropolitan area. Automated sortation hubs in Saitama and Chiba prefectures pull B-flute and E-flute corrugated volumes from integrated producers.
Kansai/Osaka
Osaka's historical manufacturing base generates steady demand for industrial packaging and export-oriented corrugated formats. The Container Packaging Recycling Act mandates traceable post-consumer fiber ratios for converters serving the region. Precision die-cut operations in Hyogo prefecture supply semiconductor and automotive component manufacturers.
Chubu/Nagoya
Nagoya's automotive and aerospace clusters generate specialized demand for protective packaging and precision-engineered corrugated structures. PMDA guidelines constrain barrier coating chemistries for food-contact materials produced in Aichi prefecture. Inline spectrophotometry adoption is highest here among mid-tier converters seeking brand color consistency.
Kyushu
Fukuoka and Kumamoto's expanding semiconductor fabrication capacity creates underpenetrated demand for anti-static folding cartons and precision die-cut formats. The Plastic Resource Circulation Act accelerates kraft paper substitution in food service carryout across metropolitan zones. Local converters face capital barriers to matching barrier performance of multilayer plastic laminates.
Hokkaido
Hokkaido's agricultural processing and seafood export industries pull specialized moisture-barrier corrugated and insulated shipping formats. Coastal mill concentration within 50 kilometers of Pacific ports exposes logistics networks to seismic disruption. Regional converters serve niche cold-chain applications with limited national procurement integration.
Japan Paper Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure consolidates around integrated pulp-to-box operators with captive linerboard supply and national fulfillment networks. Three archetypes dominate: forestry-backed integrated mills, precision converting specialists, and regional corrugated fabricators. Competitive moves center on multi-year procurement consolidation by e-commerce platforms and convenience chains, alongside METI subsidy-driven barrier coating chemistry transitions.
Among forestry-anchored integrated operators, Oji Holdings Corporation, Rengo Co., Ltd., and Nippon Paper Industries Co., Ltd. occupy positions defined by upstream pulp access and coastal mill networks. Toppan Inc. exemplifies the precision-converting archetype through high-value printed folding carton capabilities. Daio Paper Corporation and Hokuetsu Corporation represent mid-scale integrated producers with regional density in western and northern Japan respectively. These named entities serve as structural anchors for understanding how recycled-content mandates and e-commerce procurement consolidation reshape competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Nippon Paper Industries Co., Ltd. |
| Rengo Co., Ltd. |
| Oji Holdings Corporation |
| Daio Paper Corporation |
| Toyoo Seikan Group Holdings, Ltd. |
| Hokuetsu Corporation |
| Mitsubishi Paper Mills Limited |
| Toppan Inc. |
| FP Corporation |
| Others |
Supply & Pricing Matrix
Canadian and Scandinavian softwood kraft pulp concentration anchors margin distribution across Japan's converter tier, with coastal mill operators capturing value pools that inland fabricators cannot access. METI's recycled-content mandates force certification premiums that separate integrated producers from merchant buyers dependent on spot linerboard markets.
Pricing Analysis
Certification level under JIS recycled-content standards creates the primary spread between integrated mill-to-box operators and merchant converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier coating complexity and food-contact compliance. Price erosion runs through standard-grade corrugated as Rakuten and Seven-Eleven Japan procurement teams consolidate annual contracts with three approved vendors. Household goods buyers exhibit highest price sensitivity; cosmetics and pharmaceutical brand owners absorb premium tiers for color consistency and serialization features.
Supply Chain Analysis
Seismic exposure along Japan's Pacific coastal mill belt dominates supply chain risk assessment for containerboard networks. Domestic pulp production draws from Hokkaido and Kyushu forestry holdings, while specialty coating chemistries rest on imports from Germany and South Korea. Single-source vulnerability concentrates in B-flute and E-flute corrugating adhesives where bio-based ethylene vinyl acetate alternatives remain limited. Distribution runs through Tokyo-Osaka logistics corridors with just-in-time delivery to automated sortation hubs in Saitama and Chiba prefectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce platform procurement consolidation has transformed Japan's paper packaging sector into a two-sided network economy where converter scale determines access to high-volume contracts. Interoperability between METI compliance databases and brand owner sustainability scorecards now governs supplier selection.
For Market Incumbents: Build captive linerboard supply moats through backward integration into Hokkaido and Kyushu pulp assets. Oji Holdings Corporation and Rengo Co., Ltd. anchor positions demonstrate how coastal mill networks defend against merchant price volatility. Expand precision converting capacity in Aichi prefecture to capture pharmaceutical serialization demand from PMDA track-and-trace mandates. Channel control through multi-year agreements with Rakuten and Seven-Eleven Japan procurement teams locks out regional competitors. For New Entrants and Emerging Players: Pursue white-space penetration in Kyushu's Fukuoka-Kumamoto semiconductor corridor where anti-static folding carton demand outstrips local supply. Asset-light leasing arrangements for laser die-cutting equipment lower capital barriers for precision electronics packaging. Target food service kraft paper substitution in metropolitan Kanto zones under Plastic Resource Circulation Act pressure. Partner with regional convenience store chains excluded from national procurement panels to build volume credentials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale integrated producers in western and northern Japan lacking national fulfillment networks. Five-to-ten year viability hinges on METI Green Innovation Fund access for barrier coating chemistry transitions. Acquisition targets include precision converters with installed inline spectrophotometry serving cosmetics brands. Watch for inflection when e-commerce parcel volumes through Tokyo-Osaka nodes accelerate corrugated capacity utilization beyond threshold levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Hokkaido and Kyushu forestry holdings secure linerboard cost advantages against Canadian price volatility. |
| Barrier Coating Chemistry Transition | Bio-based ethylene vinyl acetate formulations unlock METI Green Innovation Fund subsidies and JIS biodegradability compliance. |
| Precision Converting Capacity Expansion | Laser die-cutting and CNC routing equipment in Aichi prefecture serves PMDA pharmaceutical serialization mandates. |
| Multi-Year Procurement Consolidation | Exclusive supply agreements with Rakuten and Seven-Eleven Japan lock out regional competitors from high-volume corrugated contracts. |
| Digital Workflow Integration | Inline spectrophotometry adoption collapses color approval cycles for cosmetics brand owners demanding shortest lead times. |
Research Methodology
The analysis maps corrugated box, folding carton, kraft paper, and specialty barrier substrate segments, each validated through mill operations directors, converter procurement leads, brand owner sustainability officers, and logistics platform supply chain managers. Primary interviews across 15 stakeholder roles combined with secondary triangulation against METI policy filings, JIS standard documentation, Container Packaging Recycling Act compliance reports, and customs trade data for pulp and coating chemistry imports. Bottom-up volume modeling from individual mill capacity and top-down demand estimation from e-commerce parcel flow data were reconciled across the analysis window.
Assumption sets held METI enforcement timelines and Plastic Resource Circulation Act substitution rates as fixed parameters while varying pulp price volatility scenarios and seismic disruption probabilities. Segmentation dimensions modeled include product format, end-use industry, material grade tier, and regional production hub clustering. CAGRs were derived from installed capacity utilization trends and substitution-driven volume shift elasticities. Forecast inputs incorporated PMDA track-and-trace mandate implementation pacing and semiconductor reshoring projections for Kyushu industrial corridors.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese containerboard exporters or accelerated bio-based adhesive breakthroughs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Global Solid Board Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Coated Paper Market
Paper & Paperboard Packaging
Egypt Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Cup Lids Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Paper Canisters Market
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Tracing Paper Market