
 Malaysia Corrugated Boxes Market | 2026-2036
Malaysia Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Corrugated Boxes Market Outlook
Multi-source procurement among fast-moving consumer goods distributors is consolidating into preferred-supplier arrangements with integrated paperboard mills. Century Bond Group leverages captive linerboard output to lock in margin visibility across the Klang Valley. Box-Pak (Malaysia) Bhd anchors its position through high-volume flat-pack contracts with multinational electronics assemblers. Oji Holdings Corporation differentiates via Japanese-standard quality protocols that command premium placement in pharmaceutical cold-chain applications.
Corrugated boxes are paper-based containers built from alternating flat linerboard sheets and arched fluting, typically bonded with starch adhesives and engineered to precise edge crush test specifications for stacking strength. They protect goods through distribution while enabling brand communication via flexographic or lithographic surface printing. Single-wall and double-wall configurations dominate volume, though triple-wall demand accelerates in heavy machinery exports where load-bearing thresholds justify material premiums. Recycled material feeds are expanding fastest as brand owners impose post-consumer waste minimums on packaging procurement.
Malaysia's Department of Environment enforces industrial effluent standards under the Environmental Quality Act, pressuring mills to adopt closed-loop water systems or face operational suspensions. BIS-equivalent MS standards for packaging safety, coupled with SIRIM certification requirements, filter substandard imports from regional competitors. Stakeholders must monitor how Putrajaya's plastics substitution mandates redirect food and beverage sector purchasing toward fiber-based alternatives.
Market Dynamics
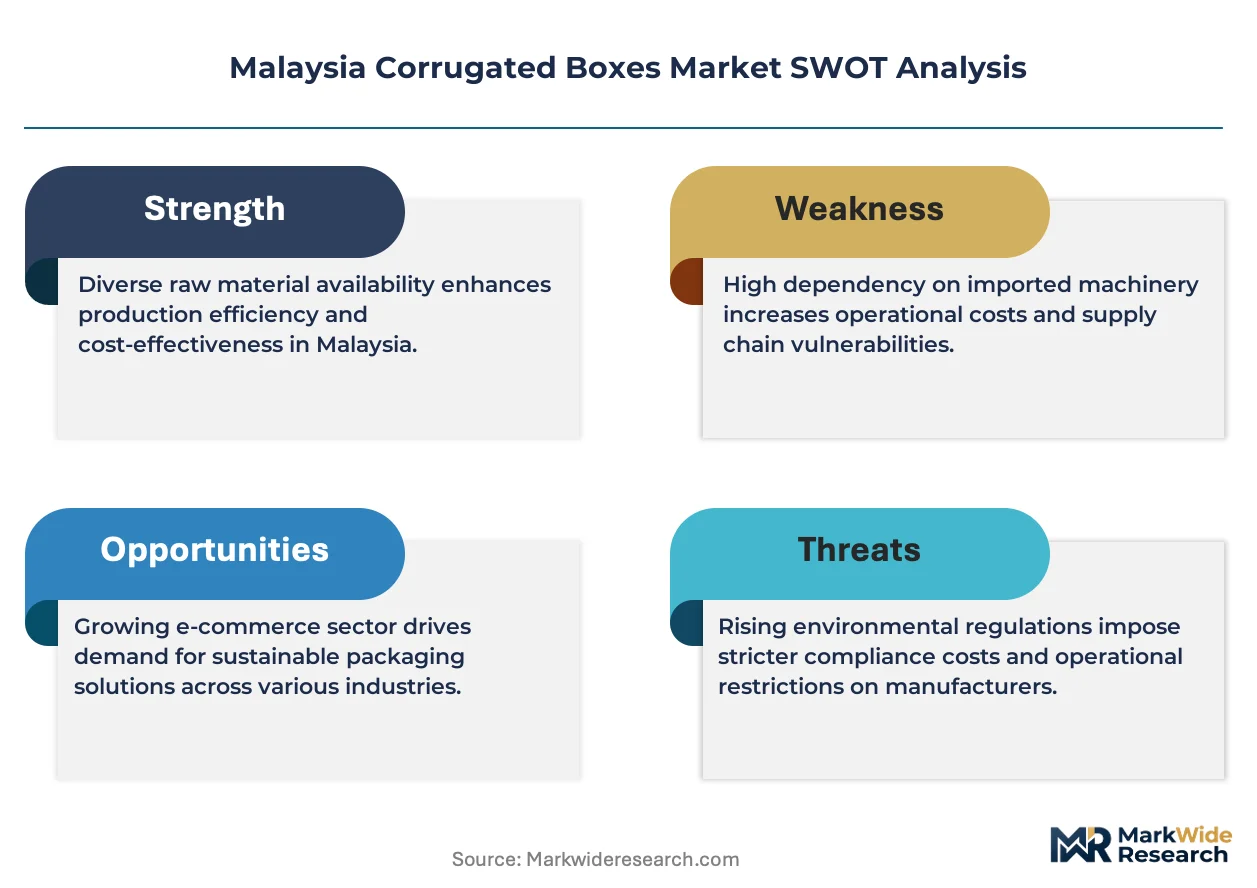
Malaysia's corrugated packaging sector is reconfiguring around Port Klang's logistics density, where e-commerce fulfillment hubs and integrated paperboard mills are compressing lead times and locking in captive linerboard flows across the Klang Valley industrial corridor.
Growth Catalysts
- Malaysian Investment Development Authority packaging incentives:Tax holidays and capital allowance extensions for recycled fiber processing plants are redirecting foreign direct investment toward circular production models in Selangor and Johor.
- E-commerce fulfillment network expansion:Peninsular Malaysia's last-mile distribution centers are absorbing larger die-cut and printed box volumes, with automated sortation facilities demanding precision-fit corrugated formats.
- Post-consumer waste minimums:Brand owners in food and beverage are imposing recycled content thresholds on packaging procurement, accelerating linerboard mill conversions to 100% recycled feedstocks.
Market Restraints
- Old corrugated container price volatility:Recycled fiber input costs fluctuate with Chinese import quota policies, squeezing margin visibility for independent converters without captive pulp supply.
- Selangor production concentration:Over 60% of national capacity sits within 50 kilometers of Port Klang, creating single-point vulnerability to port congestion or regional flooding.
- Fluting adhesive performance limits:Starch-based bonding chemistry constrains moisture resistance in tropical humidity, limiting penetration into fresh produce export cold chains without wax or polymer barrier upgrades.
Strategic Opportunities
- East Malaysia penetration gap:Sarawak and Sabah remain underserved by integrated mills, creating white space for regional converters with barge-fed linerboard supply from Peninsular hubs.
- Pharmaceutical cold-chain expansion:Temperature-validated corrugated with phase-change material integration is capturing share from expanded polystyrene in vaccine distribution, driven by WHO prequalification requirements.
- Putrajaya plastics substitution mandates:National policies restricting single-use plastics in food service are redirecting quick-service restaurant packaging procurement toward molded fiber and corrugated alternatives.
Industry Challenges
- Flexographic prepress technician scarcity:High-resolution platemaking and color management expertise concentrates in the Klang Valley, constraining quality consistency at peripheral converters in Perak and Pahang.
- SIRIM certification timeline compression:Packaging safety testing queues extend lead times for export-bound electronics assemblers, requiring parallel track validation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Corrugated Boxes Market |
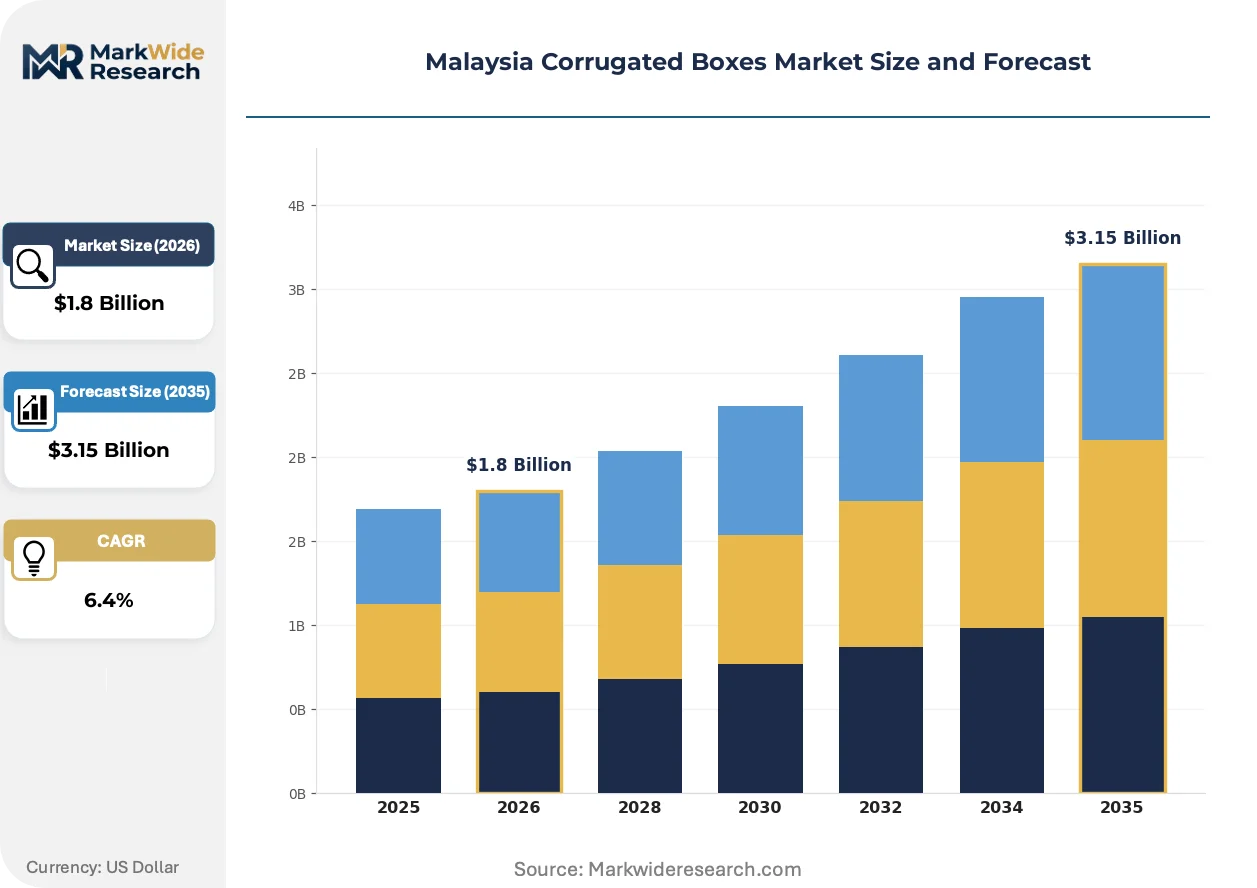
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Display Boxes Material: Fluted Paper, Linerboard, Coated Paper, Recycled Material End User: Food & Beverage, Electronics, Pharmaceuticals, Personal Care Packaging Type: Flat Pack, Die-cut Boxes, Custom Boxes, Printed Boxes |
| Companies Covered | Century Bond Group, Harta Packaging Industries, Box-Pak (Malaysia) Bhd, SCG Packaging Public Company Limited, Oji Holdings Corporation, YF Packaging, Boxku Packaging, Rengo Co., Ltd., Chuan Thong Industries Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Corrugated Boxes Market Strategic Shifts
Digital print and automation technologies are collapsing minimum order quantities while regulatory pressure on fiber sourcing transparency is rewiring procurement specifications across Malaysian manufacturing verticals.
High-speed flexographic direct-to-board printing is automating artwork changeovers that previously required physical plate swaps. Electronics assemblers in Penang are adopting this technology for regional SKU proliferation, compressing sampling cycles from weeks to days. The technology is automating short-run profitability thresholds that once favored centralized mega-facilities.
Malaysia's Environmental Quality Act effluent enforcement is mandating closed-loop water recovery at kraft linerboard mills. The Department of Environment's operational suspension authority is accelerating membrane filtration and anaerobic digestion capital deployment. Selangor-based integrated producers face the steepest compliance deadlines given their proximity to urban water catchments.
Consolidated procurement among fast-moving consumer goods distributors is displacing fragmented multi-source purchasing with preferred-supplier frameworks. Multinational brand owners are auditing mill-level fiber provenance, replacing spot-market converter relationships with multi-year volume commitments. This pattern concentrates most visibly in Port Klang's hinterland, where global consumer goods regional headquarters co-locate with distribution centers.
Malaysia Corrugated Boxes Market Segmentation
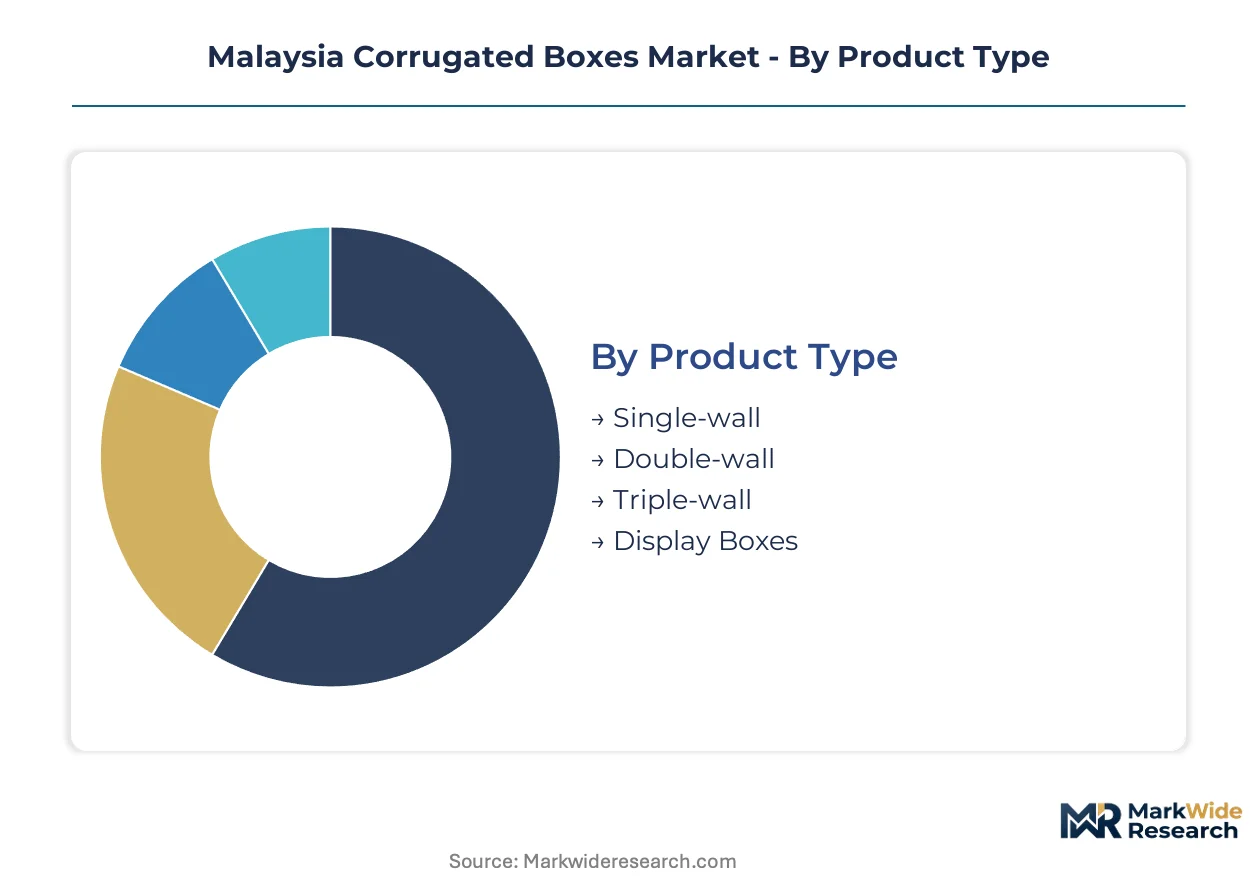
Segmentation in Malaysia's corrugated packaging sector reveals how upgrade cycles and material substitution pressures are redirecting procurement budgets across industrial verticals. Die-cut precision formats and recycled fiber specifications now dominate supplier qualification criteria in Port Klang's logistics corridor.
Product Type:
Upgrade cycles in Malaysia's corrugated sector center on stacking strength thresholds that force replacement of legacy single-wall configurations in heavy-goods distribution.
- Single-wall:One fluting layer bonded between two linerboard sheets delivers baseline protection for consumer goods under 15 kilograms. Electronics distributors in Penang's Free Industrial Zone specify this grade for component shipments where weight minimization reduces air freight charges.
- Double-wall:Two fluting layers separated by three linerboard sheets provide enhanced edge crush resistance for stacked pallet loads. Food and beverage manufacturers in Selangor specify double-wall for beverage multipacks destined for hypermarket distribution centers where warehouse stacking exceeds four meters.
- Triple-wall:Heavy machinery exporters specify this grade for load-bearing thresholds exceeding 500 kilograms in containerized ocean freight.
- Display Boxes:Retail-ready formats with pre-scored tear-away panels serve fast-moving consumer goods promotional campaigns in urban hypermarkets.
Volume placements concentrate in single-wall configurations; the faster expansion belongs to double-wall as warehouse automation raises stacking height requirements.
Material:
Cost tier differentiation in fiber sourcing separates integrated mills with captive pulp supply from converters exposed to spot-market recycled fiber volatility.
- Fluted Paper:The arched medium between linerboard sheets provides compressive cushioning through A, B, C, or E-flute profiles. Malaysian converters in Johor favor C-flute for balanced printability and stacking performance in e-commerce fulfillment applications.
- Linerboard:Flat facing sheets determine surface print quality and moisture resistance. Kraft linerboard from integrated Selangor mills commands premium placement in pharmaceutical cold-chain specifications requiring SIRIM certification.
- Coated Paper:Clay-coated surfaces enable high-resolution lithographic printing for premium cosmetic packaging in Kuala Lumpur's personal care sector.
- Recycled Material:Post-consumer corrugated containers processed into linerboard feedstock meet brand owner sustainability procurement mandates in the food service segment.
Procurement volumes cluster around virgin kraft linerboard; recycled material feeds are expanding most quickly under Department of Environment effluent enforcement pressures.
End User:
Application-specific performance requirements segment demand across temperature validation, moisture barrier, and print fidelity specifications.
- Food & Beverage:This vertical absorbs the largest corrugated volumes in Malaysia, driven by quick-service restaurant chain expansion and supermarket private-label growth. Wax-impregnated or polymer-coated variants address tropical humidity constraints in fresh produce export cold chains.
- Electronics:Penang's semiconductor and consumer electronics assemblers specify anti-static corrugated with precision die-cut foam inserts for component protection. Flat-pack formats minimize cubic volume in air freight consolidation.
- Pharmaceuticals:Temperature-validated corrugated with phase-change material integration captures vaccine distribution share from expanded polystyrene under WHO prequalification requirements.
- Personal Care:Premium cosmetic brands in the Klang Valley demand high-gloss lithographic finishes for retail shelf differentiation.
Food and beverage anchors procurement volumes; pharmaceutical cold-chain specifications are climbing the fastest as biologics distribution expands regionally.
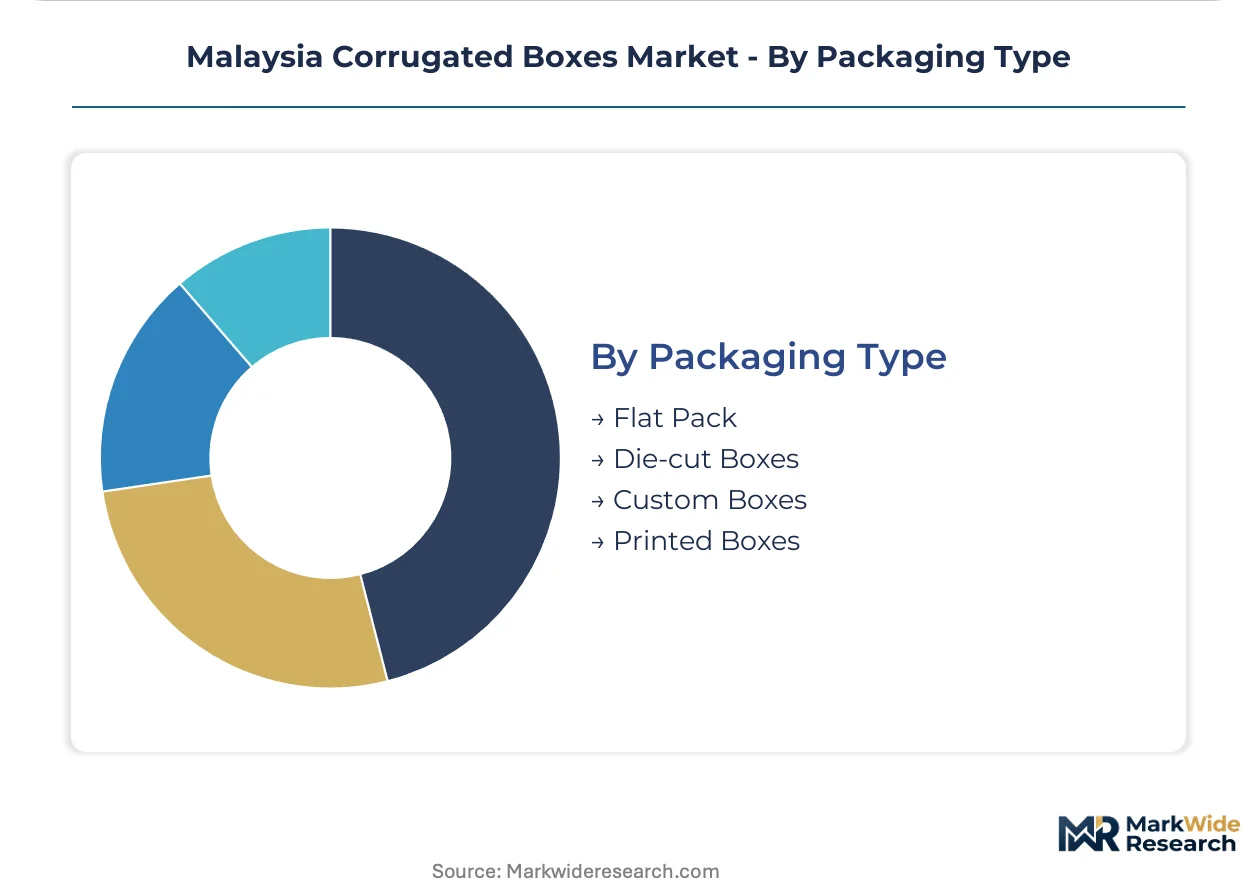
Packaging Type:
Customer type stratification separates high-volume standardized formats from customized precision-fit specifications requiring advanced prepress capabilities.
- Flat Pack:Unassembled box blanks ship in compressed bundles for on-site erection by fulfillment operators. Electronics contract manufacturers in Johor specify flat-pack for automated case-erector compatibility in high-velocity production lines.
- Die-cut Boxes:Computer-controlled cutting tables produce precision-fit formats with locking tabs and display windows. E-commerce platforms specify die-cut for automated sortation system compatibility and reduced void fill requirements.
- Custom Boxes:Bespoke structural designs engineered for irregular product geometries serve industrial machinery and automotive parts exporters.
- Printed Boxes:Flexographic or digital surface decoration enables brand communication and regulatory labeling compliance.
Flat-pack shipments dominate volume throughput; die-cut formats are gaining share fastest as automated fulfillment infrastructure expands across Peninsular Malaysia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled linerboard feedstock from Selangor's integrated mills anchors Malaysia's corrugated supply geography. Peninsular Malaysia absorbs over 85 percent of national box consumption. East Malaysia remains structurally underserved by captive pulp infrastructure.
Selangor
Port Klang's container throughput and proximity to Kuala Lumpur's distribution centers concentrate die-cut and printed box demand. The Malaysian Investment Development Authority's tax holidays for recycled fiber processing plants redirect foreign direct investment toward circular production models. Shah Alam's industrial corridor hosts integrated mills with captive linerboard output locking in margin visibility across the Klang Valley.
Penang
Free Industrial Zone electronics assemblers specify anti-static corrugated with precision die-cut foam inserts for semiconductor shipments. BIS-equivalent MS standards for packaging safety filter substandard imports from regional competitors. Bayan Lepas anchors precision-fit flat-pack procurement for automated case-erector compatibility in high-velocity production lines.
Johor
Iskandar Malaysia's logistics parks absorb e-commerce fulfillment volumes requiring automated sortation-compatible box formats. The Department of Environment's industrial effluent enforcement under the Environmental Quality Act pressures mills toward closed-loop water recovery systems. Pasir Gudang's industrial zone concentrates C-flute converters balancing printability and stacking performance for regional distribution.
Sarawak
Barge-fed linerboard supply from Peninsular hubs creates white space for regional converters serving timber and palm oil export packaging. Putrajaya's plastics substitution mandates redirect food and beverage sector purchasing toward fiber-based alternatives. Kuching's manufacturing base relies on imported board stock, extending lead times versus Peninsular competitors.
Malaysia Corrugated Boxes Market Competitive Environment
Preferred-supplier consolidation dominates the current landscape as multinational brand owners displace fragmented multi-source purchasing with multi-year volume commitments. The vendor base stratifies across integrated mills with captive pulp supply, independent converters exposed to spot-market fiber volatility, and regional specialists serving niche cold-chain specifications. Three archetypes define positioning: backward-integrated producers controlling linerboard feedstocks, precision die-cut specialists serving automated fulfillment infrastructure, and quality-certification holders capturing pharmaceutical and electronics verticals. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with mills adding recycled fiber processing lines and converters aligning with e-commerce platform technical specifications.
Among Japanese-standard quality protocol holders, Oji Holdings Corporation exemplifies the certification-driven archetype for temperature-validated applications. Century Bond Group anchors the integrated-mill tier through captive linerboard output across the Klang Valley. Box-Pak (Malaysia) Bhd occupies a position within the high-volume flat-pack segment serving multinational electronics assemblers. These three entities represent distinct competitive vectors: premium placement through quality accreditation, margin visibility through upstream feedstock control, and scale dominance through automated production line compatibility.
| Leading Market Players |
|---|
| Century Bond Group |
| Harta Packaging Industries |
| Box-Pak (Malaysia) Bhd |
| SCG Packaging Public Company Limited |
| Oji Holdings Corporation |
| YF Packaging |
| Boxku Packaging |
| Rengo Co., Ltd. |
| Chuan Thong Industries Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Brand owner mandates for 100% recycled fiber content are forcing Malaysian converters to absorb volatile old corrugated container feedstock costs, compressing margins at independent facilities without captive linerboard supply while integrated mills lock in contract premiums.
Pricing Analysis
Service bundling separates pure box supply from technical support packages covering SIRIM certification navigation and cold-chain validation documentation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale. Price differentiation hinges on captive pulp supply versus spot-market fiber exposure, with integrated producers commanding stability premiums. Cost compression in the independent converter tier is intensifying because Chinese import quota policies on recovered paper inject feedstock volatility. Quick-service restaurant chains exhibit highest price sensitivity due to standardized specifications and multi-source tendering, while pharmaceutical distributors prioritize temperature-validation guarantees over unit economics.
Supply Chain Analysis
Freight cost differentials between barge-fed East Malaysia supply and Peninsular mill direct delivery shape converter location decisions, with Sarawak operations carrying 15-20% logistics premiums. Geographic supply concentration centers on Selangor, Johor, and Penang, where integrated mills cluster within Port Klang's hinterland. Raw material dependencies draw from imported old corrugated containers, domestic kraft pulp, and starch-based adhesive formulations. Single-source vulnerability concentrates in Selangor's 60% national capacity share, exposing national supply to port congestion or regional flooding. Distribution runs through direct mill-to-fulfillment-center contracts for e-commerce platforms, with spot-market converter sales serving fragmented food and beverage processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's corrugated packaging sector is becoming a vertical-integration race as converters pursue captive linerboard supply to escape recycled fiber price volatility and secure margin visibility across the Klang Valley.
For Market Incumbents: Cement market position through backward integration into recycled fiber processing capacity in Selangor and Johor, exploiting Malaysian Investment Development Authority tax holidays before incentive windows narrow. Lock in multi-year preferred-supplier frameworks with multinational brand owners auditing mill-level fiber provenance, displacing fragmented spot-market relationships. Prioritize SIRIM certification investment to defend against Japanese-standard quality protocol holders capturing pharmaceutical cold-chain share. For New Entrants and Emerging Players: Enter via barge-fed linerboard supply to underserved Sarawak and Sabah markets, where timber and palm oil export packaging demand exceeds regional converter capacity. Target quick-service restaurant chains responding to Putrajaya plastics substitution mandates with molded fiber and corrugated alternatives. Pursue automated sortation-compatible die-cut specifications as the go-to-market angle, aligning technical capabilities with e-commerce platform infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with precision die-cut specialists serving automated fulfillment infrastructure given Peninsular Malaysia's e-commerce fulfillment network expansion. Long-term viability favors converters with demonstrated cold-chain validation capabilities and phase-change material integration expertise. Watch for Department of Environment operational suspension enforcement against non-compliant mills as an inflection indicator accelerating consolidation toward integrated producers with closed-loop water recovery systems.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Fiber Processing Capacity Addition | MIDA tax holidays redirect foreign direct investment toward circular production models in Selangor. |
| Backward Integration into Linerboard Supply | Captive pulp output locks in margin visibility against old corrugated container price volatility. |
| SIRIM Certification Parallel Track Investment | Compressed testing queues at export-bound electronics assemblers demand validation acceleration. |
| East Malaysia Barge-Fed Distribution Network | White space in Sarawak and Sabah creates regional converter opportunities beyond Peninsular saturation. |
| Phase-Change Material Cold-Chain Integration | WHO prequalification requirements drive corrugated capture of vaccine distribution from expanded polystyrene. |
Study Parameters
Multi-period observation of linerboard mill capacity utilization, e-commerce fulfillment square footage expansion, and brand owner recycled content procurement mandates anchored the trend analysis, supplemented by interviews with plant managers at integrated mills, procurement leads at multinational electronics assemblers, category buyers at quick-service restaurant chains, and technical directors at cold-chain logistics providers. Secondary validation drew from Malaysian Investment Development Authority incentive disclosures, Department of Environment enforcement records, SIRIM certification databases, and Port Klang container throughput statistics. Bottom-up facility-level production estimates and top-down sectoral absorption models were triangulated against trade flow data.
Segment-weighting across product type, material specification, end-use vertical, and packaging format dimensions informed volume and value outputs across the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling incorporating e-commerce penetration trajectories, plastics substitution policy implementation pace, and warehouse automation stacking height requirements. Industry-specific forecast inputs included flexographic direct-to-board printing adoption curves and closed-loop water recovery capital deployment timelines under Environmental Quality Act enforcement.
Revisions become necessary when Chinese recovered paper import quota policies shift, Department of Environment suspension enforcement intensifies, or multinational brand owner fiber provenance auditing requirements tighten beyond current specifications. Forecasts reflect documented assumptions regarding incentive continuity, infrastructure completion schedules, and regulatory implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Paper Based Consumer Bags Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
North America Paper Cone Market