
 Canada Plastic Packaging Films Market | 2026-2036
Canada Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plastic Packaging Films Market Insights
The gap between premium barrier films and commodity-grade polyethylene wraps is repositioning how Canadian converters allocate capital and technical resources. Amcor Group GmbH leverages its multi-layer coextrusion expertise to dominate high-performance food packaging contracts with national protein processors. FLAIR Flexible Packaging Corporation anchors its competitiveness through specialized shrink film production for Ontario's beverage bottling corridor.
Plastic packaging films constitute thermoplastic polymer sheets engineered to thicknesses between 12 and 250 micrometers, manufactured through blown film extrusion, cast extrusion, or biaxial orientation processes to deliver moisture barriers, puncture resistance, and seal integrity for perishable goods containment. Stretch film commands the largest volume position across Canadian logistics networks, while flexible film formats capture expanding share in e-commerce protective wrapping as parcel volumes surge. Polyethylene grades sustain cost leadership in industrial palletization, though polypropylene films penetrate pharmaceutical blister lidding where clarity and stiffness specifications tighten.
Health Canada, the Canadian Food Inspection Agency, and Environment and Climate Change Canada collectively govern food-contact safety approvals, extended producer responsibility mandates, and single-use plastics prohibitions that reshape formulation requirements and collection infrastructure obligations. The national plastics registry under development will force film producers to document recycled content percentages and end-of-life pathways with unprecedented granularity. Stakeholders must resolve whether to invest in domestic advanced recycling capacity or secure certified circular feedstock through import arrangements before compliance deadlines crystallize.
Market Dynamics
Health Canada's tightening food-contact material standards and Environment and Climate Change Canada's extended producer responsibility mandates are forcing converters to requalify formulations and rebuild collection infrastructure simultaneously. The national plastics registry under development will impose granular documentation requirements on film producers.
Growth Catalysts
- Extended Producer Responsibility Mandates:Provincial programs in Ontario and Quebec now require post-consumer recycled content minimums, creating pull-through demand for certified circular polyethylene feedstock.
- Mono-Material Shift:Protein processors across Alberta and Saskatchewan are specifying single-polymer structures to meet emerging mechanical recycling compatibility standards.
- E-Commerce Parcel Surge:Protective flexible film consumption in British Columbia's logistics corridors is scaling with fulfillment center density.
Market Restraints
- Resin Price Volatility:Ethylene feedstock costs tied to Western Canadian natural gas liquids pricing transmit directly to converter margin compression.
- Advanced Recycling Capacity Gap:Domestic pyrolysis and chemical recycling infrastructure remains concentrated in Ontario, leaving prairie and Atlantic converters dependent on export pathways.
- Multi-Layer Film Incompatibility:Existing barrier film architectures containing EVOH or nylon layers face mechanical recycling rejection at municipal sorting facilities.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick food processing clusters lack local high-barrier film supply, creating white space for regional converter investment.
- National Plastics Registry Alignment:Early compliance with Environment and Climate Change Canada's tracking requirements positions suppliers for preferred procurement status.
- Pharmaceutical Blister Lidding:Polypropylene clarity specifications from Health Canada are opening technical film specifications previously served by aluminum.
Industry Challenges
- Coextrusion Technician Scarcity:Seven-layer blown film expertise is concentrated among aging workforces in Ontario and Quebec, constraining expansion timelines.
- Food-Contact Requalification Burden:Health Canada's updated migration testing protocols require 18-24 month validation cycles for reformulated structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plastic Packaging Films Market |
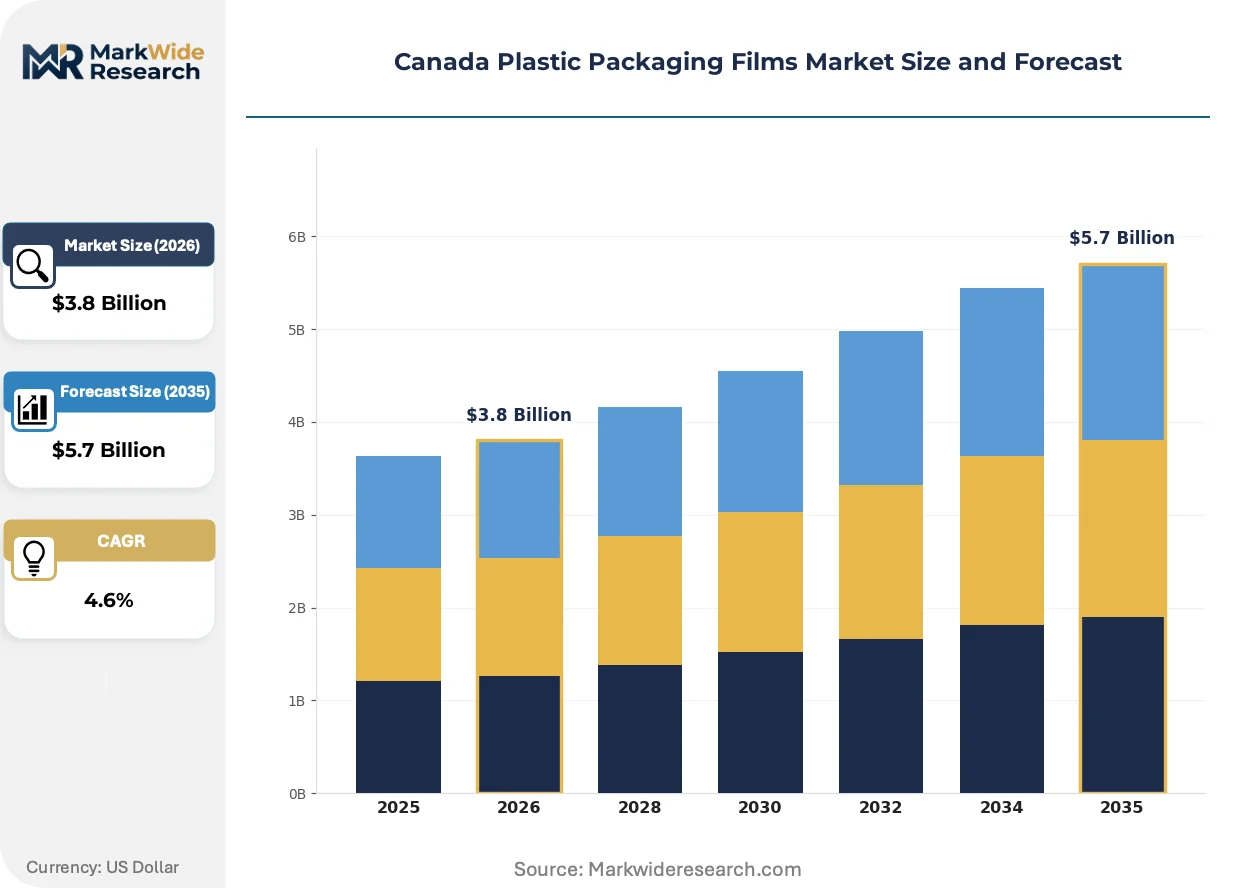
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Rigid Film, Flexible Film Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Industrial Packaging End User: Retail, Manufacturing, Logistics, E-Commerce |
| Companies Covered | Amcor Group GmbH, Mondi Plc, FLAIR Flexible Packaging Corporation, C-P Flexible Packaging, Inc., ProAmpac LLC, Berry Global Group Inc, WINPAK Ltd., Emmerson Packaging Holdings Inc, Sigma Plastics Group Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plastic Packaging Films Market Trends and Innovations
Canada's plastic packaging films sector is pivoting from cost-driven commodity supply toward compliance-integrated performance positioning. Technical differentiation now hinges on recyclability certification and food-contact safety documentation rather than gauge reduction alone.
Machine-direction oriented polyethylene film is electrifying barrier performance in protein packaging applications. National meat processors are specifying MDPE lidding films at accelerating rates to replace multi-layer structures. This substitution is electrifying converter investment in orientation lines while compressing demand for conventional coextrusion capacity.
Environment and Climate Change Canada's single-use plastics prohibition regulations are reshaping format specifications across food service and retail channels. The industrial consequence is a forced migration from polystyrene and conventional polyethylene to certified compostable or recyclable alternatives. Ontario's fresh produce packaging sector is most affected, with buyers now requiring third-party recyclability verification.
Consolidated procurement by national grocery banners is compressing supplier rosters and extending contract durations. Regional converters face displacement by integrated suppliers offering pan-Canadian logistics and unified sustainability reporting. British Columbia's beverage and dairy processing clusters exhibit this concentration most visibly, with buyers consolidating film spend under fewer master service agreements.
Canada Plastic Packaging Films Market Segmentation
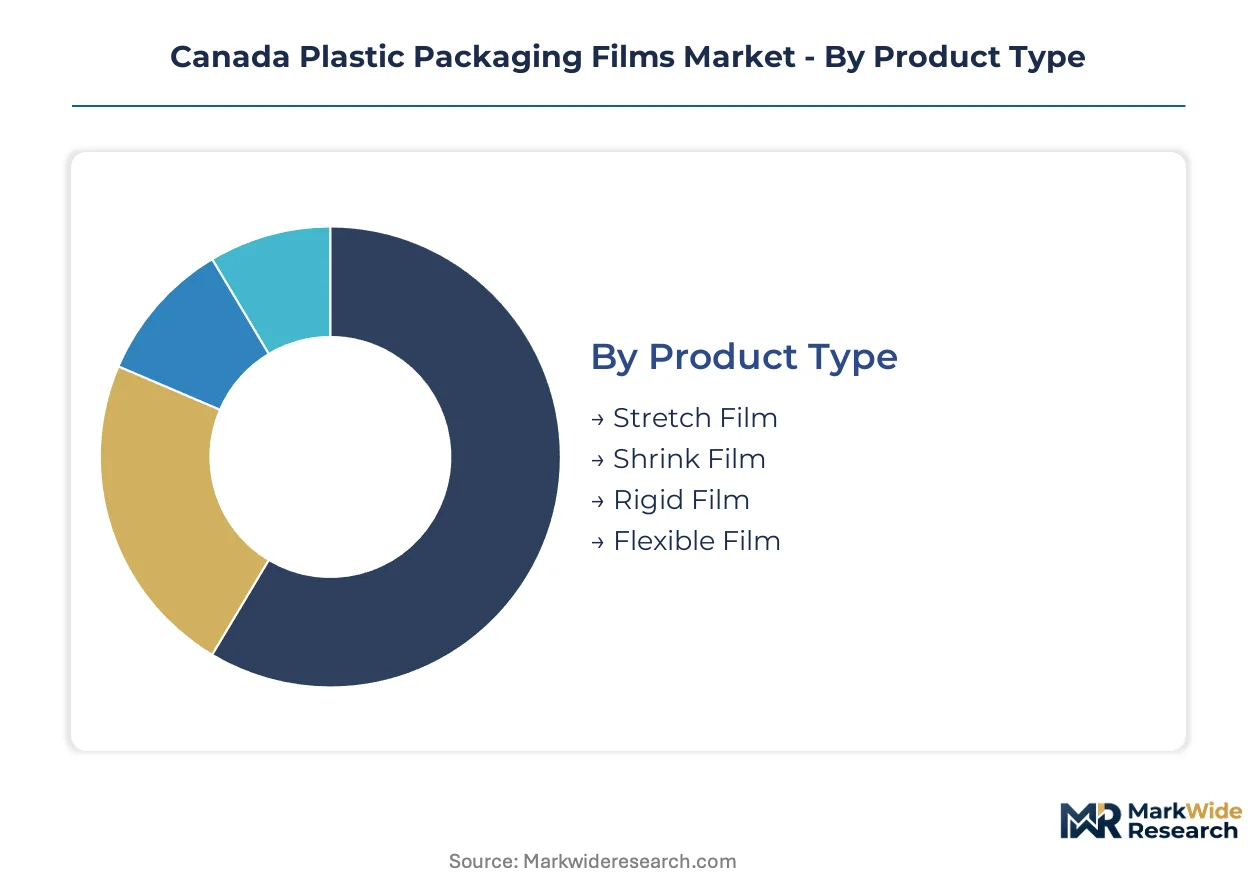
Segmentation in Canada's plastic packaging films market reveals how regulatory pressure and supply chain configuration split procurement behavior. Buyers prioritize recyclability certification in food-contact applications while logistics operators optimize for load containment economics.
Product Type:
Converters differentiate their film portfolios based on downstream handling requirements and end-of-life pathway complexity.
- Stretch Film:Linear low-density polyethylene formulations dominate pallet containment across Canadian distribution networks. Ontario's automotive parts suppliers and Quebec's food distributors consume the highest volumes as warehouse automation expands stretch wrapping throughput.
- Flexible Film:Multi-layer coextruded structures serve fresh produce and protein lidding where moisture barriers and puncture resistance converge. British Columbia's greenhouse vegetable sector and Alberta's beef processing clusters are specifying mono-material flexible alternatives to meet emerging mechanical recycling standards.
- Shrink Film:Polyolefin grades bundle beverage multipacks and frozen food cases through heat-activated contraction. Ontario's beverage bottling corridor anchors regional demand.
- Rigid Film:Thermoformed polystyrene and PET sheets form clamshells and trays for deli meats and bakery items. Health Canada's tightened migration limits are forcing reformulation toward polypropylene alternatives.
Stretch film leads volumes today; flexible film is gaining share fastest as food processors abandon multi-layer barrier structures.
Material:
Resin selection tracks price volatility exposure against performance specification rigidity across end-use applications.
- Polyethylene:Low-density and linear low-density grades sustain cost leadership in industrial palletization and commodity food wraps. Western Canadian natural gas liquids pricing directly transmits to converter margins, amplifying procurement sensitivity among prairie logistics operators.
- Polypropylene:Oriented films deliver clarity and stiffness for pharmaceutical blister lidding and high-visibility retail packaging. Health Canada's clarity specifications for unit-dose medication are displacing aluminum in Ontario's generic drug manufacturing.
- Polyvinyl Chloride:Plasticized formulations persist in medical device overwrap and select food tray applications despite mechanical recycling incompatibility. Regulatory pressure is compressing its addressable market.
- Others:Certified compostable films and bio-based polymers penetrate fresh produce segments where municipal composting infrastructure exists, notably in Metro Vancouver and Toronto.
Polyethylene dominates tonnage; polypropylene exhibits the steepest expansion trajectory as pharmaceutical specifications tighten.
Application:
Application segmentation maps directly onto Health Canada's food-contact enforcement intensity and extended producer responsibility compliance deadlines.
- Food Packaging:Protein, dairy, and fresh produce films face the most stringent requalification burdens under updated migration testing protocols. Ontario and Quebec processors are accelerating mono-material polyethylene adoption to satisfy provincial recycled content mandates.
- Industrial Packaging:Pallet wrap and intermediate bulk container liners prioritize unit economics over sustainability certification. Prairie province manufacturing clusters prioritize resin cost stability.
- Beverage Packaging:Shrink film multipacks and stretch-wrapped bottle trays serve carbonated soft drinks and bottled water. British Columbia's deposit-return system integration influences film selection.
- Pharmaceutical Packaging:Blister lidding and pouch structures demand validated barrier performance and extractables documentation. Health Canada's 18-24 month requalification cycles constrain supplier switching.
Food packaging commands the largest revenue pool; pharmaceutical packaging offers the most defensible margin structure.
End User:
End user categories separate volume-driven procurement from specification-intensive buying behavior.
- Logistics:Third-party warehouse operators and freight carriers consume stretch film at scale, with procurement decisions driven by metered yield and puncture resistance metrics. Ontario's 401 corridor distribution density concentrates demand.
- Manufacturing:Food processors and consumer goods producers specify custom barrier structures with embedded recyclability claims. National grocery banner consolidation is extending contract durations and compressing supplier rosters.
- E-Commerce:Fulfillment centers in the Greater Toronto Area and Metro Vancouver are scaling protective flexible film consumption with parcel volume density. Air pillow and bubble alternatives compete for protective packaging share.
- Retail:In-store deli, bakery, and produce departments specify pre-formed bags and wraps with third-party recyclability verification. Ontario's fresh produce packaging sector is most affected by single-use plastics prohibitions.
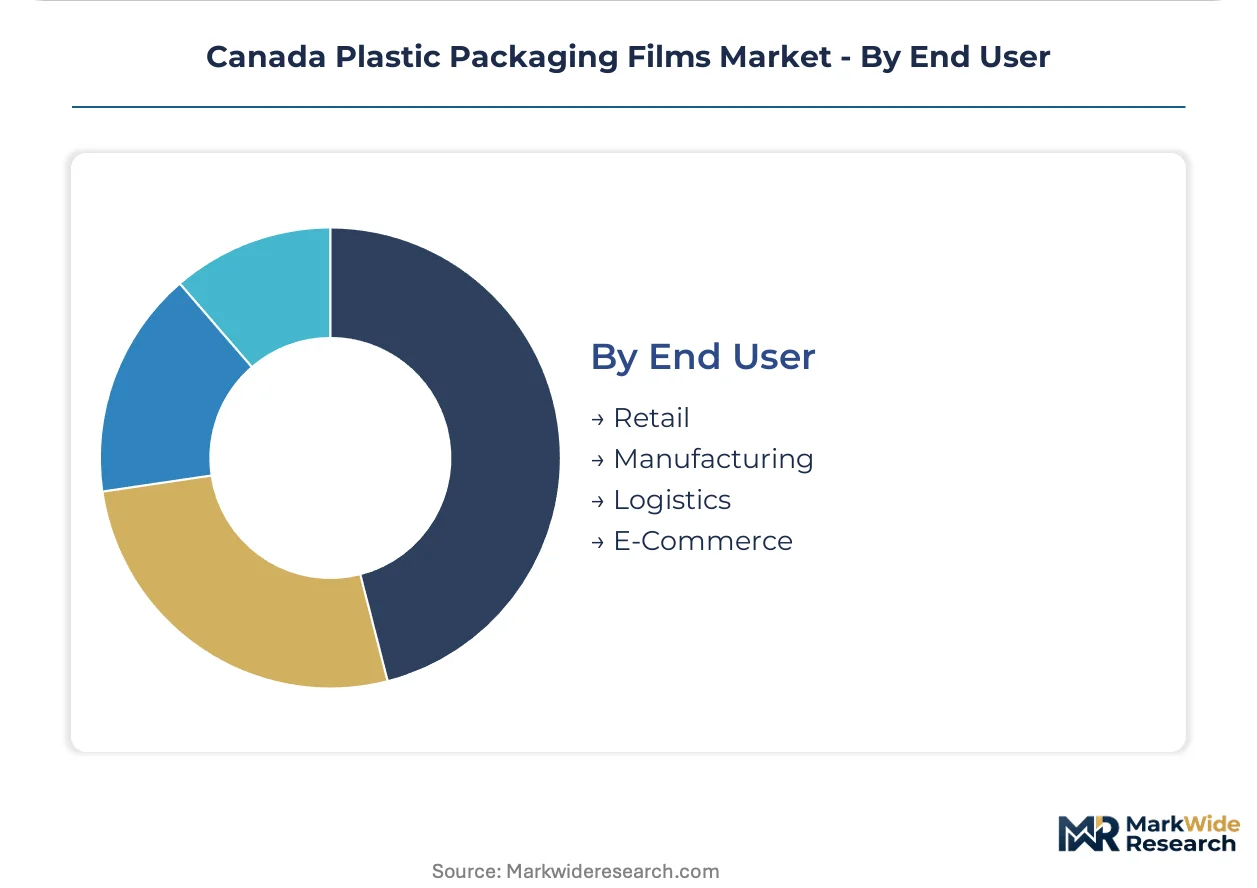
Logistics leads absolute consumption; e-commerce is climbing the fastest as fulfillment center density accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coextrusion technicians cluster in Ontario and Quebec, anchoring Canada's technical film production capacity while prairie provinces face recruitment gaps for advanced blown film operations.
Ontario
Automotive parts suppliers and food distributors drive stretch film consumption along Highway 401's warehouse corridor. Environment and Climate Change Canada's extended producer responsibility mandates force Toronto-area converters to requalify formulations. The Greater Toronto Area's fulfillment center density is scaling protective flexible film demand with e-commerce parcel volumes.
Quebec
Protein processors and dairy operations specify high-barrier lidding films under tightened Health Canada migration testing protocols. The province's recycled content minimums create pull-through demand for certified circular polyethylene feedstock. Montreal's packaging converter base is investing in mono-material extrusion lines to meet mechanical recycling compatibility standards.
Alberta
Beef processing clusters are accelerating single-polymer structure adoption to satisfy emerging recycling compatibility requirements. Western Canadian natural gas liquids pricing transmits directly to converter margins, amplifying procurement sensitivity. Calgary's logistics operators prioritize resin cost stability in industrial palletization contracts.
British Columbia
Greenhouse vegetable producers and beverage bottlers specify flexible films with third-party recyclability verification. Metro Vancouver's municipal composting infrastructure supports certified compostable film penetration in fresh produce segments. The province's deposit-return system integration influences shrink film selection for beverage multipacks.
Atlantic Canada
Nova Scotia and New Brunswick food processing clusters lack local high-barrier film supply, creating white space for regional converter investment. Health Canada's food-contact safety approvals constrain supplier switching with 18-24 month validation cycles. Halifax's emerging distribution hub is attracting protective film demand from maritime logistics expansion.
Canada Plastic Packaging Films Market Competitive Landscape
Top-tier vendors anchor national protein processor contracts and pan-Canadian logistics agreements, while mid-scale regional converters defend specialty niches in beverage shrink film and pharmaceutical lidding. The vendor base stratifies across integrated multinationals with unified sustainability reporting and independent operators with flexible technical service. Three archetypes dominate: diversified packaging conglomerates with extrusion-to-converting integration, specialized flexible film houses with barrier technology focus, and regional converters with logistics-adjacent production. Competitive moves concentrate on mono-material line investments and early national plastics registry compliance positioning.
Within the multinational tier, Amcor Group GmbH and Mondi Plc occupy positions defined by multi-layer coextrusion expertise and pan-Canadian supply network coverage. FLAIR Flexible Packaging Corporation exemplifies the specialized regional archetype, anchoring competitiveness through Ontario-focused production. Berry Global Group Inc represents the diversified conglomerate model with extrusion-to-converting integration across multiple packaging substrates.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Mondi Plc |
| FLAIR Flexible Packaging Corporation |
| C-P Flexible Packaging, Inc. |
| ProAmpac LLC |
| Berry Global Group Inc |
| WINPAK Ltd. |
| Emmerson Packaging Holdings Inc |
| Sigma Plastics Group Inc |
| Others |
Pricing and Supply Chain Analysis
Ethylene feedstock costs tied to Western Canadian natural gas liquids pricing transmit directly through converter margin structures, stratifying procurement economics across prairie logistics operators and Ontario food processors. This cost architecture separates spot-market polyethylene buyers from contract-anchored national accounts with volume-scaled pricing.
Pricing Analysis
Bundled sustainability certification and unbundled commodity resin quotes split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels tracks recyclability verification and food-contact safety documentation intensity. Price differentiation hinges on Health Canada requalification status and provincial recycled content mandate alignment. Cost compression in commodity-grade stretch film intensifies because resin volatility transmits without hedging buffers. Prairie province logistics operators exhibit highest price sensitivity; pharmaceutical blister lidding buyers show least.
Supply Chain Analysis
Dual-sourcing requirements from national grocery banners force converters to qualify secondary resin suppliers and redundant extrusion capacity. Supply concentrates in Ontario, Quebec, and Alberta, with critical mono-material orientation equipment clustering in the Golden Horseshoe. Raw material dependencies center on ethylene feedstock, certified circular polyethylene, and EVOH barrier resins. Single-source vulnerability runs through advanced recycling infrastructure concentrated in Ontario. Distribution runs through converter-direct relationships with protein processors and pan-Canadian logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Protein processors are specifying mono-material polyethylene structures with embedded recyclability certification, elevating technical film specifications above commodity resin economics.
For Market Incumbents: Deepen backward integration into certified circular feedstock supply through Ontario pyrolysis partnerships or import arrangements. Expand mono-material extrusion capacity in Quebec to capture dairy and protein processor contract renewals. Threat substitution from compostable films in Metro Vancouver demands pre-emptive recyclability verification investment.
For New Entrants and Emerging Players: Regional logistics operators in Atlantic Canada represent the most penetrable channel partner type for protective film supply. Target Nova Scotia and New Brunswick food processing clusters lacking local high-barrier capacity. Go-to-market angle: mechanical recycling compatibility certification bundled with 18-month requalification support.
For Investors and Strategic Acquirers: Roll-up economics work for specialized flexible film houses with barrier technology focus because national plastics registry compliance creates scale advantages in documentation infrastructure. Long-term viability favors converters with early registry alignment and pan-Canadian logistics coverage. Acquisition target archetype: Ontario-focused regional converters with seven-layer coextrusion expertise and aging ownership. Signal to watch: Health Canada migration testing protocol amendments accelerating requalification burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Investment | Mechanical recycling compatibility opens Ontario and Quebec protein processor contracts. |
| Certified Circular Feedstock Securement | Provincial recycled content mandates create pull-through demand with compliance premiums. |
| Advanced Recycling Partnership | Domestic pyrolysis capacity reduces export pathway dependency for prairie converters. |
| Food-Contact Requalification Service | Health Canada validation support extends contract durations with national grocery banners. |
| Atlantic Canada Regional Expansion | Nova Scotia and New Brunswick processing clusters lack local high-barrier supply. |
Research Methodology
Direct dialogue with extrusion plant managers, procurement leads at national protein processors, technical R&D directors at resin suppliers, and distribution channel partners grounded qualitative findings. Secondary validation drew from Environment and Climate Change Canada regulatory filings, Health Canada food-contact safety submissions, provincial extended producer responsibility program disclosures, and customs trade data. Bottom-up capacity and demand estimates triangulated against top-down market sizing.
Bottom-up modeling tracked installed extrusion capacity by province and resin throughput by application segment. Top-down validation referenced national plastics production statistics and packaging converter revenue disclosures. Segmentation dimensions spanned product type, material grade, application intensity, and end-user procurement behavior. CAGRs derived from regression against historical resin pricing volatility and regulatory compliance deadline clustering. Forecast inputs included Western Canadian natural gas liquids pricing trajectories and mechanical recycling infrastructure buildout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Health Canada protocol amendments and provincial recycled content mandate stringency. Deviation in advanced recycling capacity deployment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Latin America Plastic Packaging Films Market
Poly film
Bio-PET Film Market
Poly film
Global Fluoropolymer Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
India BOPP Films Market
Poly film
Shrink Bundling Films Market
Poly film
Packaging Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Hexacomb Packaging Market
Poly film
EVOH Encapsulation Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
Foamed Polypropylene Films Market
Poly film
Global PVDC Coated Films Market
Poly film
Asia-Pacific Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Vinyl Films Market