
 Bagasse Bowls Market | 2026-2036
Bagasse Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Bagasse Bowls Market Outlook
Asset-light contract manufacturing and third-party molding partnerships are reshaping competitive entry in bagasse tableware, lowering capital barriers for regional challengers. Eco-Products leverages its North American distribution network to sustain shelf presence across food service channels. GangXuan Eco-Pack anchors production scale through integrated pulp molding operations in Guangdong province. Biopak differentiates via certified compostable supply chains that meet Australian and European standards.
Bagasse bowls are molded fiber containers produced from sugarcane pulp residue, typically featuring heat tolerance to 100°C and oil resistance suitable for hot and greasy foods. Their primary commercial purpose is replacing petroleum-based disposable tableware in food service and takeaway applications. Round bowls dominate volume due to universal utility across soup, rice, and noodle formats, while compartment bowls command margin premiums from fast-casual chains requiring meal separation. The food delivery segment shows structural momentum as platform economics prioritize lightweight, stackable, and leak-resistant packaging that reduces rider handling costs.
The FDA regulates food-contact substances under 21 CFR, while the EU Packaging and Packaging Waste Directive sets recovery targets that favor compostable fiber alternatives over conventional plastics. BIS certification requirements in India and EFSA migration limits in Europe shape product formulation and barrier-coating choices for export-oriented manufacturers. Stakeholders must monitor evolving extended producer responsibility schemes and fiber sourcing traceability mandates that will determine which production bases retain cost-competitive market access.
Market Dynamics
Single-use plastic bans across Southeast Asian food service corridors are compressing substitution timelines and forcing rapid supply chain reconfiguration toward molded fiber alternatives.
Growth Catalysts
- Regulatory Prohibition Cascades:Vietnam's national plastic reduction roadmap and Indonesia's waste management law are mandating compostable tableware in informal food vending zones, creating immediate replacement demand for bagasse bowls.
- Food Delivery Platform Economics:Grab and Gojek rider networks are specifying lightweight, stackable bowl formats that reduce per-delivery handling costs and damage rates.
- Pulp Molding Automation:Robotic fiber deposition systems are cutting unit production costs and enabling tighter dimensional tolerances for leak-resistant rim designs.
Market Restraints
- Sugarcane Harvest Volatility:Monsoon pattern shifts in Maharashtra and Uttar Pradesh are creating raw fiber supply interruptions that propagate through Guangdong molding centers.
- Barrier Coating Cost Premiums:PLA and PBAT lamination layers required for oil resistance add 15-25% material cost versus uncoated fiber, compressing margins at price-sensitive contract catering segments.
- Composting Infrastructure Gaps:Industrial composting facility scarcity in Philippine and Indonesian secondary cities means bagasse bowls often enter landfill streams, undermining environmental claims and inviting regulatory scrutiny.
Strategic Opportunities
- Quick-Service Restaurant Chains:Jollibee and Yoshinoya franchise expansion across secondary Vietnamese cities is creating demand for branded, compartment-format bagasse bowls with custom embossing.
- Extended Producer Responsibility Schemes:Thailand's draft packaging waste framework is positioning compostable fiber tableware for preferential fee structures versus conventional plastics.
- Smart Packaging Convergence:Integration of QR-coded traceability layers with bagasse substrates is enabling supply chain transparency premiums for export-oriented European buyers.
Industry Challenges
- Mold Design Engineering Talent:Shortage of thermoforming specialists capable of optimizing fiber flow patterns for complex compartment geometries is extending product development cycles.
- Multi-Jurisdiction Certification Burden:Simultaneous pursuit of BIS, FDA, and EFSA food-contact approvals is requiring parallel testing protocols that strain mid-tier manufacturer cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bagasse Bowls Market |
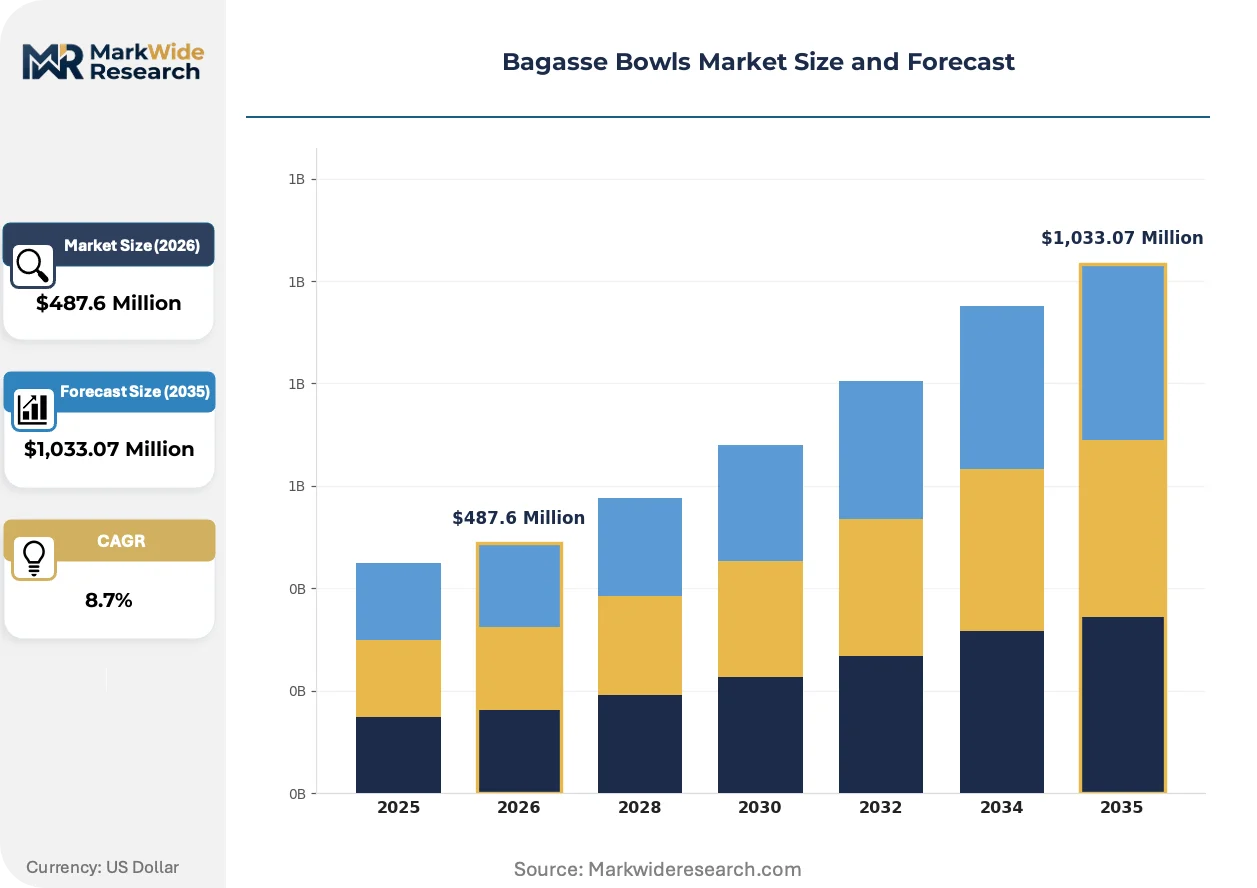
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Bowls, Square Bowls, Compartment Bowls, Biodegradable Bowls End User: Food Service, Catering, Retail, Food Delivery Application: Takeaway Packaging, Event Catering, Meal Prep, Fast Food Service Size: Small, Medium, Large, Extra Large |
| Companies Covered | GangXuan Eco-Pack, GreenGood, Eco-Products, YJS Environmental Products Co., Ltd., Sunkea, Bioleader, Biopak, Shenglin Packaging, Hefei Craft Tableware Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bagasse Bowls Market Strategic Shifts
Processing technology advances and compliance automation are compressing product development timelines while reshaping how manufacturers compete on certification breadth and barrier performance.
Precision fiber conditioning systems are digitizing quality control across bagasse pulping operations. Thai and Vietnamese molding facilities are deploying inline moisture sensors and automated density scanners to reduce batch-to-batch variation. This standardization is digitizing the path to consistent heat-tolerance ratings that meet European food-service procurement specifications.
REACH substance restrictions are tightening migration limits for fluorinated barrier coatings used in oil-resistant tableware. ECHA evaluations of PFAS alternatives are pushing manufacturers toward bio-based wax and clay composite formulations. European import channels are responding by demanding third-party compostability certifications ahead of formal regulatory deadlines.
Centralized procurement desks at regional food delivery platforms are consolidating supplier relationships and mandating unified sustainability reporting. GrabKitchen cloud kitchen networks are replacing fragmented local vendor purchasing with direct mill contracts. This concentration is most visible in Bangkok and Ho Chi Minh City, where platform-specified bowl formats now dominate mid-tier restaurant packaging decisions.
Bagasse Bowls Market Segmentation
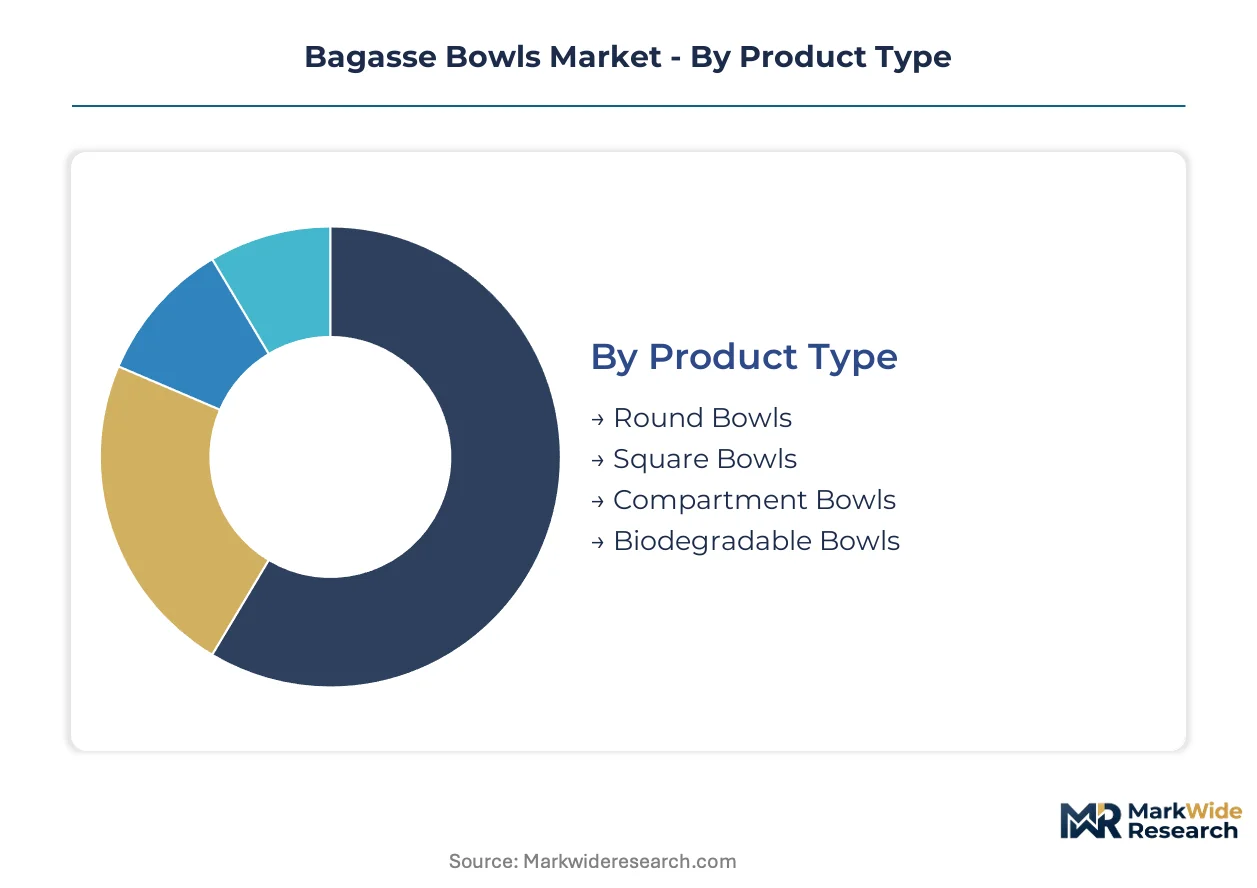
Segmentation in bagasse bowls tracks how procurement cycles, certification requirements, and food service workflows reshape demand across formats. Understanding these divides reveals where manufacturers must prioritize mold capacity and barrier coating investments.
Product Type:
Round bowls turn inventory fastest through universal compatibility, while compartment formats sit longer in specification pipelines due to custom mold requirements.
- Round Bowls:Standardized circular containers with uniform rim diameters stack efficiently for food delivery logistics. Vietnamese street food vendors and GrabKitchen cloud kitchens in Bangkok specify this format for soup and rice combinations, driving repeat procurement at high frequency.
- Compartment Bowls:Molded fiber designs with internal dividers separate proteins from carbohydrates and sauces. Fast-casual chains expanding across secondary Indonesian cities require these for meal presentation, though longer lead times apply for embossed branding and custom cavity geometries.
- Square Bowls:Angular profiles maximize storage density in refrigerated display cases. Retail delis and supermarket prepared-food sections in urban Thailand favor this geometry for shelf space optimization.
- Biodegradable Bowls:Certified compostable variants meeting BPI or OK Compost HOME standards. European export channels and Australian food service procurement desks mandate this grade for EPR compliance and sustainability reporting.
Round bowls anchor the volume base while compartment bowls gain share at the steepest rate.
End User:
Cost tiers separate contract catering from platform-driven food delivery, with certification depth determining supplier eligibility at each level.
- Food Delivery:Platform-specified procurement through Grab, Gojek, and ShopeeFood networks concentrates demand for lightweight, leak-resistant formats. Rider handling economics prioritize stackable designs that reduce per-delivery damage rates and speed order assembly.
- Food Service:Quick-service restaurants and independent eateries source through distributor networks with varying sustainability mandates. Jollibee and Yoshinoya franchise expansion across Vietnam creates demand for branded, heat-tolerant configurations.
- Catering:Event and institutional contract catering requires bulk pricing and consistent supply security. Wedding halls and corporate canteens in Jakarta and Manila specify uncoated fiber for cost control on large-volume orders.
- Retail:Supermarket chains and convenience stores stock consumer-facing multipacks. 7-Eleven Thailand and FamilyMart Indonesia are expanding private-label bagasse tableware for household meal prep applications.
Food delivery commands the steepest expansion trajectory as platform procurement desks consolidate supplier relationships.
Application:
Volume concentration follows meal occasion frequency, with daily takeaway routines outpacing episodic event demand.
- Takeaway Packaging:Daily-use containers for street food and quick-service transactions. Hawker centers in Singapore and night markets in Ho Chi Minh City generate continuous replenishment cycles for standard round formats.
- Fast Food Service:Heat-tolerant designs for fried and grilled items with oil resistance requirements. Chains serving crispy chicken and noodle soups across the Philippines specify PLA-laminated fiber to prevent leakage and structural failure.
- Meal Prep:Refrigerator-stable containers for subscription food services and health-focused consumers. Jakarta and Bangkok urban professionals drive demand for compartment formats with snap-fit lids.
- Event Catering:Single-use solutions for weddings, conferences, and festivals. Seasonal demand spikes in Malaysian festival seasons and Indonesian wedding calendars create procurement timing challenges for manufacturers.
Takeaway packaging anchors the volume base while fast food service climbs the fastest on quick-service chain expansion.
Size:
Customer type segmentation reveals how portion culture and cuisine format determine diameter and depth specifications.
- Medium:450-600ml capacity serving standard rice and noodle portions across Southeast Asian cuisines. Indonesian nasi padang and Vietnamese pho vendors specify this as the default procurement tier.
- Large:750-1000ml designs for family-style sharing and combo meals. Thai street food stalls serving multiple curry selections favor this format for value-oriented portion presentation.
- Small:250-350ml containers for side dishes, desserts, and condiment separation. Dessert specialists in Philippine food halls and sauce accompaniments for Malaysian nasi lemak drive niche demand.
- Extra Large:1200ml+ capacities for bulk catering and group orders. Corporate lunch deliveries and institutional feeding programs in Vietnamese industrial zones require this tier for cost-efficient meal distribution.
Medium sizes anchor the volume base while large formats gain share fastest on family combo meal expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Guangdong province supply molded fiber tableware to European and North American food service channels, while import dependence characterizes Southeast Asian markets lacking integrated pulp molding infrastructure. Trade flows concentrate through Vietnamese and Thai ports serving quick-service restaurant chains and platform delivery networks.
China
Guangdong province hosts the densest concentration of integrated bagasse pulp molding operations, serving export procurement desks in Europe and Australia. The country's GB standards for food-contact materials shape barrier coating formulations across the Pearl River Delta manufacturing belt. Zhengzhou and Hefei industrial clusters specialize in automated fiber deposition equipment that supplies regional molding facilities.
Vietnam
GrabKitchen cloud kitchen expansion across Ho Chi Minh City and Hanoi drives round bowl procurement at volumes exceeding domestic molding capacity. The national plastic reduction roadmap mandates compostable tableware in informal food vending zones by specified deadlines. Da Nang and Can Tho secondary cities are emerging as logistics hubs for Mekong Delta agricultural fiber sourcing.
Indonesia
Waste management law provisions are accelerating substitution timelines for street food vendors in Jakarta and Surabaya metropolitan areas. Jollibee franchise expansion across secondary cities creates specification pipelines for custom embossed compartment bowls. Surabaya industrial zones host emerging contract molding partnerships serving domestic quick-service chains.
Thailand
Bangkok's platform delivery density concentrates procurement decisions for lightweight, stackable bowl formats across Grab and ShopeeFood networks. Draft extended producer responsibility frameworks position compostable fiber tableware for preferential fee structures versus conventional plastics. Chiang Mai and Phuket tourism corridors generate seasonal demand spikes for event catering applications.
India
Maharashtra and Uttar Pradesh sugarcane belts supply raw bagasse fiber to molding centers, though monsoon volatility creates intermittent supply interruptions. BIS certification requirements for food-contact substances shape export formulation strategies for European-bound manufacturers. Gujarat industrial corridors are developing automated pulping capacity to reduce dependence on Guangdong equipment imports.
Bagasse Bowls Market Competitive Environment
On the supply side, the industry is structured around three tiers: integrated pulp molders with captive fiber processing, contract manufacturers serving platform procurement desks, and equipment suppliers enabling regional capacity expansion. Strategic archetypes include Guangdong-based scale operators, Australian-certified compostable specialists, and automation-focused machinery fabricators. Dominant competitive moves encompass third-party molding partnerships that lower capital barriers and geographic expansion through distributor network acquisitions.
Within the integrated manufacturing tier, GangXuan Eco-Pack anchors production scale through Guangdong province operations, while Biopak occupies a position exemplifying certified compostable supply chain differentiation for European and Australian procurement channels. Among North American distributors, Eco-Products represents the archetype of food service channel shelf presence sustained through established logistics networks.
| Leading Market Players |
|---|
| GangXuan Eco-Pack |
| GreenGood |
| Eco-Products |
| YJS Environmental Products Co., Ltd. |
| Sunkea |
| Bioleader |
| Biopak |
| Shenglin Packaging |
| Hefei Craft Tableware Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Ho Chi Minh City freight corridors transmit Guangdong molding center cost dynamics downstream, compressing margin structures for Vietnamese distributors while enabling three-tier pricing stratification across certification grades. This logistics artery concentrates supply-side leverage among integrated pulp processors, forcing contract manufacturers to absorb barrier-coating premiums or cede platform procurement contracts to scale operators.
Pricing Analysis
Industrial OEM buyers anchor a contract-based pricing structure where BIS-certified and FDA-tiered formulations command substantial premiums over uncoated fiber baselines. Price differentiation rests on certification depth and volume scale, with PLA-laminated compartments separating from standard round formats. Cost compression in the uncoated tier is intensifying because monsoon-driven fiber shortages propagate through Maharashtra supply belts. Contract catering segments exhibit highest price sensitivity, while European export channels tolerate premium tiers for EFSA compliance.
Supply Chain Analysis
Contract manufacturing concentrates among Guangdong integrated molders, Vietnamese assembly partnerships, and emerging Indonesian molding zones near Surabaya industrial corridors. Geographic supply draws from China, India, and Thailand, with raw fiber sourcing tethered to Maharashtra and Uttar Pradesh sugarcane belts plus Guangdong chemical pulp imports. Single-source vulnerability runs through PLA and PBAT barrier-coating suppliers concentrated in East Asian polymer production. Distribution runs through platform procurement desks at Grab and Gojek, consolidating fragmented food-service vendor relationships into direct mill contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bagasse bowl incumbents face substitution pressure from emerging mycelium and seaweed-based tableware formats that bypass composting infrastructure requirements. Defense of market position demands preemptive moves before regulatory preference shifts toward next-generation biomaterials.
For Market Incumbents: Entrench platform relationships through exclusive supply agreements with GrabKitchen and Gojek procurement desks, locking in volume commitments before mycelium alternatives achieve cost parity. Deepen upstream control over Maharashtra fiber sourcing through long-term agricultural partnerships that buffer monsoon volatility. Prioritize BIS and EFSA certification maintenance as defensive moats against mid-tier challengers lacking parallel testing capacity.
For New Entrants and Emerging Players: Philippine secondary cities present white-space opportunity where industrial composting gaps have slowed incumbent penetration and price-sensitive contract catering dominates. Target Surabaya and Bandung cloud kitchen clusters with uncoated fiber formats that undercut PLA-laminated premiums. Pursue asset-light molding partnerships with Guangdong equipment suppliers to bypass capital-intensive pulping infrastructure.
For Investors and Strategic Acquirers: Certified compostable specialists with Australian BPI and European OK Compost HOME credentials represent acquisition targets positioned for EPR scheme expansion. Long-term viability hinges on composting infrastructure buildout across Southeast Asian secondary cities. Monitor Thailand's draft packaging waste framework implementation as inflection signal for preferential fee structure confirmation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Sourcing | Maharashtra agricultural partnerships reduce monsoon exposure for Guangdong molders. |
| Certification Portfolio Expansion | Simultaneous BIS, FDA, and EFSA approvals unlock European and Australian procurement channels. |
| Platform Procurement Desk Concentration | Direct Grab and Gojek contracts displace fragmented distributor relationships in Bangkok. |
| Barrier Coating R&D Partnership | Bio-based wax and clay formulations address REACH PFAS restrictions for European exports. |
| Secondary City Logistics Hub Development | Da Nang and Can Tho facilities capture Mekong Delta fiber flows for Vietnamese molding. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food delivery platform procurement managers, quick-service restaurant supply chain directors, bagasse pulp molding plant engineers, and composting facility operators. Secondary validation drew from BIS certification registries, EU Packaging and Packaging Waste Directive implementation reports, Grab and Gojek sustainability disclosures, and Maharashtra agricultural department harvest statistics. Bottom-up volume estimates from molding facility capacity utilization were triangulated against top-down platform delivery transaction data.
Calibration against historical substitution elasticities in single-use plastic ban implementations informed demand modeling across the projection horizon. Segmentation dimensions encompassed product format, end-user channel, application occasion, and portion size tier. CAGRs were derived from fitted growth curves incorporating regulatory deadline enforcement patterns and platform expansion trajectories. Forecast inputs included sugarcane harvest yield projections and composting infrastructure development pipelines.
Practitioners should monitor Thailand EPR framework finalization and Philippine industrial composting facility announcements for early signals of demand trajectory revision. Cross-checking against EU import channel volume data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
PVC-Free Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
North America Eco-Friendly Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market