
 Composite Cardboard Tube Packaging Market | 2026-2036
Composite Cardboard Tube Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Cardboard Tube Packaging Market Intelligence
The move toward custom-shaped and highly decorated packaging is repositioning composite cardboard tubes beyond simple cylindrical formats for brand differentiation. Sonoco leverages its extensive global manufacturing footprint to serve multinational food and beverage clients. Smurfit Kappa differentiates with its portfolio of sustainably sourced fiber solutions and circular economy initiatives. Meanwhile, Visican specializes in bespoke, premium tubes for the cosmetics and luxury goods sectors.
Composite cardboard tubes are multi-ply, spirally wound paperboard structures engineered for product containment and brand presentation. An inner liner, often of polyethylene or aluminum foil, provides a crucial barrier against moisture, oxygen, and light. The cosmetics and personal care sector constitutes the largest end-user segment, valuing the premium aesthetic and customization potential. Material compositions featuring an aluminum foil layer represent the fastest-growing option for food applications where extended shelf life is critical.
Material choices are heavily influenced by food-contact safety regulations from bodies like the US FDA and material substance rules under the EU's REACH framework. In China, compliance with national GB standards for packaging is mandatory for market entry, shaping liner and adhesive formulations. Navigating the complex trade-offs between barrier performance, material recyclability, and production cost remains the central strategic challenge for manufacturers.
Market Dynamics
The central structural force shaping the composite cardboard tube packaging market is the conflict between the need for high-performance barriers for product protection and the intensifying regulatory and consumer pressure for simplified, fully recyclable packaging structures.
Growth Catalysts
- Sustainable Packaging Mandates:Stringent environmental laws, such as Germany's Packaging Act (VerpackG), incentivize the use of paper-based packaging with high recyclability, directly benefiting composite tubes that can meet these criteria over single-use plastics.
- Cosmetics Sector Demand:The cosmetics and personal care industry's focus on premium aesthetics and brand differentiation drives adoption of customizable, highly decorated cardboard tubes as a perceived sustainable alternative to plastic packaging.
- Barrier Technology Innovation:The development of new polyethylene-free, water-based barrier coatings enables the use of composite tubes for a wider range of sensitive products, expanding market applications beyond dry goods.
Market Restraints
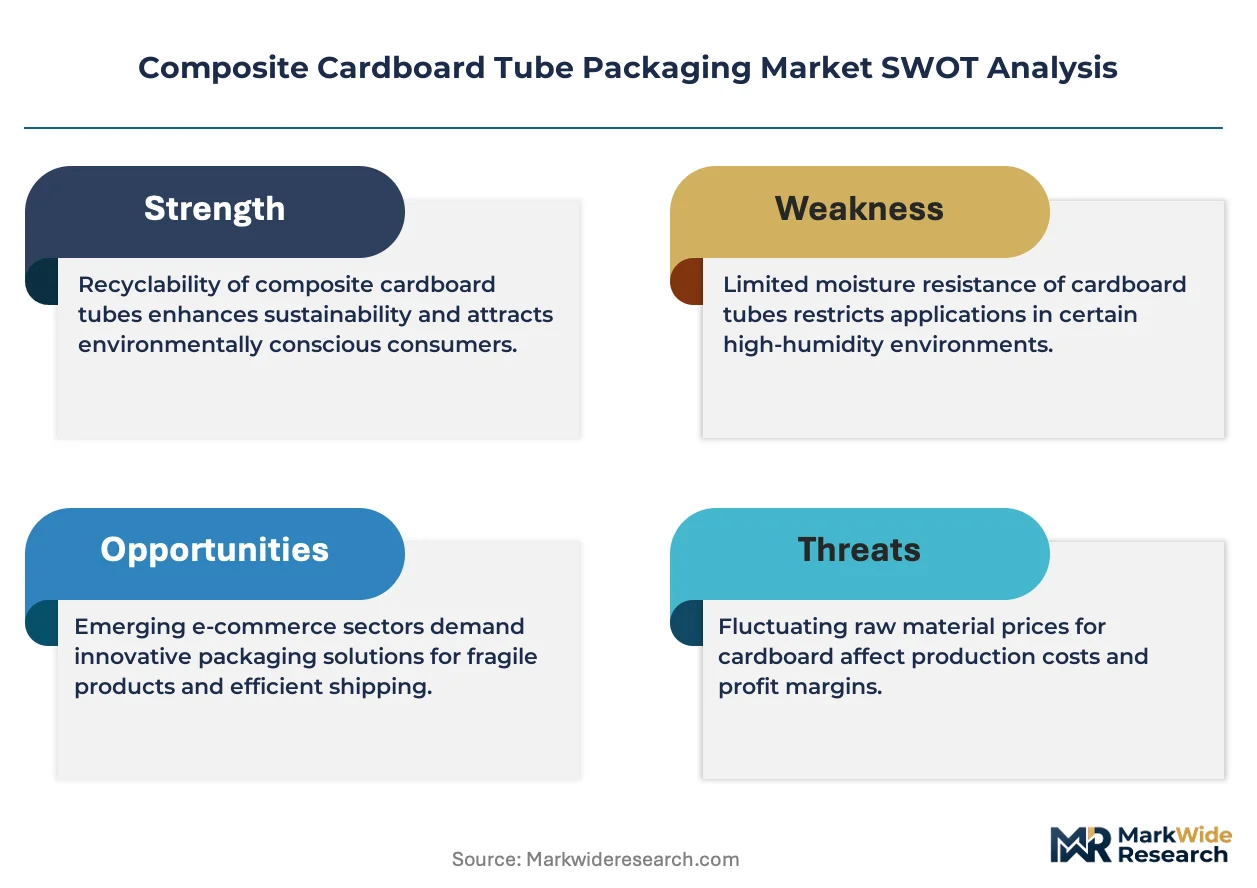
- Raw Material Cost Volatility:Fluctuation in the price of key inputs, particularly aluminum foil and specialty barrier polymers, creates margin pressure and complicates long-term pricing strategies for tube manufacturers.
- Recycling Complexity:Despite innovations, composite structures that fuse paperboard with plastic or foil liners remain challenging for many municipal recycling facilities to process, hindering circular economy goals.
- Substitution from Flexible Packaging:In cost-sensitive food segments, flexible pouches and mono-material plastic containers offer a lower-cost alternative with comparable barrier properties, limiting tube penetration.
Strategic Opportunities
- Pharmaceutical and Nutraceutical Expansion:Advanced barrier technologies create an opportunity to penetrate the high-value pharmaceutical and nutraceutical markets, which require packaging with superior protection against moisture, oxygen, and light.
- EU Single-Use Plastic Directives:Regulations under the EU Green Deal aimed at reducing plastic waste create a significant regulatory tailwind, positioning paper-based tubes as a compliant and attractive alternative for many products.
- Emerging Market Adoption:Rapid growth in the packaged food and personal care sectors in Southeast Asian countries presents an underpenetrated geographic opportunity for composite tube manufacturers.
Industry Challenges
- Navigating Global Regulations:Manufacturers face the operational challenge of ensuring liner and adhesive formulations comply with a complex web of disparate food-contact safety rules, including US FDA standards, EU's REACH framework, and China's GB standards.
- High Capital Investment:Acquiring and maintaining precision spiral-winding machinery and advanced liner application systems requires significant capital expenditure, creating a barrier to entry and expansion for smaller firms.
- Recycling Infrastructure Gaps:The effectiveness of "recyclable" claims depends on available infrastructure, and a lack of widespread facilities that can separate liners from paper fiber limits the actual circularity of many composite tubes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Cardboard Tube Packaging Market |
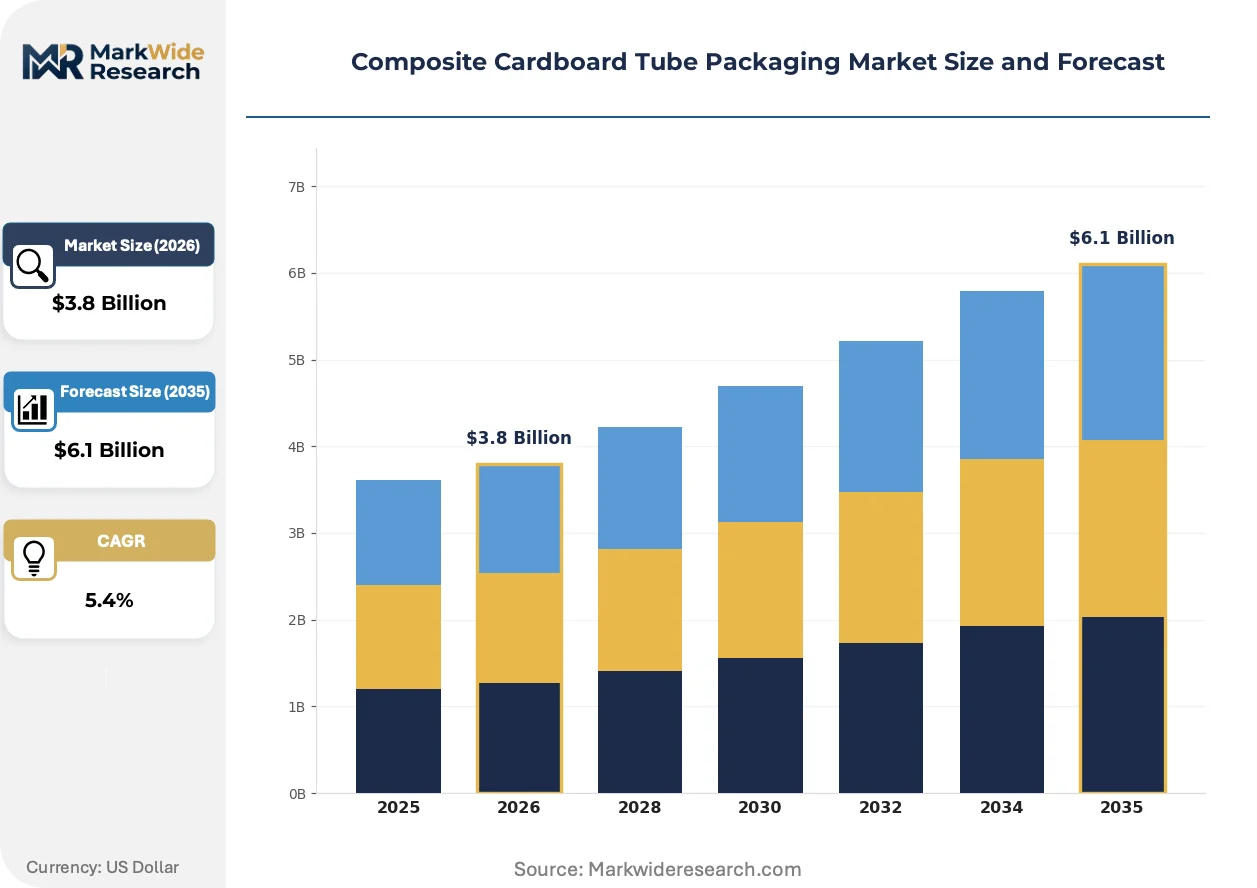
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Tubes, Square Tubes, Hexagonal Tubes, Custom-Shaped Tubes Material Composition: Kraft Paper, Wax Coated Paper, Polyethylene Lining, Aluminum Foil Layer End User Industry: Cosmetics & Personal Care, Food & Beverage, Industrial Components, Luxury Goods Distribution Channel: Direct Sales, Online Platforms, Wholesalers, Specialty Packaging Suppliers |
| Companies Covered | Mondi Group, Visican, Sonoco, Marshall Paper Tube, Valk Industries, Smurfit Kappa, CBT Packaging, Chicago Paper Tube, Ace Paper Tube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Cardboard Tube Packaging Market Strategic Shifts & Innovations
Material science is at the core of market evolution, with intense research and development focused on resolving the inherent trade-off between barrier performance and end-of-life recyclability. This pursuit drives innovation in both liner technology and structural design.
Advanced polyethylene-free barrier coatings and dispersible adhesives are gaining traction. Food and beverage brands are adopting this technology to substantiate "plastic-free" marketing claims and improve their environmental profiles. This innovation is modularizing the barrier system, allowing for tailored performance against moisture or oxygen without compromising the paper tube's recyclability in standard pulp mills.
European Union regulations, particularly the Packaging and Packaging Waste Regulation (PPWR), are setting stringent new targets for recyclability and recycled content. This policy is forcing a redesign of composite tubes away from inseparable multi-material constructions. The food and cosmetics sectors are most impacted, accelerating investment in mono-material or easily separable liner solutions to maintain market access.
Consumer demand for unique packaging formats is pushing brands beyond simple cylinders. The traditional format is being challenged by custom shapes like oval, square, or triangular tubes that provide superior shelf presence and brand differentiation. This trend is most visible in the luxury cosmetics, premium spirits, and specialty food sectors, particularly in North American and Western European markets.
Composite Cardboard Tube Packaging Market Segmentation
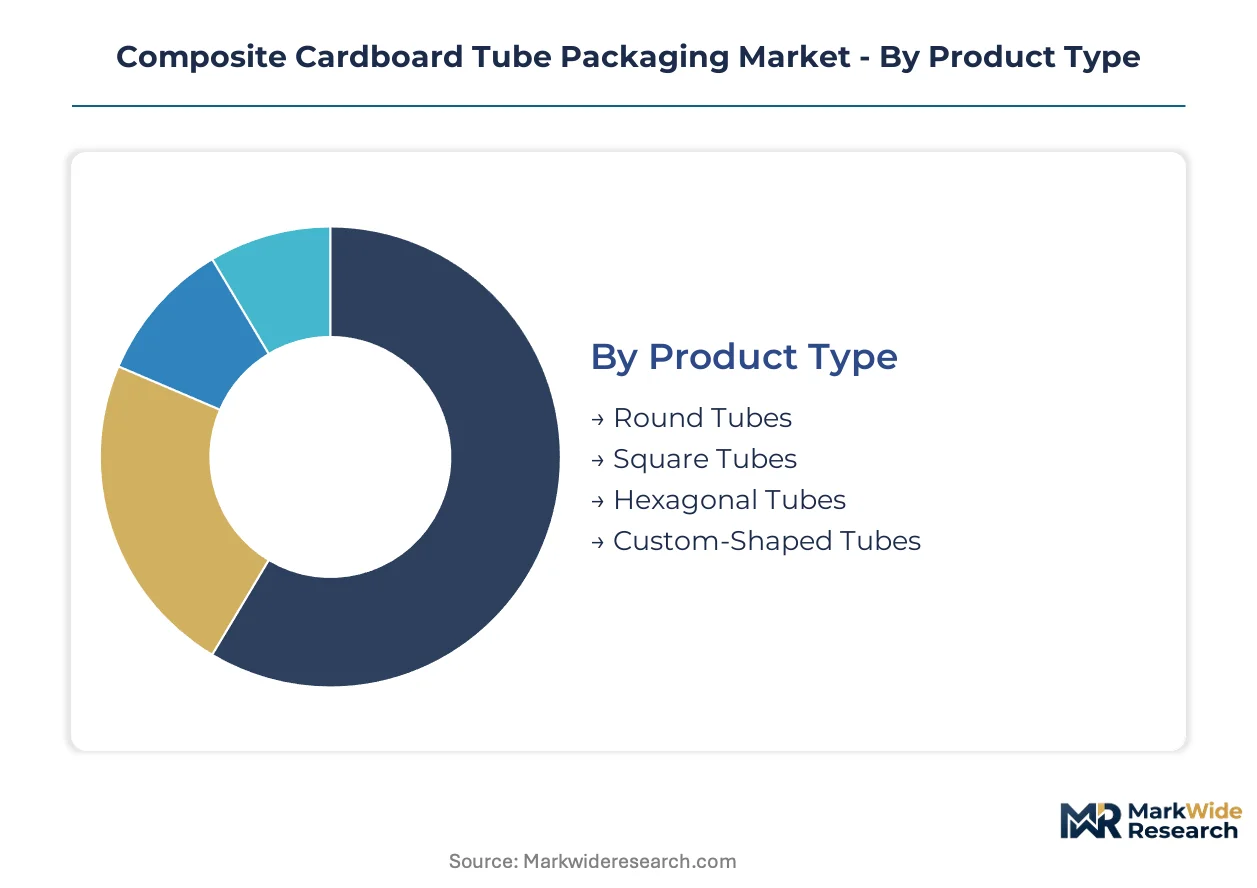
The composite cardboard tube packaging market segments reflect the diverse requirements of end-user industries and the evolving landscape of material science. Understanding these distinct segments allows manufacturers to tailor product offerings and navigate complex regulatory frameworks across different applications.
Product Type:
Specific product types often necessitate compliance with distinct packaging standards, particularly for food-contact or pharmaceutical applications under US FDA or EU Green Deal guidelines.
- Round Tubes:These traditional cylindrical structures form the foundational format for composite cardboard packaging, offering cost-effective production and efficient material usage. Demand remains consistently high across food and beverage and industrial components sectors, valued for their structural integrity and established manufacturing processes.
- Custom-Shaped Tubes:Engineered for unique brand differentiation, these tubes deviate from standard cylindrical forms, incorporating oval, square, or triangular profiles. Luxury goods and premium cosmetics brands in Western European markets increasingly adopt these formats to enhance shelf presence and consumer appeal.
- Square Tubes:Designed to optimize storage and shipping space, square tubes provide a distinct aesthetic and improved stacking efficiency compared to traditional round formats.
- Hexagonal Tubes:Offering a visually interesting alternative, hexagonal tubes combine structural stability with a unique form factor, appealing to brands seeking innovative presentation.
Leading the category by volume: Round Tubes. Custom-Shaped Tubes represent the fastest-growing option.
Material Composition:
Material choices are primarily driven by a balance of barrier performance, recyclability, and production cost considerations for various product categories.
- Aluminum Foil Layer:This multi-ply construction incorporates an aluminum foil layer, providing superior barrier protection against moisture, oxygen, and light, crucial for product shelf life. Food and beverage brands, especially for sensitive perishables, increasingly specify this composition to meet extended shelf-life requirements and comply with food safety regulations.
- Polyethylene Lining:A common inner liner, polyethylene provides an effective moisture barrier and heat-sealable properties for product containment. While widely used in cosmetics and personal care, innovations in polyethylene-free alternatives are gaining traction due to environmental pressures.
- Kraft Paper:Forming the primary structural component, kraft paper offers inherent strength and a natural aesthetic, serving as the base for various composite tube constructions.
- Wax Coated Paper:This material provides a basic moisture barrier, often used for dry goods or products requiring moderate protection from external elements.
These material choices reflect a balance between performance requirements and cost considerations.
End User Industry:
The application of composite cardboard tubes varies significantly across industries, each with unique packaging needs and regulatory compliance demands.
- Cosmetics & Personal Care:This sector utilizes composite tubes for premium packaging, valuing their aesthetic appeal, customization potential, and perceived sustainability for products like creams, lotions, and powders. The demand for highly decorated tubes for brand differentiation is particularly strong in Germany and the United States.
- Food & Beverage:Composite tubes protect dry goods, snacks, and powdered beverages from moisture and oxygen, extending shelf life and maintaining product freshness. Brands in the European Union are increasingly adopting these tubes for their recyclability and compliance with packaging waste directives.
- Industrial Components:Packaging for industrial components prioritizes protection from physical damage and environmental factors during transit and storage.
- Luxury Goods:High-end luxury products leverage the premium feel and customization options of composite tubes to enhance brand image and consumer experience.
The diverse application landscape drives innovation in both barrier properties and aesthetic design.
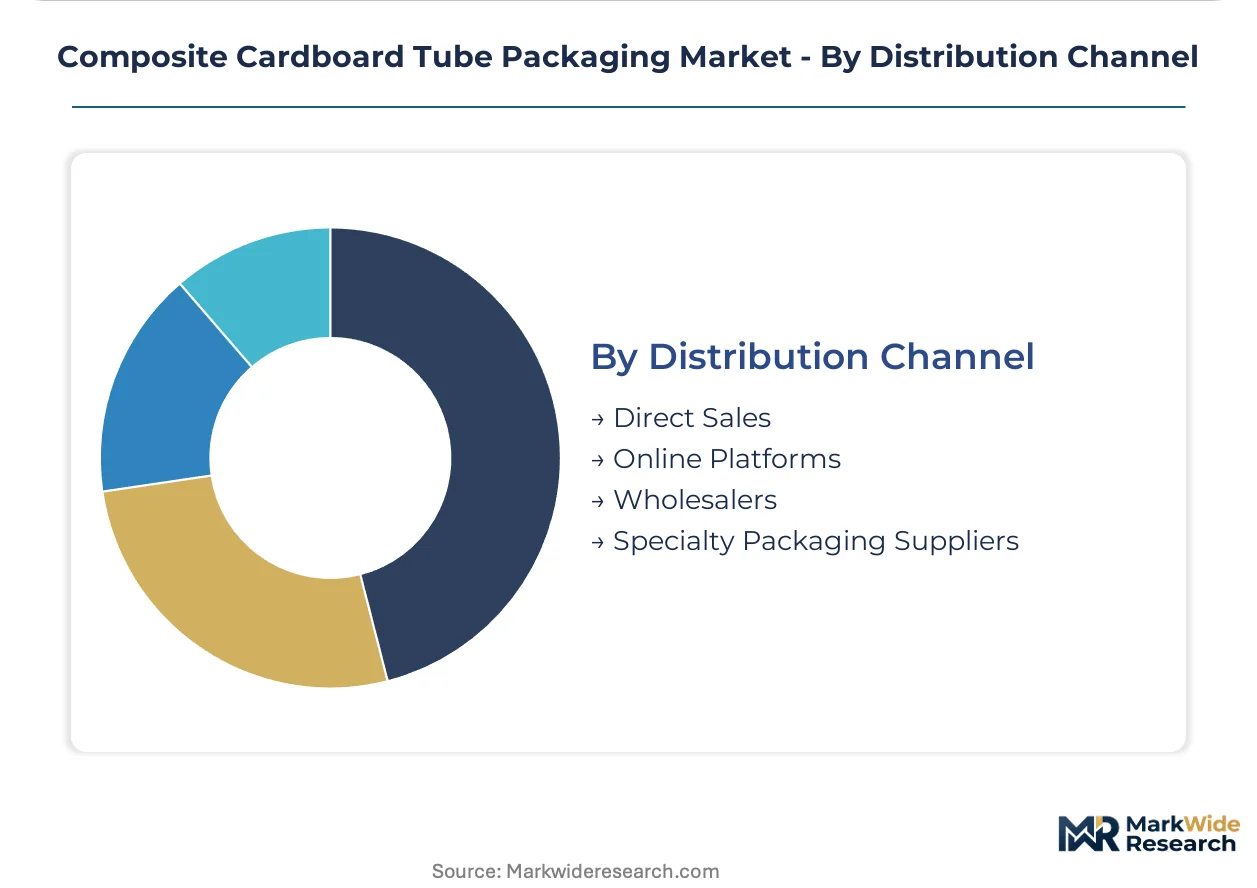
Distribution Channel:
Different distribution channels cater to varying customer types, from large-scale industrial buyers to smaller, specialized brands, influencing sales strategies and logistical approaches.
- Direct Sales:Manufacturers engage directly with large enterprise clients, offering customized solutions, bulk purchasing options, and dedicated technical support. This channel is crucial for securing major contracts with multinational food and beverage companies like Sonoco's clients.
- Online Platforms:Digital marketplaces and e-commerce sites provide accessibility for smaller brands and niche product manufacturers seeking flexible ordering and a wider selection of standard or semi-custom packaging. This channel supports emerging brands in the cosmetics sector.
- Wholesalers:These intermediaries purchase composite tubes in bulk from manufacturers and distribute them to a broad network of retailers and smaller businesses.
- Specialty Packaging Suppliers:These suppliers focus on bespoke packaging solutions, often serving luxury goods and high-end cosmetics brands with unique design and material requirements.
Strategic distribution channels enable manufacturers to reach diverse client bases, from large enterprises to niche brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The composite cardboard tube packaging market exhibits a complex regional dynamic, with significant production concentrated in established industrial economies while consumption drivers emerge across diverse geographies. Developed markets prioritize sustainable solutions and premium aesthetics, contrasting with emerging economies focused on expanding packaged goods access. This creates varied compliance landscapes and material requirements for manufacturers globally.
Germany
Demand for premium, sustainable packaging from the cosmetics and personal care sector drives market activity. Germany's Packaging Act (VerpackG) mandates high recyclability rates, influencing material choices for composite tubes. Manufacturers in the Rhine-Ruhr region actively innovate polyethylene-free linings to meet these stringent environmental standards.
United States
The cosmetics and personal care industry's focus on brand differentiation fuels demand for custom-shaped, highly decorated tubes. US FDA food-contact safety regulations guide liner and adhesive formulations for food and pharmaceutical applications. Packaging manufacturers in the Midwest are investing in advanced spiral-winding machinery to expand production capabilities.
China
Rapid expansion of the packaged food and personal care sectors creates substantial opportunities for composite tube adoption. Compliance with national GB standards for packaging is mandatory for market entry, shaping inner liner and adhesive compositions. Industrial clusters around the Yangtze River Delta focus on developing cost-effective, compliant packaging solutions for diverse consumer products.
India
A growing middle class and expanding packaged food market stimulate demand for protective and aesthetically pleasing packaging solutions. The country's national food safety regulations, enforced by FSSAI, influence barrier material specifications for composite tubes. Manufacturers in the Delhi-NCR region are enhancing production capacity for sustainable paper-based packaging.
Brazil
The large consumer products industry, particularly in food and beverage, requires robust and cost-effective packaging for market penetration. ANVISA regulations for food contact materials dictate the safety profiles of liners and adhesives used in composite tubes. Sao Paulo's industrial base develops innovative packaging designs catering to local consumer preferences and logistical challenges.
Composite Cardboard Tube Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the composite cardboard tube packaging market, creating a tiered competitive structure. The market exhibits a blend of large-scale integrated producers and niche providers catering to specific industry demands. Companies differentiate through material science innovation, bespoke design capabilities, and extensive global manufacturing footprints. Strategic partnerships and targeted acquisitions are common competitive moves to expand market reach and enhance technological offerings.
Within the global market, companies like Sonoco exemplify large-scale, diversified packaging solutions providers, leveraging extensive manufacturing networks to serve multinational clients. Smurfit Kappa, a European-based group, anchors the segment focused on sustainably sourced fiber solutions and circular economy initiatives. Visican, on the other hand, represents a specialist archetype, concentrating on bespoke, premium tubes for the cosmetics and luxury goods sectors. These entities navigate complex regulatory environments and consumer preferences to secure market share.
| Leading Market Players |
|---|
| Mondi Group |
| Visican |
| Sonoco |
| Marshall Paper Tube |
| Valk Industries |
| Smurfit Kappa |
| CBT Packaging |
| Chicago Paper Tube |
| Ace Paper Tube |
| Others |
Cost & Logistics Intelligence
Germany's stringent Packaging Act (VerpackG) mandates high recyclability rates, compelling composite tube manufacturers to invest in polyethylene-free linings. This regulatory demand significantly influences production costs and ultimately shapes market pricing.
Pricing Analysis
Margin tightening in the composite cardboard tube market reflects raw material cost volatility for aluminum foil and specialty barrier polymers. Pricing primarily follows a contract-based long-term offtake model for large enterprise clients, while smaller brands utilize per-unit transactional pricing. Price differentiation stems from customization level for luxury goods and the specific barrier performance required for food applications. Cost-sensitive food segments exhibit higher price sensitivity compared to the premium cosmetics and luxury sectors.
Supply Chain Analysis
Kraft paper and specialty barrier polymer supply relies on global chemical producers and paper mills, with significant manufacturing concentrated in China, Germany, and the United States. Aluminum foil supply, crucial for high-barrier tubes, introduces commodity price volatility as a structural risk. Distribution runs through direct sales for large multinational clients and online platforms for emerging cosmetics brands. Wholesalers and specialty packaging suppliers also facilitate market access for diverse customer bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The composite cardboard tube market navigates a technology-transition phase, moving from traditional polyethylene-lined structures to polyethylene-free, recyclable paper-based linings. This shift redefines product capabilities and market access for sensitive categories.
For Market Incumbents:
Hedge against substitution from flexible packaging by accelerating investment in polyethylene-free barrier technology and dispersible adhesives. Incumbents should expand their global manufacturing footprint, particularly in Southeast Asian markets, to serve emerging packaged food demand. Securing long-term contracts for specialty barrier polymers and kraft paper can mitigate raw material cost volatility. This dual strategy reinforces market position against regulatory and competitive pressures.
For New Entrants and Emerging Players:
EU Single-Use Plastic Directives in Europe open a window for new entrants specializing in fully recyclable, paper-based composite tubes. Target the high-value pharmaceutical and nutraceutical markets requiring advanced barrier protection against moisture and oxygen. Focus on bespoke, custom-shaped tube designs for luxury cosmetics brands seeking premium aesthetics and differentiation. A go-to-market strategy emphasizing certified recyclability and unique brand presentation will attract niche clients.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking specialized firms with advanced barrier technology intellectual property or unique custom-shaping capabilities. Long-term viability remains strong, driven by persistent consumer and regulatory pressure for sustainable packaging solutions over the next decade. Identify companies with proven expertise in polyethylene-free linings compliant with US FDA and EU REACH standards. Widespread adoption of fully recyclable composite tubes by major consumer packaged goods brands is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Polyethylene-Free Linings | Enables compliance with stringent environmental regulations, expanding market access for sensitive products. |
| Expand Custom-Shaped Tube Production | Caters to premium cosmetics and luxury goods sectors, enhancing brand differentiation and shelf appeal. |
| Secure Long-Term Raw Material Contracts | Mitigates cost volatility for aluminum foil and specialty polymers, stabilizing production margins. |
| Target Pharmaceutical Market Entry | Leverages advanced barrier technologies to penetrate high-value segments requiring superior product protection. |
| Establish Manufacturing in Southeast Asia | Capitalizes on rapid growth in packaged food and personal care sectors within underpenetrated emerging markets. |
Research Approach
Multi-period observation of material science advancements and regulatory shifts anchored the trend analysis, supplemented by interviews with packaging engineers, brand managers, and material science researchers. This primary research was validated against secondary sources including industry association reports, regulatory body publications from US FDA and EU REACH, and relevant trade journals. A combination of bottom-up market sizing and top-down validation ensured comprehensive data triangulation.
An input-output matrix structured the quantitative analytical framework across the analysis window, modeling composite tube demand and supply. Segmentation dimensions included product type, material composition, end-user industry, distribution channel, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical data and projected forward using industry-specific inputs like raw material price indices and sustainable packaging adoption rates.
The model assumes a particular technology adoption path for polyethylene-free linings; alternative pathways for barrier coating development would alter the outlook. Forecasts reflect assumptions regarding raw material volatility and recycling infrastructure development. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Paper Packaging Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Foam Cups Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Plastic Toilet Paper Dispenser Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market