
 Vietnam Paper Packaging Market | 2026-2036
Vietnam Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Paper Packaging Market Analytics
E-commerce fulfillment networks is collapsing the historical dominance of traditional retail procurement cycles in Vietnam's paper packaging sector. An Phat Holdings dominates the northern manufacturing corridor with integrated blown film and paper converting lines. SCG Paper Public Company Limited anchors supply security through captive pulp sourcing from Thai plantations. Tetra Pak International S.A. differentiates via aseptic liquid carton technology licensed to dairy and beverage processors.
Vietnam paper packaging comprises containerboard, cartonboard, and specialty paper substrates engineered into protective and promotional structures through corrugation, folding, or lamination processes, typically specified by burst strength, edge crush test values, and moisture resistance ratings to preserve product integrity through tropical distribution cycles. Kraft-grade containerboard leads volume consumption across the Boxes segment as FMCG brands mandate stackable retail-ready cases. The Recyclable grade category is gaining fastest among export-oriented food processors responding to EU Green Deal due diligence requirements on packaging waste. Flexography occupies the dominant print technology position for long-run corrugated post-print applications, though Digital is displacing conventional makeready in short-run personalized e-commerce unboxing experiences.
Vietnam's Ministry of Natural Resources and Environment enforces circular economy action plans that mandate recyclability labeling and extended producer responsibility fees on packaging importers. The country's national standards body aligns GB/T migration testing protocols with regional ASEAN harmonization frameworks for food-contact paper safety. Stakeholders must monitor whether domestic recovered fiber collection infrastructure expands sufficiently to offset imported OCC price volatility before committing to brownfield capacity additions.
Market Dynamics
E-commerce fulfillment networks are compressing procurement cycles and forcing corrugated converters toward shorter-run, digitally-enabled production. The Ministry of Natural Resources and Environment's circular economy directives are simultaneously mandating substrate recyclability while imported OCC price volatility squeezes margin structures.
Growth Catalysts
- EU Green Deal due diligence:Export-oriented food processors in the Mekong Delta are accelerating adoption of recyclable-grade cartonboard to satisfy extended producer responsibility requirements on packaging waste entering European markets.
- Ho Chi Minh City logistics corridor expansion:Fulfillment center construction in Binh Duong province is absorbing containerboard volumes for protective shipping structures at rates exceeding traditional retail replenishment cycles.
- Digital print makeready elimination:Short-run personalized unboxing experiences for direct-to-consumer brands are displacing conventional flexographic plate costs and enabling batch-size-one economics.
Market Restraints
- Imported OCC price volatility:Vietnam's recovered fiber collection infrastructure remains underdeveloped, forcing dependence on fluctuating international old corrugated container markets for kraft pulp substitution.
- ASEAN harmonization lag:GB/T migration testing protocol alignment for food-contact paper safety remains incomplete, creating certification friction for converters serving cross-border dairy and beverage processors.
- Plastic flexible substitution:Blown film alternatives from integrated petrochemical complexes in Ca Mau province are capturing moisture-sensitive agricultural export applications where paper barrier properties underperform.
Strategic Opportunities
- Central Highlands underpenetration:Coffee and pepper processing cooperatives in Dak Lak province lack proximity to integrated converting capacity, creating white space for regional corrugator investment.
- Aseptic liquid carton technology convergence:Dairy processors in the northern Red River Delta are licensing barrier-coated board structures that merge paper substrate sustainability with extended shelf-life performance.
- Extended producer responsibility fee structures:The Ministry of Natural Resources and Environment's forthcoming recyclability labeling mandates will reward domestic converters with closed-loop fiber recovery systems.
Industry Challenges
- Flexographic-to-digital skill migration:Short-run digital press operation requires prepress technicians trained in variable data workflows rather than traditional plate mounting and ink viscosity management.
- Edge crush test certification timelines:Tropical distribution cycle validation for export cartonboard specifications involves extended humidity chamber testing that delays customer qualification.
- Legacy ERP integration with e-commerce order portals:Real-time inventory visibility systems for direct-to-consumer fulfillment networks conflict with batch-oriented production scheduling software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Paper Packaging Market |
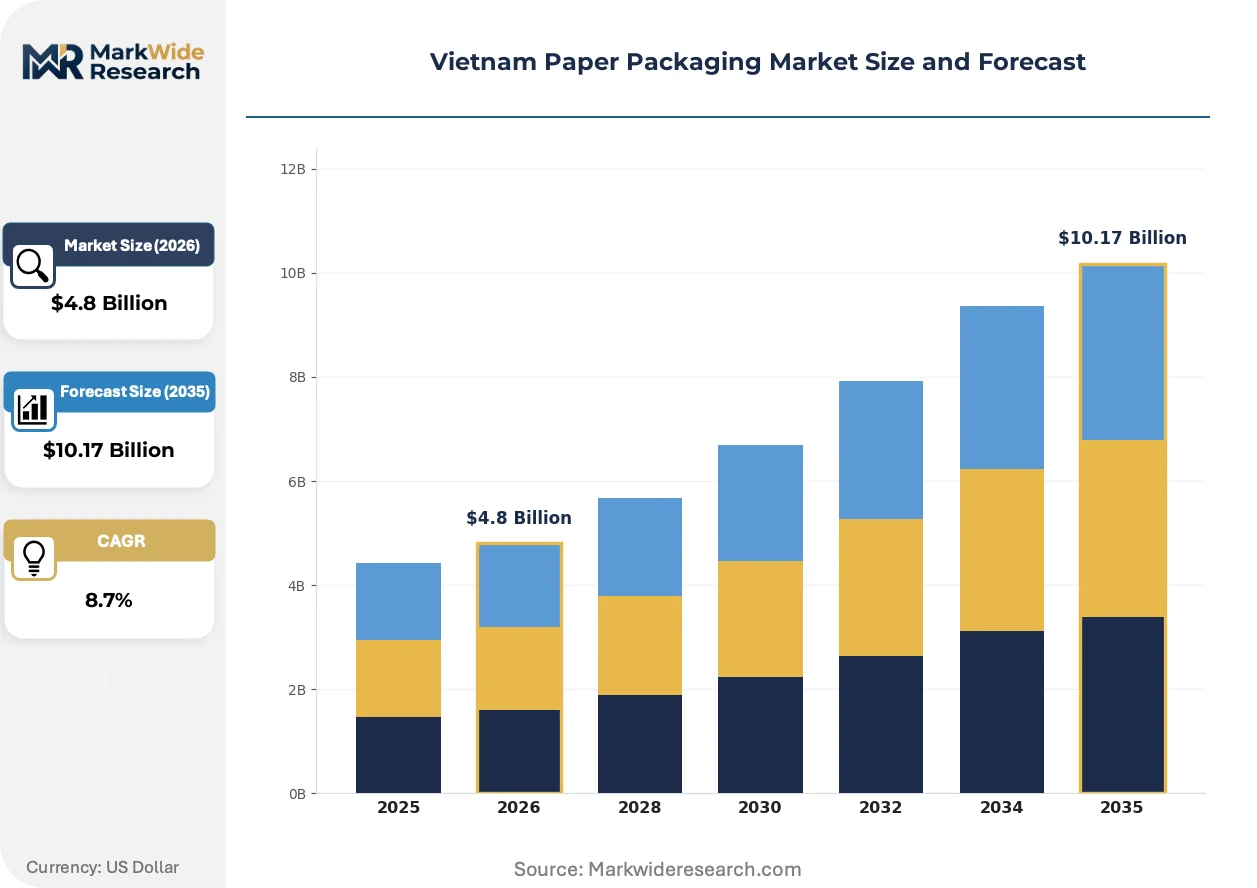
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Sheets, Wraps End User: Food & Beverage, Personal Care, Electronics, Healthcare Grade: Kraft, Recyclable, Coated, Uncoated Technology: Flexography, Rotogravure, Offset, Digital |
| Companies Covered | Starprint Vietnam Joint Stock Company, Oji Interpack Vietnam Co., Ltd, Tetra Pak International S.A., Tan Tien Packaging Company, An Phat Holdings, SCG Paper Public Company Limited, Lee & Man Paper Manufacturing Ltd., Saigon Paper Corporation, Bien Hoa Packaging Joint Stock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Paper Packaging Market Evolving Landscape
Digital production technologies and regulatory compliance frameworks are simultaneously fragmenting established manufacturing economics and procurement patterns. Three converging developments are restructuring competitive capability requirements.
Single-pass inkjet corrugated post-print systems are fragmenting the historical volume threshold separating flexographic and digital cost structures. E-commerce fulfillment networks in Binh Duong province are adopting these presses for batch-size-one unboxing personalization. The technology is fragmenting converter specialization between long-run commodity containerboard and short-run promotional case markets.
The Ministry of Natural Resources and Environment's circular economy action plans mandate recyclability labeling and extended producer responsibility fees on packaging importers. Industrial consequence includes mandatory fiber sourcing documentation and end-of-life recovery chain verification. Export-oriented food processors in the southern corridor are responding by specifying FSC-certified kraft linerboard to preempt compliance penalties.
Direct-to-consumer brands are compressing procurement cycles from quarterly replenishment to weekly demand-driven replenishment. Traditional distributor-wholesaler channels serving Ho Chi Minh City retail networks are being disintermediated by converter-direct fulfillment relationships. This pattern is most visible among cosmetic and electronics brands targeting urban millennials with personalized unboxing requirements.
Vietnam Paper Packaging Market Segmentation
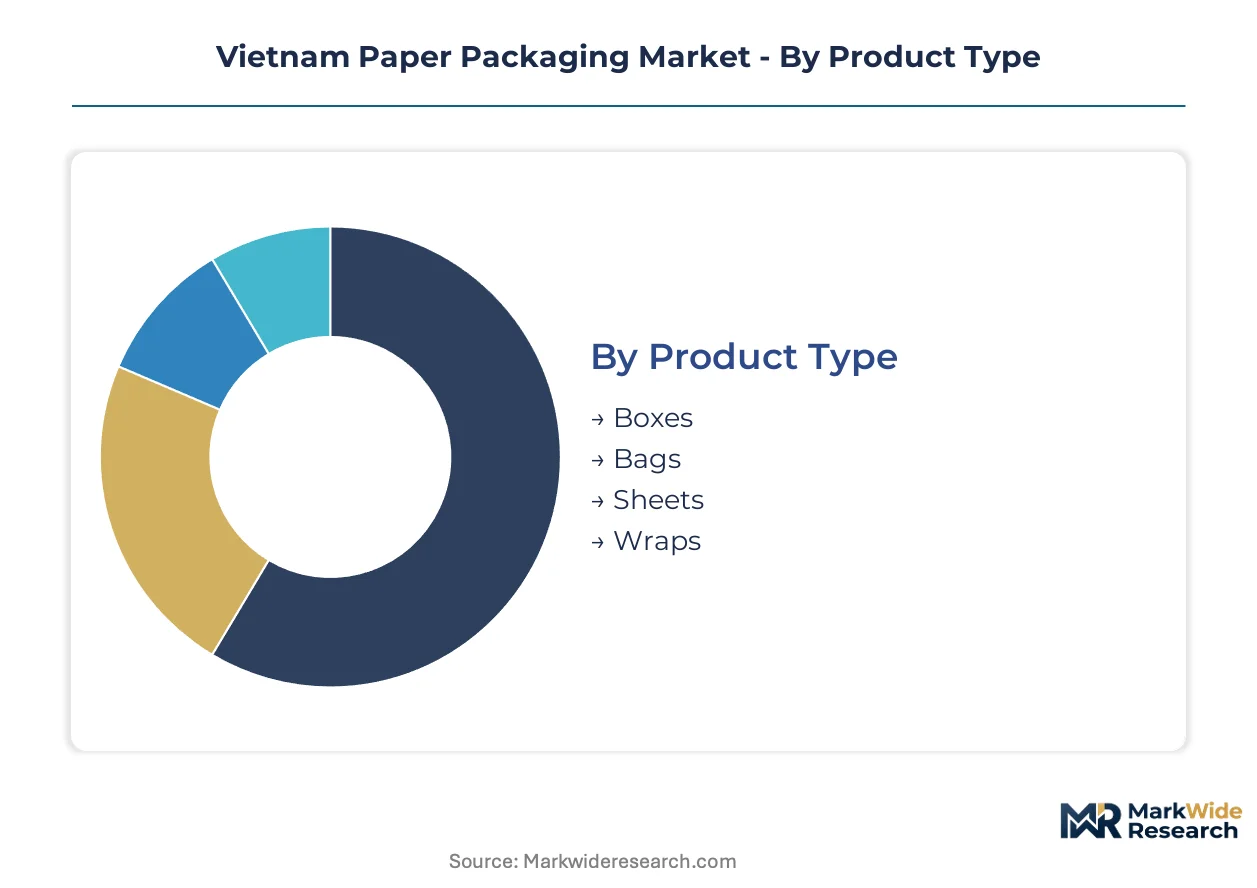
Vietnam's paper packaging segmentation reveals divergent margin structures across substrate grades and print technologies. Procurement patterns in the southern industrial corridor favor containerboard specifications tuned to tropical logistics, while northern converters optimize for aseptic liquid carton barrier performance.
Product Type:
Margin pools concentrate in protective shipping structures serving e-commerce fulfillment networks, with secondary value capture in retail-ready display formats.
- Boxes:Corrugated containerboard structures dominate volume throughput across Ho Chi Minh City logistics hubs. FMCG brands in Binh Duong province mandate stackable retail-ready cases with specified edge crush test values for tropical distribution cycles.
- Bags:Multiwall kraft constructions serve agricultural export processors in the Mekong Delta. Coffee and pepper cooperatives specify moisture-resistant pinch-bottom designs that withstand high-humidity port storage before EU-bound shipment.
- Sheets:Protective interlayer substrates separate palletized electronics components for northern Red River Delta assembly plants. Lightweight corrugated sheet demand tracks semiconductor packaging volumes through Bac Ninh province industrial zones.
- Wraps:Grease-resistant tissue and glassine structures wrap processed food items for domestic retail distribution. Quick-service restaurant chains in Da Nang specify compostable wrap grades responding to Ministry of Natural Resources and Environment circular economy directives.
Boxes holds installed capacity. Bags is rotating up the share rankings.
End User:
Application-specific barrier requirements fragment substrate specification across customer verticals, with food-contact migration testing protocols creating certification moats.
- Food & Beverage:Dairy processors license aseptic liquid carton technology for extended shelf-life UHT milk distribution. Tetra Pak International S.A. barrier-coated board structures merge paper sustainability with tropical climate performance requirements.
- Personal Care:Cosmetic brands targeting urban millennials specify digitally-printed unboxing experiences with batch-size-one personalization. Direct-to-consumer fulfillment networks in Thu Duc City compress procurement cycles from quarterly to weekly replenishment.
- Electronics:Static-dissipative corrugated structures protect semiconductor components through Bac Ninh province assembly corridors. ESD-safe containerboard specifications require conductive coating layers that elevate unit economics above commodity kraft grades.
- Healthcare:Sterile barrier systems for medical device distribution demand ISO 11607-compliant substrate validation. Pharmaceutical cold chain specifications in Hanoi prioritize moisture vapor transmission rate performance for temperature-sensitive biologics.
Food & Beverage commands specification authority. Personal Care is expanding most quickly.
Grade:
Recyclability certification tiers are reconstituting price realization across export-oriented supply chains subject to EU Green Deal due diligence.
- Kraft:Unbleached virgin fiber structures provide burst strength for heavy-duty agricultural export packaging. Ca Mau province seafood processors specify wet-strength kraft linerboard for frozen shrimp containerization through Cat Lai port.
- Recyclable:FSC-certified recovered fiber grades satisfy extended producer responsibility requirements for EU-bound food exports. Mekong Delta rice processors accelerate adoption to preempt compliance penalties under forthcoming Ministry of Natural Resources and Environment labeling mandates.
- Coated:Polyethylene-extruded barrier layers extend shelf life for moisture-sensitive snack foods. Domestic confectionery brands in Dong Nai province specify heat-sealable coated boards replacing flexible plastic alternatives.
- Uncoated:Porous fiber structures serve dry goods distribution where moisture protection is unnecessary. Bulk grain bagging operations in the Central Highlands prioritize cost minimization over barrier performance.
Kraft retains volume leadership. Recyclable is gaining share fastest.
Technology:
Print method selection hinges on run length economics, with makeready cost structures fragmenting converter specialization between commodity and promotional case markets.
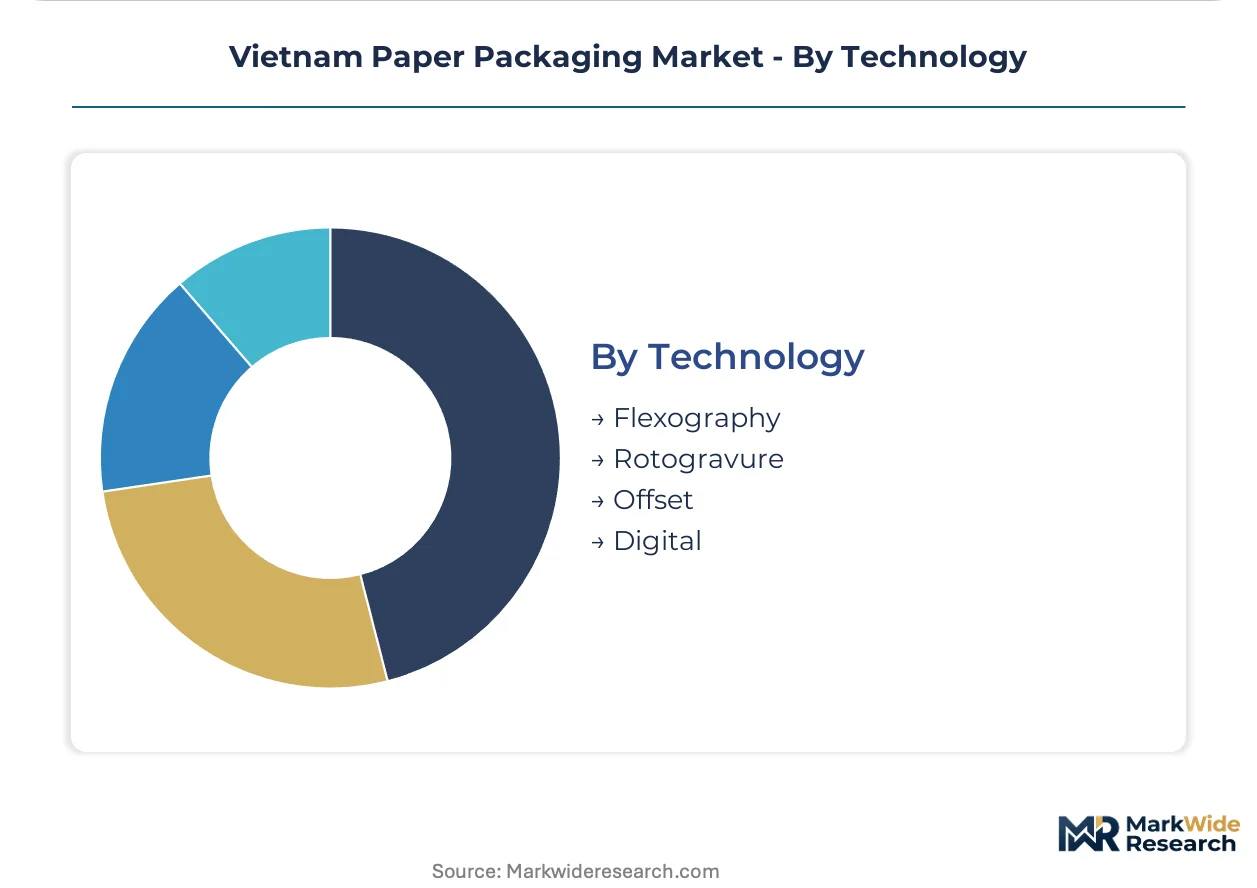
- Flexography:Anilox roller ink transfer dominates long-run corrugated post-print applications for FMCG case goods. SCG Paper Public Company Limited operates multi-color flexo lines optimized for 50,000+ unit production runs.
- Rotogravure:Cylinder-engraved high-definition reproduction serves premium cosmetic carton requirements. Halftone gravure quality justifies plate cost amortization across extended beauty brand campaigns.
- Offset:Lithographic transfer excels for folding carton applications requiring fine-line graphic reproduction. Pharmaceutical insert printing in Hanoi demands offset registration precision for multilingual regulatory text.
- Digital:Single-pass inkjet systems eliminate conventional makeready for short-run e-commerce unboxing personalization. Binh Duong province fulfillment centers adopt these presses for batch-size-one promotional case production.
Flexography holds installed capacity. Digital is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cat Lai Port's container throughput underwrites the southern corridor's dominance in Vietnam's paper packaging trade, with the Cai Mep-Thi Vai deepwater complex anchoring export-oriented converting capacity for Mekong Delta agricultural processors.
Ho Chi Minh City Metropolitan Area
E-commerce fulfillment networks in Thu Duc City compress procurement cycles from quarterly to weekly replenishment for cosmetic and electronics brands. The Ministry of Natural Resources and Environment's circular economy labeling mandates drive specification shifts toward FSC-certified kraft linerboard. Binh Duong province hosts the densest corrugator concentration, with protective shipping structures absorbing containerboard volumes at rates exceeding traditional retail channels.
Northern Red River Delta
Dairy processors in Bac Ninh and Hai Duong provinces license aseptic liquid carton technology for UHT milk distribution through tropical climate supply chains. The national standards body aligns GB/T migration testing protocols with ASEAN harmonization frameworks for food-contact paper safety. Hanoi pharmaceutical cold chain specifications prioritize moisture vapor transmission rate performance for temperature-sensitive biologics packaging.
Central Highlands
Coffee and pepper processing cooperatives in Dak Lak province lack proximity to integrated converting capacity, creating white space for regional corrugator investment. Provincial agricultural extension programs promote moisture-resistant pinch-bottom bag designs for high-humidity port storage. Pleiku and Buon Ma Thuot industrial zones remain underpenetrated by containerboard distribution networks serving EU-bound agricultural exports.
Mekong Delta
Seafood processors in Ca Mau province specify wet-strength kraft linerboard for frozen shrimp containerization through Cat Lai port. Rice exporters accelerate adoption of recyclable-grade cartonboard to preempt EU Green Deal due diligence penalties. Can Tho logistics hubs fragment procurement patterns between traditional distributor-wholesaler channels and converter-direct fulfillment relationships.
Central Coast Corridor
Da Nang quick-service restaurant chains specify compostable wrap grades responding to Ministry of Natural Resources and Environment circular economy directives. Electronics assembly plants in Quang Nam province demand static-dissipative corrugated structures for semiconductor component protection. The East-West Economic Corridor highway linkage funnels containerboard from northern mills toward central region distribution points.
Vietnam Paper Packaging Market Competitive Landscape
Concentration sits with integrated pulp-to-converter conglomerates and regional specialists holding captive southern corridor logistics access. Three archetypes populate the competitive terrain: Thai-backed plantation-integrated operators with captive fiber security, northern Vietnamese blown film and paper hybrid manufacturers, and international technology licensors with aseptic barrier expertise. Dominant competitive moves include strategic partnerships with e-commerce fulfillment networks and geographic expansion into Central Highlands agricultural processing zones.
Among Thai-integrated operators, SCG Paper Public Company Limited exemplifies captive pulp sourcing from plantation assets. Tetra Pak International S.A. occupies the technology-licensor archetype through aseptic liquid carton barrier systems. An Phat Holdings represents northern manufacturing corridor integration across blown film and paper converting lines. Starprint Vietnam Joint Stock Company and Oji Interpack Vietnam Co., Ltd anchor mid-tier specialist positions serving FMCG brand specifications.
| Leading Market Players |
|---|
| Starprint Vietnam Joint Stock Company |
| Oji Interpack Vietnam Co., Ltd |
| Tetra Pak International S.A. |
| Tan Tien Packaging Company |
| An Phat Holdings |
| SCG Paper Public Company Limited |
| Lee & Man Paper Manufacturing Ltd. |
| Saigon Paper Corporation |
| Bien Hoa Packaging Joint Stock Company |
| Others |
Value Network & Pricing Analysis
Imported old corrugated container substitution for domestic recovered fiber simultaneously concentrates supply geography around Thai plantation pulp and compresses converter margins through OCC price volatility. This input substitution dynamic forces Vietnamese converters toward long-term offtake contracts with SCG Paper Public Company Limited while spot-market buyers absorb margin erosion from international fiber price swings.
Pricing Analysis
Three-tier pricing structure across FSC-certified premium, standard recyclable, and economy kraft grades dominates contract negotiations. Price differentiation hinges on certification tier and volume scale, with EU-bound food processors paying premiums for documented fiber chain-of-custody. Pricing pressure stems from imported OCC cost compression in the standard tier, where Mekong Delta rice exporters exhibit highest price sensitivity. Dairy processors in the northern corridor show lowest sensitivity, prioritizing aseptic barrier performance over unit cost.
Supply Chain Analysis
Thailand and Indonesia anchor regional pulp supply through plantation-integrated operations, while Vietnam's domestic converting capacity clusters in Binh Duong province. Raw material dependencies center on imported kraft linerboard, barrier-coated board substrates, and water-based flexographic inks. Single-source vulnerability concentrates in Thai plantation pulp controlled by integrated conglomerates. Distribution runs through Cat Lai Port container terminals serving Ho Chi Minh City logistics hubs, with secondary nodes at Cai Mep-Thi Vai deepwater complex.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short-run digital press operation capability sits in acute scarcity against compressed e-commerce procurement cycles, creating asymmetric returns for converters bridging this skill gap. The market rewards operational agility over legacy scale.
For Market Incumbents: Compound defensive positioning through captive fiber recovery infrastructure in southern industrial corridors and digital press fleet expansion for batch-size-one economics. Blown film substitution from Ca Mau petrochemical complexes threatens moisture-sensitive agricultural applications. Backward integration into domestic OCC collection networks secures margin insulation against imported fiber volatility. For New Entrants and Emerging Players: Lead with Central Highlands corrugator investment targeting Dak Lak coffee cooperative packaging demand, where containerboard distribution networks remain underdeveloped. The most penetrable segment sits in moisture-resistant pinch-bottom bag specifications for EU-bound pepper exports. A converter-direct fulfillment model bypassing traditional distributor-wholesaler channels captures procurement cycle compression value. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier specialists with regional logistics access and FSC certification infrastructure already in place. Long-term viability over the coming decade rests on circular economy compliance capability rather than commodity scale. The signal to watch is Ministry of Natural Resources and Environment enforcement timing on extended producer responsibility fee implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Press Fleet Expansion | Single-pass inkjet adoption in Binh Duong fulfillment centers enables batch-size-one unboxing personalization economics. |
| Captive Fiber Recovery Infrastructure | Domestic OCC collection networks in Ho Chi Minh City industrial zones offset imported fiber price volatility exposure. |
| FSC Certification Investment | Chain-of-custody documentation satisfies EU Green Deal due diligence for Mekong Delta food exporters. |
| Central Highlands Capacity Buildout | Regional corrugator placement in Dak Lak province closes proximity gap for coffee and pepper processing cooperatives. |
| Aseptic Barrier Technology Licensing | Tetra Pak International S.A. partnerships with Red River Delta dairy processors merge paper sustainability with tropical shelf-life performance. |
Research Methodology
A standing panel of corrugated plant managers, e-commerce fulfillment procurement leads, dairy packaging engineers, and Ministry of Natural Resources and Environment compliance officers provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from customs trade records, Vietnam Paper Association production statistics, EU Green Deal regulatory filings, and ASEAN harmonization framework documents. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across substrate grades and print technologies.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled segmentation dimensions including substrate grade tier, end-use vertical, print technology, and regional logistics corridor. CAGRs derived from trend extrapolation of e-commerce fulfillment network expansion rates and circular economy regulatory enforcement trajectories. Forecast inputs incorporated tropical distribution cycle validation timelines and digital press adoption curves in Binh Duong province.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth or accelerated EU due diligence enforcement would require recalibration. Forecasts reflect assumptions on OCC import price stability and ASEAN harmonization completion timing. Specific risks that could revise projections include Ministry of Natural Resources and Environment labeling mandate acceleration and Thai plantation pulp supply disruption. Recalibration cycles align with material shifts in circular economy regulatory implementation and e-commerce fulfillment network geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
South Korea Paper Packaging Market
Paper & Paperboard Packaging
Food Wrapping Paper Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Paper Bag Box Market