
 Urinary Tract Infection (UTI) Treatment Market | 2026-2036
Urinary Tract Infection (UTI) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Tract Infection (UTI) Treatment Market Intelligence
A shift toward multi-sourcing of antibiotic active pharmaceutical ingredients is broadening supply chain resilience for drug manufacturers. This strategy mitigates risks associated with single-point failures in production. Pfizer leverages its extensive manufacturing network to ensure a stable supply of established antibiotic therapies. In contrast, F. Hoffmann-La Roche specializes in developing novel diagnostics and targeted treatments for complicated UTIs, differentiating through innovation rather than scale alone.
Urinary tract infection treatment involves therapeutic agents designed to eliminate pathogenic bacteria like Escherichia coli. These drugs typically function by disrupting bacterial cell wall synthesis or inhibiting DNA replication processes. While antibiotics represent the core product type, preventative options like probiotics are gaining share. The choice of delivery mode is critical, with oral administration dominating outpatient settings and intravenous solutions being essential for treating complicated infections within hospitals.
Regulatory frameworks established by the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) govern the approval pathways for new anti-infective drugs. These agencies mandate rigorous clinical trials to prove safety and efficacy against resistant pathogens. National bodies such as India's CDSCO further implement antibiotic stewardship guidelines to curb misuse. Future success depends on balancing investment in novel drug discovery with effective lifecycle management for existing antibiotic classes.
Market Dynamics
The central tension shaping the urinary tract infection treatment market is the dual pressure of advancing antibiotic stewardship to combat resistance while simultaneously innovating new therapies for increasingly prevalent multi-drug resistant pathogens. This dynamic forces a bifurcation in strategy between managing existing drug lifecycles and high-risk, high-reward novel drug discovery.
Growth Catalysts
- Regulatory Incentives:The FDA's Qualified Infectious Disease Product (QIDP) designation provides fast-track review and extended market exclusivity, directly stimulating investment into novel antibiotics and antifungals for treating complicated UTIs.
- Aging Demographics:Countries with rapidly aging populations, particularly Japan and Germany, are experiencing a higher incidence of catheter-associated and complicated UTIs, expanding the core patient base for advanced intravenous therapies in hospital settings.
- Non-Antibiotic Therapies:The development of alternative treatments, including vaccines and bacteriophage therapies, is creating new product categories that address the unmet need for managing recurrent infections without contributing to antibiotic resistance.
Market Restraints
- Clinical Trial Hurdles:Rigorous efficacy and safety benchmarks mandated by regulatory bodies like the EMA for new anti-infectives lead to long and expensive clinical development timelines, deterring investment in the antibiotic pipeline.
- Substitution by Preventatives:Increasing consumer and clinician preference for non-prescription options, such as probiotics and cranberry-based supplements for UTI prevention, reduces the addressable market for first-line antibiotic treatments for uncomplicated cases.
- Limited Return on Investment:Antibiotic stewardship programs, while medically necessary, restrict the use of novel, powerful antibiotics to last-resort scenarios, severely limiting sales volume and making it difficult for manufacturers to recoup R&D expenditures.
Strategic Opportunities
- Microbiome-Based Therapeutics:A significant opportunity exists in developing therapies that modulate the urinary microbiome to prevent recurrent infections, creating a new market for long-term preventative care beyond acute treatment.
- AI-Powered Diagnostics:The convergence of artificial intelligence with rapid diagnostic tools can enable highly specific pathogen identification, creating demand for targeted therapies and supporting personalized medicine approaches to UTI management.
- Emerging Market Expansion:Improving healthcare infrastructure and rising disposable incomes in large markets like Brazil and India present an opportunity to expand access to second-line and branded generic antibiotics for complicated UTIs.
Industry Challenges
- Stewardship Guideline Fragmentation:Manufacturers face operational complexity in navigating disparate antibiotic stewardship guidelines across different national health systems, such as those implemented by India's CDSCO versus policies in the European Union.
- Biologic Supply Chain Development:The shift towards biologics and phage therapies requires building new cold-chain logistics and specialized manufacturing capabilities, a significant capital challenge compared to traditional small-molecule antibiotic production.
- Intellectual Property Defense:Securing and defending patents for novel mechanisms of action, particularly in the competitive field of bacteriophage cocktails and microbiome modulators, presents a continuous legal and financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Tract Infection (UTI) Treatment Market |
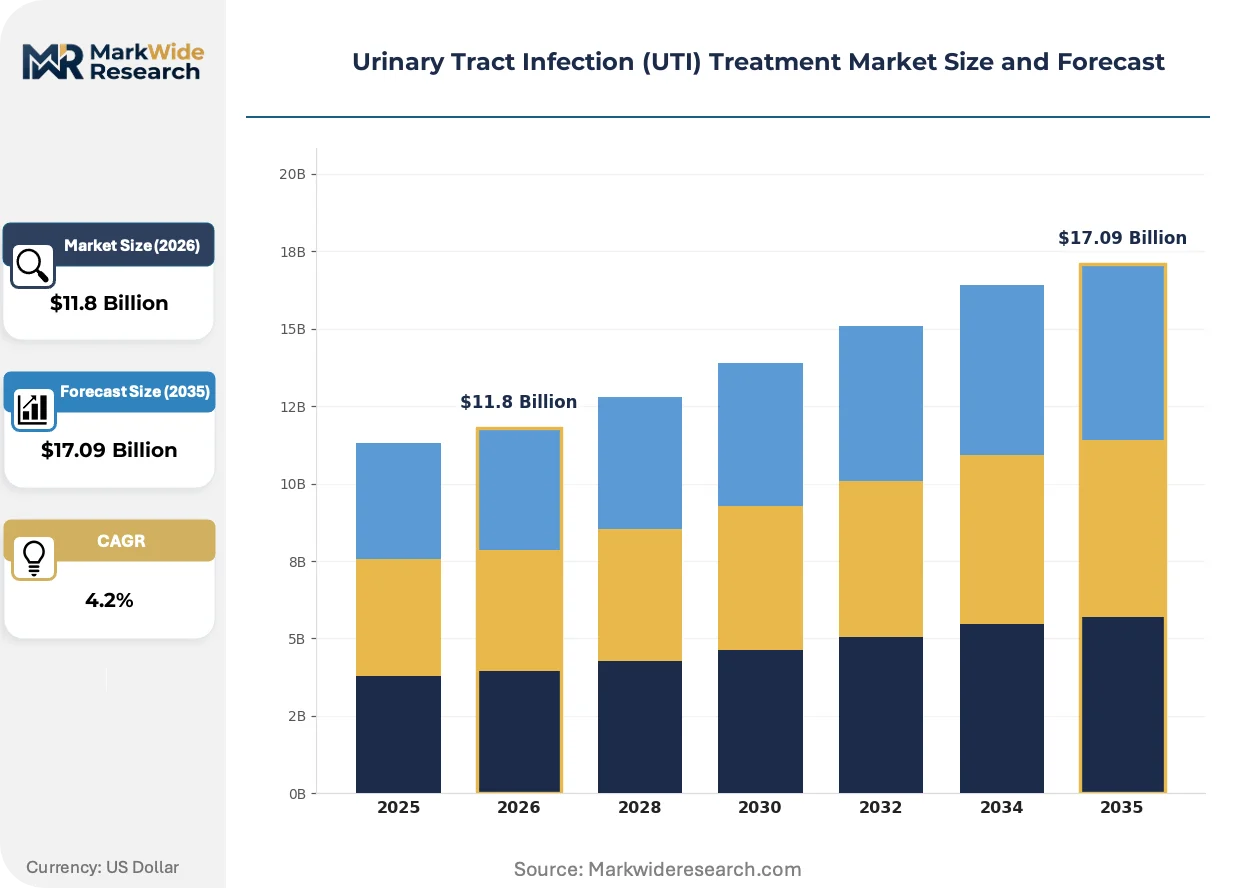
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.09 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Cranberry Extracts, Probiotics Delivery Mode: Oral, Intravenous, Topical, Herbal End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Retail, Online, Wholesalers, Drug Stores |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., AbbVie Inc., F. Hoffmann-La Roche Ltd., GlaxoSmithKline Plc, AstraZeneca Plc, Johnson & Johnson, Bayer AG, Cipla Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Tract Infection (UTI) Treatment Market Strategic Shifts & Innovations
Precision medicine and preventative strategies are fundamentally altering the UTI treatment landscape. The market is moving away from a reliance on broad-spectrum antibiotics toward targeted, pathogen-specific interventions and non-antibiotic solutions that address the root causes of recurrence and resistance.
Bacteriophage therapy utilizes viruses to specifically target and lyse pathogenic bacteria, such as resistant strains of E. coli. Specialized biotechnology firms and academic centers are advancing its use in compassionate care and clinical trials for multi-drug resistant infections. This approach is modularizing treatment, enabling the assembly of personalized phage cocktails to neutralize unique bacterial profiles that have evolved beyond the reach of conventional antibiotics.
The European Medicines Agency's adaptive pathways framework offers a route for earlier patient access to drugs addressing high unmet medical needs. This regulatory pathway accelerates development timelines for novel anti-infectives by allowing for iterative data submission and approval based on accumulating evidence. Drug developers focused on therapies for complicated UTIs caused by resistant pathogens are most affected, redesigning clinical programs to align with this flexible, evidence-gathering model.
A notable shift in purchasing models is moving from per-unit sales toward subscription-based access for healthcare systems, particularly for last-resort antibiotics. This "Netflix model," piloted in countries like the United Kingdom, decouples manufacturer revenue from sales volume, creating a stable market for critical drugs while removing the incentive to overuse them. This trend is most prominent within nationalized health systems seeking to secure their antibiotic arsenal against future resistance threats.
Urinary Tract Infection (UTI) Treatment Market Segmentation
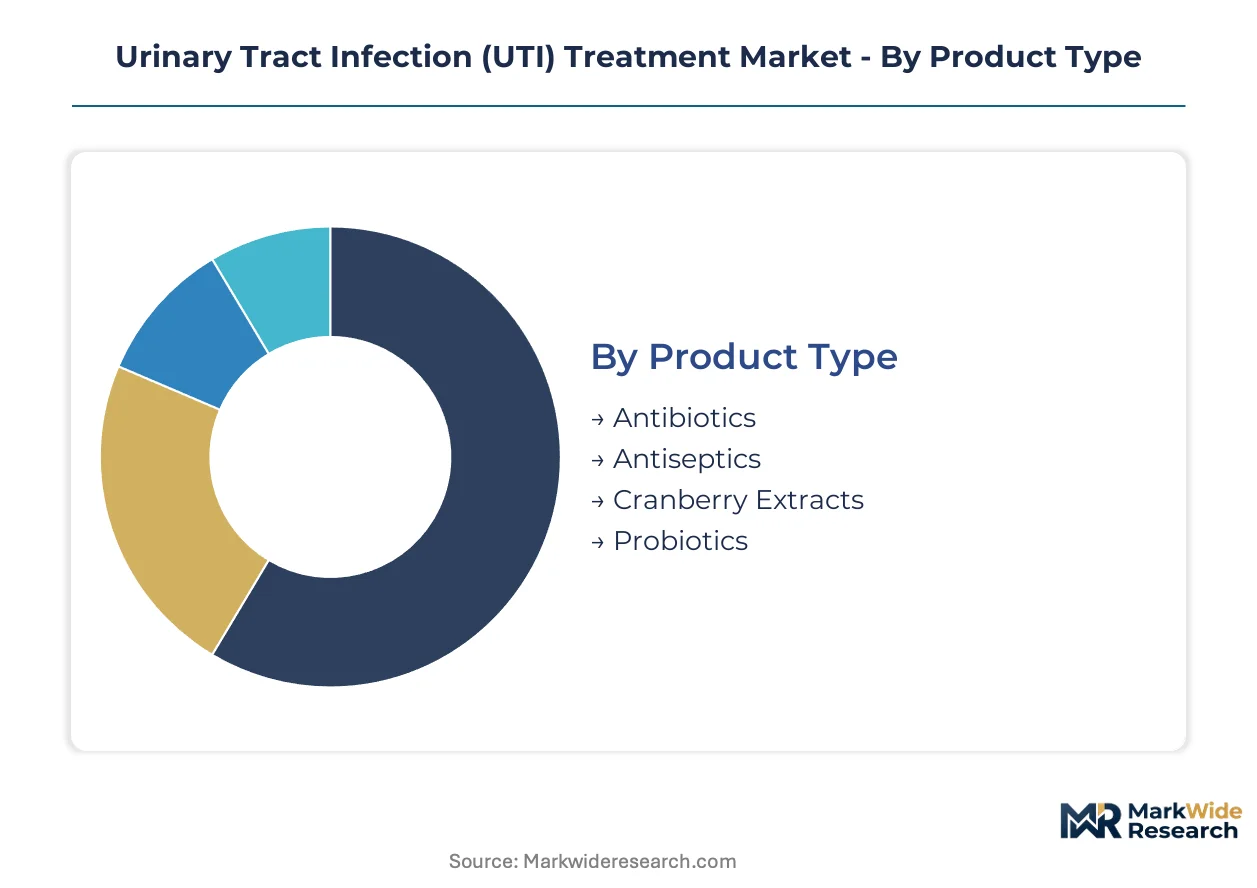
The urinary tract infection treatment market segments across various dimensions, reflecting the diverse approaches to managing bacterial pathogens. Understanding these categories is crucial for drug manufacturers and healthcare providers to tailor interventions and optimize resource allocation. This granular view highlights areas of unmet need and commercial opportunity.
Product Type:
Product type segmentation reveals the spectrum from standardized broad-spectrum agents to highly customized non-antibiotic solutions addressing specific patient needs.
- Antibiotics:These therapeutic agents target bacterial cell wall synthesis or DNA replication, forming the core of UTI treatment. Demand concentrates in hospital settings for complicated UTIs, driven by the need for rapid eradication of resistant pathogens.
- Antiseptics:These agents inhibit microbial growth, often used topically or in urinary tract washes to reduce bacterial load.
- Cranberry Extracts:Derived from cranberries, these supplements are utilized for their anti-adhesion properties, preventing bacterial attachment to the urinary tract lining.
- Probiotics:Probiotic formulations introduce beneficial microorganisms to restore microbial balance, particularly in preventative care for recurrent UTIs. Demand is gaining share in outpatient settings, driven by consumer preference for non-prescription preventative options in countries like Germany.
Most installed capacity flows through Antibiotics. Expansion is steepest in Probiotics.
Delivery Mode:
Delivery mode segmentation highlights how treatment administration adapts to varying infection severities and patient care environments.
- Oral:Medications administered by mouth offer convenience and are the primary route for outpatient treatment of uncomplicated UTIs. This mode dominates in primary care settings across countries like India and Brazil, facilitating broad patient access.
- Intravenous:Solutions delivered directly into the bloodstream ensure rapid systemic distribution, essential for severe and complicated infections. Utilization is concentrated in hospital settings, especially for managing complicated UTIs in aging populations in Japan and Germany.
- Topical:Applied directly to the affected area, topical formulations provide localized treatment, minimizing systemic exposure.
- Herbal:Derived from plant sources, herbal remedies are used for their perceived natural properties in managing UTI symptoms or prevention.
Oral administration commands the largest volume of treatments, while intravenous solutions often represent higher value per dose due to complexity.
End User:
End user segmentation categorizes the primary healthcare facilities and consumer environments where UTI treatments are administered or acquired.
- Hospitals:These institutions manage severe, complicated, and recurrent UTIs, often requiring intravenous antibiotics and advanced diagnostics. Demand is high in regions with aging demographics, such as Germany, for managing catheter-associated infections and multi-drug resistant cases.
- Clinics:Outpatient clinics provide initial diagnosis and treatment for uncomplicated UTIs, primarily utilizing oral antibiotic regimens.
- Home Care:Patients manage less severe UTIs or preventative regimens at home, often involving oral medications or non-antibiotic therapies. This segment is expanding due to a preference for convenience and the availability of over-the-counter preventative options like probiotics.
- Pharmacies:Pharmacies serve as access points for prescribed antibiotics and a range of over-the-counter preventative supplements for UTIs.
Treatment of complicated infections concentrates within hospitals, while preventative and uncomplicated care is increasingly decentralized to home care settings.
Distribution Channel:
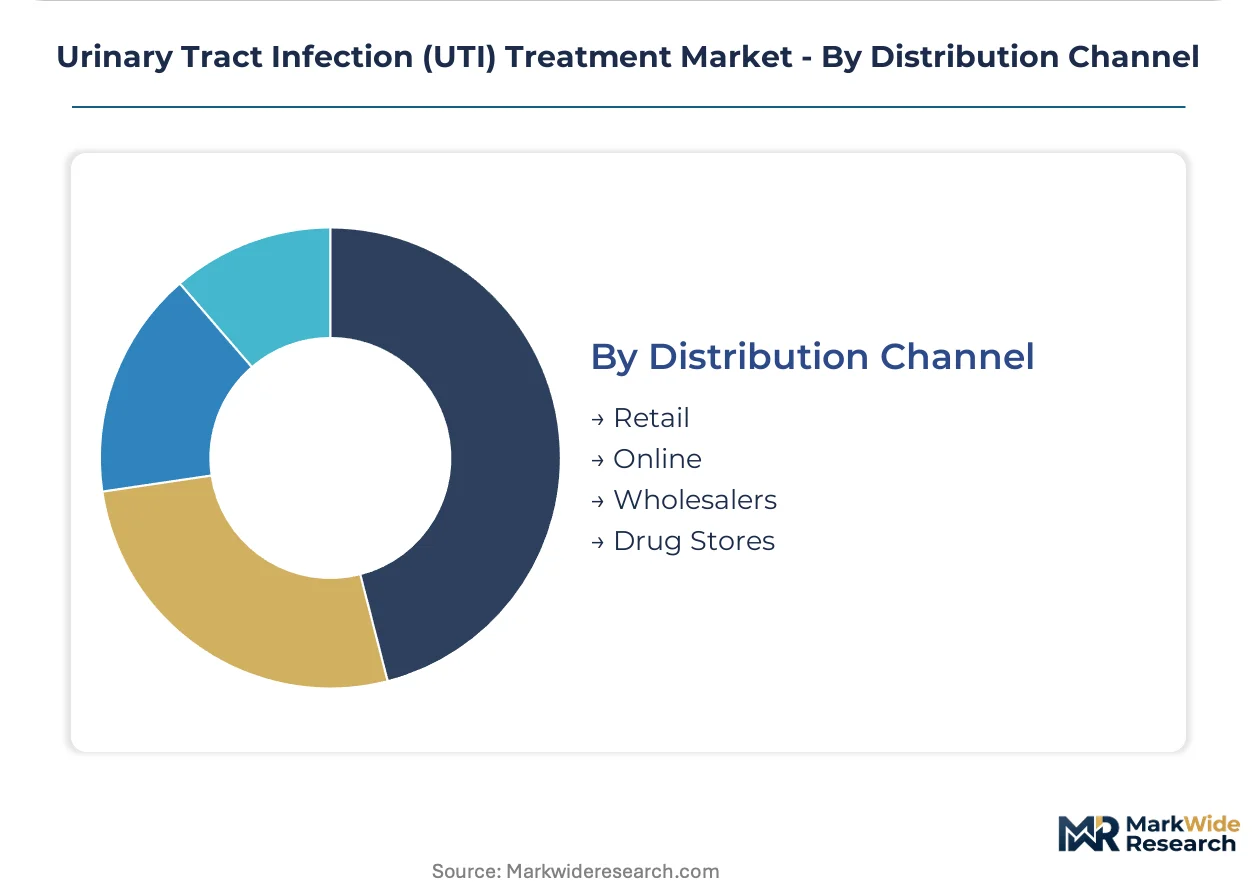
Distribution channel segmentation illustrates the varied pathways through which UTI treatment products reach end-users and healthcare providers.
- Retail:This channel includes traditional brick-and-mortar pharmacies and supermarkets, providing direct consumer access to prescription and OTC products. Retail distribution remains strong for established antibiotic therapies and preventative supplements in markets with robust physical infrastructure.
- Online:E-commerce platforms and digital pharmacies facilitate convenient purchasing of both prescription and non-prescription UTI treatments. This channel is experiencing rapid growth, particularly for preventative options and discreet delivery, appealing to younger demographics globally.
- Wholesalers:Wholesalers serve as intermediaries, supplying large volumes of pharmaceutical products to hospitals, clinics, and retail pharmacies.
- Drug Stores:These specialized retail outlets offer a focused range of prescription and over-the-counter medications, including UTI treatments.
The efficiency of supply chains for institutional procurement depends on wholesalers, while direct consumer access is increasingly driven by online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States biopharmaceutical hub drives significant investment into novel UTI therapies, shaping global innovation. Demand for advanced formulations is particularly strong in countries with aging demographics, including Germany and Japan. Emerging markets like India and Brazil are expanding access to essential treatments, influencing regional supply dynamics.
United States
Strong regulatory incentives, such as the FDA's Qualified Infectious Disease Product (QIDP) designation, stimulate investment in novel anti-infectives. These policies accelerate development timelines for treatments addressing multi-drug resistant pathogens. Biotech clusters in Boston and the San Francisco Bay Area lead research into new antibiotic classes and non-antibiotic modalities.
Germany
Germany's aging population contributes to a higher incidence of complicated and catheter-associated UTIs, increasing demand for advanced intravenous therapies. The European Medicines Agency (EMA) sets rigorous efficacy and safety benchmarks for new anti-infectives in the region. Pharmaceutical research centers in Munich and Frankfurt focus on developing targeted treatments for hospital-acquired infections.
Japan
Japan experiences a high prevalence of complicated UTIs among its rapidly aging demographic, creating a consistent need for specialized treatments. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates the approval and market access of new therapeutic agents. Major pharmaceutical manufacturing hubs in Tokyo and Osaka ensure a stable supply of established and advanced UTI medications.
India
Improving healthcare infrastructure and rising disposable incomes in India expand access to second-line and branded generic antibiotics for complicated UTIs. India's Central Drugs Standard Control Organization (CDSCO) implements antibiotic stewardship guidelines to curb misuse. Pharmaceutical production centers in Hyderabad and Bengaluru are critical for manufacturing affordable oral and injectable anti-infectives.
Brazil
Brazil's growing healthcare sector and increasing patient awareness drive demand for both oral and intravenous UTI treatments. The National Health Surveillance Agency (ANVISA) oversees the regulation and approval of pharmaceutical products within the country. Major urban centers like São Paulo serve as key distribution points for UTI medications and diagnostic tools.
Urinary Tract Infection (UTI) Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue non-antibiotic therapies and advanced diagnostics. The market structure exhibits a tiered consolidation, with large pharmaceutical companies dominating the antibiotic segment while smaller biotech firms innovate in niche areas. Strategic partnerships for drug discovery and geographic expansion into underserved markets represent dominant competitive moves.
Within the established pharmaceutical tier, Pfizer Inc. and Merck & Co. Inc. anchor the supply of foundational antibiotic therapies, leveraging extensive manufacturing networks. F. Hoffmann-La Roche Ltd. exemplifies a different strategic vector, specializing in novel diagnostics and targeted treatments for complicated UTIs. These companies collectively influence pricing and market access for a significant portion of the global UTI treatment landscape.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| AbbVie Inc. |
| F. Hoffmann-La Roche Ltd. |
| GlaxoSmithKline Plc |
| AstraZeneca Plc |
| Johnson & Johnson |
| Bayer AG |
| Cipla Inc. |
| Others |
Cost & Logistics Intelligence
Specialized pharmaceutical research talent concentrated in biotech hubs like Boston and the San Francisco Bay Area influences the premium pricing of novel anti-infective therapies, creating distinct pricing tiers for advanced treatments versus established generics.
Pricing Analysis
Input-cost pass-through significantly impacts pricing for generic antibiotics, where multi-sourcing of active pharmaceutical ingredients creates competitive pressure. The dominant pricing structure is a hybrid, combining per-unit transactional sales for established antibiotics with value-based agreements for novel biologics. Regulatory approval, such as the FDA's QIDP designation, and unique mechanisms of action drive price differentiation for innovative treatments. Pricing stability remains robust for novel drugs addressing unmet medical needs, while older generic antibiotics face ongoing cost compression due to increased supply chain resilience. Hospitals managing complicated infections exhibit less price sensitivity for advanced therapies compared to outpatient settings procuring first-line generic treatments.
Supply Chain Analysis
Certification and qualification gating by regulatory bodies like the EMA and FDA heavily influences the pharmaceutical supply chain for UTI treatments, dictating standards for sterile manufacturing facilities. Geographic supply concentration for active pharmaceutical ingredients centers on India for generics and China for intermediates, while novel biologics manufacturing often occurs in the US and Europe. The supply chain depends on critical raw materials such as antibiotic active pharmaceutical ingredients and specialized bioreactor components for advanced therapies. Single-source vulnerability for complex, novel biologics represents a key structural risk. Distribution runs through wholesalers for institutional procurement by hospitals and retail pharmacies for outpatient oral medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary tract infection treatment market is evolving into a late-cycle quality story, driven by a demand shift toward pathogen-specific interventions over broad-spectrum approaches.
For Market Incumbents: Cement market share in established antibiotic segments by leveraging extensive manufacturing networks and multi-sourcing strategies to ensure supply stability. Invest in strategic partnerships with biotech firms to gain access to novel drug discovery platforms, mitigating the threat from emerging non-antibiotic therapies. Focus R&D efforts on developing advanced formulations for complicated UTIs, utilizing existing regulatory expertise. Expand into emerging markets with established antibiotic lines to capture growing demand.
For New Entrants and Emerging Players: Online platforms for preventative probiotics and microbiome modulators offer a viable digital-channel route to market penetration. Target white-space opportunities in microbiome-based therapeutics and AI-powered rapid diagnostics for personalized UTI management. The most penetrable segment involves recurrent UTI prevention for outpatient settings, where consumer preference for non-prescription options is rising. A direct-to-consumer model can effectively reach this segment with novel preventative solutions.
For Investors and Strategic Acquirers: Large pharmaceutical companies are the most active acquirers in this space, seeking to diversify portfolios beyond traditional antibiotics. The long-term viability of the market is strong, with the shift to targeted therapies offering sustained value over a five-to-ten-year window. Acquisition targets should include biotech firms with advanced bacteriophage therapy platforms or novel non-antibiotic drug candidates in late-stage clinical trials. A successful Phase 3 clinical trial for a non-antibiotic modality represents a critical signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Non-Antibiotics | Accelerates market entry for novel therapies addressing resistance, shifting treatment paradigms. |
| Manufacturing Scale-Up for Biologics | Ensures commercial availability of complex, targeted treatments for multi-drug resistant infections. |
| Strategic Partnership in Diagnostics | Integrates AI-powered tools for precise pathogen identification, enabling personalized medicine approaches. |
| Distribution Channel Expansion into Online Retail | Increases access for preventative options, catering to consumer preference for convenient, discreet purchases. |
| Investment in Microbiome Research | Unlocks new therapeutic categories for long-term prevention of recurrent urinary tract infections. |
Research Approach
Multiple input streams — scientific literature, regulatory filings, and clinical trial databases — were reconciled to construct a comprehensive view of the urinary tract infection treatment market. Primary data collection involved in-depth interviews with infectious disease specialists, hospital pharmacists, biotech R&D directors, and public health officials. This primary intelligence was then validated against secondary sources including WHO reports, CDC data, company annual reports, and medical journal articles, employing both bottom-up and top-down triangulation.
The data-stream reconciliation informed an analytical framework that projects market trends and growth trajectories across the analysis window. Segmentation dimensions modeled included product type, delivery mode, end user, pathogen resistance profile, and regional regulatory landscape. Compound annual growth rates were derived through a rigorous analysis of historical market performance and projected shifts in treatment paradigms. Industry-specific forecast inputs included disease incidence rates and evolving antibiotic resistance patterns.
The model assumes a particular technology adoption path; alternative pathways for bacteriophage therapies would alter the outlook. Forecasts reflect assumptions regarding regulatory incentives and the pace of novel drug development. Geopolitical events or a major breakthrough in non-antibiotic drug discovery represent specific risk factors that could significantly revise projections. A model refresh is warranted upon material change in antibiotic stewardship guidelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Ultrasound Market
Urology
Nordic Urinary Catheters Market
Urology
Botulinum Toxin in Urology Market
Urology
Penile Cancer Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Continence Care Market
Urology
Urology Lasers Market
Urology
Self-Intermittent Catheters Market
Urology
Pyelonephritis Treatment Market
Urology
Global Bladder Scanner Market
Urology
Renal Cyst Treatment Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
India Urology Market
Urology
India Urology Device Market
Urology
Urology Robotic Surgery Market