
 UAE in Vitro Diagnostics Market | 2026-2036
UAE in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE in Vitro Diagnostics Market Outlook
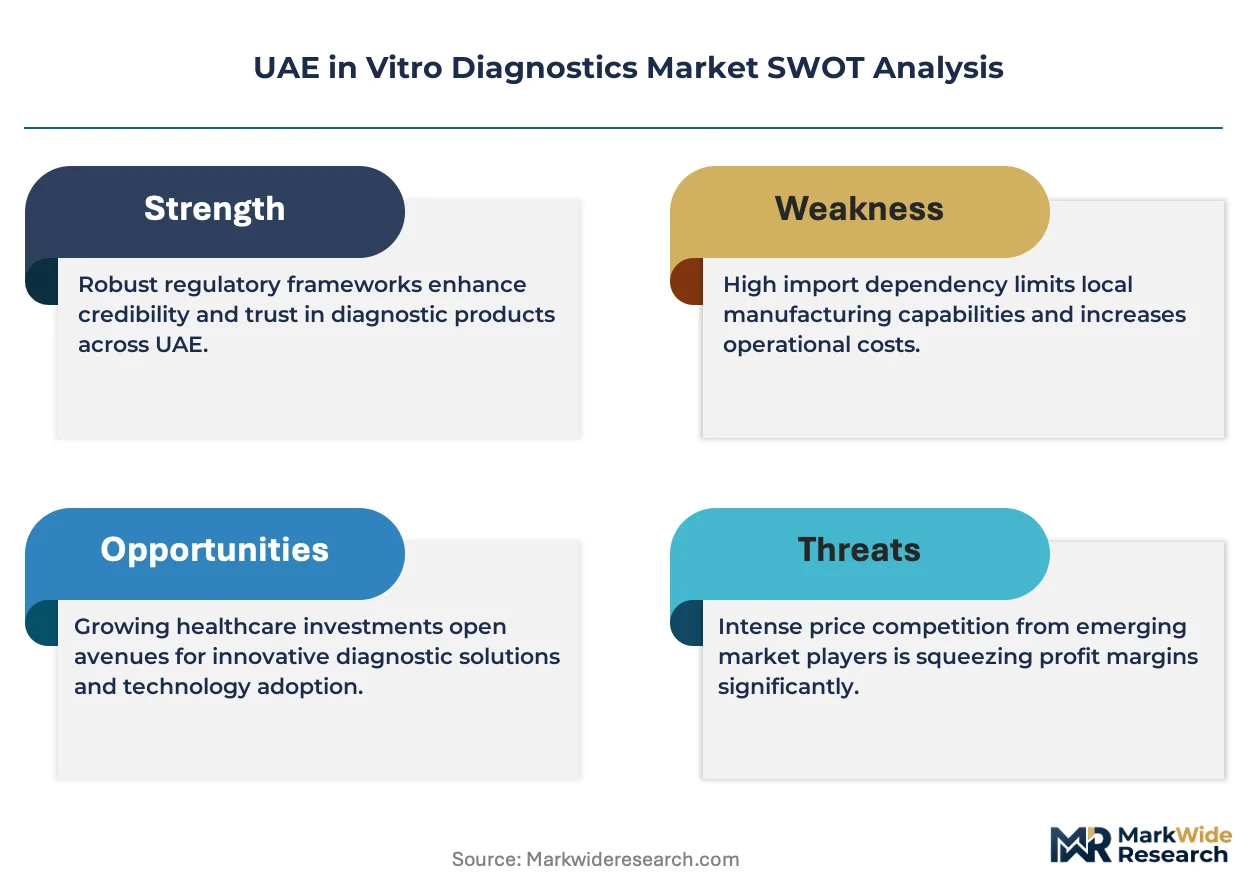
The gap between premium molecular diagnostics and commodity clinical chemistry is consolidating as health systems prioritize targeted therapeutics over broad screening panels. Abbott Laboratories leverages its integrated immunoassay platforms to anchor high-throughput hospital contracts across the Gulf. Roche Diagnostics differentiates through proprietary digital pathology workflows that sustain premium positioning in oncology testing.
In vitro diagnostics comprises analytical systems, reagent kits, and software platforms that detect disease markers, pathogens, and metabolic indicators from patient-derived biological specimens, typically operating with sensitivity thresholds measured in picograms per milliliter and turnaround windows under two hours for stat testing. Molecular diagnostics and immunoassays occupy the fastest-expanding margin pools as precision medicine protocols displace legacy workflows, while clinical chemistry remains a mature volume base where price compression limits upside. Hematology instruments compete on automation density and walkaway capacity rather than novel biomarker expansion.
MOHAP and the country's national pharmaceutical regulator enforce pre-market registration, quality system audits, and post-market surveillance that shape product entry timelines and capital allocation for localization. BIS-aligned standards for instrument calibration and reagent stability create technical barriers that favor suppliers with established Middle East service networks. Stakeholders must weigh the trade-off between centralized reference laboratory scale and point-of-care decentralization as reimbursement frameworks evolve.
Market Dynamics
Hospital laboratories across the Emirates are consolidating testing workflows onto integrated platforms, compressing vendor relationships from fragmented point solutions toward single-source automation contracts that lock in reagent volumes and service dependencies.
Growth Catalysts
- MOHAP Quality Mandates:Mandatory accreditation for diagnostic facilities is accelerating replacement cycles for non-compliant instruments and driving standardization across hospital networks.
- Molecular Diagnostics Expansion:Precision medicine protocols in oncology and infectious disease are displacing legacy immunoassay panels with higher-margin PCR and NGS workflows.
- Dubai Healthcare City Clustering:Concentrated procurement authority within the free zone's reference laboratories is creating anchor contracts that shape national pricing benchmarks.
Market Restraints
- Reagent Import Dependency:Over 80% of diagnostic consumables enter through Jebel Ali, exposing margins to freight volatility and currency fluctuation against the dollar-pegged dirham.
- Technical Talent Scarcity:Certified biomedical engineers and clinical laboratory scientists remain concentrated in Abu Dhabi and Dubai, constraining expansion into Northern Emirates.
- Capital Intensity Barriers:Fully automated chemistry and immunoassay platforms require seven-figure dirham investments that filter out mid-tier private clinic operators.
Strategic Opportunities
- Point-of-Care Decentralization:MOHAP's emerging reimbursement frameworks for ambulatory testing are opening procurement channels outside hospital laboratory networks.
- AI-Enabled Digital Pathology:Convergence of whole-slide imaging with machine learning classification is creating new service revenue streams in histopathology outsourcing.
- Northern Emirates Penetration:Ras Al Khaimah and Fujairah healthcare infrastructure buildouts lack established vendor relationships, presenting first-mover contract opportunities.
Industry Challenges
- ISO 15189 Certification Timelines:Multi-month audit queues at MOHAP-accredited bodies are delaying laboratory commissioning and revenue recognition for new facilities.
- Legacy LIS Integration Complexity:Hospital information system architectures from the 2010s require middleware development to interface with modern instrument data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE in Vitro Diagnostics Market |
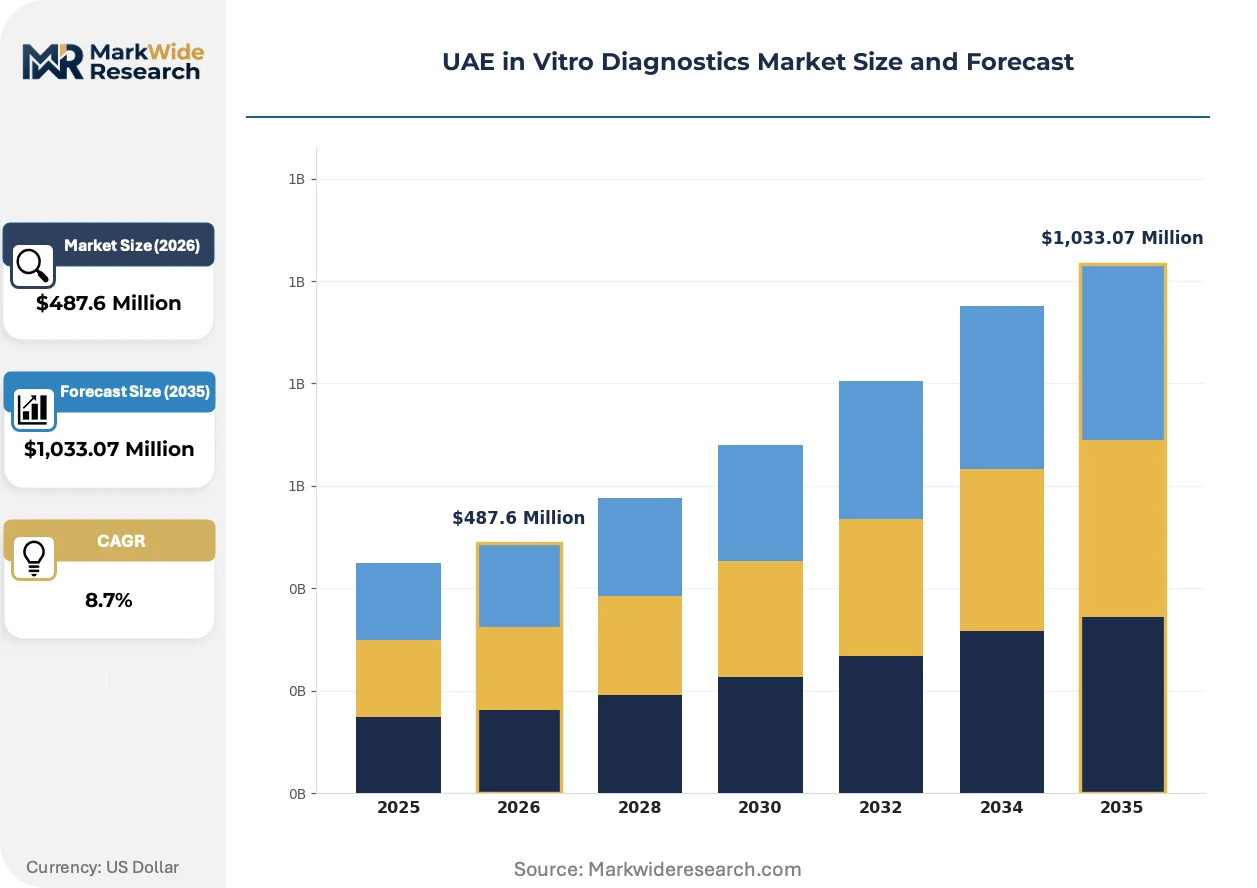
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables Technology: Molecular Diagnostics, Immunoassays, Clinical Chemistry, Hematology End User: Hospitals, Laboratories, Clinics, Research Institutions Application: Oncology, Infectious Diseases, Cardiovascular Disorders, Diabetes |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, bioMérieux, QIAGEN, Thermo Fisher Scientific, Becton Dickinson, Danaher, Sysmex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE in Vitro Diagnostics Market Strategic Shifts
Diagnostics workflows are fragmenting between centralized high-throughput automation and distributed near-patient testing, forcing suppliers to maintain dual platform architectures without sacrificing margin on either.
Random-access immunoassay analyzers are unifying previously separate chemistry, immunoassay, and hematology workstations into single floor-footprint installations. Tertiary hospitals in Abu Dhabi are adopting these consolidated lines to reduce staffing ratios and maintenance contracts. This unification is compressing the addressable market for standalone instrument specialists while elevating service-network scale as the primary competitive barrier.
MOHAP's post-market surveillance requirements for IVD reagent stability are tightening cold-chain documentation and lot-traceability obligations. Manufacturers must now submit real-world performance data for annual license renewals. Hospital laboratories are responding by consolidating purchasing through distributors with established local quality assurance infrastructure.
Direct-to-hospital contracting is displacing traditional medical supply house intermediaries for high-value instrument placements. Procurement committees in Dubai's health authorities now negotiate multi-year total-cost-of-ownership agreements that bundle equipment, reagents, and service. This shift is most visible in oncology molecular diagnostics, where test volume guarantees determine instrument placement decisions.
UAE in Vitro Diagnostics Market Segmentation
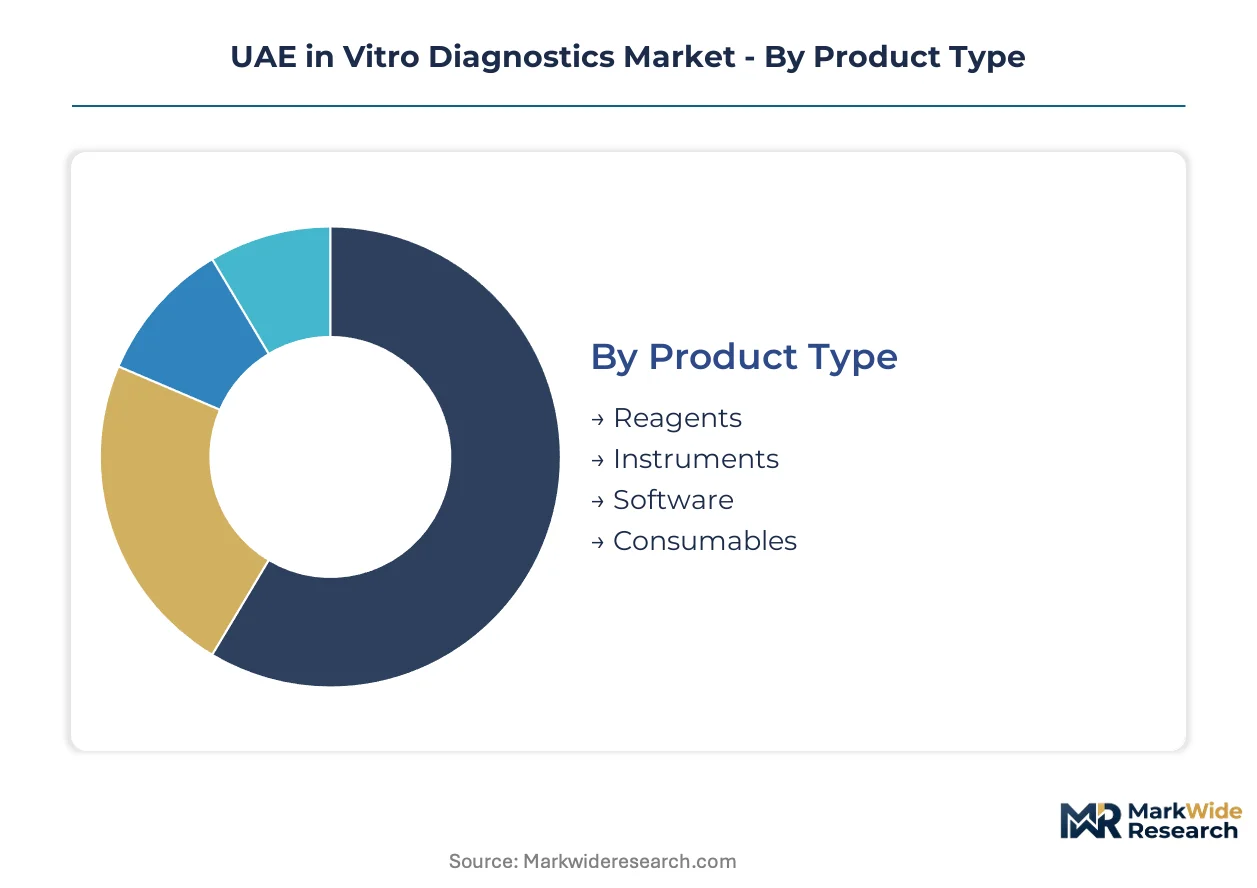
Procurement committees in UAE health authorities evaluate IVD purchases through four intersecting lenses: capital intensity for instruments, reagent annuity economics, workflow integration, and MOHAP compliance tier. Segment boundaries blur as integrated platforms collapse traditional product silos and automation contracts bundle hardware with multi-year consumable commitments.
Product Type:
Capital allocation decisions separate high-value instrument placements from recurring reagent procurement, with software emerging as a distinct margin pool as laboratories digitize quality management and LIS integration.
- Reagents:Diagnostic consumables comprising antibodies, enzymes, nucleic acid probes, and calibrator solutions formulated for specific assay protocols. Demand concentrates in Dubai's hospital networks where MOHAP's mandatory quality accreditation is accelerating replacement of non-compliant reagent lots and locking in approved supplier relationships.
- Instruments:Analytical platforms including random-access immunoassay analyzers, PCR thermal cyclers, and automated hematology counters with throughput specifications measured in tests per hour. Abu Dhabi's tertiary hospitals anchor regional procurement volumes as they consolidate testing onto single-source automation contracts that bundle equipment with multi-year service dependencies.
- Software:Laboratory information systems, middleware for instrument connectivity, and AI-enabled digital pathology platforms. MOHAP's post-market surveillance requirements are tightening cold-chain documentation and lot-traceability obligations that only integrated software stacks can satisfy.
- Consumables:Pipette tips, reaction vessels, sample tubes, and specimen collection devices with BIS-aligned stability standards. Northern Emirates clinics face supply gaps as distributors prioritize high-volume hospital contracts.
Volume sits with Reagents; growth tilts toward Software.
Technology:
Margin stratification follows the shift from legacy broad-screening panels to precision medicine protocols that command premium pricing for targeted biomarker detection.
- Molecular Diagnostics:PCR, NGS, and nucleic acid amplification technologies detecting genetic mutations and pathogen sequences with sensitivity thresholds in picograms per milliliter. Dubai Healthcare City's reference laboratories are displacing immunoassay workflows with higher-margin molecular protocols for oncology staging and infectious disease subtyping.
- Immunoassays:Antibody-antigen binding assays for hormone, tumor marker, and cardiac troponin quantification. Ras Al Khaimah's expanding hospital infrastructure lacks established vendor relationships, presenting first-mover opportunities for integrated platform suppliers.
- Clinical Chemistry:Enzymatic and photometric assays for metabolic indicators including glucose, lipids, and liver function markers. Price compression limits upside as this segment matures into a commoditized volume base.
- Hematology:Cell counting and morphology analysis for complete blood count parameters. Automation density and walkaway capacity determine competitive positioning rather than novel biomarker expansion.
Clinical Chemistry carries baseline volume; Molecular Diagnostics climbs the fastest.
End User:
Site-of-care economics and reimbursement authority shape vendor access, with hospital laboratories consolidating purchasing power while ambulatory channels fragment across regulatory tiers.
- Hospitals:Tertiary and secondary medical centers with centralized laboratory departments operating 24-hour stat testing capabilities. Dubai and Abu Dhabi health authorities negotiate multi-year total-cost-of-ownership agreements that bundle equipment, reagents, and service into single-source contracts.
- Laboratories:Independent diagnostic facilities and reference laboratories serving outpatient and contract testing demand. MOHAP's mandatory accreditation is accelerating replacement cycles for non-compliant instruments across this channel.
- Clinics:Primary care and specialist outpatient facilities with limited on-site testing capacity. MOHAP's emerging reimbursement frameworks for point-of-care testing are opening procurement channels outside hospital networks.
- Research Institutions:Academic medical centers and biotechnology facilities conducting clinical trials and biomarker discovery. Fujairah's healthcare infrastructure buildouts lack established research-grade supplier relationships.
Hospitals dominate current procurement; Clinics represent the steepest expansion trajectory.
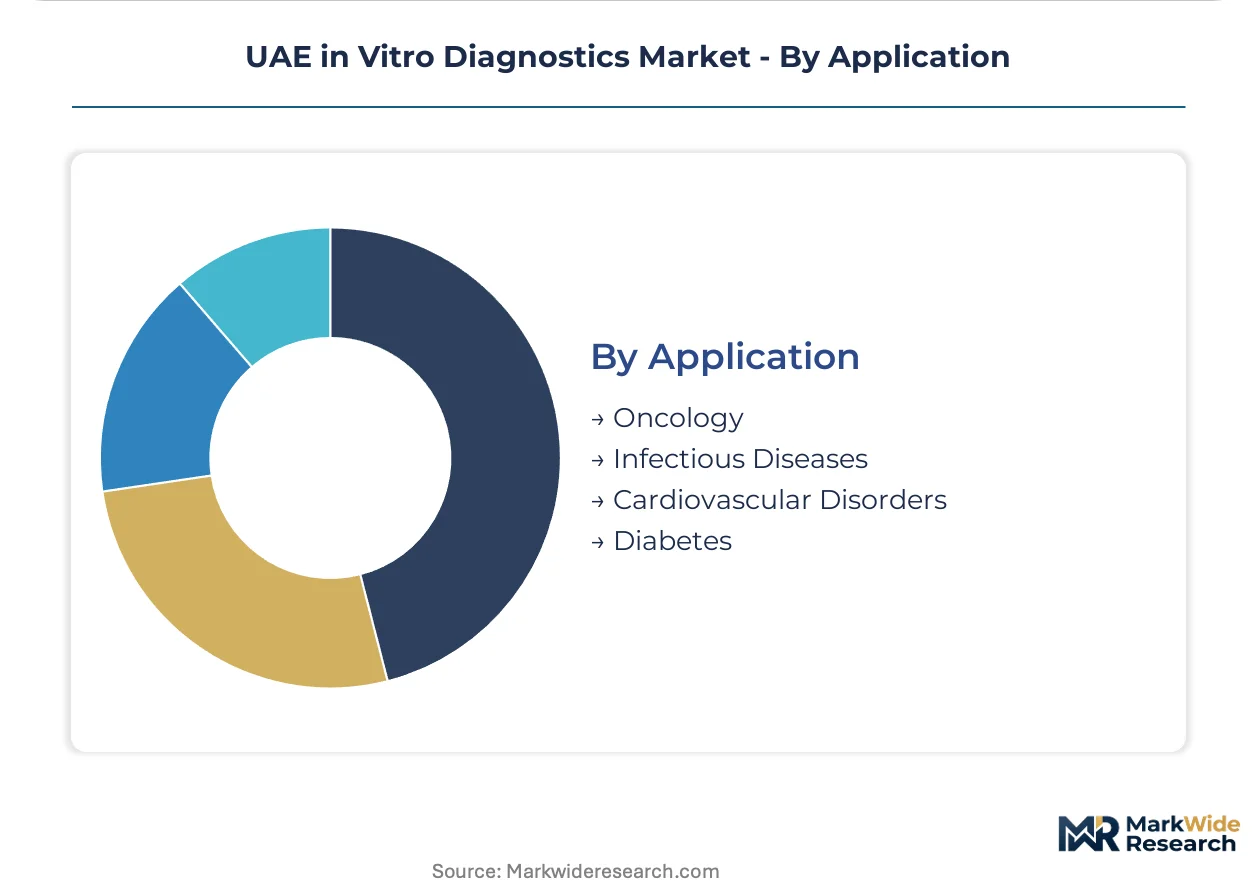
Application:
Disease prevalence and therapeutic pipeline activity determine test menu prioritization, with oncology and infectious disease commanding the highest per-test margins.
- Oncology:Tumor marker quantification, companion diagnostic testing, and minimal residual disease monitoring for precision therapy selection. Test volume guarantees determine instrument placement decisions in Dubai's health authority procurement committees.
- Infectious Diseases:Pathogen detection, antimicrobial resistance profiling, and viral load monitoring. Abu Dhabi's reference laboratories are adopting PCR workflows that displace legacy culture-based methods.
- Cardiovascular Disorders:Cardiac troponin, BNP, and lipid panel assays for acute coronary syndrome and heart failure management. Standardized protocols limit differentiation among suppliers.
- Diabetes:HbA1c, glucose, and microalbumin testing for metabolic monitoring. High test frequency sustains volume but compresses per-test margins in competitive bidding.
Diabetes generates test frequency; Oncology gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Healthcare City anchors procurement authority for the Emirates, with its reference laboratories setting national pricing benchmarks that cascade through MOHAP's regulatory framework.
Dubai
Private hospital groups and diagnostic chains drive instrument replacement cycles, with mandatory MOHAP accreditation compressing vendor selection to approved suppliers. Dubai Healthcare City's concentrated procurement authority bundles multi-year total-cost-of-ownership agreements that lock in reagent volumes. The emirate's free zone status accelerates instrument import timelines through Jebel Ali's logistics corridor.
Abu Dhabi
Tertiary medical centers consolidate testing onto integrated automation platforms, reducing staffing ratios through random-access analyzer unification. SEHA's health system standardization mandates filter procurement toward single-source contracts with embedded service dependencies. The emirate's biomedical engineering talent concentration supports complex instrument commissioning that Northern Emirates cannot replicate.
Sharjah
Mid-tier private clinics face capital intensity barriers for fully automated platforms, constraining molecular diagnostics penetration. MOHAP's emerging point-of-care reimbursement frameworks are opening ambulatory channels outside hospital laboratory networks. The emirate's healthcare infrastructure lacks the procurement scale to negotiate tier-one vendor pricing.
Northern Emirates
Ras Al Khaimah and Fujairah healthcare buildouts present first-mover contract opportunities where established vendor relationships remain unsettled. Technical talent scarcity in certified clinical laboratory scientists delays laboratory commissioning timelines. MOHAP's ISO 15189 certification queues extend revenue recognition delays for new facilities in these sub-regions.
UAE in Vitro Diagnostics Market Competitive Environment
Capital-heavy instrument manufacturers compete with asset-light reagent specialists for laboratory budget allocation across the Emirates. Market structure tilts toward consolidation as hospital networks compress fragmented point solutions into single-source automation contracts. Three archetypes dominate: integrated platform suppliers bundling hardware with consumable annuities, molecular diagnostics specialists commanding premium pricing for precision protocols, and regional distributors bridging MOHAP compliance requirements for mid-tier clinics. Dominant competitive moves include multi-year total-cost-of-ownership agreements that embed reagent volume guarantees, and strategic partnerships with Dubai Healthcare City reference laboratories to anchor national pricing benchmarks.
Among the integrated platform tier, Abbott Laboratories and Roche Diagnostics exemplify contrasting positioning strategies—Abbott anchoring high-throughput hospital contracts through immunoassay unification, Roche sustaining premium oncology positioning through digital pathology differentiation. Siemens Healthineers occupies a scale-driven position spanning instrumentation breadth across chemistry, immunoassay, and hematology modalities. These three represent the archetype of vendors capable of satisfying MOHAP's post-market surveillance requirements while maintaining service network density across the Emirates.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| bioMérieux |
| QIAGEN |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Danaher |
| Sysmex |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed health systems in Abu Dhabi and Dubai anchor procurement authority, compressing vendor margins through multi-year total-cost-of-ownership agreements while concentrating reagent purchasing power in SEHA and Dubai Health Authority networks. This ownership pattern locks suppliers into service-dependent relationships that limit price negotiation leverage outside anchor contract renewals.
Pricing Analysis
Throughput-based pricing anchors hospital laboratory contracts, with per-test economics bundled across chemistry, immunoassay, and hematology modalities. Price differentiation separates MOHAP-accredited reference laboratories commanding premium service tiers from mid-tier private clinics facing capital barriers to automation. Pricing pressure stems from SEHA's standardization mandates filtering procurement toward single-source contracts with embedded volume guarantees. Private clinic operators exhibit highest price sensitivity due to limited bargaining scale against integrated platform suppliers.
Supply Chain Analysis
Single-source vulnerability sits with Jebel Ali as the dominant import corridor for diagnostic consumables, concentrating over four-fifths of reagent flows through one logistics node. The supply chain draws from Germany, Switzerland, and the USA for analytical instruments, while reagent formulations depend on enzymes, antibodies, and nucleic acid probes manufactured in Western Europe and North America. Tariff exposure runs through dirham-dollar peg volatility against euro and swiss franc procurement costs. Distribution runs through MOHAP-licensed distributors with established cold-chain quality assurance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE IVD sector functions as a vertical-integration race where control over reagent manufacturing and local service networks determines contract retention. Incumbents and challengers alike must secure backward integration into consumable production or forward integration into laboratory management services to defend margin pools.
For Market Incumbents: Extend service-network density across Northern Emirates before competitor lock-in, prioritizing Ras Al Khaimah and Fujairah where established vendor relationships remain unsettled. Consolidate reagent supply agreements with MOHAP-accredited distributors to preempt regulatory compliance barriers for challengers. Anchor multi-year automation contracts with test volume guarantees that embed switching costs. The priority lever centers on pre-empting ISO 15189 certification support for new laboratory entrants before they commission competing platforms. For New Entrants and Emerging Players: Mid-tier private clinics in Sharjah represent the most penetrable buyer archetype, constrained by capital intensity barriers that filter out integrated platform specialists. Target point-of-care molecular diagnostics where MOHAP's emerging reimbursement frameworks are opening procurement channels outside hospital laboratory networks. Pursue digital pathology outsourcing partnerships with Dubai Healthcare City reference laboratories to anchor service revenue streams. The go-to-market angle emphasizes AI-enabled workflow integration that reduces staffing ratios for resource-constrained operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with MOHAP compliance infrastructure and established cold-chain capabilities in secondary emirates. Long-term viability over a five-to-ten year window hinges on consolidation plays that bundle reagent procurement with software-enabled quality management systems. Acquisition targets should demonstrate embedded relationships with SEHA or Dubai Health Authority procurement committees. The signal to watch is MOHAP accreditation queue lengths, as extended ISO 15189 audit timelines compress revenue recognition for new facilities and strain working capital for undercapitalized operators.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Accreditation Fast-Track | Accelerates laboratory commissioning timelines and revenue recognition for new facilities. |
| Reagent Localization Partnership | Reduces Jebel Ali import dependency and insulates margins from currency fluctuation exposure. |
| AI-Enabled Digital Pathology Platform | Creates service revenue streams in histopathology outsourcing for Dubai Healthcare City reference laboratories. |
| Northern Emirates Service Network Expansion | Captures first-mover contract opportunities in Ras Al Khaimah and Fujairah infrastructure buildouts. |
| Point-of-Care Reimbursement Strategy | Positions for MOHAP's emerging ambulatory testing frameworks outside hospital laboratory networks. |
Study Parameters
MOHAP regulatory filings, SEHA procurement disclosures, and Dubai Health Authority contract awards formed the secondary backbone for market sizing and competitive positioning. Primary interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and IVD distributor executives validated instrument placement data and reagent volume flows. Bottom-up triangulation across emirate-level healthcare infrastructure investments combined with top-down reconciliation against national health expenditure benchmarks anchored the analytical framework.
Historical trendline analysis across instrument replacement cycles and reagent consumption patterns informed the projection methodology. Segmentation modeling spanned product type, technology modality, end-user site-of-care, and application area across the analysis window. CAGRs were derived from regression-adjusted growth rates applied to base-year estimates, incorporating MOHAP accreditation timelines and Dubai Healthcare City procurement authority as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MOHAP regulatory shifts, reagent import policy changes, and precision medicine protocol adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Vision Screeners Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
Cervical Cancer Diagnostic Tests Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Women's Health Diagnostics Market