
 Urinary Incontinence Market | 2026-2036
Urinary Incontinence Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Incontinence Market Outlook
Project finance for durable medical equipment leasing is tilting competitive dynamics toward asset-light distribution models. Medtronic leverages its neuromodulation platform to sustain recurring revenue from implantable pulse generators. Essity Aktiebolag anchors retail shelf presence across European pharmacy chains with private-label absorbent lines. Kimberly-Clark Corporation competes on consumer brand recognition in the over-the-counter pad segment.
Urinary incontinence encompasses involuntary urine leakage managed through absorbent collection systems, urethral or suprapubic drainage catheters, sacral nerve electrical stimulators, and pharmaceutical agents targeting detrusor muscle overactivity; devices typically incorporate biocompatible silicone, hydrophilic coatings, and closed-drainage valves to prevent infection and maintain skin integrity. Absorbent pads dominate volume due to low clinical barriers and direct consumer purchase, while electrically stimulated devices capture premium margins tied to surgical implantation and programming services. Home care settings represent the fastest-growing delivery channel as reimbursement shifts favor outpatient continence management over institutional stays.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape device commercialization timelines and clinical evidence burdens for manufacturers. CMS national coverage determinations and NICE technology appraisals directly influence patient access to advanced neuromodulation systems across the United States and United Kingdom. Stakeholders must monitor evolving HTA body criteria for digital continence diagnostics and biofeedback-enabled wearable devices.
Market Dynamics
Neuromodulation device reimbursement pathways are compressing clinical trial timelines while expanding addressable patient populations beyond pharmaceutical-refractory cases.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit expanding cohorts over 65 requiring outpatient continence management, driving durable medical equipment demand in home care settings.
- FDA Breakthrough Device Designation:Accelerated review pathways for closed-loop sacral nerve stimulators reduce premarket approval cycles, enabling faster commercialization of next-generation implantable pulse generators.
- Closed-Drainage Valve Innovation:Hydrophilic-coated silicone catheters with anti-reflux mechanisms are reducing catheter-associated urinary tract infection rates, expanding hospital procurement of premium drainage systems.
Market Restraints
- Silicone Raw Material Concentration:Medical-grade elastomer supply concentrates among specialty chemical producers in Germany and Japan, exposing device manufacturers to input cost volatility and single-source risk.
- EU MDR Technical Documentation Burden:Enhanced clinical evidence requirements for Class III implantable devices extend conformity assessment timelines, delaying market entry for novel neuromodulation systems.
- Pharmaceutical Substitution:Oral antimuscarinics and beta-3 agonists retain first-line therapy status in mild-to-moderate urgency incontinence, limiting surgical device penetration in early-stage patients.
Strategic Opportunities
- India's Underserved Patient Base:Low penetration of advanced continence devices among India's aging population creates white space for affordable absorbent product lines and basic catheter systems.
- Digital Therapeutic Convergence:Integration of biofeedback-enabled wearables with pelvic floor muscle training apps enables remote monitoring reimbursement codes in United States Medicare Advantage plans.
- Retail Pharmacy Channel Expansion:Direct-to-consumer e-commerce platforms for absorbent pads bypass traditional durable medical equipment distributors, capturing margin in Germany's pharmacy-dense urban markets.
Industry Challenges
- Specialized Urogynecology Workforce Scarcity:Limited fellowship-trained surgeons capable of implanting sacral nerve stimulators constrains procedure volume growth in secondary and tertiary United States markets.
- Legacy Electronic Health Record Integration:Neuromodulation device programming software requires custom API development to interface with hospital IT systems, extending sales cycles and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Incontinence Market |
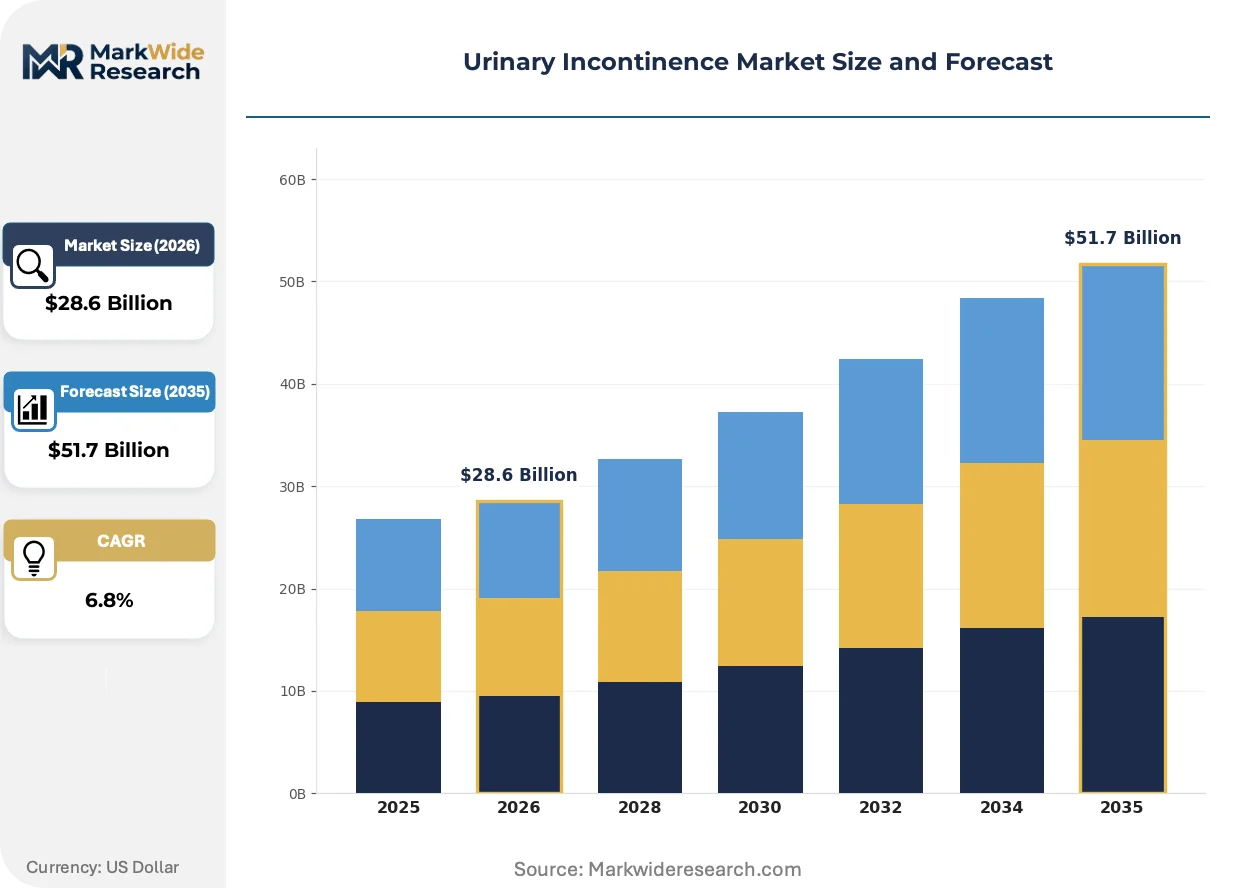
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, Catheters, Electrically Stimulated Devices, Medications Delivery Mode: Oral, Injectable, Transdermal, Surgical End User: Hospitals, Home Care Settings, Rehabilitation Centers, Clinics Application: Childbirth Recovery, Geriatrics, Neurological Disorders, Prostate Surgery |
| Companies Covered | Coloplast A/S, Boston Scientific Corporation, Medtronic, Essity Aktiebolag, Becton, Dickinson and Company, Teleflex Incorporated, ConvaTec Group plc, Johnson & Johnson, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Incontinence Market Strategic Shifts
Sensor-embedded continence products are generating real-world evidence streams that reshape both clinical practice patterns and payer coverage determinations.
Closed-loop sacral nerve stimulation systems are digitizing patient-specific therapy delivery by automatically adjusting electrical parameters based on detrusor pressure feedback. Urogynecology practices in the United States are piloting these devices for medication-refractory urgency incontinence. The technology is digitizing the traditional trial-and-error programming model, compressing optimization timelines from months to weeks.
EU MDR post-market surveillance requirements are mandating systematic collection of implantable device performance data across European member states. Manufacturers must now maintain updated periodic safety update reports and vigilance databases. Sacral nerve stimulator producers face heightened documentation burdens, prompting consolidation of notified body relationships to streamline conformity assessments.
Home care agencies are unbundling after-sales support from product procurement, creating discrete service revenue streams for device programming and maintenance. This separation disrupts traditional durable medical equipment bundling models in United States Medicare fee-for-service environments. Rural health systems in the American Midwest exhibit the most pronounced shift toward standalone clinical service contracts.
Urinary Incontinence Market Segmentation
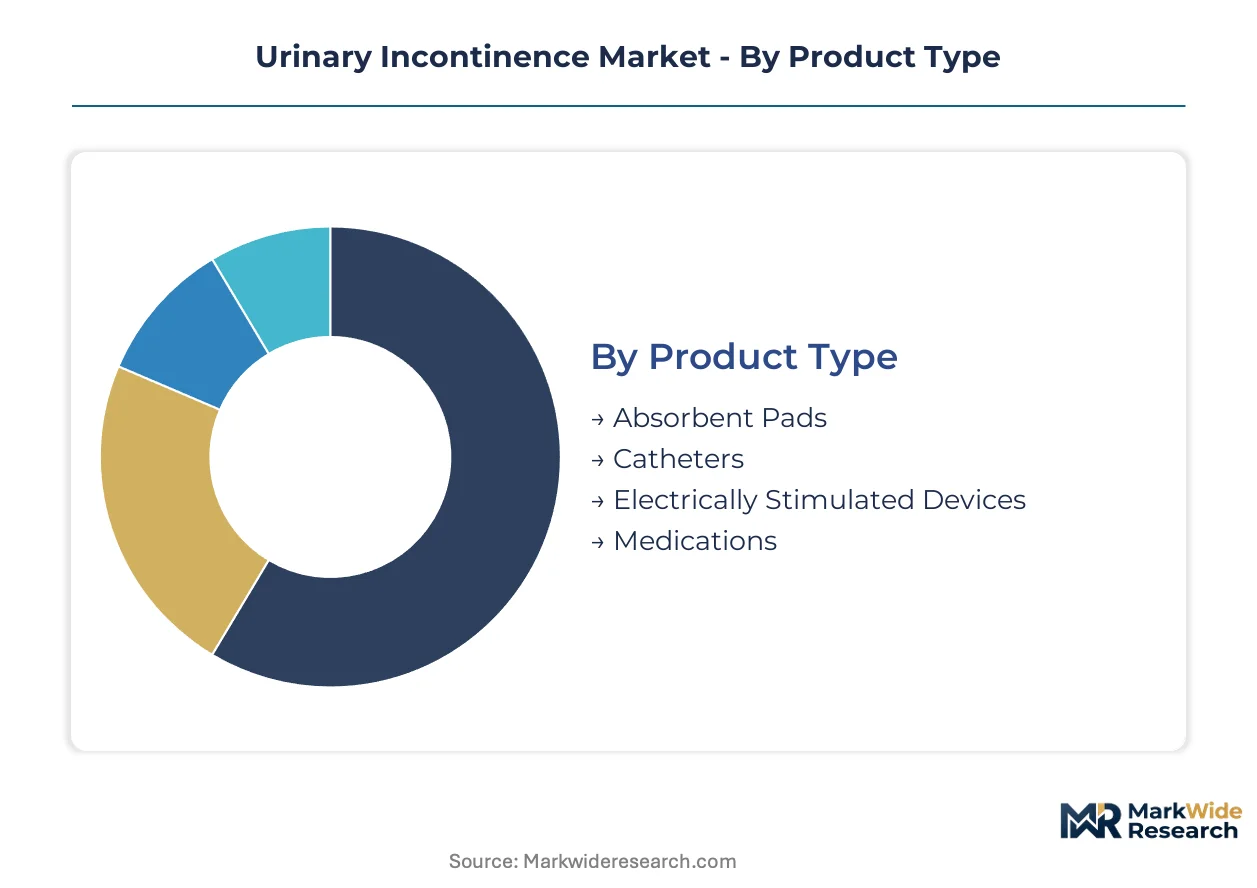
Segmentation in the urinary incontinence market reveals divergent margin structures and reimbursement pathways. Product categories span disposable consumables with pharmacy distribution to implantable systems requiring surgical infrastructure. Understanding these divisions illuminates where capital deployment concentrates versus where volume throughput dominates.
Product Type:
Mature absorbent technologies coexist with emerging neuromodulation platforms at opposite ends of the clinical intervention spectrum.
- Absorbent Pads:Multi-layer constructions combine acquisition/distribution layers with superabsorbent polymer cores for moisture retention. Demand concentrates in Germany's pharmacy-dense urban corridors and Japan's aging suburban prefectures where direct consumer purchase bypasses prescription requirements.
- Electrically Stimulated Devices:Implantable pulse generators deliver sacral nerve modulation through biocompatible leads with closed-loop pressure feedback capability. Adoption clusters in United States tertiary urogynecology centers where CMS reimbursement codes support surgical implantation and programming services.
- Catheters:Hydrophilic-coated silicone systems with anti-reflux valves reduce catheter-associated urinary tract infection rates in institutional settings.
- Medications:Oral antimuscarinics and beta-3 agonists target detrusor overactivity through peripheral receptor modulation.
Absorbent pads handle the majority of throughput; electrically stimulated devices are the fastest mover on share.
Delivery Mode:
Route of administration determines regulatory pathway complexity and patient compliance profiles across the therapeutic continuum.
- Oral:First-line pharmaceutical agents including antimuscarinics and beta-3 agonists deliver systemic detrusor muscle modulation with established bioavailability profiles.
- Surgical:Implantation of sacral nerve stimulators and artificial urinary sphincters requires specialized urogynecology fellowship training and operating room infrastructure.
- Injectable:Intravesical botulinum toxin and periurethral bulking agents offer minimally invasive alternatives for patients refractory to oral therapy.
- Transdermal:Oxybutynin patches bypass first-pass hepatic metabolism while reducing anticholinergic systemic side effects.
Oral administration commands the widest prescriber base; surgical delivery captures the highest per-procedure revenue.
End User:
Site-of-care migration from institutional to domestic settings is restructuring procurement relationships and service bundling models.
- Home Care Settings:Aging cohorts in the United States, Germany, and Japan drive durable medical equipment demand for outpatient continence management. Reimbursement shifts favor home-based absorbent product procurement and remote device programming over extended institutional stays.
- Hospitals:Acute care facilities manage post-surgical urinary retention and neurological injury cases through indwelling catheterization and interim neuromodulation trials.
- Clinics:Urogynecology and urology outpatient practices conduct diagnostic urodynamic testing and device programming optimization.
- Rehabilitation Centers:Post-stroke and spinal cord injury patients receive pelvic floor biofeedback training and intermittent catheterization instruction.
Home care settings absorb the steepest expansion trajectory; hospitals retain the highest-acuity device implantation volume.
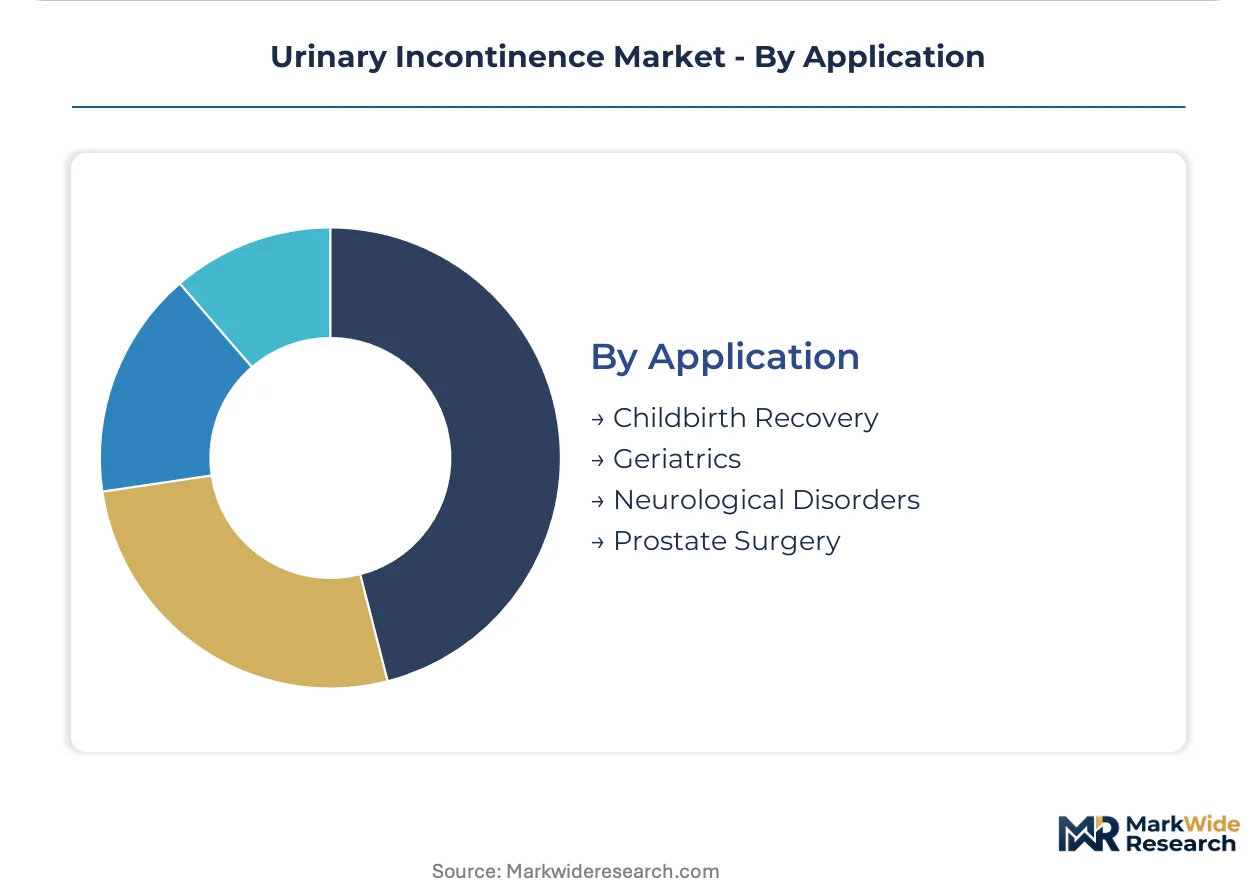
Application:
Underlying etiology segments addressable populations by clinical pathway and intervention timing.
- Geriatrics:Age-related detrusor overactivity and sphincter weakness in patients over 65 create sustained demand for absorbent products and pharmaceutical first-line therapy across developed economies.
- Prostate Surgery:Radical prostatectomy and transurethral resection procedures generate post-operative stress incontinence requiring temporary catheterization or permanent artificial sphincter implantation.
- Neurological Disorders:Multiple sclerosis, Parkinson's disease, and spinal cord injury disrupt central and peripheral micturition control mechanisms.
- Childbirth Recovery:Vaginal delivery-related pelvic floor trauma produces transient or persistent stress incontinence in postpartum populations.
Geriatrics generates the largest absolute patient volume; prostate surgery applications command the highest device-related expenditure per case.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home care agencies and hospital procurement departments concentrate demand across aging economies where reimbursement frameworks favor outpatient continence management over institutional stays.
United States
CMS national coverage determinations for sacral nerve stimulators and Medicare Advantage remote monitoring codes drive device adoption in tertiary urogynecology centers. FDA breakthrough device designation pathways accelerate commercialization timelines for closed-loop neuromodulation systems. Minneapolis-based Medtronic anchors implantable pulse generator production while Boston Scientific Corporation maintains surgical device manufacturing in Massachusetts.
Germany
Pharmacy-dense urban corridors in Bavaria and North Rhine-Westphalia sustain absorbent product volume through direct consumer purchase channels. EU MDR technical documentation requirements for Class III implantable devices extend conformity assessment timelines at notified bodies in Berlin and Munich. Essity Aktiebolag leverages retail shelf presence across European pharmacy chains with private-label lines manufactured in regional facilities.
Japan
PMDA accelerated approval pathways for novel neuromodulation devices reduce premarket review cycles for medication-refractory urgency incontinence cases. METI reimbursement frameworks support home-based durable medical equipment procurement for aging suburban prefectures. Medical-grade silicone elastomer supply concentrates among specialty chemical producers in Osaka and Nagoya, exposing device manufacturers to input cost volatility.
United Kingdom
NICE technology appraisals directly influence patient access to advanced neuromodulation systems through NHS England commissioning frameworks. HTA body criteria for digital continence diagnostics reshape coverage determinations for biofeedback-enabled wearable devices. Urogynecology practices in Greater London and the Midlands pilot closed-loop sacral nerve stimulation systems for outpatient programming optimization.
India
Low penetration of advanced continence devices among aging urban populations creates white space for affordable absorbent product lines. CDSCO medical device registration requirements for imported neuromodulation systems establish quality benchmarks for domestic distribution. Home care agencies in Maharashtra and Karnataka unbundle after-sales support from product procurement, creating discrete service revenue streams for basic catheter systems.
Urinary Incontinence Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures in the urinary incontinence market. Consolidation concentrates around implantable device manufacturers with recurring revenue from pulse generator replacements and programming services. Three archetypes dominate: diversified medical technology conglomerates with neuromodulation platforms, consumer hygiene multinationals with pharmacy retail scale, and specialized urology device manufacturers with surgical infrastructure ties. Competitive moves center on M&A to capture digital therapeutic capabilities and strategic partnerships to secure silicone elastomer supply.
Within the diversified medical technology tier, Medtronic and Boston Scientific Corporation exemplify platform players with implantable pulse generator portfolios. Among consumer hygiene specialists, Essity Aktiebolag and Kimberly-Clark Corporation occupy positions anchored by retail shelf presence and brand recognition. Coloplast A/S represents the specialized surgical device archetype with urology-focused manufacturing heritage. Johnson & Johnson and Becton, Dickinson and Company sit within broader medical supply conglomerates leveraging hospital procurement relationships.
| Leading Market Players |
|---|
| Coloplast A/S |
| Boston Scientific Corporation |
| Medtronic |
| Essity Aktiebolag |
| Becton, Dickinson and Company |
| Teleflex Incorporated |
| ConvaTec Group plc |
| Johnson & Johnson |
| Kimberly-Clark Corporation |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone elastomer production concentrates among specialty chemical producers in Germany and Japan, anchoring margin pools in implantable neuromodulation devices where biocompatible material certification commands premium positioning over commodity absorbent products.
Pricing Analysis
Certification level creates the primary spread across product tiers, with FDA 510(k)-cleared and CE-marked Class III implantable devices capturing substantial premiums over basic absorbent pads lacking regulatory documentation. Pricing stratifies across premium neuromodulation systems with closed-loop programming, standard intermittent catheters with hydrophilic coatings, and economy absorbent lines sold through retail pharmacy channels. Cost compression in the economy tier intensifies as private-label manufacturers expand direct-to-consumer e-commerce presence, bypassing traditional distributor markups. Home care agencies exhibit highest price sensitivity due to reimbursement rate constraints, while tertiary urogynecology centers demonstrate lowest sensitivity given CMS coverage determination support for advanced surgical devices.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electronic components in implantable pulse generator manufacturing. Device production draws from medical-grade silicone supply in Germany and Japan, lithium-ion battery cells from South Korea, and semiconductor components from Taiwan. Single-source vulnerability concentrates in specialty biocompatible coating formulations produced by limited qualified suppliers. Distribution runs through durable medical equipment distributors in institutional channels, direct-to-consumer e-commerce platforms for absorbent products, and specialized surgical device representatives for implantable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary incontinence market sits in early-cycle expansion as closed-loop neuromodulation systems penetrate beyond pharmaceutical-refractory patient populations, supported by accelerated FDA review pathways and Medicare Advantage remote monitoring reimbursement codes.
For Market Incumbents: Insulate implantable device margins by securing captive supply agreements for medical-grade silicone elastomers in Germany and Japan, while expanding hospital system partnership structures to lock in programming service revenue streams. Counter pharmaceutical substitution threats by embedding biofeedback-enabled wearables into pelvic floor muscle training protocols that capture discrete reimbursement codes.
For New Entrants and Emerging Players: Pursue India's underserved aging population with affordable absorbent product lines manufactured to CDSCO quality benchmarks, targeting Maharashtra and Karnataka home care agencies that unbundle after-sales support from procurement. Capture margin through direct-to-consumer e-commerce platforms bypassing traditional distributor structures, leveraging pharmacy-dense urban corridors for last-mile delivery optimization.
For Investors and Strategic Acquirers: Capital is best deployed toward neuromodulation platform specialists with recurring revenue from pulse generator replacements and programming services, given durable competitive moats from regulatory clearance portfolios and specialized urogynecology surgeon training relationships. Monitor FDA breakthrough device designation awards as inflection indicators for accelerated commercialization timelines and valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review cycles compress premarket approval timelines for closed-loop sacral nerve stimulators. |
| CE Marking Pathway under EU MDR | Class III implantable documentation requirements extend conformity assessments at Berlin and Munich notified bodies. |
| Hospital System Partnership | Urogynecology center alliances lock in surgical implantation volume and programming service contracts. |
| Software Companion Development | Biofeedback-enabled wearable integration with pelvic floor training apps enables remote monitoring reimbursement. |
| Reimbursement Strategy | CMS national coverage determinations and Medicare Advantage coding directly influence patient access expansion. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EMA medical device registration filings, CMS national coverage determinations, and GPO contract repositories. Interviews with urogynecology surgeons, hospital purchasing committee members, biomedical engineers, and durable medical equipment procurement managers inform demand-side validation. Bottom-up modeling of device implantation volumes and absorbent product consumption triangulates against top-down market sizing from regulatory filing revenue disclosures and trade data.
Forecast inputs span product type segmentation across absorbent pads, electrically stimulated devices, catheters, and medications; delivery mode including oral, surgical, injectable, and transdermal routes; and end user categories from home care settings through hospitals and rehabilitation centers. CAGRs derive from regression analysis of historical reimbursement code utilization, procedure volume trends, and aging demographic projections across the analysis window. Industry-specific inputs incorporate EU MDR implementation timelines and PMDA accelerated approval pathway utilization rates.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rate adjustments, medical-grade silicone commodity pricing, or EU MDR notified body capacity constraints would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and surgeon workforce expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urology Surgery Supplies Market
Urology
Urology Robotic Surgery Market
Urology
Hematuria Treatment Market
Urology
Pyelonephritis Treatment Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Nordic Urinary Catheters Market
Urology
Ureteral Catheters Market
Urology
Europe Urology Devices Market
Urology
Male Urinary Incontinence Market
Urology
Europe Bladder Disorders Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Ureter Cancer Treatment Market
Urology
Botulinum Toxin in Urology Market
Urology
Penile Cancer Market
Urology
Single Use Cystoscope Market