
 Global Cancer Treatment Market | 2026-2036
Global Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Treatment Market Analysis
Branded biologic therapy margins is narrowing as biosimilar competition intensifies across major oncology indications. F. Hoffmann-La Roche Ltd. anchors its position through deep vertical integration in diagnostic-to-treatment ecosystems. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor leadership in solid tumor applications. Merck & Co., Inc. dominates the PD-1 landscape with sustained clinical trial investment across combination regimens.
Cancer treatment encompasses pharmacological, radiological, and biological interventions designed to destroy, control, or palliate malignant cell proliferation, typically administered through intravenous infusion, oral dosing, or precision radiation delivery with dose parameters measured in Gray units. Immunotherapy and targeted therapy now command the fastest expansion within product type segmentation, driven by biomarker-driven patient selection and durable response profiles in melanoma and lung malignancies. Intravenous delivery sustains the largest volume share, though subcutaneous formulations are gaining traction through reduced infusion center burden and patient convenience advantages.
The FDA, EMA, and WHO collectively govern cancer treatment market access through accelerated approval frameworks, orphan drug incentives, and biosimilar interchangeability standards that directly shape development priorities and commercial launch sequencing. China's NMPA and Japan's PMDA are expanding regional trial acceptance criteria, altering where companies initiate pivotal studies. Stakeholders must monitor evolving reimbursement evidence requirements for cell and gene therapies as payers tighten outcome-based contracting terms.
Market Dynamics
The FDA's accelerated approval pathways for breakthrough therapies are compressing commercialization timelines and forcing manufacturers to front-load clinical investment. This regulatory velocity is reshaping how oncology assets reach patients and how competitors sequence their pipeline launches.
Growth Catalysts
- Biomarker-Driven Patient Selection:Companion diagnostics now gate access to targeted therapies, expanding addressable populations for precision oncology. Hospital-based pathology departments are upgrading molecular profiling infrastructure.
- Orphan Drug Incentives:The FDA's seven-year market exclusivity provisions for rare cancer indications are redirecting R&D toward underserved histologies. Developers prioritize indications with unmet need and favorable trial design.
- Subcutaneous Formulation Innovation:Reduced infusion center burden is accelerating uptake in community oncology practices. Patients complete treatment cycles without prolonged hospital visits.
Market Restraints
- Plasma-Derived Raw Material Volatility:Immunoglobulin and albumin supply fluctuations constrain monoclonal antibody production. Fractionation capacity concentrates in North American and European facilities.
- Reimbursement Evidence Thresholds:Payers in Germany and France now mandate head-to-head survival data for premium pricing. Manufacturers face extended post-approval study commitments.
- Cold Chain Infrastructure Gaps:Cell therapy distribution requires liquid nitrogen logistics that remain underdeveloped in secondary cities. Temperature excursion risks limit patient access outside major metropolitan hubs.
Strategic Opportunities
- India's Expanding Clinical Trial Infrastructure:CDSCO streamlined approval timelines for oncology studies, attracting Phase II and III investment. Cost advantages in patient recruitment accelerate enrollment.
- Artificial Intelligence-Enabled Drug Discovery:Machine learning platforms are compressing target identification timelines when paired with CRISPR validation. Biotech entrants leverage computational chemistry to compete with established discovery engines.
- Community Oncology Channel Expansion:Independent practices seek infusion capacity partnerships to retain patients leaving hospital systems. Manufacturers build direct distribution relationships bypassing group purchasing organizations.
Industry Challenges
- Cell Therapy Manufacturing Scale-Up:Autologous production requires patient-specific batch processing that defies economies of scale. Contract development organizations face capacity constraints for viral vector supply.
- Interoperable Electronic Health Record Integration:Real-world evidence collection depends on structured oncology data capture that remains fragmented across hospital systems. Data standardization delays regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Treatment Market |
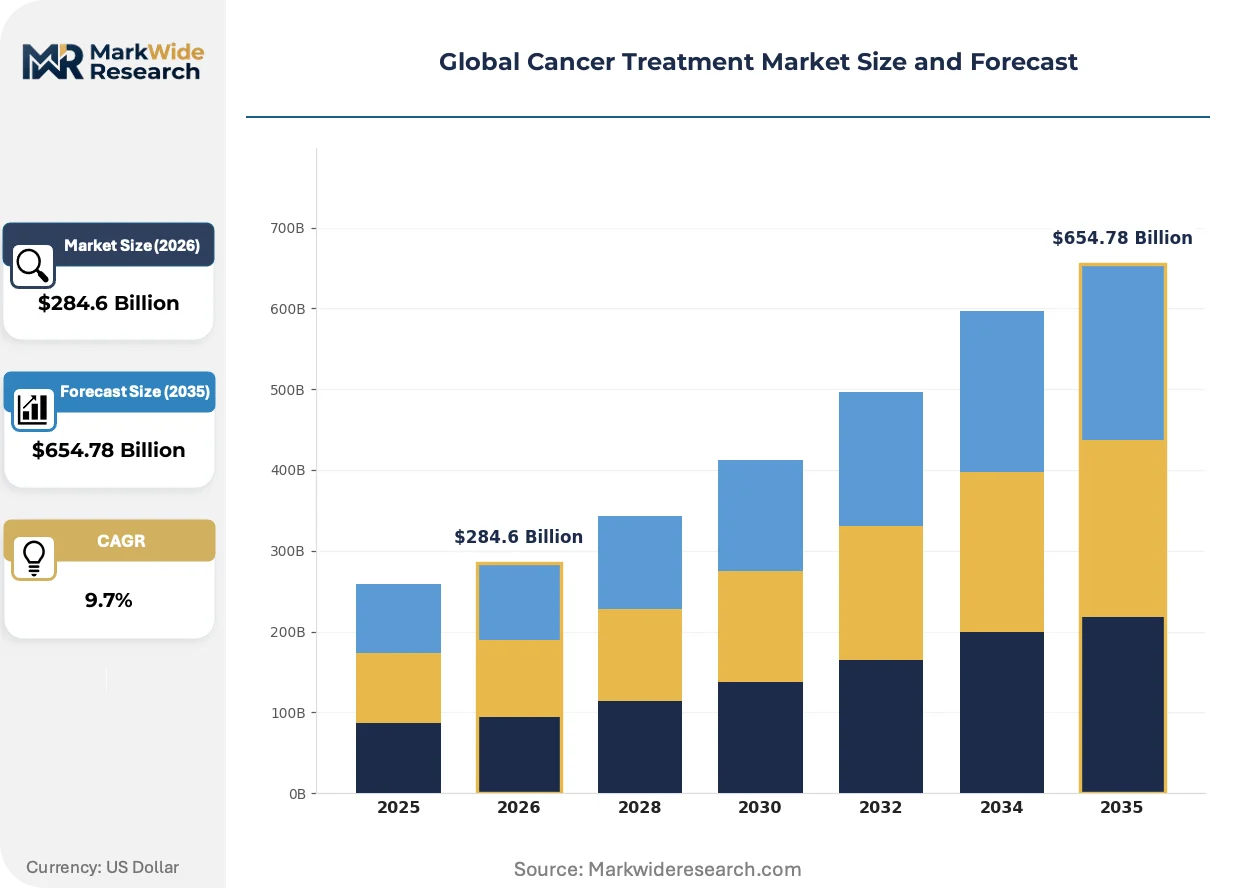
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $654.78 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy Delivery Mode: Intravenous, Oral, Topical, Subcutaneous End User: Hospitals, Clinics, Diagnostics Centers, Home Care Therapy Area: Breast Cancer, Lung Cancer, Prostate Cancer, Colorectal Cancer |
| Companies Covered | F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, Pfizer Inc., Novartis AG, AbbVie Inc., Johnson & Johnson, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Treatment Market Emerging Trajectories
Bispecific antibody constructs are collapsing traditional therapeutic categories by engaging multiple targets simultaneously. This architectural shift is redrawing competitive boundaries between solid tumor and hematologic malignancy specialists.
Dual-antigen engagement is collapsing the distinction between checkpoint inhibition and targeted cytotoxic delivery. Bristol-Myers Squibb and Genentech are advancing bispecific T-cell engagers through Phase III trials in multiple myeloma and lung cancer. The technology is collapsing development timelines by combining mechanisms previously requiring separate agents.
Japan's PMDA introduced conditional early approval pathways for regenerative medicines in 2024, compressing review periods for cell therapies. The framework permits limited commercialization pending confirmatory trials. Asian biotech firms are relocating pivotal study initiation to Tokyo and Osaka to exploit this regulatory velocity.
Hospital procurement committees are consolidating vendor relationships for oncology biologics, reducing supplier counts by half across major US health systems. Integrated delivery networks now negotiate enterprise-wide contracts covering infusion services, pharmacy benefit management, and specialty distribution. The concentration is most visible in Texas and Florida where Catholic health systems and for-profit chains dominate regional markets.
Global Cancer Treatment Market Segmentation
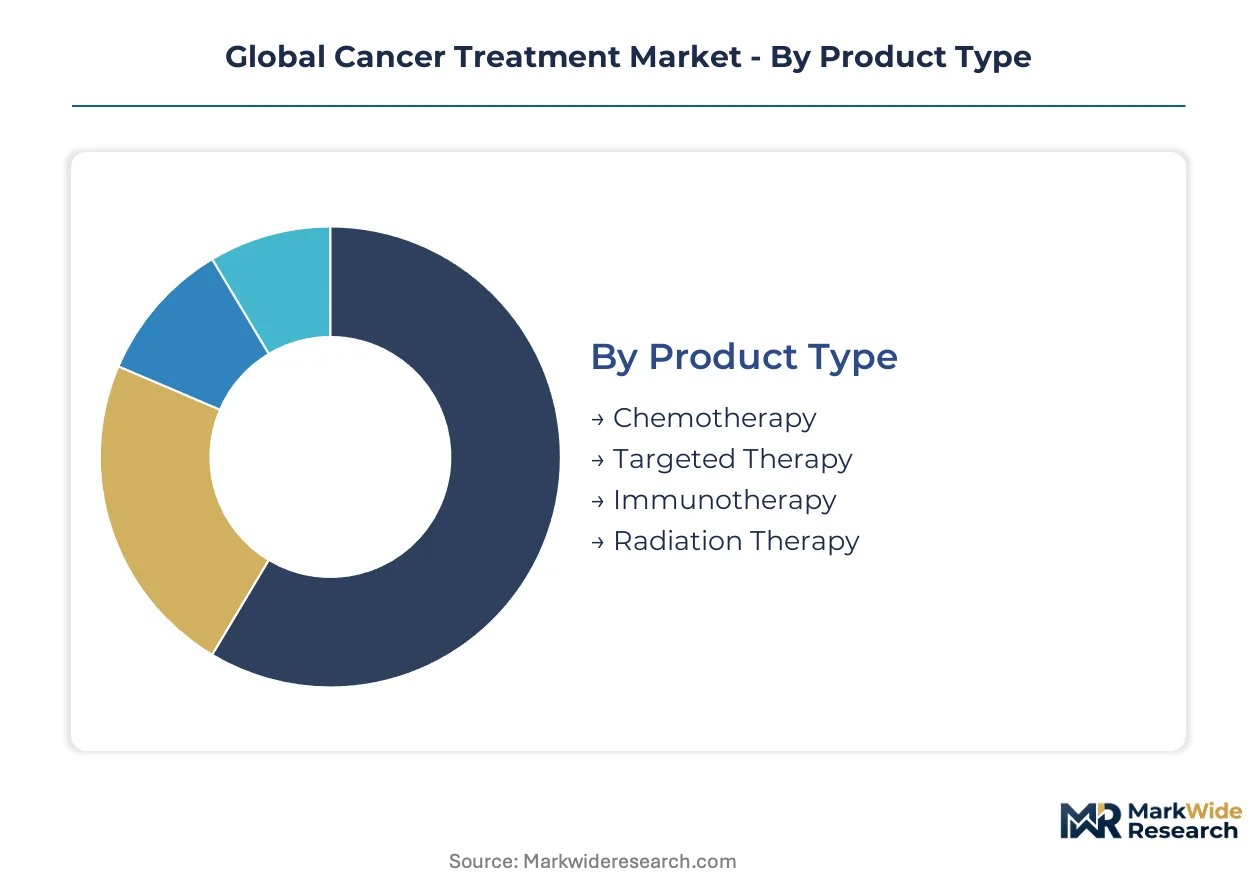
Segmentation in cancer treatment reveals how clinical practice, reimbursement pathways, and manufacturing capabilities allocate value across distinct therapeutic modalities. Understanding these divisions exposes where capital deployment concentrates and where technology transitions disrupt established revenue pools.
Product Type:
Cost tier stratification separates mature cytotoxic agents from premium biologics, with pricing power clustering around mechanisms that demonstrate survival advantages in head-to-head trials.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies command premium reimbursement through durable response profiles in melanoma and hematologic malignancies. Hospital outpatient departments in the United States and Germany anchor demand as these settings manage complex infusion protocols and adverse event monitoring.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed at specific oncogenic drivers require companion diagnostic pairing. China's NMPA and Japan's PMDA have accelerated approval timelines for biomarker-defined indications, concentrating clinical trial initiation in Asia-Pacific markets.
- Chemotherapy:Alkylating agents, antimetabolites, and taxanes constitute the volume foundation across solid tumor protocols. Generic substitution has compressed margins, though platinum compounds retain pricing power in combination regimens.
- Radiation Therapy:External beam systems, brachytherapy, and radioisotope delivery address localized disease control. Proton center construction concentrates in Texas, Florida, and metropolitan Japan where capital investment supports high fixed-cost infrastructure.
Immunotherapy holds installed capacity. Targeted therapy is rotating up the share rankings.
Delivery Mode:
Application context determines route selection, with site-of-care economics and patient convenience exerting countervailing pressures on formulation development priorities.
- Intravenous:Infusion center administration dominates biologic delivery, requiring cold chain logistics and specialized nursing capacity. United States hospital systems and German university hospitals maintain the densest infrastructure for monoclonal antibody administration.
- Subcutaneous:Self-administered formulations reduce facility dependency and enable community oncology practice expansion. Roche's subcutaneous Herceptin and Phesgo formulations demonstrate manufacturing feasibility for high-concentration biologics.
- Oral:Tyrosine kinase inhibitors and hormone therapies support patient autonomy and reduce healthcare system burden. India's CDSCO has streamlined bioequivalence requirements, accelerating local production of generic oral oncology agents.
- Topical:Localized application addresses skin malignancies and palliative lesions with minimal systemic exposure. Dermatology clinics and specialized wound care centers in France and Italy concentrate utilization.
Intravenous retains treatment episode volume. Subcutaneous is gaining fastest in new product launches.
End User:
Customer type segmentation tracks how care migration from inpatient to ambulatory settings reshapes purchasing authority and service bundling requirements.
- Hospitals:Academic medical centers and integrated delivery networks control access to complex cellular therapies and radiation oncology. United States health systems in Texas and California negotiate enterprise-wide contracts spanning infusion pharmacy, specialty distribution, and pathology services.
- Clinics:Independent and hospital-affiliated community oncology practices seek capacity partnerships to retain patients requiring biologic administration. Germany's outpatient oncology centers (Ambulante Krebszentren) concentrate infusion capacity outside hospital walls.
- Diagnostics Centers:Molecular profiling and imaging services gate access to targeted therapy selection. Japan's clinical laboratory improvement standards and China's NMPA diagnostic regulations shape regional infrastructure investment.
- Home Care:Oral agents and subcutaneous formulations enable treatment completion outside clinical facilities. France's autorisation de mise sur le marché pathways for home administration support reimbursement innovation.
Hospitals anchor biologic therapy access. Clinics are climbing the fastest in patient visit share.
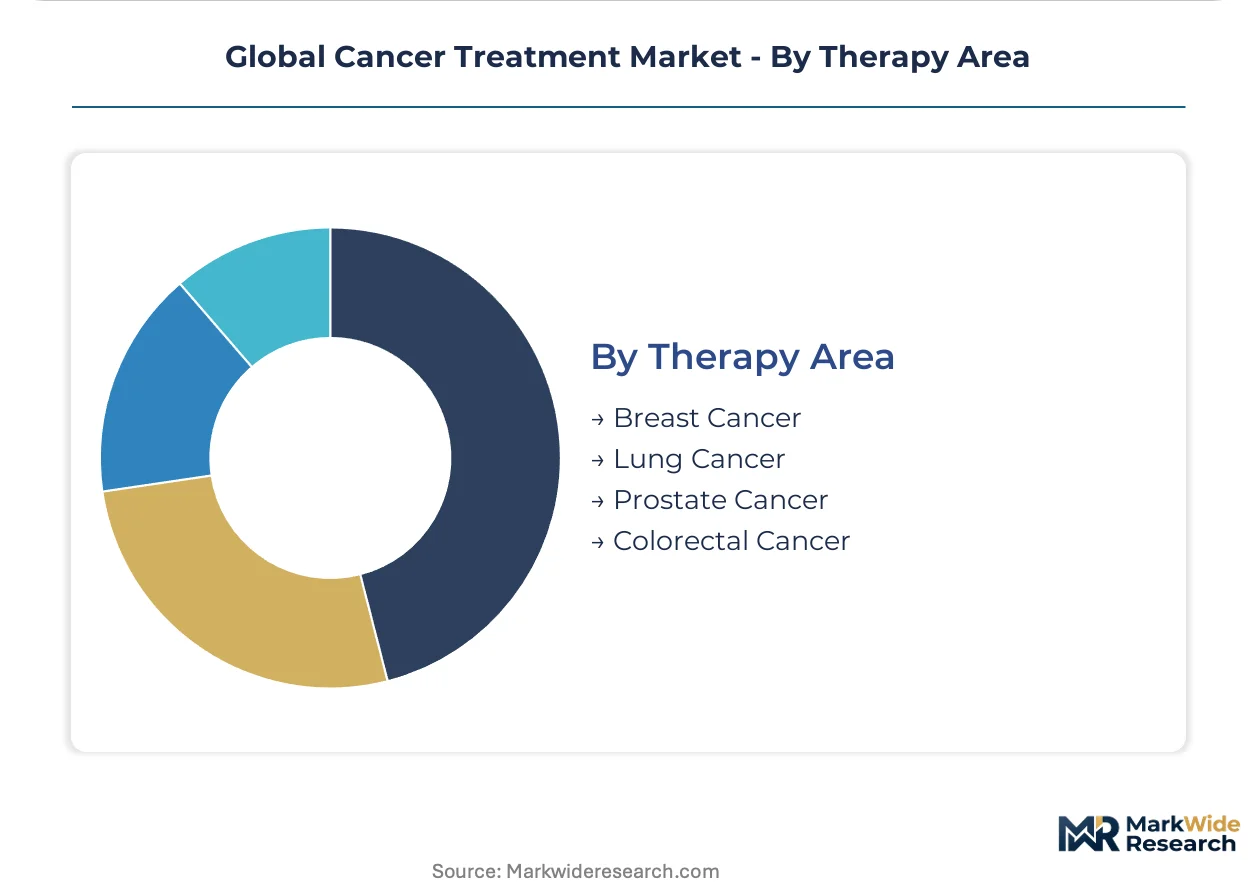
Therapy Area:
Geography of disease incidence and screening penetration creates divergent addressable populations across malignancy types, with lung and breast cancer commanding the largest absolute patient volumes.
- Lung Cancer:Non-small cell histologies drive precision oncology adoption with EGFR, ALK, and PD-L1 biomarker stratification. China's tobacco-related incidence and Japan's screening infrastructure generate the largest Asian patient pools for targeted therapy trials.
- Breast Cancer:HER2-directed and hormone receptor-targeted protocols span early and metastatic settings. Germany's mammography screening program and United States community oncology networks concentrate adjuvant therapy demand.
- Colorectal Cancer:MSI-high and RAS wild-type biomarkers select for immunotherapy and anti-EGFR approaches. France's national cancer institute (INCa) coordinates molecular profiling standardization.
- Prostate Cancer:Androgen deprivation combinations and radioligand therapies address castration-resistant progression. United States urology practice consolidation and United Kingdom NHS prostate cancer pathways shape treatment sequencing.
Breast cancer holds established protocol volume. Lung cancer is rotating up the share rankings through biomarker expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Immunotherapy protocols dominate United States treatment patterns while Asian markets emphasize biosimilar substitution and cost-containment pathways. European systems balance reference pricing with accelerated access schemes for breakthrough therapies. Each geography deploys distinct regulatory levers to manage budget impact against clinical innovation.
United States
Hospital outpatient departments and integrated delivery networks control access to cellular therapies and complex biologics. The FDA's accelerated approval pathways compress commercialization timelines for checkpoint inhibitors. Texas and Florida health systems negotiate enterprise-wide contracts spanning infusion pharmacy and specialty distribution.
Germany
Ambulante Krebszentren concentrate infusion capacity outside hospital walls, shifting biologic administration toward community settings. The Federal Joint Committee (G-BA) mandates head-to-head survival data for premium reimbursement. Bavaria and North Rhine-Westphalia anchor manufacturing for plasma-derived raw materials and monoclonal antibody production.
China
Domestic biotech firms exploit NMPA streamlined timelines for biomarker-defined oncology indications. The National Reimbursement Drug List expansion includes locally manufactured PD-1 inhibitors. Shanghai and Beijing clusters attract Phase II and III trial investment through cost advantages in patient recruitment.
Japan
PMDA conditional early approval pathways for regenerative medicines compress review periods for autologous cell therapies. The Sakigake designation system prioritizes innovative oncology assets. Tokyo and Osaka medical centers concentrate liquid nitrogen logistics infrastructure for CAR-T distribution.
India
CDSCO streamlined oncology study approvals attract global sponsors seeking enrollment velocity. The PLI scheme for pharmaceuticals incentivizes local production of oral oncology generics. Maharashtra and Gujarat house contract research organizations managing multinational trial operations.
Global Cancer Treatment Market Vendor Landscape
Capability concentration sits with integrated diagnostic-to-treatment ecosystems; scale advantage sits with broad oncology portfolios spanning multiple mechanisms. The market structures around three tiers: full-stack biopharmaceutical conglomerates, precision oncology specialists, and biosimilar manufacturers. Dominant competitive moves include diagnostic partnership formations and subcutaneous formulation investments that reduce site-of-care dependency.
Within the full-stack tier, F. Hoffmann-La Roche Ltd. and Bristol-Myers Squibb Company occupy positions defined by vertical control over companion diagnostics and checkpoint inhibitor development. Merck & Co., Inc. exemplifies the precision-scale archetype through sustained clinical trial investment across combination regimens. These three Swiss and American entities anchor competitive dynamics in solid tumor and hematologic malignancy applications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Pfizer Inc. |
| Novartis AG |
| AbbVie Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Plasma fractionation capacity in North America and Europe constrains monoclonal antibody output, anchoring margin pools with manufacturers commanding captive immunoglobulin supply. Contract structures for oncology biologics separate long-term offtake agreements for hospital systems from spot purchasing by independent infusion centers.
Pricing Analysis
Long-term offtake contracts dominate hospital system procurement, while independent oncology practices negotiate spot-based purchasing for single treatment episodes. Price differentiation rests on FDA breakthrough therapy designation and companion diagnostic bundling, with certified biologics commanding premium positioning. Cost compression in the chemotherapy tier intensifies as Indian and Chinese generic manufacturers expand oral oncology production. Community oncology practices exhibit the highest price sensitivity, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Upstream feedstock for plasma-derived therapies concentrates in the United States, Germany, and Austria, where fractionation infrastructure has consolidated among three major suppliers. Raw material dependencies span immunoglobulin, albumin, and recombinant protein media for cell culture propagation. Single-source vulnerability in viral vector manufacturing for CAR-T production creates bottleneck exposure for autologous therapies. Distribution runs through cold-chain logistics providers specializing in liquid nitrogen transport for cellular therapies, with hospital outpatient departments serving as the terminal node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States integrated delivery networks consolidate vendor relationships, reducing oncology biologic supplier counts by half across major health systems. Hospital procurement committees now negotiate enterprise-wide contracts spanning infusion pharmacy, specialty distribution, and pathology services.
For Market Incumbents: Build diagnostic-to-treatment ecosystem moats by deepening companion diagnostic partnerships and securing exclusive biomarker access. Incumbent manufacturers must expand subcutaneous formulation pipelines to reduce site-of-care dependency, while simultaneously defending against biosimilar erosion through sustained clinical trial investment in combination regimens. The priority lever centers on locking in molecular profiling infrastructure within hospital systems.
For New Entrants and Emerging Players: Build out artificial intelligence-enabled target identification capabilities to compress discovery timelines against established discovery engines. White-space opportunities concentrate in India's CDSCO-streamlined trial infrastructure and Japan's PMDA conditional approval pathways for regenerative medicines. Community oncology channel partnerships offer the most penetrable entry point, bypassing consolidated hospital procurement committees through direct distribution relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract development organizations facing viral vector capacity constraints for cell therapy manufacturing. Long-term viability framing favors platforms with demonstrated manufacturing scale-up feasibility and regulatory approval across multiple jurisdictions. The inflection signal to watch is reimbursement evidence threshold tightening in Germany and France, where head-to-head survival data mandates will separate viable assets from stranded pipeline candidates.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | FDA breakthrough therapy designation requires biomarker co-development with diagnostic manufacturers. |
| Subcutaneous Formulation Investment | Roche's Phesgo demonstrates manufacturing feasibility for high-concentration biologic delivery. |
| CDSCO Trial Relocation | India's streamlined oncology approvals attract Phase II and III investment for enrollment velocity. |
| Viral Vector Capacity Expansion | Autologous cell therapy production depends on contract manufacturing organization scale-up feasibility. |
| Real-World Evidence Infrastructure | Structured oncology data capture supports outcome-based contracting with United States payers. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base. Primary interview findings combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling and top-down revenue triangulation cross-checked segmentation outputs.
Scenario-bracketing framed analytical outputs across the projection horizon, with CAGRs derived from treatment-line expansion rates and biomarker penetration curves. Segmentation dimensions spanned product type, delivery mode, end-user setting, therapy area, and regional regulatory cluster. Forecast inputs incorporated clinical trial success probabilities and reimbursement pathway timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar manufacturers or AI-native drug discovery platforms would shift outcomes. Cross-checking against CMS Medicare data and hospital procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Ovarian Cancer Market
Oncology
North America Veterinary Oncology Market
Oncology
Radiation Therapy Software Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Hadron Therapy Market
Oncology
Global Interventional Oncology Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Global Particle Therapy Market
Oncology
Glottic Cancer Treatment Market
Oncology
Breast Cancer Therapy Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Colorectal Cancer Screening Market
Oncology
Metastatic Melanoma Market
Oncology
Laser Cancer Therapy Market