
 Urology Forceps Market | 2026-2036
Urology Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Forceps Market Intelligence
Revenue from single-use, disposable forceps is reshaping the profit pools previously held by reusable instrument sterilization and repair services. This shift favors large-scale manufacturers with robust supply chains. Boston Scientific Corporation leverages its extensive distribution network in minimally invasive devices. Olympus Corporation specializes in integrated endoscopic systems, while KARL STORZ sustains a strong position in high-end reusable instrumentation.
Urology forceps are specialized surgical instruments designed for grasping, manipulating, or retrieving tissue, stones, and foreign objects within the urinary tract. They are typically manufactured from surgical-grade stainless steel with precise jaw configurations. The demand for Biopsy Forceps is driven by early cancer detection protocols, while Stone Forceps are essential for lithotripsy procedures. Hospitals remain the largest end-user segment, but Ambulatory Surgical Centers represent the fastest-growing channel due to procedural shifts.
Market access is governed by stringent regulatory frameworks. The US FDA's 510(k) clearance process and Europe's CE marking under the Medical Device Regulation (MDR) dictate design and safety standards. Japan's PMDA imposes similar requirements for device approval. The critical decision for healthcare providers involves balancing the upfront cost of reusable systems against the per-procedure cost and infection control benefits of single-use forceps.
Market Dynamics
The central tension shaping the urology forceps market is the conflict between healthcare providers' cost-containment mandates and escalating regulatory requirements for clinical evidence and post-market surveillance, particularly for single-use devices which alter traditional hospital procurement models.
Growth Catalysts
- Biopsy Demand:The rising incidence of urological cancers and the implementation of standardized early detection protocols in developed nations drive consistent demand for specialized biopsy forceps within oncology departments and diagnostic centers.
- Ambulatory Surgical Centers:A procedural shift towards minimally invasive surgeries in outpatient settings, especially in the US and Germany, fuels growth in ASCs, which favor efficient, single-use forceps to maximize patient throughput and minimize sterilization overhead.
- Regulatory Upgrades:The EU's Medical Device Regulation (MDR) elevates the standards for device safety and performance, creating a catalyst for premium, well-documented forceps and favoring manufacturers with strong clinical data and quality management systems.
Market Restraints
- Capital Cost of Reusables:The significant upfront investment required for high-end reusable forceps systems, coupled with the ongoing costs of sterilization and repair infrastructure, acts as a barrier for smaller clinics and hospitals in emerging economies.
- Alternative Technologies:The advancement of non-forceps techniques, such as advanced laser lithotripsy and holmium laser enucleation of the prostate (HoLEP), can reduce the necessity for stone forceps or tissue grasping instruments in certain procedures.
- Stringent Approval Timelines:The rigorous data submission and review process for the US FDA's 510(k) clearance and Japan's PMDA approval can create lengthy delays for market entry, constraining the pace of new product introductions from smaller innovators.
Strategic Opportunities
- Emerging Market Modernization:Healthcare infrastructure upgrades in countries across Southeast Asia and Latin America present an opportunity for manufacturers to introduce both reusable and single-use forceps to hospitals transitioning to modern surgical standards.
- Smart Instrument Integration:There is an opportunity to embed micro-sensors or fiber optics into forceps tips to provide surgeons with real-time tactile feedback, tissue-type differentiation, or pressure measurement, enhancing procedural safety and precision.
- Bundled Consumable Contracts:Manufacturers can create value by offering bundled contracts to large hospital networks and ASCs, combining single-use forceps with other disposable urology supplies, streamlining procurement for providers.
Industry Challenges
- Supply Chain Vulnerability:The reliance on specialized surgical-grade stainless steel and third-party sterilization services creates supply chain vulnerabilities for single-use forceps, with disruptions impacting availability and per-unit costs for manufacturers.
- Instrument Standardization Gaps:A lack of universal standardization in handle ergonomics, jaw patterns, and shaft lengths across different manufacturers complicates training and can lead to inefficiencies or errors when surgical teams switch between brands.
- Post-Market Surveillance Burden:Fulfilling the extensive post-market surveillance and reporting requirements mandated by the EU MDR and other regulators imposes a significant and ongoing operational and financial burden on all device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Forceps Market |
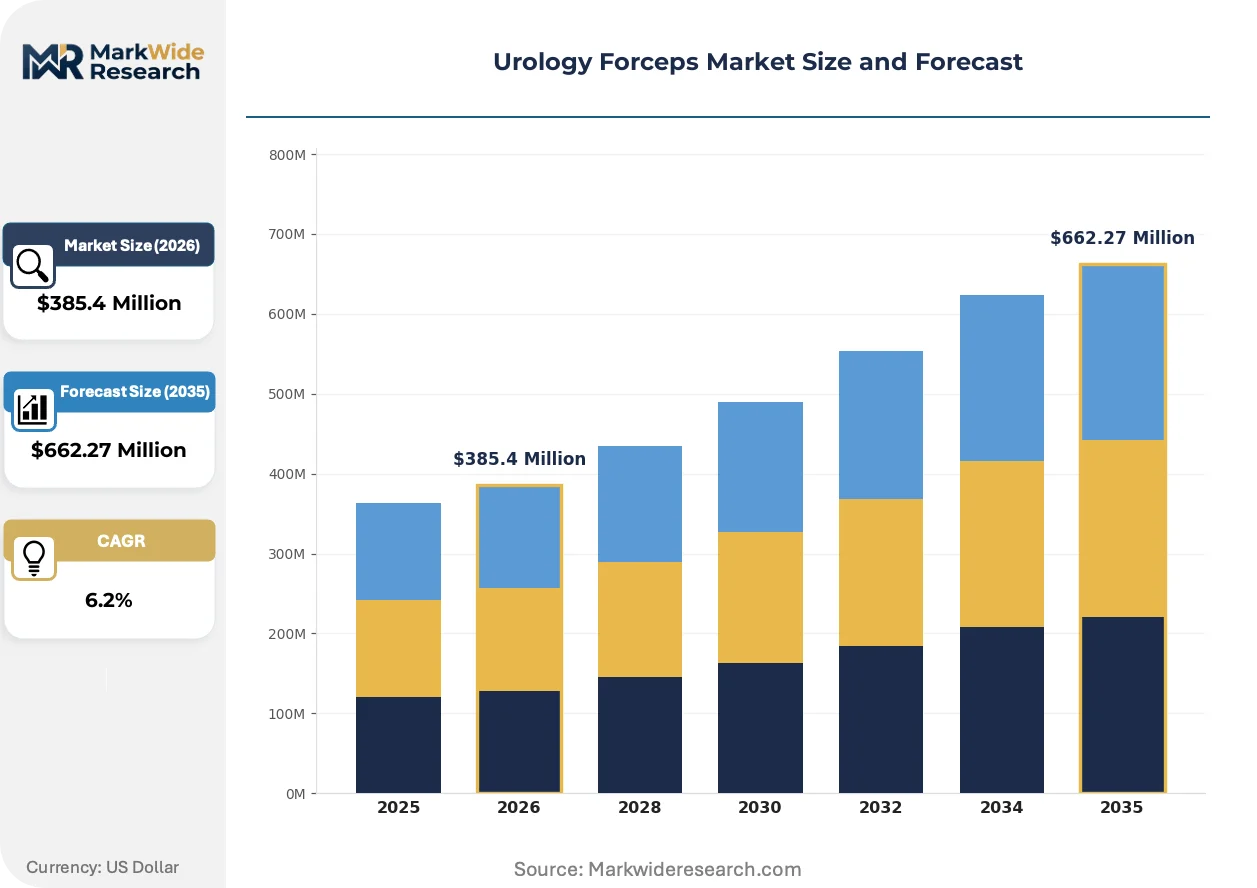
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grasping Forceps, Stone Forceps, Biopsy Forceps, Alligator Forceps, Balloon Forceps Material: Stainless Steel, Titanium, Plastic Handle, Carbon Steel, Silicone Grip Application: Urinary Stone Removal, Tissue Biopsy, Foreign Body Retrieval, Catheter Placement, Endoscopic Surgery End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Urology Clinics, Specialty Surgical Centers |
| Companies Covered | Boston Scientific Corporation, Medtronic, Olympus Corporation, Cook Medical, B. Braun Melsungen AG, KARL STORZ, Richard Wolf, Stryker, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Forceps Market Strategic Shifts & Innovations
Innovation in the urology forceps market is driven by the dual objectives of improving procedural outcomes in minimally invasive surgery and optimizing workflow efficiency. This is leading to developments in instrumentation that enhance surgeon control while addressing the economic and safety priorities of healthcare institutions.
Advanced materials and articulation mechanisms are defining the next generation of forceps. These instruments, often designed for robotic-assisted or complex laparoscopic procedures, feature enhanced flexibility and multi-angled jaw actuation. Specialized urology centers within large academic hospitals are the primary adopters, seeking to improve access and manipulation in constrained anatomical spaces. This evolution is hybridizing the tactile skill of manual surgery with the enhanced precision of advanced platforms.
Europe's Medical Device Regulation (MDR) is forcing a fundamental shift in data management and supply chain transparency. The regulation's Unique Device Identification (UDI) system mandates that every individual device be traceable from factory to patient, increasing the administrative workload. Manufacturers of both single-use and reusable forceps are most affected, compelling significant investment in new labeling technologies and robust digital tracking systems to maintain market access within the EU.
Value analysis committees are increasingly influencing purchasing decisions within consolidated hospital systems. This shift moves the decision-making process away from individual surgeon preference and toward a more data-driven evaluation of total cost of ownership, infection control benefits, and procedural efficiency. The traditional sales model focused on physician relationships is being displaced by one that must justify clinical and economic value to administrative stakeholders. This trend is most prominent in the United States and Western European healthcare systems.
Urology Forceps Market Segmentation
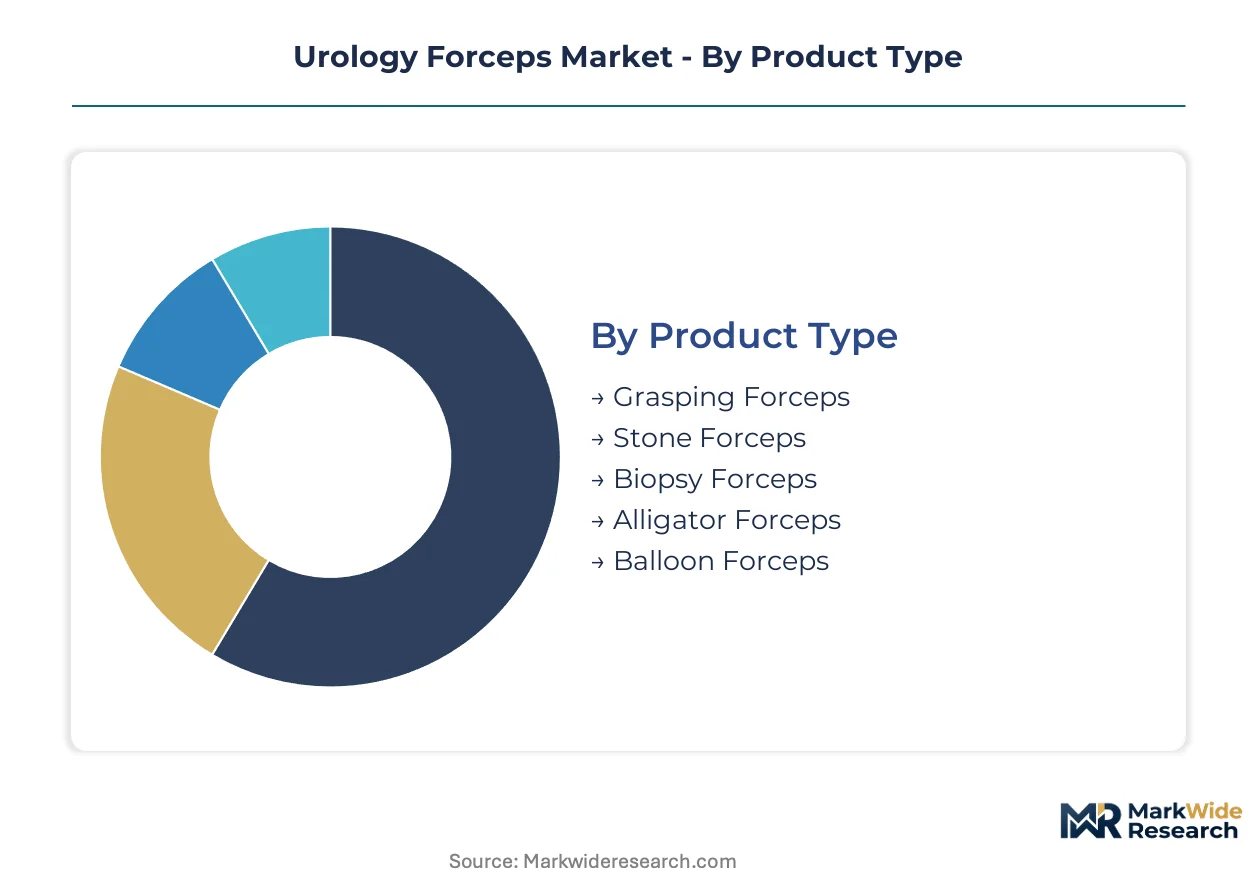
Understanding the Urology Forceps Market through segmentation reveals critical insights into product utility and end-user demand. This granular analysis differentiates instruments by design, material, application, and purchasing entity, highlighting where innovation and investment are most impactful. It provides a framework for manufacturers to align product development with evolving clinical needs.
Product Type:
Product type segmentation delineates the functional specialization of urology forceps, addressing distinct procedural requirements within the urinary tract.
- Biopsy Forceps:These instruments feature precise jaw mechanisms designed for excising small tissue samples from the bladder, ureter, or kidney. Demand concentrates in oncology departments and diagnostic centers in Germany and the United States, driven by early cancer detection protocols and increasing screening volumes.
- Stone Forceps:Engineered with robust jaws and often a basket-like configuration, these forceps grasp and retrieve urinary calculi during lithotripsy and ureteroscopy. Hospitals in developed healthcare systems, particularly in Japan, utilize these for common urological procedures, minimizing the need for more invasive interventions.
- Grasping Forceps:These general-purpose instruments manipulate tissue or retrieve foreign objects during various endoscopic urological procedures.
- Alligator Forceps:Characterized by their serrated jaws, these forceps provide a secure grip for removing small, irregular foreign bodies or tissue fragments.
- Balloon Forceps:Combining a grasping mechanism with an inflatable balloon, these instruments are used for dilating strictures or retrieving objects by creating a seal.
Biopsy Forceps commands the established base. The steepest expansion runs through specialized Stone Forceps optimized for advanced laser lithotripsy procedures.
Material:
The material composition of urology forceps directly impacts instrument performance and procedural suitability, influencing durability and sterilization methods.
- Stainless Steel:This material forms the backbone of reusable urology forceps due to its corrosion resistance, strength, and ability to withstand repeated sterilization cycles. Hospitals in Western Europe, including France and Italy, prioritize these for their long-term cost-effectiveness and durability.
- Titanium:Offering superior strength-to-weight ratio and MRI compatibility, titanium forceps are preferred for delicate or complex procedures requiring minimal interference. Specialty surgical centers in the United States increasingly adopt titanium instruments for advanced robotic-assisted surgeries.
- Plastic Handle:Often integrated with single-use forceps, plastic handles reduce manufacturing costs and eliminate the need for sterilization between procedures.
- Carbon Steel:Used for specific cutting components, carbon steel provides exceptional sharpness, though it requires specialized coatings for corrosion resistance.
- Silicone Grip:Incorporated into handles, silicone enhances surgeon ergonomics and provides a non-slip surface, improving control during lengthy procedures.
Stainless Steel remains the foundational material choice for traditional instruments, while Titanium offers specialized benefits for advanced surgical platforms.
Application:
Procedural application defines the specific surgical utility and design requirements for urology forceps across the spectrum of interventions.
- Tissue Biopsy:This application drives demand for forceps capable of precise tissue acquisition for histological examination, crucial in diagnosing urological malignancies. Diagnostic centers and hospitals globally, particularly in the UK and Canada, rely on these for early cancer detection protocols.
- Urinary Stone Removal:Forceps designed for this application aid in fragmenting or extracting renal and ureteral stones, often complementing laser lithotripsy techniques. Hospitals with high volumes of urolithiasis cases, such as those in India and Brazil, frequently procure these instruments.
- Foreign Body Retrieval:This application involves using forceps to safely remove inadvertently placed or migrated objects from the urinary tract.
- Catheter Placement:Forceps assist in guiding and securing catheters within the urinary system, ensuring accurate positioning and minimizing trauma.
- Endoscopic Surgery:This broad application covers the use of forceps in various minimally invasive procedures performed through endoscopes for diagnosis and treatment.
Tissue Biopsy applications consistently generate high demand, while Endoscopic Surgery represents a broad and evolving area of forceps utility.
End User:
The end-user landscape for urology forceps reflects diverse institutional needs and operational priorities, from large hospitals to specialized outpatient centers.
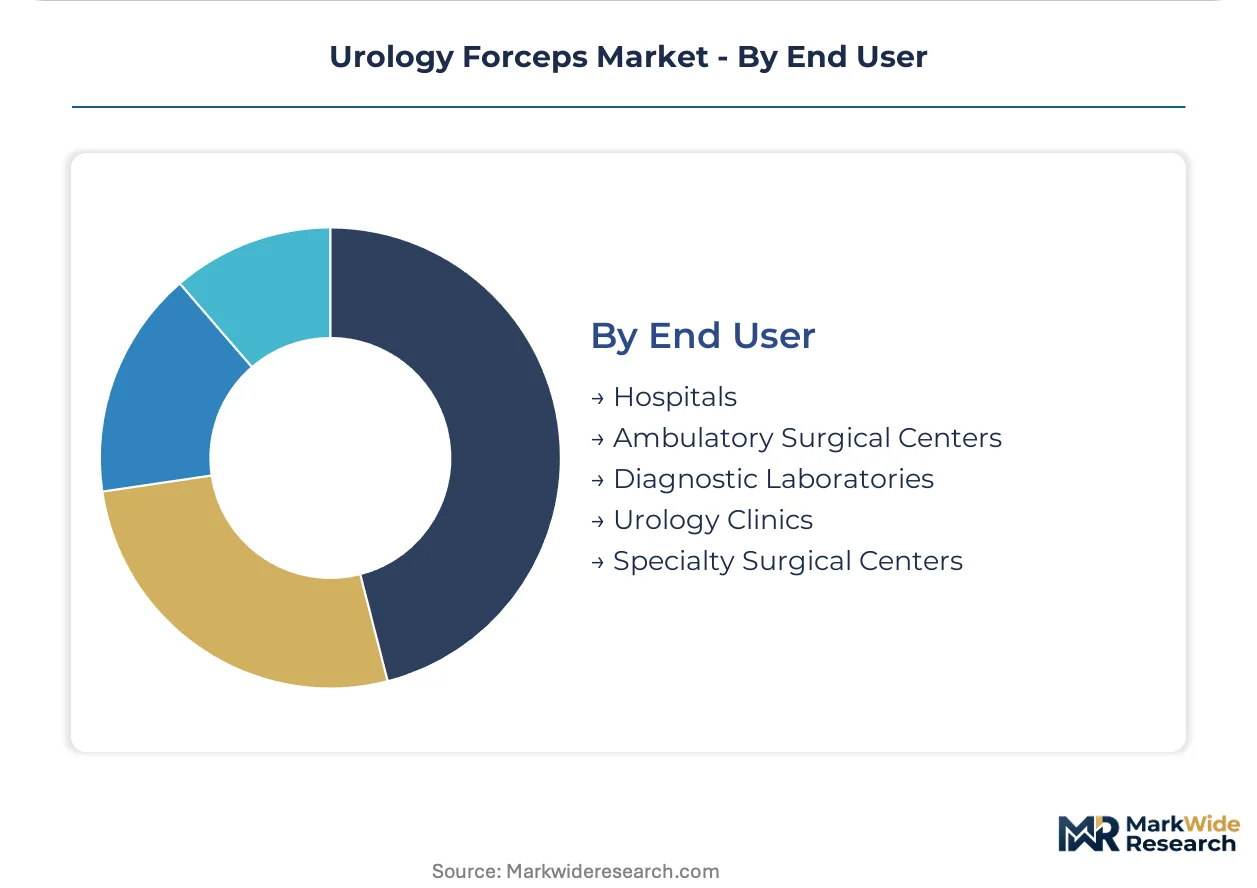
- Hospitals:These institutions represent the largest end-user segment, procuring a wide array of urology forceps for complex surgeries, emergency procedures, and inpatient care. Large academic hospitals in the United States and China maintain extensive inventories for their comprehensive urology departments.
- Ambulatory Surgical Centers:ASCs are the fastest-growing end-user segment, prioritizing single-use forceps for their efficiency, infection control benefits, and rapid patient turnover. These centers in countries like Australia and Canada focus on outpatient minimally invasive urological procedures.
- Diagnostic Laboratories:These facilities utilize specialized biopsy forceps primarily for tissue sample collection, supporting urological pathology analysis.
- Urology Clinics:Outpatient clinics employ forceps for minor diagnostic procedures and simple interventions, often favoring reusable instruments for cost control.
- Specialty Surgical Centers:These centers focus on specific urological sub-specialties, demanding highly specialized forceps tailored to their niche procedural volumes.
Hospitals remain the dominant procurement channel, but Ambulatory Surgical Centers represent the fastest-growing trajectory for urology forceps adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global urology forceps market exhibits varying demand elasticity, with developed healthcare systems prioritizing advanced features and infection control benefits over upfront cost. Conversely, emerging economies often balance initial capital expenditure with long-term durability for reusable instruments. This regional divergence shapes procurement strategies and product adoption cycles.
United States
Demand for biopsy forceps is driven by early cancer detection protocols and the expansion of ambulatory surgical centers. The US FDA's 510(k) clearance process dictates market entry and product innovation. Major medical device clusters in places like the Greater Boston area focus on developing integrated endoscopic systems.
Germany
Germany's extensive hospital network creates consistent demand for both single-use and high-end reusable urology forceps. The EU's Medical Device Regulation (MDR) significantly elevates clinical evidence requirements for manufacturers. The Munich region, a hub for medical technology, sees continuous investment in advanced surgical instrument design.
Japan
Specialized stone forceps are essential for lithotripsy procedures, driven by a high prevalence of urolithiasis cases. Japan's PMDA imposes rigorous approval timelines, influencing new product introductions. Medical device manufacturing in the Kanto region emphasizes precision engineering for minimally invasive instruments.
India
Hospitals with high volumes of urolithiasis cases frequently procure instruments for urinary stone removal, reflecting a large patient population. The Central Drugs Standard Control Organization (CDSCO) regulates medical device imports and manufacturing standards. Chennai, a growing medical tourism destination, is expanding its surgical capabilities.
Australia
Ambulatory Surgical Centers (ASCs) in Australia are rapidly adopting single-use forceps for outpatient minimally invasive urological procedures. The Therapeutic Goods Administration (TGA) ensures device safety and performance through its regulatory framework. Sydney's health precincts integrate advanced surgical technologies to enhance patient throughput.
Urology Forceps Market Key Industry Players
Vertically integrated device manufacturers and specialized instrument producers split the market for urology forceps, influencing competitive positioning. The market exhibits a tiered structure, with global players dominating high-volume segments and niche specialists serving complex procedural needs. Strategic partnerships often drive technology co-development, while targeted acquisitions expand product portfolios across different urological applications. Geographic expansion into emerging markets also represents a common competitive move.
Within the segment of large-scale medical technology providers, Boston Scientific Corporation exemplifies a broad distribution network in minimally invasive devices, representing a significant force in single-use product supply across various urological procedures. Olympus Corporation, known for its integrated endoscopic systems, occupies a position in advanced visualization and instrumentation, often bundling forceps with larger capital equipment solutions. KARL STORZ, a privately held company, anchors the high-end reusable instrumentation sector, focusing on precision engineering and durability for specialized surgical environments requiring long-term investment.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Olympus Corporation |
| Cook Medical |
| B. Braun Melsungen AG |
| KARL STORZ |
| Richard Wolf |
| Stryker |
| BD |
| Others |
Cost & Logistics Intelligence
The specialized logistics corridor for surgical instruments between manufacturing hubs in Germany and consumption markets in the United States directly influences cost dynamics, shaping both supply concentration and downstream price differentiation. This reflects the high value and regulatory requirements for medical device transport.
Pricing Analysis
After-sales revenue from sterilization and repair services for reusable instruments significantly drives lifetime value for manufacturers. The market operates on a hybrid pricing model, combining per-unit transactional pricing for disposables with long-term service contracts for reusable systems. Price differentiation stems from the quality grade of materials, such as surgical-grade stainless steel versus titanium, and the level of regulatory certification. Pricing softness stems from healthcare providers' cost-containment mandates. Ambulatory Surgical Centers exhibit the highest price sensitivity, while large academic hospitals prioritize advanced features over initial cost.
Supply Chain Analysis
Supply chain vulnerability stemming from reliance on specialized surgical-grade stainless steel and third-party sterilization services presents a structural risk for single-use forceps manufacturers. Geographic supply concentrates in Germany, the United States, and Japan for high-end manufacturing, with raw material sourcing often drawing from broader global markets. Key raw material dependencies include surgical-grade stainless steel, titanium alloys, and specialized polymers for handles. Distribution runs through a mix of direct sales to large hospital networks and extensive distributor networks serving smaller clinics and Ambulatory Surgical Centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by advancements in minimally invasive surgical techniques and the elevating standards mandated by the EU's Medical Device Regulation.
For Market Incumbents: Build a regulatory compliance moat by proactively investing in robust clinical evidence and quality management systems for new and existing products. Consolidate market share by expanding bundled consumable contracts with large hospital networks, mitigating the threat from niche specialists. Leverage existing distribution networks to accelerate the adoption of single-use devices, addressing infection control concerns.
For New Entrants and Emerging Players: Establish a beachhead in rapidly expanding Ambulatory Surgical Centers by offering cost-effective, high-efficiency single-use forceps. Target emerging markets in Southeast Asia and Latin America, where healthcare infrastructure upgrades create opportunities for both reusable and disposable instruments. Focus go-to-market strategies on demonstrating clear infection control benefits and workflow efficiencies to administrative stakeholders.
For Investors and Strategic Acquirers: Specialized software developers for smart instrument integration represent an attractive acquisition target archetype, enhancing precision and data capture. The long-term viability of the market is anchored by an aging global population and the rising incidence of urological cancers. The adoption rate of advanced endoscopic platforms in Ambulatory Surgical Centers is a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | Ensures continued market access in Europe and builds a strong foundation for global regulatory adherence. |
| Bundled Consumable Contracts | Secures long-term revenue streams and streamlines procurement for large healthcare systems. |
| Smart Instrument R&D | Enhances procedural safety and precision, differentiating products in a competitive landscape. |
| Emerging Market Expansion | Captures growth from modernizing healthcare infrastructure in underserved regions. |
| GPO Partnership Development | Facilitates broader market penetration and efficient sales to consolidated hospital networks. |
Research Approach
The analysis maps key sub-sectors, including biopsy forceps, stone forceps, and grasping forceps, each validated through primary interviews with urologists, hospital procurement managers, ASC administrators, and medical device engineers. Secondary validation draws from sources such as FDA 510(k) clearances, CE marking databases, specialized medical journal articles, and industry association reports. A robust triangulation approach combines both bottom-up market sizing with top-down validation.
The forecast framework assumes a stable regulatory environment and consistent global healthcare spending growth across the analysis window. Segmentation dimensions modeled include product type, material, application, end-user, and geographic region. Compound Annual Growth Rates (CAGRs) were derived using regression analysis and market penetration models. Key forecast inputs include the incidence rates of urological cancers and the increasing volume of minimally invasive surgical procedures.
Sensitivities concentrate around unforeseen technological breakthroughs or major shifts in healthcare reimbursement policies. Forecasts reflect assumptions documented through extensive primary and secondary research. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Disposables Market
Urology
Global Bladder Scanner Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Urology Lasers Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Europe Urology Devices Market
Urology
Europe Bladder Disorders Market
Urology
Global Lithotripsy Market
Urology
Self-Intermittent Catheters Market
Urology
Global Nephrology and Urology Devices Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Urinary Tract Infection Testing Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Global Bladder Cancer Market
Urology
Botulinum Toxin in Urology Market