
 Disposable Ureteroscope Market | 2026-2036
Disposable Ureteroscope Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Ureteroscope Market Intelligence
Subscription-based reprocessing alternatives and per-procedure procurement bundles is realigning how hospitals source ureteroscope capacity, shifting capital expenditure into operational line items. Karl Storz GmbH leverages its rigid scope heritage to anchor premium positioning in European urology suites. Ambu A/S competes through dedicated single-use manufacturing scale, while Boston Scientific Corporation extends its endourology ecosystem with integrated retrieval and lithotripsy accessories.
A disposable ureteroscope is a single-use endoscopic instrument featuring a working channel of 1.2–3.6 Fr and deflection angles reaching 270°, constructed from medical-grade polymers with fiber optic or digital CMOS distal tips, designed for retrograde visualization and intervention within the upper urinary tract. Flexible ureteroscopes command the dominant revenue share due to their maneuverability through the intrarenal collecting system, while digital imaging technology displaces fiber optic platforms as CMOS sensors deliver superior resolution at reduced unit cost. Stone removal applications absorb the largest procedure volume, though diagnostic indications expand as outpatient settings seek to minimize reprocessing infrastructure.
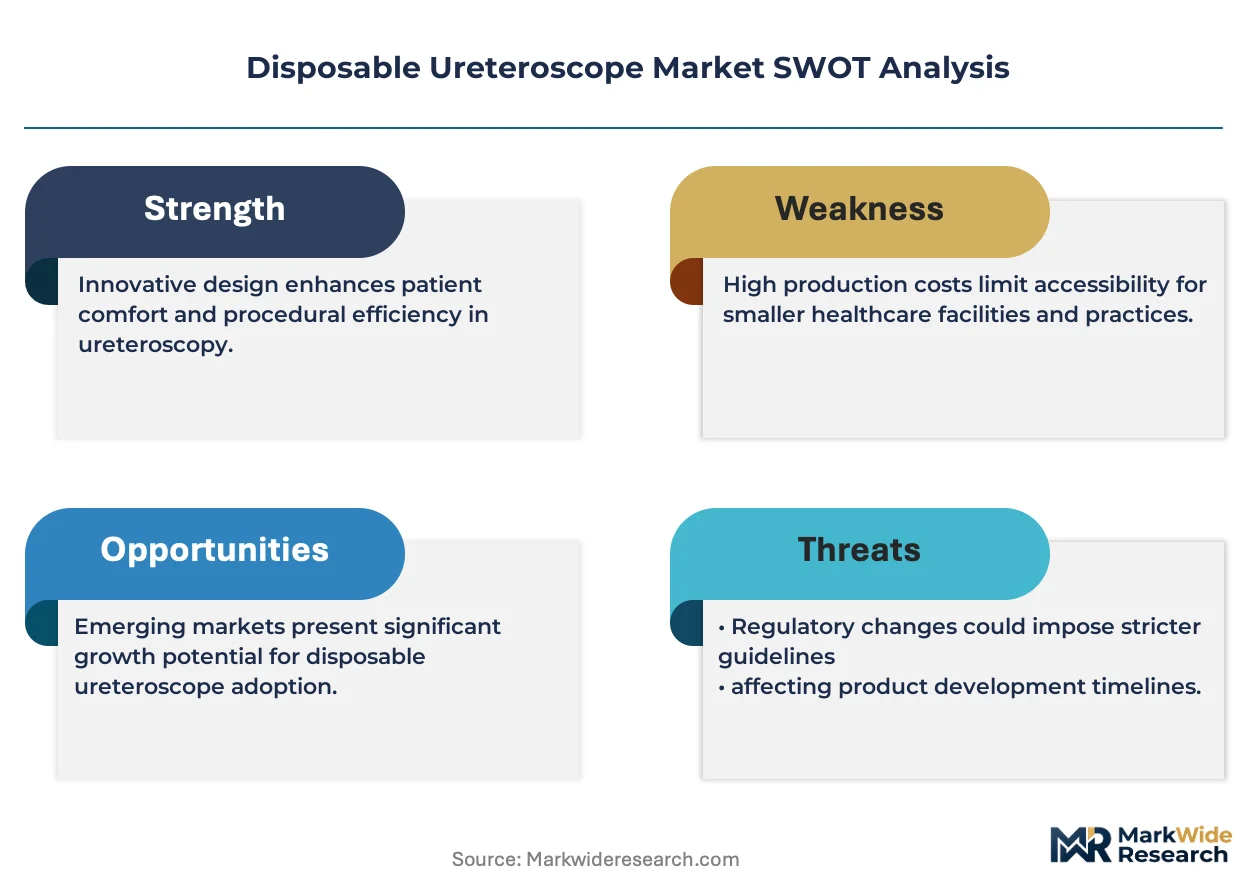
FDA 510(k) clearance requirements and EU MDR technical documentation for sterile single-use endoscopes shape product development timelines and market access costs, with notified bodies demanding enhanced biocompatibility and sterility assurance data. Japan's PMDA and China's NMPA impose additional clinical evaluation standards that fragment registration pathways across major jurisdictions. Stakeholders must monitor reimbursement recalibration for single-use procedures against reusable reprocessing costs as health technology assessment bodies scrutinize life-cycle economics.
Market Dynamics
The transition from fiber optic to digital CMOS imaging platforms is compressing manufacturing costs while elevating diagnostic fidelity, forcing reprocessing-dependent reusable scope vendors to defend installed base economics against single-use alternatives.
Growth Catalysts
- EU MDR sterility mandates:The Medical Device Regulation's enhanced biocompatibility documentation requirements for reusable endoscopes extend revalidation timelines, tilting hospital capital committees toward pre-sterilized disposable platforms.
- Ambulatory surgical center expansion:Freestanding urology clinics in the United States lack centralized sterile processing departments, making single-use ureteroscopes the only viable option for stone management procedures.
- Polymer extrusion advances:Medical-grade thermoplastic elastomers now achieve deflection angles matching stainless steel braid constructions, eliminating the performance gap that once justified reusable instrument premiums.
Market Restraints
- CMOS sensor supply concentration:Sony and OmniVision control over 70 percent of miniature medical imaging sensor output, creating vulnerability to allocation constraints during semiconductor demand surges.
- Reimbursement misalignment:US CMS procedure codes bundle ureteroscope costs within the surgical fee, preventing separate billing for single-use instruments and masking true economic comparisons.
- Reusable scope aftermarket:Third-party reprocessors in Germany and Japan offer certified reconditioned flexible ureteroscopes at 40-60 percent below OEM replacement pricing, extending competitive pressure.
Strategic Opportunities
- India's urology infrastructure buildout:Government hospital modernization programs under the Ayushman Bharat scheme create first-mover positioning for disposable platforms where reprocessing infrastructure remains underdeveloped.
- Diagnostic indication expansion:Surveillance ureteroscopy for upper tract urothelial carcinoma permits outpatient scheduling without same-day sterilization capacity, opening oncology clinics as a new prescriber segment.
- 5G-enabled remote proctoring:Integration of disposable scopes with low-latency surgical telepresence allows academic medical centers to supervise complex intrarenal procedures at satellite facilities, expanding addressable procedure volume.
Industry Challenges
- ISO 13485 quality management certification:Disposable manufacturers must demonstrate process validation for sterile packaging integrity across accelerated aging studies, extending product development cycles by 12-18 months.
- Legacy EHR integration:Hospital information systems track reusable instrument utilization through RFID asset tags; single-use scopes lack equivalent traceability hooks, complicating supply chain analytics and par level optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Ureteroscope Market |
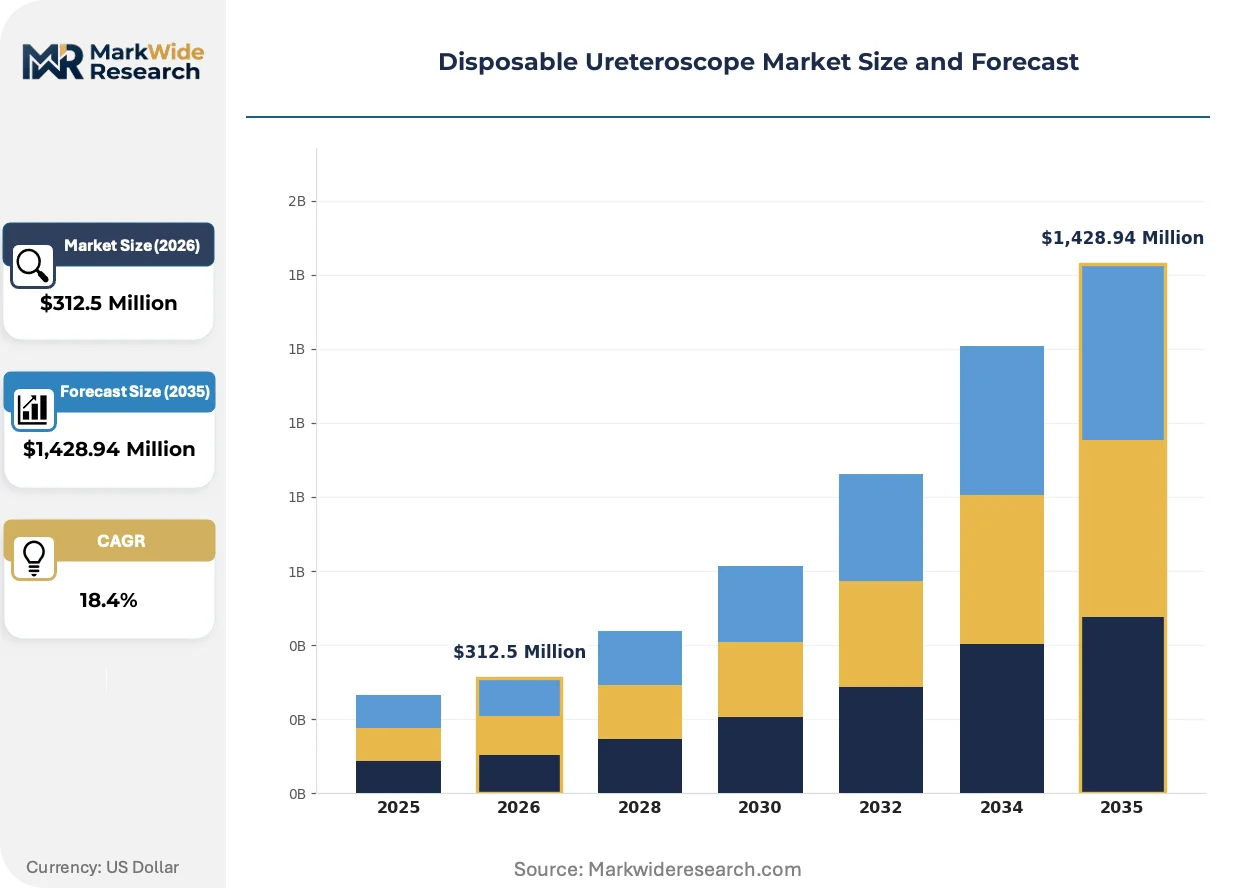
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,428.94 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Ureteroscope, Flexible Ureteroscope, Semi-Rigid Ureteroscope, Others End User: Hospitals, Ambulatory Surgical Centers, Urology Clinics, Specialty Clinics Technology: Fiber Optic, Digital Imaging, Video, Light Guide Technology Application: Stone Removal, Tumor Ablation, Biopsy, Diagnostic Procedures |
| Companies Covered | Karl Storz GmbH, FUJIFILM Holdings Corporation, Boston Scientific Corporation, PENTAX Medical, Ambu A/S, Olympus Corporation, Richard Wolf GmbH, OTU Medical, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Ureteroscope Market Strategic Shifts & Innovations
Digital imaging convergence with polymer miniaturization is collapsing the cost-performance tradeoff that historically protected reusable ureteroscope incumbents, while regulatory sterility requirements harden against reprocessing validation.
CMOS distal chip-on-tip technology is consolidating market preference by eliminating fiber bundle fragility and enabling 720p resolution at sub-$400 unit manufacturing cost. Academic medical centers in Boston and Heidelberg now specify digital platforms for fellowship training programs, accelerating generational turnover in hospital purchasing committees. The technology shift is consolidating procurement decisions around imaging performance rather than instrument longevity, compressing the evaluation criteria set that reusable vendors historically exploited.
Japan's PMDA revised its guidance on sterile single-use endoscopes in 2023, requiring enhanced pyrogen testing and endotoxin validation for polymer instruments contacting urinary mucosa. Domestic manufacturers must submit additional clinical safety data for digital imaging variants, extending registration timelines by eight to fourteen months. The regulatory friction most impacts mid-tier entrants lacking established QMS infrastructure, advantaging diversified endoscopy portfolios with dedicated regulatory affairs functions in Tokyo.
Subscription-based instrument access models are displacing capital purchase cycles for high-volume urology service lines. United States health systems in Texas and Florida now contract for per-procedure ureteroscope availability with guaranteed sterile delivery, converting fixed equipment expenditure into variable cost structures aligned with case volume fluctuation. The purchasing transformation is most visible in hospital-owned ambulatory surgery centers where capital allocation constraints and staffing shortages make reprocessing infrastructure economically unsustainable.
Disposable Ureteroscope Market Segmentation
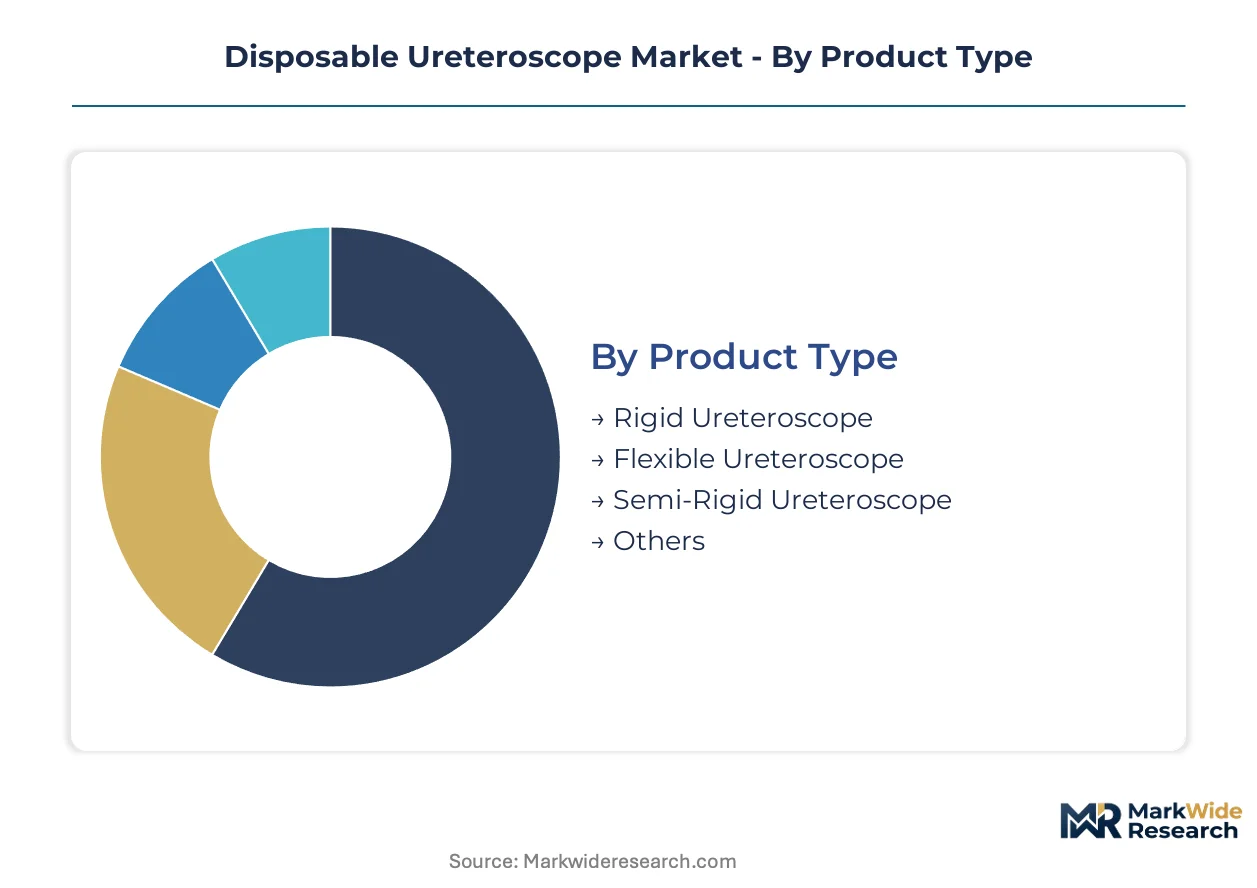
Disposable ureteroscope procurement decisions fragment across instrument flexibility, imaging fidelity, and care setting infrastructure. Each segmentation axis reveals distinct value hierarchies that manufacturers must navigate to secure hospital formulary placement and ambulatory surgery center contracts.
Product Type:
Customization versus standardization tension peaks in instrument construction, where deflection mechanics and working channel diameter trade off against unit economics and sterilization assurance.
- Flexible Ureteroscope:Polymer construction with 270° bidirectional deflection and 1.2–3.6 Fr working channels enables complete intrarenal access. Demand concentrates in United States academic medical centers where fellowship training programs now mandate digital flexible platforms for ureteroscopy credentialing.
- Rigid Ureteroscope:Stainless steel or polymer shaft with 0° or 30° fixed lens orientation serves distal ureter and ureteropelvic junction interventions. German hospital procurement committees favor rigid instruments for lithotripsy suites with established sterilization infrastructure, slowing single-use conversion in this subsegment.
- Semi-Rigid Ureteroscope:Hybrid construction merges proximal shaft rigidity with distal flexibility for mid-ureter navigation.
- Others:Specialty configurations include dual-channel instruments and pediatric-diameter variants for niche anatomical requirements.
Leading the category by volume: Flexible Ureteroscope. Expanding most quickly: Flexible Ureteroscope.
End User:
Capital intensity and sterile processing capacity create sharp procurement bifurcation between integrated health systems and distributed outpatient facilities.
- Hospitals:Inpatient and outpatient surgical departments with centralized sterile processing departments evaluate single-use platforms against per-procedure reprocessing costs. United States health systems in Texas and Florida increasingly contract for subscription-based instrument access to convert fixed capital expenditure into variable operational line items.
- Ambulatory Surgical Centers:Freestanding facilities lack economies of scale for in-house reprocessing infrastructure. These settings drive pure single-use adoption for stone management procedures, with procurement decisions prioritizing guaranteed sterile delivery over unit cost minimization.
- Urology Clinics:Office-based practices performing diagnostic ureteroscopy favor disposable platforms to eliminate same-day sterilization bottlenecks.
- Specialty Clinics:Oncology-focused facilities adopt single-use instruments for upper tract urothelial carcinoma surveillance protocols.
Dominant procurement volume: Hospitals. Steepest expansion trajectory: Ambulatory Surgical Centers.
Technology:
Imaging modality selection determines manufacturing cost structure and diagnostic performance ceiling, with CMOS sensor integration collapsing historical fiber optic premiums.
- Digital Imaging:Distal chip-on-tip CMOS sensors deliver 720p resolution at sub-$400 unit manufacturing cost. Heidelberg and Boston academic centers specify digital platforms for fellowship training, accelerating generational turnover in purchasing committees.
- Fiber Optic:Bundle-based image transmission through coherent fiber arrays remains entrenched in price-sensitive procurement segments. Third-party reprocessors in Germany and Japan extend competitive pressure through certified reconditioned fiber optic instruments at 40–60 percent below OEM replacement pricing.
- Video:External camera coupling to rod-lens systems persists in rigid instrument configurations.
- Light Guide Technology:Illumination pathway optimization for LED distal tip integration in next-generation polymer constructions.
Highest revenue concentration: Digital Imaging. Gaining share fastest: Digital Imaging.
Application:
Procedure complexity and reimbursement bundling shape instrument specification requirements across therapeutic and diagnostic indications.
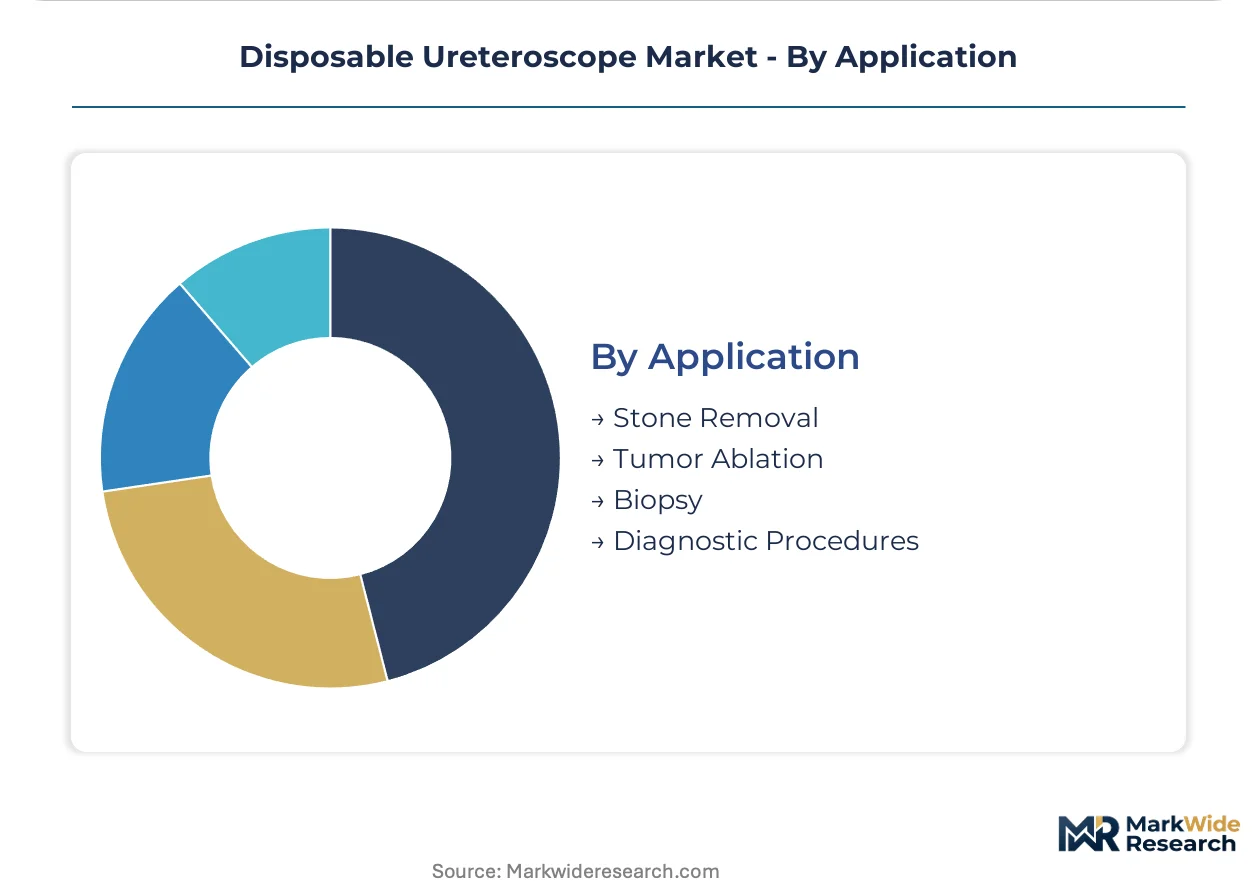
- Stone Removal:Percutaneous and retrograde intrarenal surgery for nephrolithiasis absorbs the largest procedure volume. United States CMS procedure codes bundle ureteroscope costs within surgical fees, complicating separate billing for single-use instruments in this high-volume segment.
- Diagnostic Procedures:Surveillance ureteroscopy for hematuria evaluation and upper tract urothelial carcinoma monitoring permits outpatient scheduling without same-day sterilization capacity. Oncology clinics in Japan and Germany emerge as new prescriber segments following expanded indication labeling.
- Tumor Ablation:Laser and electrosurgical intervention for papillary lesions requires specialized working channel configurations.
- Biopsy:Tissue acquisition for histopathological confirmation drives demand for instruments with integrated irrigation and suction capability.
Procedure volume leader: Stone Removal. Climbing the fastest: Diagnostic Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American demand for disposable ureteroscopes through its concentration of academic medical centers and fellowship training programs. Heidelberg and Tokyo form complementary innovation clusters driving digital imaging adoption and regulatory advancement across their respective markets.
United States
Texas and Florida health systems drive subscription-based procurement models that convert capital expenditure into operational line items. FDA 510(k) clearance pathways for sterile single-use endoscopes shape product development timelines and market access costs. Greater Boston's academic medical centers specify digital platforms for urology fellowship training, accelerating generational turnover in hospital purchasing committees.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia favor rigid instruments for lithotripsy suites with established sterilization infrastructure. EU MDR technical documentation requirements for reusable endoscopes extend revalidation timelines, tilting capital committees toward pre-sterilized disposable platforms. Third-party reprocessors in Baden-Württemberg offer certified reconditioned flexible ureteroscopes at substantial discounts below OEM replacement pricing.
Japan
PMDA revised guidance on sterile single-use endoscopes in 2023, requiring enhanced pyrogen testing and endotoxin validation for polymer instruments contacting urinary mucosa. Tokyo-based diversified endoscopy portfolios with dedicated regulatory affairs functions capture advantage from extended registration timelines. Kansai region oncology clinics emerge as new prescriber segments for diagnostic ureteroscopy in upper tract urothelial carcinoma surveillance.
India
Government hospital modernization programs under the Ayushman Bharat scheme create first-mover positioning for disposable platforms where reprocessing infrastructure remains underdeveloped. CDSCO registration requirements for sterile urological devices impose clinical evaluation standards that fragment market access pathways. Maharashtra and Karnataka urology infrastructure buildout concentrates demand in metropolitan tertiary care centers.
China
NMPA clinical evaluation standards for digital imaging variants extend registration timelines, advantaging manufacturers with established quality management infrastructure. Yangtze River Delta hospital networks evaluate single-use platforms against per-procedure reprocessing costs as outpatient surgical volume expands. Shanghai academic medical centers drive specification requirements for next-generation polymer constructions with integrated CMOS distal tips.
Disposable Ureteroscope Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the disposable ureteroscope market, creating a tiered competitive structure where manufacturing scale and regulatory infrastructure determine positioning. The vendor base separates into diversified endoscopy incumbents with reusable instrument heritage, dedicated single-use specialists with polymer manufacturing scale, and diversified medical technology conglomerates with integrated lithotripsy ecosystems. Strategic moves concentrate on M&A activity targeting regulatory capabilities and capacity expansion in medical-grade polymer extrusion.
Within the diversified endoscopy tier, Karl Storz GmbH and Olympus Corporation occupy positions anchored by rigid scope heritage and established European urology suite relationships. Ambu A/S exemplifies the dedicated single-use manufacturing archetype with focused polymer production scale. Boston Scientific Corporation represents the integrated ecosystem approach, extending presence through complementary retrieval and lithotripsy accessories rather than standalone instrument competition.
| Leading Market Players |
|---|
| Karl Storz GmbH |
| FUJIFILM Holdings Corporation |
| Boston Scientific Corporation |
| PENTAX Medical |
| Ambu A/S |
| Olympus Corporation |
| Richard Wolf GmbH |
| OTU Medical |
| Stryker |
| Others |
Cost & Logistics Intelligence
Subscription-based procurement mandates from United States health systems in Texas and Florida are forcing manufacturers to restructure production for variable-cost delivery models, compressing margins on standardized flexible ureteroscopes while creating pricing power for integrated digital imaging bundles.
Pricing Analysis
Margin tightening in economy-tier fiber optic instruments reflects third-party reprocessor competition in Germany and Japan. Three-tier pricing structure across premium digital, standard flexible, and economy fiber optic levels differentiates by CMOS sensor grade and EU MDR certification status. Cost-down pressure on standard-tier products accelerates because ambulatory surgical centers prioritize guaranteed sterile delivery over unit cost minimization. Hospital procurement committees show lowest price sensitivity for fellowship-training-specified digital platforms, while independent urology clinics drive hardest bargain on fiber optic alternatives.
Supply Chain Analysis
Reverse logistics for expired sterile packaging and defective CMOS sensors flows through specialized medical waste processors in Ireland and Singapore. Manufacturing concentrates in Denmark, Massachusetts, and Baden-Württemberg for polymer extrusion and distal tip assembly. Production draws from medical-grade thermoplastic elastomers, Sony and OmniVision imaging sensors, and LED illumination modules. Single-source vulnerability in CMOS sensor allocation creates exposure during semiconductor demand surges. Distribution runs through GPO contracts and direct hospital system agreements with just-in-time sterile delivery guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with dedicated polymer manufacturing scale and established regulatory affairs infrastructure in Tokyo and Brussels, squeezing mid-tier entrants lacking ISO 13485 quality management certification.
For Market Incumbents: Lock in hospital system subscription contracts before ambulatory surgical center procurement standardizes around pure single-use platforms. Deepen backward integration into medical-grade thermoplastic elastomer production to defend margin position against polymer price volatility. Prioritize CMOS sensor supply agreements with Sony and OmniVision to secure allocation priority during semiconductor demand cycles. For New Entrants and Emerging Players: Oncology clinic partnerships offer the most penetrable channel for diagnostic ureteroscopy positioning in upper tract urothelial carcinoma surveillance. Target India's Maharashtra and Karnataka tertiary care centers where Ayushman Bharat infrastructure buildout lacks established reprocessing capacity. Pursue CDSCO registration pathway for sterile single-use endoscopes as first-mover advantage in government hospital modernization. For Investors and Strategic Acquirers: Re-rating potential sits with dedicated single-use manufacturers given EU MDR sterility mandate acceleration and reusable scope revalidation timeline extension. Long-term viability favors asset-light designers with regulatory infrastructure in multiple jurisdictions over capital-heavy producers dependent on reusable instrument installed base. Monitor PMDA registration timeline compression for digital imaging variants as inflection indicator for competitive positioning in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for pre-sterilized disposable platforms against reusable alternatives. |
| CMOS Sensor Supply Agreement | Secures allocation priority from Sony and OmniVision during semiconductor demand surges. |
| Ambulatory Surgery Center Partnership | Captures pure single-use adoption in settings lacking reprocessing infrastructure. |
| Subscription-Based Procurement Model | Converts hospital capital expenditure into operational line items aligned with case volume. |
| India CDSCO Registration Pathway | Establishes first-mover positioning in Ayushman Bharat hospital modernization programs. |
Research Approach
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital GPO contract records, complemented by interviews with urology department heads, biomedical engineering directors, sterile processing managers, and procurement committee chairs. Secondary validation drew from CMS procedure code bundling analyses, PMDA guidance documents, and CDSCO registration requirements. Bottom-up procedure volume estimates triangulated against top-down health system expenditure data.
Historical adoption curves for digital imaging platforms cross-referenced against expert panel input on fellowship training specification timelines. Segmentation modeling spanned instrument flexibility, imaging technology, end-user infrastructure, and application indication across the projection horizon. CAGRs derived from procedure volume elasticity to reimbursement alignment and regulatory sterility mandate implementation schedules. Forecast inputs incorporated polymer extrusion cost curves and CMOS sensor manufacturing scale trajectories.
Caveats apply where reimbursement recalibration for single-use procedures or reusable scope reprocessing cost accounting revisions could materially shift the outlook. Forecasts reflect assumptions regarding EU MDR implementation consistency and semiconductor supply normalization. Practitioners should monitor health technology assessment body life-cycle economics scrutiny and pyrogen testing requirement evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Laser Fibers Market
Urology
Continence Care Market
Urology
Cystectomy Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Prostate Cancer Treatment Market
Urology
Hematuria Treatment Market
Urology
Global Lithotripsy Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Cystoscope Market
Urology
Urology Disposables Market
Urology
US Urology Devices Market
Urology
Urinary Catheters Market
Urology
Primary Aldosteronism Market
Urology
Asia-Pacific Bladder Disorders Market