
 Global Castrate Resistant Prostate Cancer Market | 2026-2036
Global Castrate Resistant Prostate Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Castrate Resistant Prostate Cancer Market Intelligence
Outcome-based financing and risk-sharing agreements between pharmaceutical manufacturers and public payers are reshaping competitive dynamics in castrate resistant prostate cancer therapeutics. Johnson & Johnson Services, Inc. leverages its vertically integrated oncology portfolio to sustain pricing power across hormonal therapy lines. Astellas Pharma Inc. anchors its position through specialized urology-focused commercial infrastructure. Pfizer Inc. competes by extending its presence into novel androgen receptor pathway inhibitors.
Castrate resistant prostate cancer refers to metastatic or locally advanced prostate malignancy that continues progressing despite surgical or medical testosterone suppression to castrate levels, typically requiring therapeutic intervention through androgen receptor signaling inhibition, cytotoxic chemotherapy, or radiopharmaceutical delivery. The disease state demands agents capable of blocking extragonadal androgen synthesis or receptor activation to delay radiographic progression and extend overall survival. Oral enzalutamide formulations command substantial margin pools due to physician familiarity and established reimbursement codes, while intravenous cabazitaxel retains niche positioning in post-docetaxel settings where rapid cytoreduction is clinically necessary. Hospital pharmacies dominate distribution channels for infused cytotoxics, whereas retail and online pharmacies capture growing volumes of oral maintenance therapies as homecare administration expands.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are accelerating market access timelines for novel androgen receptor inhibitors, compressing the gap between clinical proof and commercial availability. REACH compliance and the EU's pharmaceutical strategy for critical medicines are tightening manufacturing and environmental standards for active pharmaceutical ingredient production across European supply chains. Stakeholders must monitor evolving health technology assessment methodologies in Germany and Japan, where ICER thresholds and cost-effectiveness benchmarks increasingly determine formulary placement for premium oncology agents.
Market Dynamics
FDA breakthrough therapy designations and EMA priority medicines schemes are compressing development timelines for novel androgen receptor inhibitors, while outcome-based financing agreements between manufacturers and public payers reshape competitive positioning in castrate resistant prostate cancer therapeutics.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation and EMA's priority medicines scheme compress regulatory review periods for novel hormonal agents. Tertiary care hospitals in the United States, Germany, and Japan are expanding adoption of next-generation therapies.
- Reimbursement Infrastructure Maturation:Established frameworks for metastatic prostate cancer therapies in Japan and Germany enable rapid formulary placement. Public payer risk-sharing agreements create predictable revenue streams for manufacturers.
- Androgen Receptor Pathway Science:Advances in extragonadal androgen synthesis inhibition drive pipeline expansion. Clinical validation of oral maintenance regimens supports homecare administration expansion.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production for hormonal therapies concentrates in Asian contract manufacturers, creating single-source vulnerabilities and quality audit backlogs.
- REACH Compliance Burden:The EU's pharmaceutical strategy for critical medicines and REACH environmental standards tighten manufacturing requirements, extending facility qualification timelines for European supply chains.
- Health Technology Assessment Friction:Germany's IQWiG and Japan's Chuikyo apply stringent ICER thresholds that delay premium oncology agent reimbursement, compressing commercial windows.
Strategic Opportunities
- Radiopharmaceutical Delivery Expansion:Theranostic pairing of diagnostic imaging with targeted alpha-emitters opens new treatment lines. Specialized nuclear medicine infrastructure in the United States and Germany supports clinical adoption.
- Homecare Administration Models:Oral enzalutamide and abiraterone formulations enable retail pharmacy distribution. Patient support programs reduce hospital infusion center dependency.
- Biomarker-Driven Segmentation:AR-V7 splice variant testing identifies non-responders to hormonal therapy, directing patients toward taxane chemotherapy or PARP inhibitors.
Industry Challenges
- Specialized Urology-Oncology Talent Scarcity:Community oncology practices lack expertise in sequencing hormonal, cytotoxic, and radiopharmaceutical therapies. Academic medical centers concentrate specialized care, limiting patient access.
- Cold Chain Radiopharmaceutical Logistics:Short half-life isotopes require just-in-time production and delivery infrastructure. Hospital nuclear pharmacies face capital constraints for lutetium-177 and actinium-225 handling capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Castrate Resistant Prostate Cancer Market |
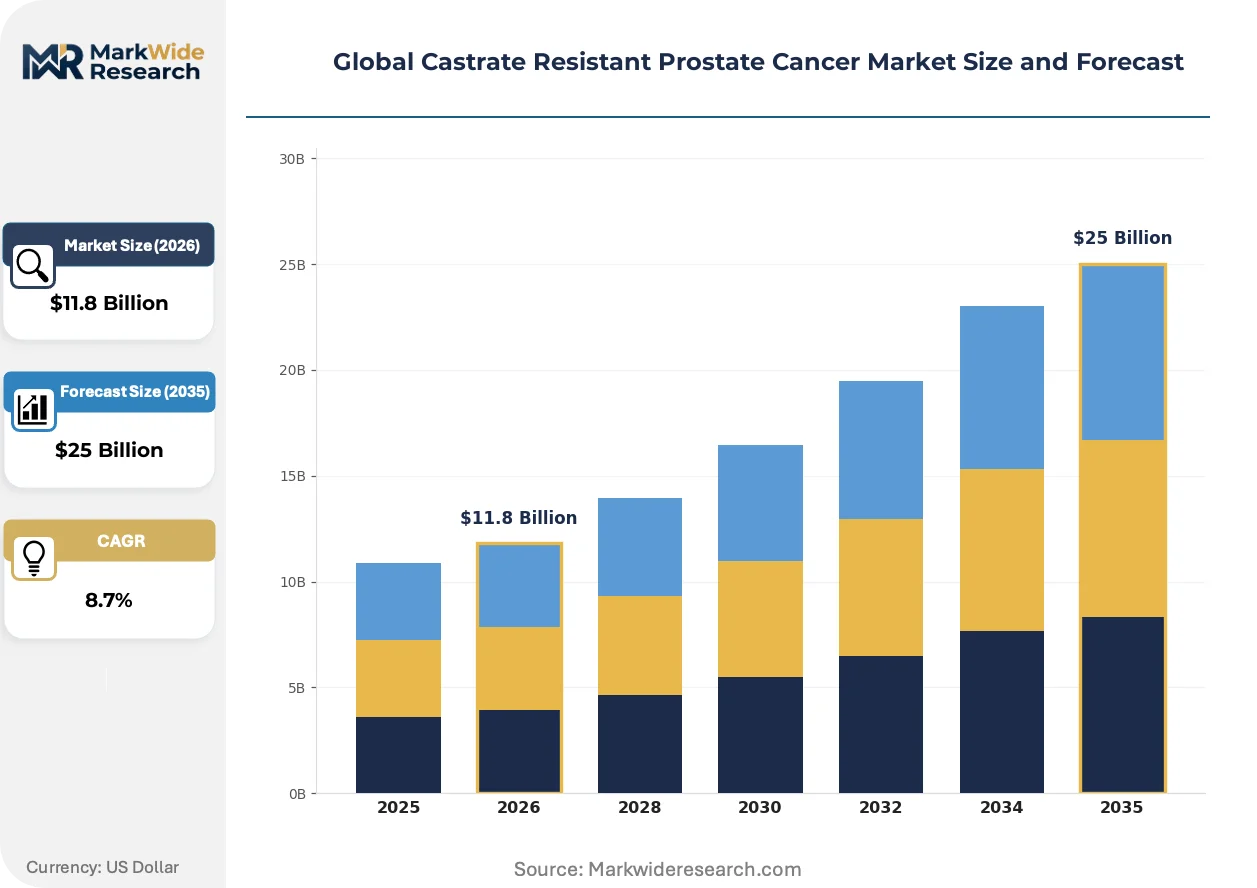
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Abiraterone, Enzalutamide, Docetaxel, Cabazitaxel Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare, Research Laboratories Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Johnson & Johnson Services, Inc., Astellas Pharma Inc., Pfizer Inc., Sanofi S.A., Bayer AG, AstraZeneca plc, Merck & Co., Inc., Bristol-Myers Squibb Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Castrate Resistant Prostate Cancer Market Strategic Shifts & Innovations
Digital pathology platforms and artificial intelligence algorithms are virtualizing diagnostic workflows, while regulatory frameworks accelerate novel therapeutic modalities and procurement patterns shift toward value-based contracting.
Artificial intelligence-powered digital pathology is virtualizing histopathological assessment of prostate biopsies. Academic medical centers in the United States and Germany are deploying FDA-cleared algorithms for Gleason grading standardization. This technology is virtualizing specialist pathologist capacity, enabling community hospitals to access subspecialty-level diagnostic accuracy without physical slide transport.
REACH compliance and the EU pharmaceutical strategy for critical medicines are tightening environmental release standards for hormonal active pharmaceutical ingredients. European manufacturers must retrofit facilities with advanced wastewater treatment systems. German and Swiss production sites face the steepest capital requirements, accelerating contract manufacturing organization consolidation.
Hospital pharmacy procurement committees are unbundling drug acquisition from administration services. Integrated delivery networks in the United States negotiate bundled pricing for oral oncology therapies through specialty pharmacy carve-outs. This reconfiguration is most visible in Medicare Advantage plans, where risk-bearing entities capture margin through vertical integration into dispensing.
Global Castrate Resistant Prostate Cancer Market Segmentation
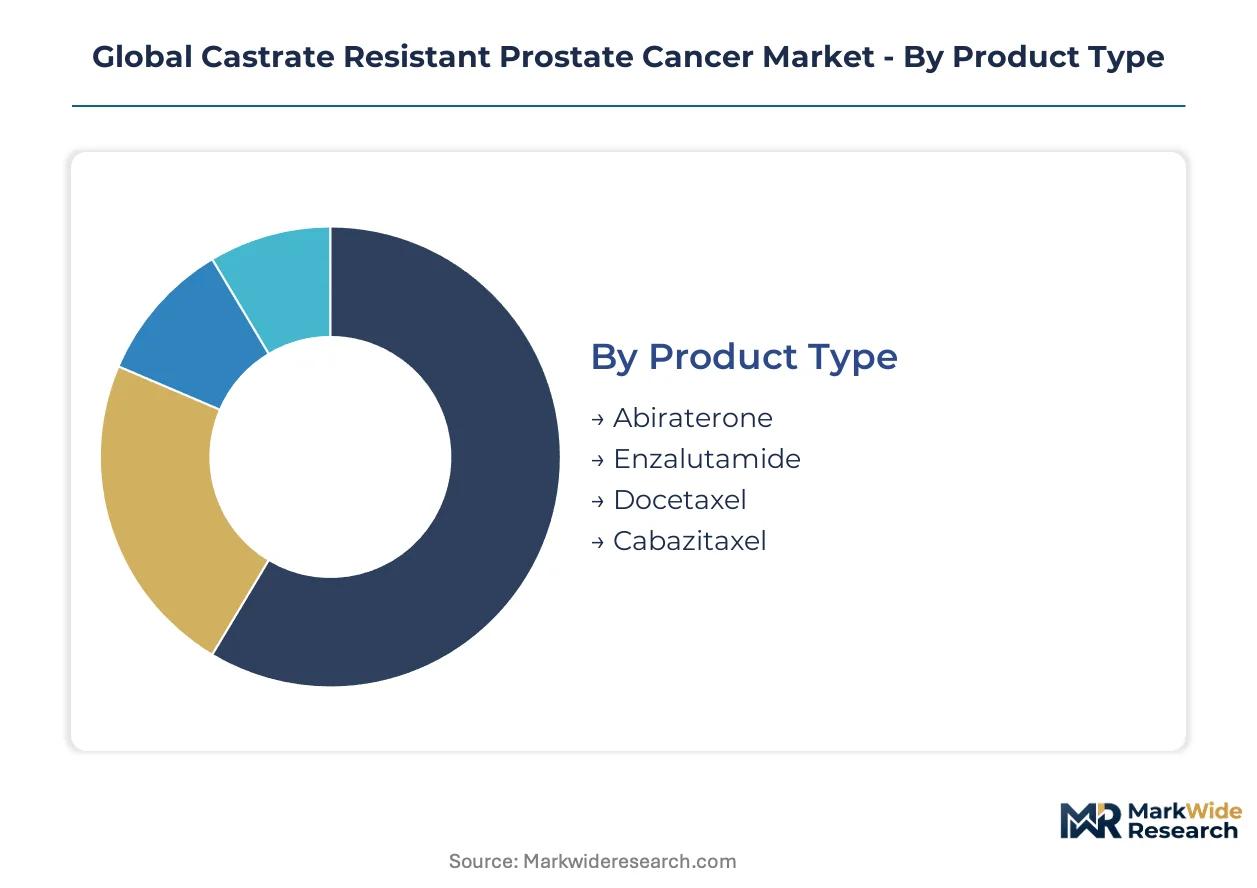
Therapeutic modality and care setting segmentation determines pricing architecture and channel economics in castrate resistant prostate cancer. Product form, administration route, and distribution pathway each impose distinct manufacturing, logistics, and reimbursement requirements that shape competitive positioning.
Product Type:
Oral hormonal agents dominate maintenance therapy across tertiary care hospitals in the United States, Germany, and Japan, while intravenous cytotoxics retain acute intervention roles.
- Abiraterone:CYP17 inhibitor formulated with prednisone to suppress extragonadal androgen synthesis. Demand concentrates in Medicare Advantage networks and German statutory health insurance where risk-bearing entities negotiate bundled oral oncology pricing through specialty pharmacy carve-outs.
- Enzalutamide:Androgen receptor antagonist with higher central nervous system penetration than first-generation antiandrogens. United States academic medical centers and Japanese designated cancer hospitals drive volume through established reimbursement codes for metastatic castrate resistant disease.
- Docetaxel:Taxane chemotherapy administered intravenously in hospital infusion centers. First-line cytotoxic standard before hormonal agent failure.
- Cabazitaxel:Second-generation taxane for post-docetaxel progression. Requires microtubule-stabilizing mechanism in docetaxel-resistant clones.
Established volume favors enzalutamide; emerging adoption favors cabazitaxel in post-docetaxel sequencing protocols.
Administration Route:
Route selection drives site-of-care economics and patient compliance profiles across reimbursement frameworks.
- Oral:Self-administered small-molecule inhibitors enabling homecare transition. Medicare Advantage plans and German sickness funds prefer oral agents for reduced infusion center utilization.
- Intravenous:Hospital-based cytotoxic delivery requiring pharmacy compounding and nursing supervision. Concentrates in tertiary oncology centers with infusion infrastructure.
- Subcutaneous:Emerging delivery for supportive care agents and investigational hormonal formulations. Limited current penetration in prostate cancer protocols.
- Topical:Negligible commercial presence in castrate resistant disease; experimental formulations in early development.
Oral administration captures margin through retail pharmacy distribution; intravenous retains hospital pharmacy revenue concentration.
End User:
Care setting fragmentation reflects specialization requirements and reimbursement site-of-service differentials.
- Hospitals:Academic medical centers and designated cancer hospitals manage complex sequencing of hormonal, cytotoxic, and radiopharmaceutical therapies. FDA breakthrough therapy designations accelerate formulary placement in United States NCI-designated centers.
- Clinics:Community oncology practices with limited urology-oncology expertise refer advanced cases to academic centers. EMA priority medicines schemes compress access timelines in European clinic networks.
- Homecare:Oral maintenance therapy administration supported by patient support programs and remote monitoring. Expanding in Japanese long-term care insurance frameworks.
- Research Laboratories:Biomarker testing and clinical trial enrollment sites. AR-V7 splice variant testing directs therapy selection in specialized reference laboratories.
Hospital concentration dominates intravenous therapy; homecare is expanding most quickly for oral maintenance regimens.
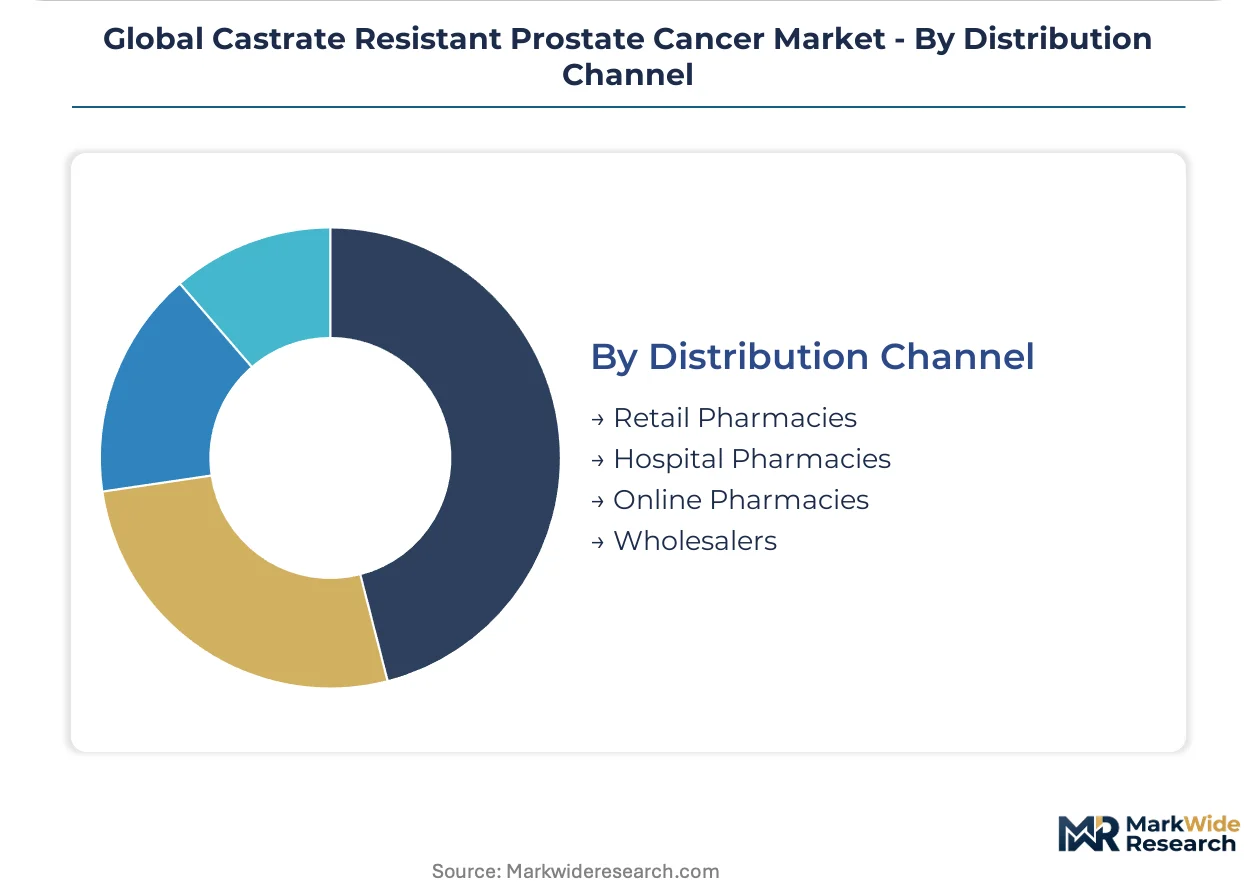
Distribution Channel:
Channel selection reflects product stability requirements and payer vertical integration strategies.
- Retail Pharmacies:Oral enzalutamide and abiraterone dispensing through specialty pharmacy networks. United States integrated delivery networks capture margin through captive specialty pharmacy operations.
- Hospital Pharmacies:Intravenous cytotoxic procurement and compounding. REACH compliance requirements tighten environmental release standards for European hospital pharmacy hormonal API handling.
- Online Pharmacies:Direct-to-patient oral therapy delivery with cold chain monitoring. Growing share in German mail-order pharmacy frameworks.
- Wholesalers:Bulk distribution to hospital systems and retail chains. Three-tier pricing structure across premium, standard, and economy levels based on volume commitments and contract exclusivity.
Hospital pharmacies retain infused therapy control; retail and online channels gain oral therapy share through homecare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial pharmaceutical trade surplus in oncology therapeutics, while Germany and Japan import significant volumes of active pharmaceutical ingredients for hormonal therapy manufacturing. China and India supply contract manufacturing capacity that European and North American formulators depend upon.
United States
Medicare Advantage networks and integrated delivery systems drive oral oncology dispensing through captive specialty pharmacies. The FDA's breakthrough therapy designation accelerates formulary placement at NCI-designated cancer centers. Greater Boston and the Research Triangle in North Carolina concentrate clinical trial enrollment and biomarker testing infrastructure for AR-V7 splice variant diagnostics.
Germany
Statutory health insurance funds negotiate risk-sharing agreements for premium hormonal agents through IQWiG assessment frameworks. REACH compliance requirements tighten environmental release standards for API manufacturing in the Rhine-Ruhr industrial corridor. Bavaria's designated cancer hospitals concentrate radiopharmaceutical delivery infrastructure for lutetium-177 therapies.
Japan
Chuikyo cost-effectiveness thresholds determine reimbursement timelines for novel androgen receptor inhibitors in designated cancer hospitals. The PMDA's sakigake designation accelerates priority review for prostate cancer therapeutics. Tokyo and Osaka metropolitan areas concentrate urology-oncology specialist capacity and homecare administration programs under long-term care insurance frameworks.
China
Domestic pharmaceutical manufacturers expand CYP17 inhibitor production under the NMPA's priority review pathway for oncology drugs. The National Reimbursement Drug List updates increasingly include metastatic prostate cancer therapies. Yangtze River Delta bioclusters in Shanghai and Suzhou concentrate contract manufacturing organization capacity for hormonal API synthesis.
Switzerland
Swissmedic regulatory frameworks enable early access programs for novel hormonal agents ahead of EU-wide EMA approvals. Basel and Zurich pharmaceutical clusters anchor European headquarters operations for global oncology portfolios. The country's bilateral trade agreements facilitate API import from Asian contract manufacturers with streamlined customs clearance.
Global Castrate Resistant Prostate Cancer Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated pharmaceutical conglomerates with oncology-focused divisions, mid-cap urology specialists, and diversified generics manufacturers. Three strategic archetypes dominate: diversified healthcare conglomerates leveraging cross-therapeutic pricing power, specialized oncology players with urology commercial infrastructure, and broad-based pharmaceutical companies extending into novel androgen receptor pathway science. Competitive moves center on backward integration into API manufacturing and risk-sharing agreements with public payers.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and Bayer AG exemplify the archetype of players sustaining pricing power across hormonal therapy lines through vertically integrated oncology portfolios. Astellas Pharma Inc. occupies a distinct position as a urology-focused specialist with dedicated commercial infrastructure. Pfizer Inc. represents the pattern of broad-based pharmaceutical companies extending presence into novel androgen receptor pathway inhibitors through portfolio diversification.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Astellas Pharma Inc. |
| Pfizer Inc. |
| Sanofi S.A. |
| Bayer AG |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Others |
Cost & Logistics Intelligence
Asian contract manufacturers in India and China concentrate active pharmaceutical ingredient production for hormonal therapies, anchoring margin pools with European and North American formulators who capture value through finished-dose packaging and proprietary formulation patents.
Pricing Analysis
Hospital pharmacy procurement committees anchor pricing negotiations through bundled acquisition agreements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough therapy designation status and IQWiG assessment outcomes. Pricing pressure stems from German statutory health insurance risk-sharing agreements that compress commercial windows for premium agents. Medicare Advantage plans demonstrate highest price sensitivity due to capitated reimbursement structures, while Japanese designated cancer hospitals show lowest sensitivity under Chuikyo-established premium tiers.
Supply Chain Analysis
Single-source vulnerability in CYP17 inhibitor API production dominates supply chain risk concentration. Manufacturing draws from India, China, and Switzerland for hormonal active pharmaceutical ingredients, with finished-dose formulation in Germany, the United States, and Japan. Raw material dependencies include prednisone co-formulation, microcrystalline cellulose excipients, and specialized coating polymers. REACH compliance requirements in the EU tighten environmental release standards, extending facility qualification timelines. Distribution runs through hospital pharmacies for intravenous cytotoxics and retail specialty pharmacies for oral maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The castrate resistant prostate cancer therapeutics market functions as a defensive-moat story where regulatory entrenchment through FDA breakthrough therapy and EMA priority medicines schemes creates substantial switching costs for prescribers and payers.
For Market Incumbents: Pre-empt biosimilar erosion by securing backward integration into API manufacturing and expanding patient support programs that embed oral therapy adherence into Medicare Advantage contracts. Generic entrants threaten margin pools in post-patent hormonal agents; counter by deepening formulary relationships with integrated delivery networks and accelerating radiopharmaceutical pipeline assets that require specialized nuclear medicine infrastructure. For New Entrants and Emerging Players: Build out biomarker-driven segmentation capabilities targeting AR-V7 splice variant testing laboratories, the most penetrable node in treatment sequencing protocols. White-space exists in homecare administration platforms for oral maintenance regimens under Japanese long-term care insurance frameworks. Go-to-market through specialty pharmacy carve-out negotiations with risk-bearing entities captures margin without requiring hospital infusion center infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed urology-focused commercial infrastructure platforms lacking radiopharmaceutical delivery capabilities. Long-term viability hinges on therapeutic modality diversification beyond hormonal agents into alpha-emitter theranostics. Watch FDA accelerated approval conversion rates as the inflection signal distinguishing sustainable revenue streams from regulatory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment in AR-V7 stratified populations validates biomarker-driven regulatory pathways. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for novel androgen receptor inhibitors. |
| Manufacturing Scale-Up | REACH-compliant API production expansion in the Rhine-Ruhr corridor secures European supply continuity. |
| Pipeline Diversification | Actinium-225 radiopharmaceutical assets reduce dependency on oral hormonal agent revenue concentration. |
| Reimbursement Strategy | IQWiG risk-sharing agreements in Germany establish predictable revenue streams for premium oncology agents. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling across treatment lines and top-down pharmaceutical revenue triangulation were cross-referenced for consistency.
Forecast inputs across the projection horizon incorporated treatment modality segmentation, administration route economics, and regional regulatory cluster differentiation. CAGRs were derived from epidemiological incidence projections, therapy sequencing protocol adoption curves, and reimbursement framework maturation timelines. Modeled variables included oral versus intravenous therapy mix shifts and radiopharmaceutical infrastructure penetration rates.
Stress conditions across IQWiG assessment stringency, FDA accelerated approval conversion failure, and API manufacturing concentration disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding payer risk-sharing agreement prevalence and biomarker testing adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Hematuria Treatment Market
Urology
Urology Lasers Market
Urology
Transrectal Ultrasound Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Varicocele Treatment Market
Urology
Penile Cancer Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Global Prostate Cancer Market
Urology
Uropathy Treatment Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Europe Urology Devices Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Global Bladder Scanner Market
Urology
Urinary Retention Therapeutics Market