
 Leuprolide Acetate Market | 2026-2036
Leuprolide Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
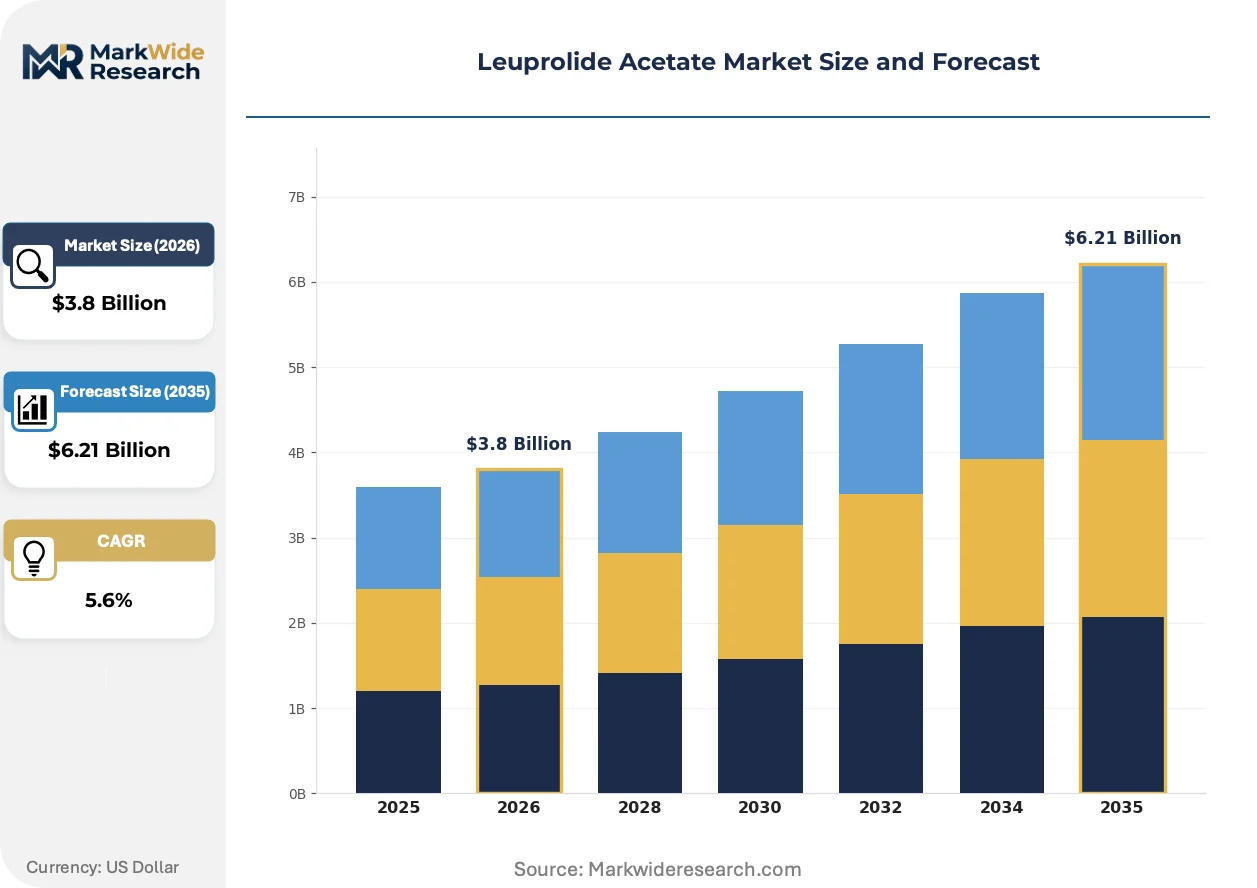
Leuprolide Acetate Market Outlook
Oncology applications is repositioning leuprolide acetate demand away from traditional endometriosis monotherapy. AbbVie Inc. leverages its established depot formulation infrastructure across North American hospital networks. Takeda Pharmaceutical Co. Ltd. anchors its competitive stance through sustained-release injection specialization in Asian markets. Teva Pharmaceutical Industries Ltd. competes aggressively on cost positioning in European generics channels.
Leuprolide acetate is a synthetic nonapeptide analogue of gonadotropin-releasing hormone, formulated as depot suspensions in polymeric microspheres for sustained release over one-, three-, four-, or six-month intervals. It suppresses pituitary gonadotropin secretion through continuous receptor stimulation, primarily serving prostate cancer, endometriosis, and central precocious puberty management. The injection segment dominates volume due to established clinical familiarity and reimbursement coding, while the implant category captures premium margins through reduced administration frequency. Cancer therapy areas absorb the largest share of production capacity, though precocious puberty applications sustain above-average pricing power through orphan-drug-like prescribing concentration.
FDA oversight of bioequivalence standards for depot formulations shapes generic substitution rates, while EMA REACH compliance governs residual solvent limits in poly-lactic-co-glycolic acid microsphere production. The EU MDR framework imposes escalating clinical evidence requirements on sustained-release device-drug combinations, tightening market access for new entrants. Stakeholders must monitor evolving FDA guidance on complex generic peptide products and corresponding patent litigation timelines to anticipate competitive inflection points.
Market Dynamics
Depot formulation bioequivalence standards are compressing generic substitution timelines while oncology demand concentrates production capacity toward prostate cancer protocols. FDA complex generic peptide guidance and EMA MDR device-drug combination rules are forcing reformulation investments across manufacturing networks.
Growth Catalysts
- EMA MDR Compliance:The EU Medical Device Regulation imposes escalating clinical evidence requirements on sustained-release device-drug combinations, accelerating consolidation among manufacturers with established quality management systems.
- Oncology Protocol Expansion:Prostate cancer treatment guidelines in the United States, Germany, and Japan are incorporating gonadotropin-releasing hormone agonists earlier in therapeutic sequences.
- Poly-lactic-co-glycolic Acid Microsphere Advances:Improved polymer degradation kinetics enable extended-release intervals, reducing administration burden in pediatric central precocious puberty management.
Market Restraints
- Residual Solvent Volatility:ECHA REACH compliance for dichloromethane and ethyl acetate limits in microsphere production creates input cost uncertainty for European manufacturers.
- Active Pharmaceutical Ingredient Concentration:Peptide synthesis capacity clusters in China and India, exposing supply chains to single-source dependencies and geopolitical friction.
- Peptide Substitution Pressure:Oral gonadotropin-releasing hormone antagonists are displacing depot agonists in select endometriosis protocols where rapid testosterone suppression is not required.
Strategic Opportunities
- Pediatric Orphan Concentration:Central precocious puberty applications sustain premium pricing through concentrated prescribing at pediatric endocrinology centers in the United States.
- Complex Generic Pathway:FDA guidance on peptide bioequivalence creates first-mover advantages for filers with validated pharmacokinetic bridging studies.
- Six-Month Implant Migration:Reduced administration frequency implants are capturing hospital formulary preference where reimbursement coding supports pharmacy benefit management integration.
Industry Challenges
- Peptide Analytical Methodology Gap:Bioanalytical talent scarcity in high-performance liquid chromatography-mass spectrometry for depot release kinetics extends development timelines.
- Stability Validation Burden:Long-term shelf-life studies for polymeric microspheres require capital-intensive climate-controlled storage infrastructure and real-time aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leuprolide Acetate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Implant, Oral Tablet, Solution Therapy Area: Cancer, Endometriosis, Prostate Disorders, Precocious Puberty End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Co. Ltd., Teva Pharmaceutical Industries Ltd., Ferring Pharmaceuticals, Sun Pharmaceutical Industries Ltd., Fresenius Kabi AG, Mylan N.V., Hikma Pharmaceuticals PLC, AstraZeneca PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leuprolide Acetate Market Strategic Shifts
Continuous manufacturing technologies are displacing batch processing in peptide synthesis, while regulatory convergence around complex generic standards is compressing competitive differentiation windows. These forces are reshaping investment priorities across formulation development and quality assurance functions.
At-line process analytical technology is automating real-time monitoring of microsphere size distribution and drug loading during emulsion-solvent evaporation. Contract development and manufacturing organizations in Switzerland and Germany are deploying these systems to reduce batch failure rates. The technology is automating quality control throughput, enabling faster release testing for clinical trial materials.
FDA draft guidance on in vivo bioequivalence studies for depot leuprolide acetate injections is tightening statistical power requirements for pharmacokinetic endpoints. Generic sponsors must now demonstrate equivalence across multiple time points in testosterone suppression profiles. United States ANDA filers are responding by investing in adaptive clinical trial designs with interim analysis protocols.
Hospital pharmacy consolidation is compressing formulary decision cycles from annual to quarterly review schedules. Integrated delivery networks in the United States are unbundling drug acquisition from administration reimbursement, forcing manufacturers to justify total cost-of-care metrics. This shift is most visible in prostate cancer care pathways where oncology pharmacy committees now control gonadotropin-releasing hormone agonist selection.
Leuprolide Acetate Market Segmentation
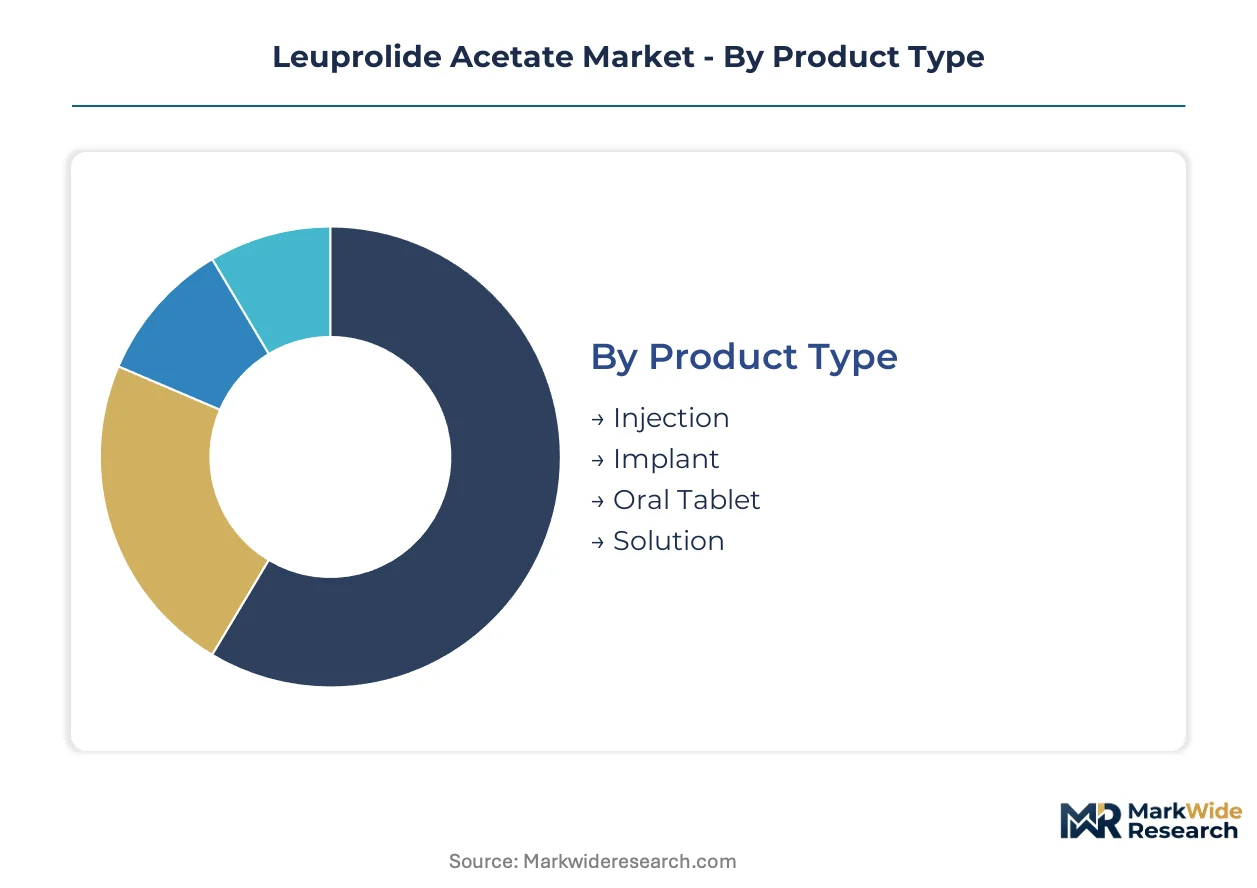
Leuprolide acetate formulations diverge sharply in administration burden and reimbursement coding, creating distinct competitive arenas across depot injections, implants, and emerging oral alternatives. Therapy area concentration in oncology versus pediatric endocrinology drives divergent pricing power and regulatory scrutiny profiles.
Product Type:
Hospital pharmacy committees and homecare infusion services prioritize administration frequency and total cost-of-care metrics when selecting among formulation alternatives.
- Injection:Poly-lactic-co-glycolic acid microsphere suspensions enable one-, three-, four-, or six-month dosing intervals through subcutaneous or intramuscular delivery. Prostate cancer protocols in the United States and Japan absorb the majority of production capacity, with reimbursement coding favoring established depot familiarity over novel delivery systems.
- Implant:Solid polymer rods provide continuous release over extended intervals, reducing clinic visits for pediatric central precocious puberty management. Premium pricing persists in United States pediatric endocrinology centers where orphan-drug-like prescribing concentration sustains margin structures despite lower absolute volumes.
- Oral Tablet:Peptide permeability enhancers enable gastrointestinal absorption, though bioavailability constraints limit clinical adoption to endometriosis protocols where rapid testosterone suppression is non-critical.
- Solution:Immediate-release liquid formulations serve diagnostic applications and short-term pituitary desensitization prior to assisted reproduction protocols.
Injection leads volumes today; implant is gaining share fastest through six-month interval extensions and pharmacy benefit management integration.
Therapy Area:
Clinical guideline positioning and screening infrastructure density determine regional demand concentration across oncologic and non-oncologic applications.
- Cancer:Prostate adenocarcinoma protocols incorporate gonadotropin-releasing hormone agonists earlier in therapeutic sequences per United States and German oncology guidelines. Androgen deprivation therapy sustains chronic administration models with predictable reimbursement.
- Endometriosis:Estrogen suppression for ectopic endometrial tissue management faces substitution pressure from oral antagonists in European markets where rapid hormonal offset is not required.
- Prostate Disorders:Benign prostatic hyperplasia and related lower urinary tract symptoms represent secondary indications with limited formal guideline endorsement.
- Precocious Puberty:Central nervous system-mediated early puberty arrest commands premium pricing through concentrated United States pediatric specialty prescribing and limited therapeutic alternatives.
Cancer absorbs capacity today; precocious puberty commands the steepest expansion trajectory through pediatric orphan concentration.
End User:
Site-of-care economics and infusion infrastructure availability segment demand between institutional and ambulatory settings.
- Hospitals:Integrated delivery networks in the United States control gonadotropin-releasing hormone agonist selection through oncology pharmacy committees, unbundling drug acquisition from administration reimbursement.
- Clinics:Urology and gynecology outpatient practices in Germany and Japan manage depot injection scheduling with established reimbursement frameworks.
- Homecare:Self-administration training programs expand for six-month implant recipients with stable disease profiles.
- Specialty Pharmacies:Limited distribution networks handle prior authorization complexity for high-cost pediatric formulations.
Hospitals dominate procurement today; specialty pharmacies are climbing fastest through orphan drug distribution concentration.
Distribution Channel:
Supply chain configuration and formulary access requirements create divergent margin structures across direct and intermediated pathways.
- Direct Sales:Manufacturer contracts with United States integrated delivery networks bypass wholesale markups for high-volume oncology accounts.
- Retail Pharmacies:Community dispensing faces compression from mail-order and specialty pharmacy migration for chronic therapy maintenance.
- Online Pharmacies:Digital fulfillment expands in European markets with established cold-chain logistics and prescription verification infrastructure.
- Wholesalers:Three-tier distribution maintains relevance for smaller clinic accounts and geographic coverage gaps.
Direct sales anchor volume today; online pharmacies are expanding most quickly through pharmacy benefit management platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical corridors anchor leuprolide acetate demand through integrated delivery network procurement concentration. German and Japanese screening infrastructure sustains parallel demand volumes. Regulatory divergence across FDA, EMA, and PMDA pathways fragments approval timelines for depot formulation entrants.
United States
Oncology pharmacy committees at major integrated delivery networks now control gonadotropin-releasing hormone agonist selection through quarterly formulary reviews. FDA complex generic peptide guidance tightens pharmacokinetic bridging requirements for ANDA filers. Boston and Research Triangle Park clusters host contract development organizations specializing in poly-lactic-co-glycolic acid microsphere analytics.
Germany
Urology outpatient practices in Bavaria and North Rhine-Westphalia manage depot injection scheduling through established statutory health insurance reimbursement. EMA MDR compliance imposes escalating clinical evidence requirements on sustained-release device-drug combinations. Frankfurt-Rhine-Main pharmaceutical manufacturing belt concentrates polymeric microsphere production capacity for European distribution.
Japan
PMDA oversight of depot bioequivalence studies shapes generic substitution timelines for prostate cancer protocols. Universal screening infrastructure sustains chronic androgen deprivation therapy administration models. Osaka-Kobe pharmaceutical corridor hosts formulation specialists serving Asian market export requirements.
India
CDSCO regulatory pathways for peptide synthesis facilities govern active pharmaceutical ingredient export capacity to formulation markets. Peptide manufacturing clusters in Hyderabad and Ahmedabad supply intermediate materials for depot microsphere production. Domestic oncology protocol expansion is accelerating hospital pharmacy procurement of finished dosage forms.
Switzerland
Swissmedic quality management system requirements attract contract manufacturing organizations serving EU and US markets simultaneously. Basel and Zurich regions concentrate analytical method development talent for high-performance liquid chromatography-mass spectrometry release testing. Polymer degradation kinetics research at federal institutes of technology informs next-generation extended-release interval designs.
Leuprolide Acetate Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend depot formulation intervals to capture pharmacy benefit management preference. The vendor base stratifies across three tiers: originator manufacturers with established hospital network contracts, complex generic filers with validated bioequivalence studies, and commodity peptide suppliers feeding formulation partnerships. Strategic archetypes include sustained-release technology specialists, vertically integrated active pharmaceutical ingredient producers, and regional hospital channel aggregators. Capacity expansion in poly-lactic-co-glycolic acid microsphere production and technology licensing for six-month implant migration represent the dominant competitive vectors.
Among originator-tier manufacturers, AbbVie Inc. and Takeda Pharmaceutical Co. Ltd. occupy positions defined by depot formulation infrastructure and geographic market specialization respectively. Teva Pharmaceutical Industries Ltd. exemplifies the complex generic archetype through European channel cost positioning. These three anchors illustrate how competitive differentiation fragments across formulation technology, regulatory filing strategy, and procurement channel access rather than converging on single-dimension scale advantages.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Co. Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Ferring Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Mylan N.V. |
| Hikma Pharmaceuticals PLC |
| AstraZeneca PLC |
| Others |
Value Chain & Pricing Dynamics
ECHA REACH compliance for residual solvent limits gates qualified supply access for European manufacturers and simultaneously anchors premium-tier pricing for depot formulations meeting stringent dichloromethane thresholds. Buyers in United States integrated delivery networks now unbundle drug acquisition from administration reimbursement, forcing manufacturers to justify total cost-of-care metrics across formulation alternatives.
Pricing Analysis
Direct-to-hospital contracting discounts dominate oncology procurement as integrated delivery networks consolidate purchasing power through quarterly formulary reviews. Three-tier pricing structure across premium six-month implants, standard three-month depots, and economy one-month injections reflects administration frequency and pediatric orphan concentration. Pricing pressure stems from oral gonadotropin-releasing hormone antagonists displacing depot agonists in European endometriosis protocols. Hospital pharmacy committees exhibit highest price sensitivity; pediatric endocrinology centers demonstrate lowest sensitivity due to limited therapeutic alternatives for central precocious puberty.
Supply Chain Analysis
Regional distribution centers in Frankfurt-Rhine-Main and Basel manage poly-lactic-co-glycolic acid microsphere release testing and cold-chain logistics for European hospital networks. Active pharmaceutical ingredient synthesis concentrates in India and China, with peptide manufacturing clusters in Hyderabad and Ahmedabad feeding formulation partnerships. Supply chain risk centers on single-source dependencies for specialized high-performance liquid chromatography-mass spectrometry bioanalytical talent. Distribution runs through direct manufacturer contracts with United States integrated delivery networks for high-volume oncology accounts, supplemented by specialty pharmacy limited distribution networks for pediatric formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leuprolide acetate market reads as a late-cycle quality story where oncology protocol expansion toward earlier therapeutic sequencing rewards manufacturers with validated bioequivalence studies and established depot formulation infrastructure.
For Market Incumbents: Lock in hospital network contracts through six-month implant formulary preference and pharmacy benefit management integration before FDA complex generic peptide guidance accelerates ANDA filer entry. Backward integration into poly-lactic-co-glycolic acid microsphere production secures margin control against ECHA REACH input cost volatility. Priority certification investment in EMA MDR quality management systems consolidates European manufacturing base. For New Entrants and Emerging Players: The price-point gap between premium six-month implants and economy one-month injections creates entry opportunity for mid-interval three-month depot specialists with validated pharmacokinetic bridging studies. Target German urology outpatient practices and Japanese universal screening infrastructure where reimbursement frameworks remain established. Go-to-market through contract development and manufacturing organization partnerships in Switzerland bypasses capital-intensive climate-controlled storage infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for complex generic filers with validated bioequivalence studies because FDA guidance on peptide bioequivalence creates first-mover advantages with extended competitive protection windows. Long-term viability centers on acquisition of sustained-release technology specialists with proprietary polymer degradation kinetics capabilities. Watch for inflection in patent litigation timelines around depot formulation intervals as signal for competitive intensity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive designs with interim analysis protocols satisfy FDA bioequivalence statistical power requirements for testosterone suppression profiles. |
| Manufacturing Scale-Up | Continuous manufacturing technologies in Swiss and German contract development organizations reduce poly-lactic-co-glycolic acid microsphere batch failure rates. |
| Regulatory Approval Pathway | EMA MDR compliance investments accelerate consolidation among manufacturers with established quality management systems for device-drug combinations. |
| Pipeline Diversification | Extended-release interval designs from federal Swiss polymer research institutes enable six-month implant migration capturing hospital formulary preference. |
| Licensing Agreement | Technology licensing for polymer degradation kinetics extends competitive differentiation windows as regulatory convergence compresses generic timelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down manufacturer capacity assessments were cross-referenced to anchor volume estimates.
Comparable-period anchoring tied projection assumptions to historical depot formulation adoption curves and androgen deprivation therapy protocol expansion patterns across the analysis window. Segmentation modeling incorporated therapy area, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of oncology guideline positioning and pediatric orphan prescribing concentration, with inputs from poly-lactic-co-glycolic acid microsphere production capacity expansion announcements and peptide synthesis facility utilization rates.
The model assumes a particular technology adoption path; alternative pathways for oral gonadotropin-releasing hormone antagonists would alter the outlook through accelerated substitution in endometriosis protocols. Forecasts reflect assumptions about EMA MDR compliance timelines, FDA complex generic peptide guidance finalization, and ECHA REACH solvent limit enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Human Combination Vaccines Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Global Hormonal Contraceptives Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Chloramphenicol Eye Drops Market