
 Global Prostate Cancer Market | 2026-2036
Global Prostate Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prostate Cancer Market Analysis
Oncology nursing specialization is rotating toward precision medicine protocols, expanding the addressable patient pool for next-generation prostate cancer therapies. Pfizer Inc. leverages its kinase inhibitor portfolio to sustain competitive presence in metastatic settings. AstraZeneca anchors its position through PARP inhibitor combinations, while Bayer AG differentiates via radioligand therapy manufacturing scale.
Prostate cancer encompasses malignant neoplasms arising from glandular epithelium in the male reproductive system, typically graded by Gleason score and PSA velocity to determine progression risk and therapeutic intensity. Hormonal therapy occupies the largest revenue share as androgen deprivation remains foundational across treatment stages, though immunotherapy segments are attracting R&D investment following checkpoint inhibitor approvals in castration-resistant disease. Early-stage detection through PSA screening and mpMRI fusion biopsy is expanding the curative-intent patient pool, while metastatic-stage protocols command premium pricing due to combination therapy requirements and extended treatment duration.
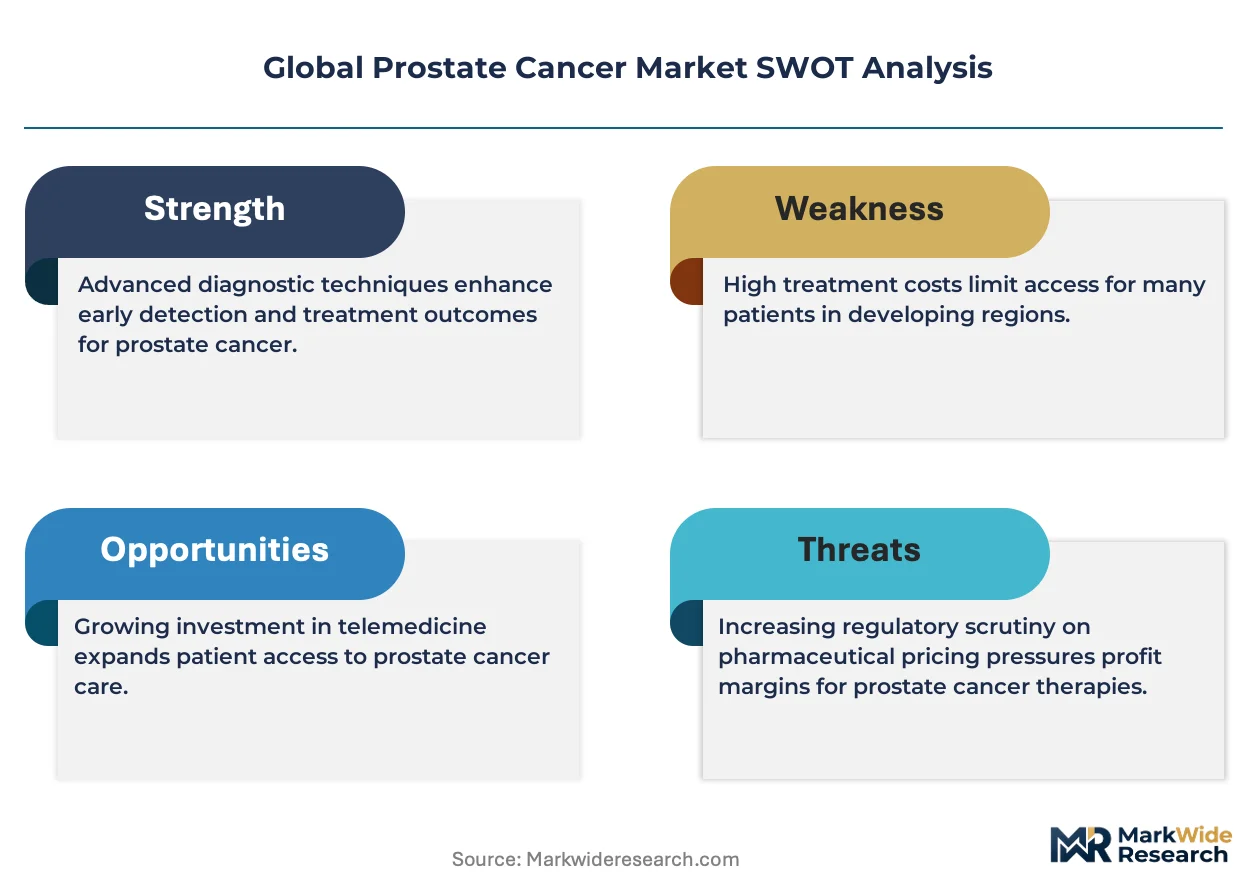
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines for novel prostate cancer agents, though post-market confirmatory trial obligations raise commercial risk. Japan's PMDA has aligned oncology review standards with FDA precedent, accelerating Asian-Pacific market entry for Western innovators. Stakeholders must monitor reimbursement negotiations for radiopharmaceuticals and gene therapies, as these modalities reshape cost structures across hospital, clinic, and home care delivery channels.
Market Dynamics
Accelerated regulatory pathways at FDA and EMA are compressing commercialization timelines for novel hormonal agents and radioligand therapies, reshaping how manufacturers sequence clinical development and pricing negotiations across hospital procurement channels.
Growth Catalysts
- Expanded PSA Screening:Japan's national health insurance now covers prostate-specific antigen velocity testing for men over 50, enlarging the curative-intent patient pool eligible for early-stage intervention.
- EMA Conditional Marketing Authorization:This framework permits pre-approval access to PARP inhibitor combinations in castration-resistant settings, shortening revenue recognition timelines for novel agents.
- mpMRI Fusion Biopsy:Urology clinics in Germany and the United States are deploying multiparametric magnetic resonance imaging to reduce false-negative rates and escalate appropriate patients to definitive therapy.
Market Restraints
- Radiopharmaceutical Supply Concentration:Production of lutetium-177 and actinium-225 concentrates at four North American cyclotron facilities, creating single-point vulnerability for radioligand therapy distribution.
- Post-Market Confirmatory Obligations:FDA accelerated approval mandates require ongoing randomized trials, exposing manufacturers to revenue clawback if efficacy endpoints fail in broader populations.
- Androgen Deprivation Therapy Substitution:Generic leuprolide formulations continue to capture volume in earlier-stage disease, compressing branded hormonal agent pricing power.
Strategic Opportunities
- Home Administration Infrastructure:Subcutaneous formulations of androgen receptor inhibitors enable oncology practices to shift monitoring and dosing outside hospital infusion centers.
- Combination Therapy Reimbursement:Germany's G-BA is piloting indication-based pricing for PARP inhibitor plus novel hormonal agent sequences, creating precedent for value-based contracts.
- Liquid Biopsy Integration:Circulating tumor DNA testing in metastatic settings identifies actionable mutations for precision therapy selection, expanding addressable testing volume.
Industry Challenges
- Radiochemistry Workforce Scarcity:Qualified nuclear pharmacists capable of handling alpha-emitting isotopes remain concentrated at academic medical centers, constraining community clinic adoption.
- Real-World Evidence Infrastructure:Electronic health record interoperability gaps between community urology practices and academic centers fragment post-market safety monitoring for combination regimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prostate Cancer Market |
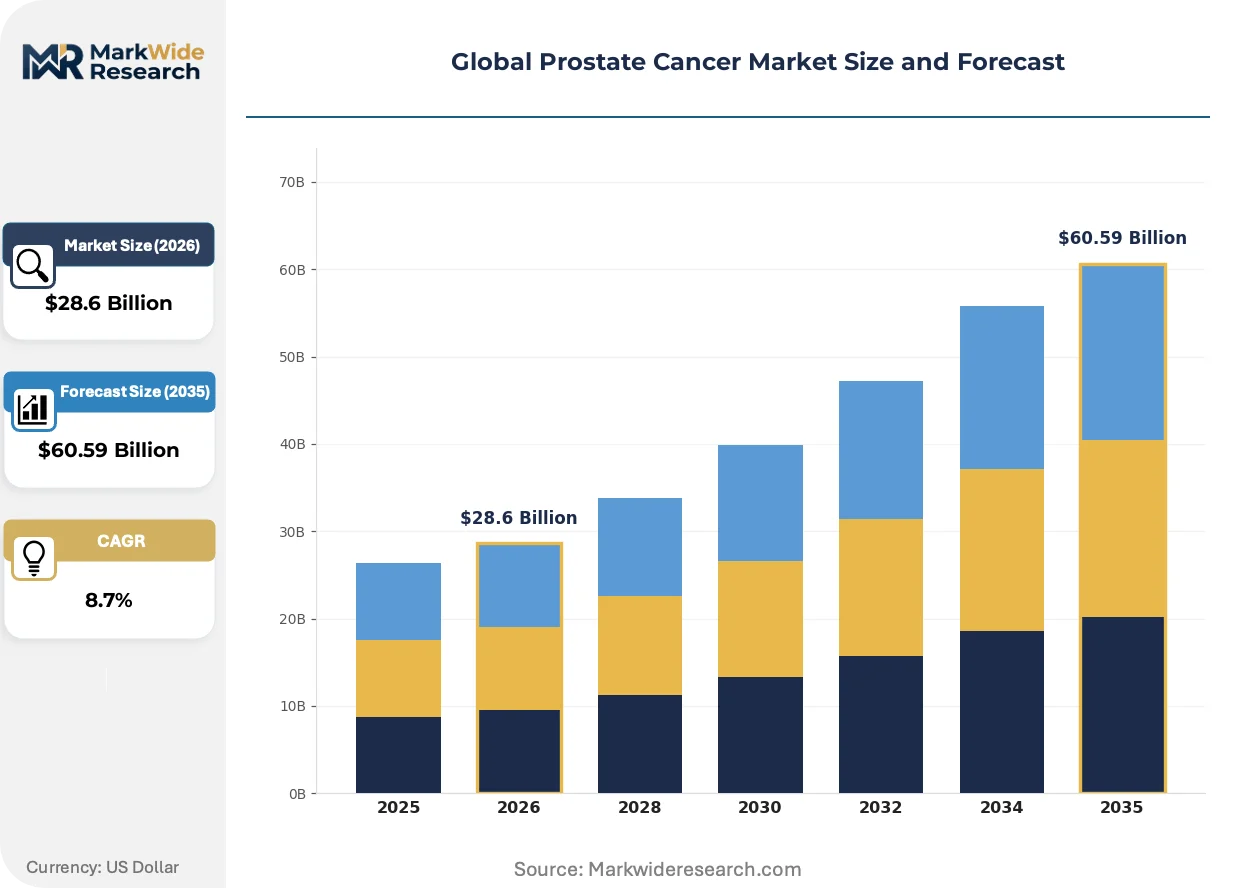
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Chemotherapy, Immunotherapy, Radiation Therapy End User: Hospitals, Clinics, Home Care, Research Institutes Treatment Stage: Early Stage, Advanced Stage, Recurrent Stage, Metastatic Stage Administration Route: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Johnson & Johnson, Astellas Pharma, AstraZeneca, Bayer AG, Pfizer Inc., Merck & Co., Inc., Novartis AG, Sanofi, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prostate Cancer Market Emerging Trajectories
Artificial intelligence is penetrating diagnostic and treatment planning workflows, while radiopharmaceutical manufacturing scales to meet demand for targeted alpha therapy in late-stage disease.
PSMA-targeted PET imaging is displacing conventional bone scan and CT staging protocols in high-risk and biochemical recurrence settings. Major cancer centers in the United States and Japan are adopting gallium-68 and fluorine-18 tracers as standard-of-care for metastasis detection. This displacement is compressing the diagnostic timeline from weeks to days while redirecting capital expenditure toward cyclotron and radiochemistry infrastructure.
REACH authorization requirements for novel chemical entities are tightening impurity specifications for kinase inhibitor active pharmaceutical ingredients manufactured in European Union facilities. EMA's updated guideline on genotoxic impurities now mandates sub-ppm thresholds for specific structural alerts, forcing contract manufacturers to deploy additional purification steps. Small-molecule suppliers serving the prostate cancer pipeline are responding by qualifying secondary API sources outside the EU regulatory perimeter.
Oncology purchasing committees are consolidating vendor relationships for precision medicine diagnostics, shifting from decentralized laboratory selection to system-wide contracts. Hospital networks in Germany and the United States are centralizing next-generation sequencing and immunohistochemistry procurement under single-source agreements with reference laboratories. This concentration is most visible in integrated delivery networks exceeding 50 hospital sites, where standardization overrides physician-level preference for local testing platforms.
Global Prostate Cancer Market Segmentation
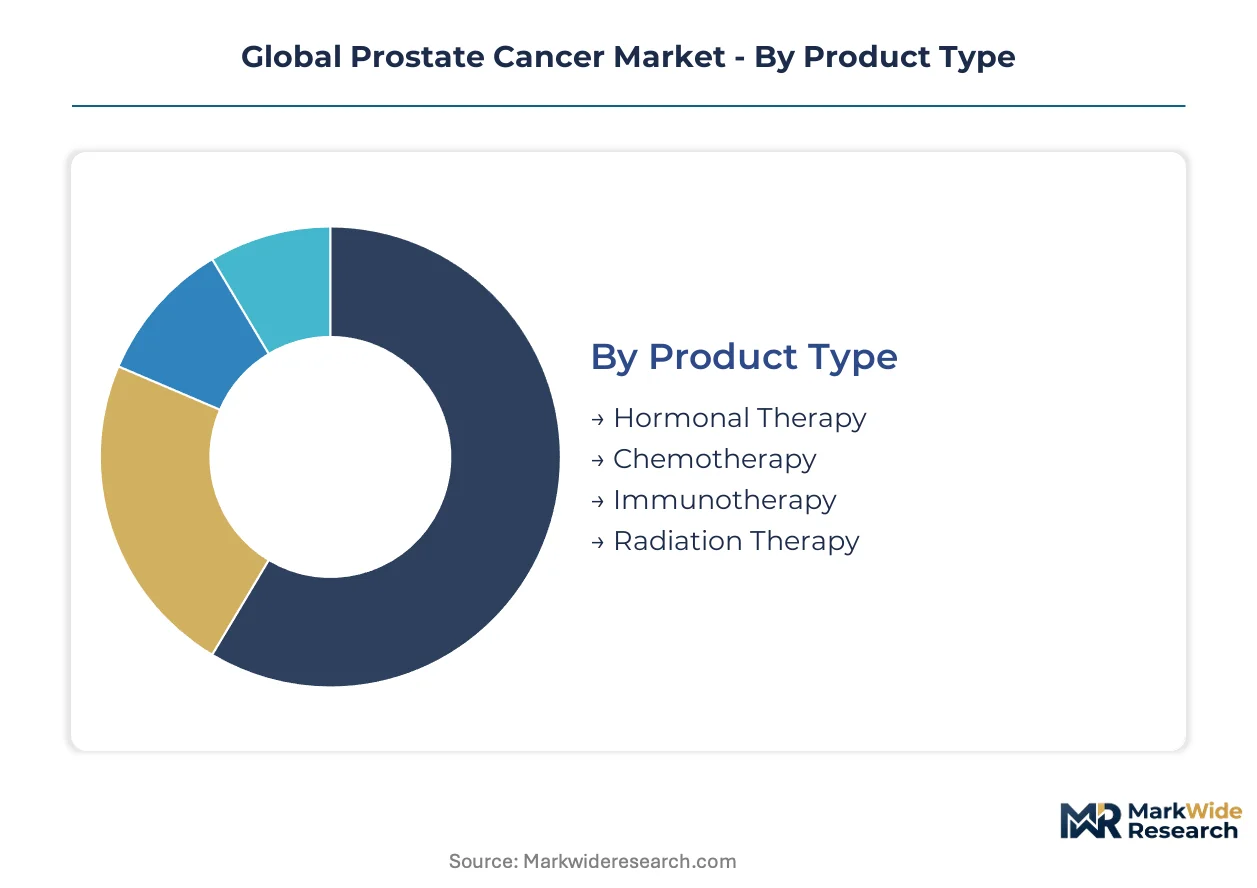
Segmentation in prostate cancer therapeutics reveals how regulatory pathways, reimbursement structures, and care delivery settings allocate value across distinct product and service categories. Understanding these divisions enables stakeholders to align portfolio investments with where clinical demand and pricing power are concentrating.
Product Type:
FDA breakthrough therapy designation and EMA conditional marketing authorization create divergent commercialization timelines across therapeutic modalities, favoring agents that compress Phase III-to-launch intervals.
- Hormonal Therapy:Androgen deprivation regimens employing GnRH agonists and androgen receptor inhibitors constitute the foundational pharmacologic intervention across all disease stages. Hospital procurement in the United States and Germany concentrates volume here due to established reimbursement codes and extended treatment duration in metastatic settings.
- Immunotherapy:Sipuleucel-T and checkpoint inhibitor combinations activate host anti-tumor responses in castration-resistant disease. Japan's PMDA alignment with FDA review standards is accelerating Asian-Pacific market entry for cellular immunotherapies, though manufacturing complexity limits community clinic adoption.
- Chemotherapy:Taxane-based regimens retain salvage utility in post-hormonal progression, with docetaxel and cabazitaxel formulations dominating infusion center throughput.
- Radiation Therapy:External beam and brachytherapy approaches compete with emerging radioligand therapies for curative-intent and palliative indications.
Established volume favors hormonal therapy; emerging adoption favors immunotherapy.
End User:
Site-of-care economics and reimbursement differentials are reallocating patient volumes between institutional and ambulatory settings.
- Hospitals:Academic medical centers in the United States, Germany, and Japan anchor clinical trial enrollment for novel agents and concentrate radiopharmaceutical administration due to cyclotron proximity. Medicare's hospital outpatient prospective payment system sustains margin capture for infused therapies.
- Home Care:Subcutaneous androgen receptor inhibitor formulations enable oncology practices to shift monitoring outside infusion centers. Germany's G-BA pilot programs for indication-based pricing are creating precedent for home administration reimbursement.
- Clinics:Community urology practices in the United States perform the majority of early-stage diagnoses and active surveillance protocols.
- Research Institutes:National cancer centers in Japan and Germany lead biomarker discovery and combination therapy protocol development.
Hospital infrastructure captures premium pricing; home care channels gain share fastest.
Treatment Stage:
Disease progression status determines therapeutic intensity, combination requirements, and duration of therapy.
- Metastatic Stage:Castration-resistant and castration-sensitive metastatic disease commands the highest per-patient revenue due to sequential combination requirements. FDA accelerated approval pathways have compressed development timelines for novel hormonal agents in this setting.
- Early Stage:Localized disease management through radical prostatectomy or radiation therapy offers curative intent with shorter pharmaceutical exposure. Expanded PSA screening in Japan is enlarging this addressable pool.
- Advanced Stage:Regionally extensive disease without distant metastasis requires multimodal coordination between urology and radiation oncology.
- Recurrent Stage:Biochemical relapse after definitive therapy drives PSMA-targeted PET imaging demand and salvage intervention decisions.
Metastatic protocols sustain revenue concentration; early-stage detection expands total addressable volume.
Administration Route:
Formulation technology and patient convenience preferences are shifting competitive advantage across delivery mechanisms.
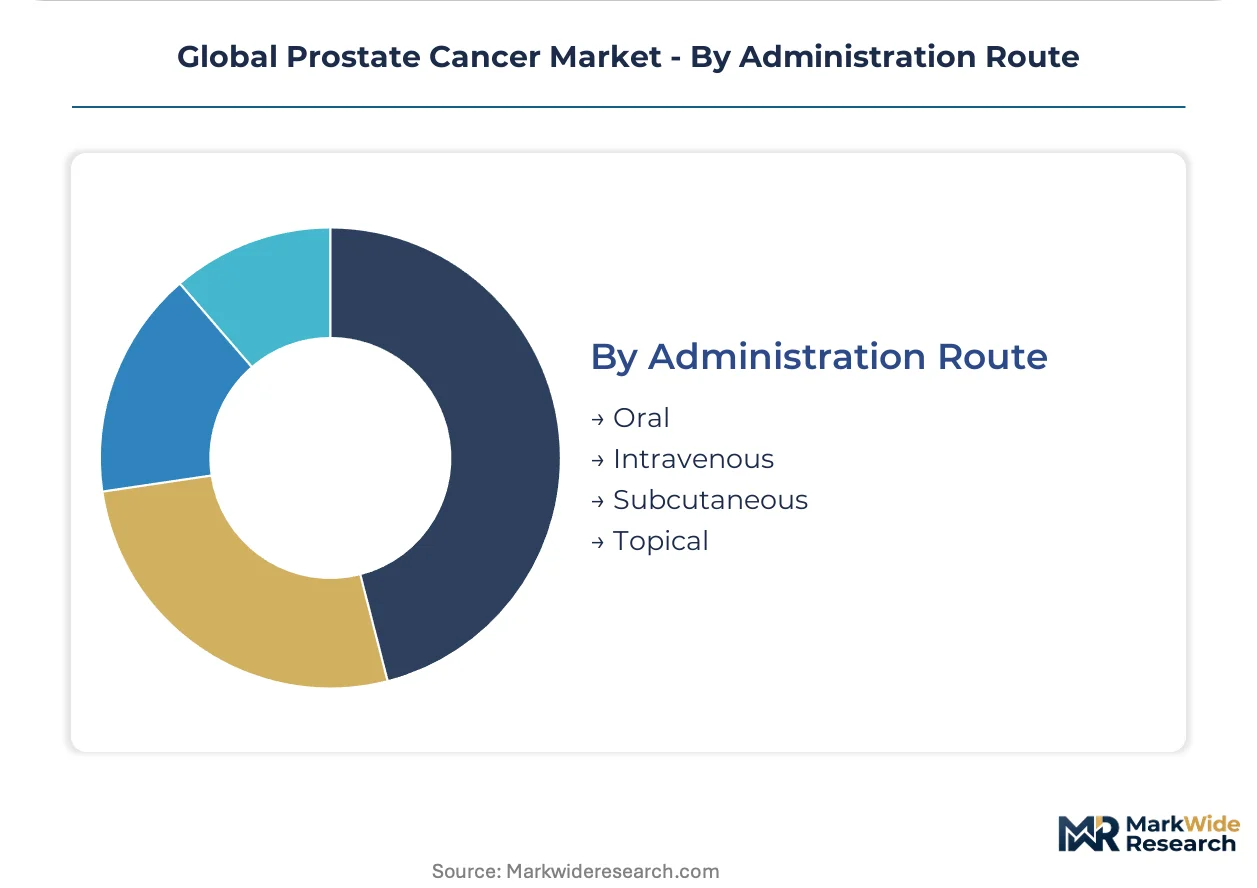
- Oral:Androgen receptor inhibitors and PARP inhibitors in tablet formulation enable patient self-administration and reduce healthcare utilization costs. REACH authorization requirements for active pharmaceutical ingredients are tightening impurity specifications for kinase inhibitors manufactured in EU facilities.
- Intravenous:Chemotherapy and immunotherapy infusion maintains hospital-based revenue capture despite site-of-care migration pressures.
- Subcutaneous:Leuprolide depot formulations and emerging androgen receptor inhibitors support clinic efficiency and home transition.
- Topical:Limited current utility in prostate cancer, though transdermal delivery research continues for hormonal agents.
Oral routes enable care setting flexibility; intravenous administration retains institutional anchoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and Medicare reimbursement structures anchor the United States as the dominant geography, while EMA conditional marketing authorization and Japan's PMDA alignment reshape commercialization timelines across Western Europe and Asia-Pacific.
United States
Hospital procurement of radioligand therapies and PARP inhibitor combinations drives volume concentration at academic medical centers. Medicare's hospital outpatient prospective payment system sustains margin capture for infused therapies in metastatic settings. The Greater Boston and San Francisco Bay Area clusters anchor clinical trial enrollment for novel hormonal agents.
Germany
G-BA indication-based pricing pilots and expanded mpMRI fusion biopsy deployment enlarge the curative-intent patient pool. REACH authorization requirements for active pharmaceutical ingredients tighten impurity specifications for kinase inhibitors manufactured in EU facilities. The Rhine-Ruhr and Munich metropolitan regions concentrate radiopharmaceutical administration due to cyclotron proximity.
Japan
National health insurance coverage of PSA velocity testing for men over 50 expands early-stage detection. PMDA alignment with FDA oncology review standards accelerates market entry for Western innovators. The Kanto region surrounding Tokyo anchors biomarker discovery and combination therapy protocol development at national cancer centers.
United Kingdom
NICE technology appraisals for novel hormonal agents create reimbursement precedent across the NHS. The Cancer Drugs Fund enables pre-approval access to PARP inhibitor combinations in castration-resistant settings. The Cambridge-London corridor concentrates precision medicine diagnostics procurement under single-source agreements with reference laboratories.
Switzerland
Swissmedic marketing authorization pathways and premium pricing tolerance attract headquarters functions for major oncology innovators. The Basel-Zurich corridor anchors radioligand therapy manufacturing scale and contract research organization concentration for prostate cancer clinical development.
Global Prostate Cancer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated revenue concentration among diversified pharmaceutical conglomerates and emerging competition from radiopharmaceutical-focused entities. The structure stratifies across three archetypes: kinase inhibitor portfolio holders, PARP inhibitor combination developers, and radioligand therapy manufacturers. Competitive moves center on strategic partnerships for diagnostic-therapeutic pairing and manufacturing scale expansion for alpha-emitting isotopes.
Within the integrated pharmaceutical tier, Johnson & Johnson and AstraZeneca occupy positions exemplifying diversified oncology portfolio anchoring, while Astellas Pharma represents the specialist archetype concentrated on urological malignancies. These entities sit within distinct competitive vectors—hormonal agent manufacturing scale, PARP inhibitor clinical development, and radioligand therapy distribution infrastructure—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Astellas Pharma |
| AstraZeneca |
| Bayer AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Sanofi |
| AbbVie Inc. |
| Others |
Supply Flow & Price Mechanics
Generic leuprolide substitution for branded GnRH agonists is compressing hormonal therapy margins while simultaneously redirecting procurement volume toward Indian and Chinese API manufacturers, fragmenting pricing power across hospital formularies and community clinic networks.
Pricing Analysis
Price spreads between the United States and Germany exceed those seen in other oncology categories due to Medicare's hospital outpatient prospective payment system anchoring premium reimbursement. Three-tier pricing structure across novel hormonal agents, PARP inhibitors, and generic taxanes reflects FDA breakthrough designation status and manufacturing complexity. Cost compression in the hormonal segment intensifies because of leuprolide commoditization. Community urology practices exhibit highest price sensitivity, while academic medical centers maintain formulary preference for branded agents.
Supply Chain Analysis
Cyclotron facility concentration in the northeastern United States and Rhineland-Palatinate creates single-point vulnerability for lutetium-177 and actinium-225 distribution. Active pharmaceutical ingredient production draws from India, China, and Switzerland for kinase inhibitor precursors. Isotope half-life constraints and cold-chain logistics requirements compound radiopharmaceutical supply fragility. Distribution runs through hospital-based nuclear pharmacies and specialized radiochemistry units rather than conventional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways for radioligand therapies and PARP inhibitors have compressed commercialization timelines, creating a high-growth disruption where manufacturing scale and diagnostic-therapeutic pairing determine competitive survival.
For Market Incumbents: Secure cyclotron capacity through long-term isotope supply agreements before actinium-225 scarcity constrains alpha-therapy expansion. Anchor hospital formulary position by integrating PSMA-targeted PET imaging with therapeutic sequences, defending against radiopharmaceutical-focused entrants. For New Entrants and Emerging Players: Differentiate on home administration infrastructure for subcutaneous androgen receptor inhibitors, targeting community oncology practices burdened by infusion center capacity constraints. Penetrate Japan's expanded PSA screening population through PMDA-aligned regulatory submissions and local biomarker partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed radiopharmaceutical manufacturers holding alpha-emitting isotope production licenses. Five-to-ten-year viability hinges on manufacturing scale rather than pipeline depth. Watch for EMA conditional marketing authorization conversions to full approval as inflection signals for revenue sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Pairing | PSMA-targeted PET imaging integration anchors reimbursement for radioligand therapy sequences. |
| Alpha-Emitting Isotope Scale-Up | Actinium-225 production capacity determines market access for next-generation targeted alpha therapy. |
| Home Administration Formulation | Subcutaneous androgen receptor inhibitors shift site-of-care economics toward community practices. |
| Liquid Biopsy Integration | Circulating tumor DNA testing expands precision therapy selection in castration-resistant settings. |
| Indication-Based Pricing Pilots | Germany's G-BA pilots create precedent for value-based contracts across combination regimens. |
Methodological Framework
The analysis maps hormonal therapy, immunotherapy, radioligand therapy, and precision diagnostics segments, each validated through hospital procurement managers, nuclear pharmacy directors, regulatory affairs leads, and formulary access specialists. Primary fieldwork combined with FDA filings, EMA assessment reports, ClinicalTrials.gov records, and hospital procurement database extracts enabled bottom-up and top-down triangulation across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across treatment stage, administration route, and regional regulatory cluster segmentations. CAGRs derived from patient flow modeling and pricing elasticity analysis incorporated PSA screening expansion rates, radiopharmaceutical manufacturing capacity buildouts, and conditional marketing authorization conversion probabilities as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement for radioligand therapies and continued FDA-EMA regulatory alignment would require recalibration. Forecasts reflect documented assumptions about isotope supply continuity and combination therapy adoption curves. Practitioners should keep alternative scenarios live as post-market confirmatory trial outcomes and radiochemistry workforce availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
India Urology Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urinary Catheters Market
Urology
Ureter Cancer Treatment Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
India Urology Device Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Disposable Ureteroscope Market
Urology
Penile Cancer Market
Urology
Global Prostate Health Market
Urology
Urology Lasers Market
Urology
Global Bladder Cancer Market