
 Global Androgen Deprivation Therapy Market | 2026-2036
Global Androgen Deprivation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Androgen Deprivation Therapy Market Foresight
The manufacturing scale gap between large-cap pharmaceutical conglomerates and mid-sized hormone specialists is redrawing competitive boundaries in androgen deprivation therapy. Johnson & Johnson leverages its vertically integrated biologics infrastructure to dominate long-acting depot formulation production. Tolmar Pharmaceuticals specializes in polymer-based drug delivery systems that sustain release kinetics over six-month intervals. Bayer anchors European supply through its captive API manufacturing network in Germany.
Androgen deprivation therapy encompasses pharmacological and surgical interventions that suppress testosterone synthesis or block androgen receptor signaling, typically achieved through GnRH agonist depot injections containing leuprolide acetate in polylactic-co-glycolic acid microspheres at doses ranging from 7.5 mg to 45 mg. These therapies starve prostate cancer cells of the dihydrotestosterone required for proliferation, forming the backbone of first-line management for hormone-sensitive malignancies. Among product type segments, GnRH antagonists are gaining fastest traction due to their immediate testosterone suppression without the flare phenomenon associated with agonist initiation. Oral androgen synthesis inhibitors now capture expanding margin pools as patients seek alternatives to clinic-based injection schedules. Hospitals remain the dominant end-user channel, though specialized urology clinics are capturing growing referral volumes for maintenance therapy administration.
The FDA's oncology drug approval framework and the EMA's centralized marketing authorization procedure jointly determine market access timelines for novel hormonal agents across North America and Europe. BIS certification requirements in India and NMPA registration mandates in China create layered compliance barriers for multinational manufacturers seeking to serve Asia-Pacific patient populations. Stakeholders must monitor evolving reimbursement criteria for oral versus injectable formulations as payers recalibrate cost-effectiveness thresholds across public and private coverage schemes.
Market Dynamics
The androgen deprivation therapy market is undergoing structural compression as GnRH antagonist formulations displace agonist protocols in hospital formularies, eliminating the testosterone flare window that previously required anti-androgen co-administration and reducing total cost of care per patient episode.
Growth Catalysts
- Oral Synthesis Inhibitors:Abiraterone acetate and enzalutamide tablets enable home-based administration, expanding patient eligibility beyond clinic-dependent populations in rural United States counties and Australian outback regions.
- FDA Breakthrough Therapy Designation:Accelerated review pathways compress Phase III-to-approval timelines for novel hormonal agents, compressing competitor response windows and rewarding first-mover manufacturing scale.
- Japan's PMDA Sakigake System:Priority review status for prostate cancer innovations creates regulatory arbitrage opportunities for depot formulations seeking early Asian market entry ahead of European centralized procedures.
Market Restraints
- API Supply Concentration:Leuprolide acetate active pharmaceutical ingredient production clusters in Italian and Spanish contract manufacturing organizations, exposing formulation sponsors to single-source disruption risk.
- Reimbursement Compression:Medicare's average sales price plus 6% reimbursement model for physician-administered drugs erodes margin pools on long-acting injectables as reference pricing spreads across United States commercial payers.
- Biologic Substitution Threat:Biosimilar goserelin implants from South Korean manufacturers threaten originator depot franchises in European tenders where cost-effectiveness thresholds dominate award criteria.
Strategic Opportunities
- Brazil's ANVISA Fast-Track:Priority review for oncology products creates first-mover positioning in Latin America's largest prostate cancer patient pool, where private insurance penetration is deepening.
- Subcutaneous Autoinjector Convergence:Combination of polymer-based sustained-release matrices with wearable injection devices enables six-month interval administration outside clinical settings, opening urology clinic bypass channels.
- India's PLI Scheme for APIs:Production-linked incentive structures for critical starting materials reduce import dependency for domestic formulation manufacturers serving Asia-Pacific price-sensitive segments.
Industry Challenges
- Sterile Manufacturing Talent Scarcity:Aseptic filling operations for microsphere depots require specialized operators; workforce gaps in German and Swiss manufacturing hubs delay capacity expansion timelines.
- Legacy EHR Integration Friction:Hormone therapy monitoring protocols in United States hospital systems require custom interface builds with Epic and Cerner platforms, extending implementation cycles for novel agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Androgen Deprivation Therapy Market |
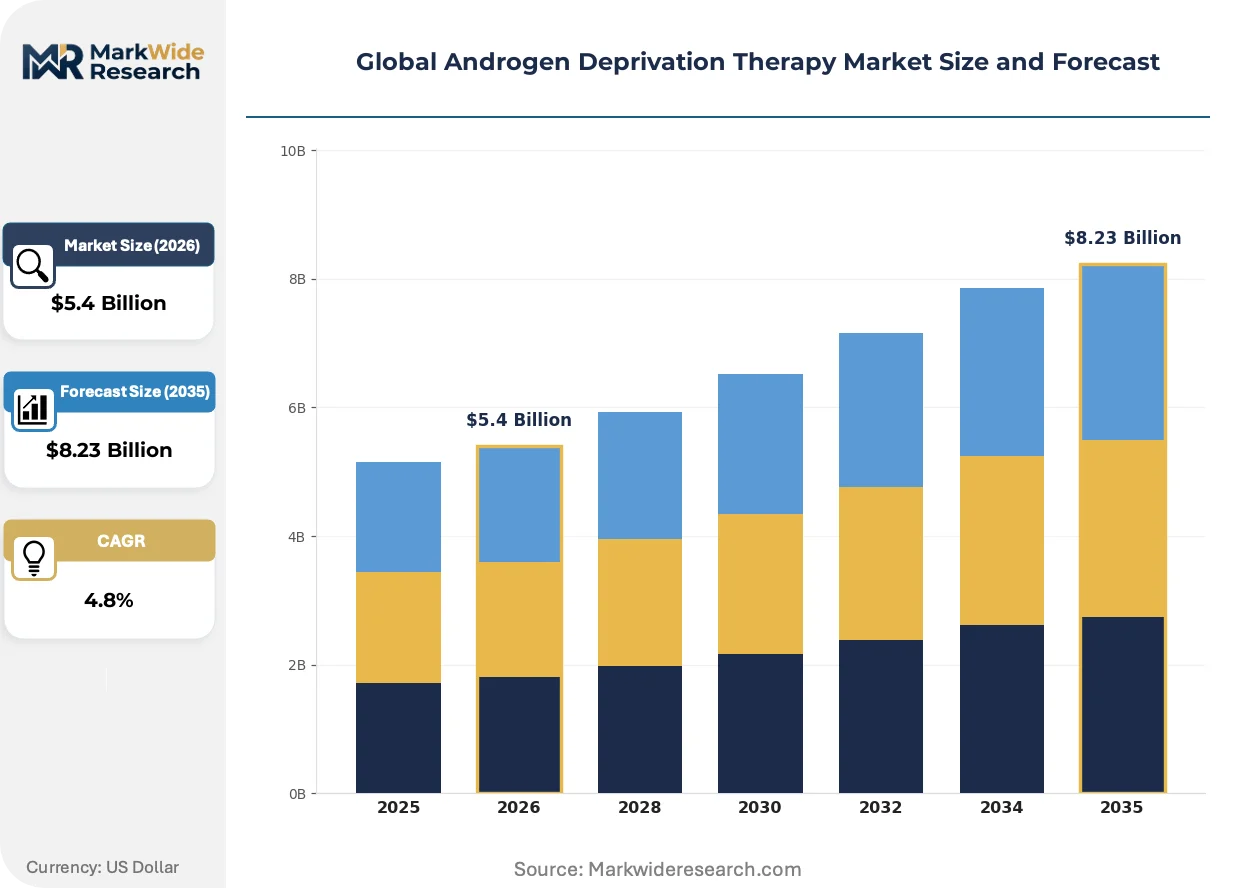
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gonadotropin-Releasing Hormone Agonists, Anti-Androgens, Gonadotropin-Releasing Hormone Antagonists, Androgen Synthesis Inhibitors, Orchiectomy Therapy Area: Prostate Cancer, Metastatic Castration-Resistant Cancer, Advanced Prostate Carcinoma, Benign Prostatic Hyperplasia, Hormone-Sensitive Prostate Conditions End User: Hospitals, Specialized Urology Clinics, Cancer Treatment Centers, Ambulatory Surgical Centers, Diagnostic Laboratories Delivery Mode: Injectable, Oral, Transdermal Patch, Implantable, Surgical Procedure |
| Companies Covered | Astellas Pharma, Tolmar Pharmaceuticals, Johnson & Johnson, Myovant Sciences, Ferring Pharmaceuticals, AstraZeneca, AbbVie, Viatris, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Androgen Deprivation Therapy Market Shifts & Advancements
Active pharmaceutical ingredient sourcing patterns and delivery modality preferences are diverging across reimbursement environments, creating technology bets that favor either clinic-centric depot administration or patient-directed oral regimens depending on payer architecture.
Implantable polymer matrices incorporating leuprolide acetate into biodegradable lactide-glycolide copolymers are miniaturizing depot dimensions while extending release duration from three to six months. United States urology clinics are adopting these formulations at accelerating pace as Medicare reimbursement differentials favor reduced injection frequency. The technology is miniaturizing patient burden and compressing total healthcare utilization per treatment course.
EMA's centralized marketing authorization procedure now mandates real-world evidence submission for hormonal oncology products, shifting pre-approval investment toward observational registry infrastructure. Manufacturers must deploy post-marketing surveillance systems across German, French, and Italian hospital networks before commercial launch. This regulatory evolution most affects GnRH antagonist sponsors seeking European Union-wide label claims.
Hospital procurement committees in the United States are consolidating hormone therapy purchasing through group purchasing organizations, displacing individual physician preference as the dominant selection criterion. Cardinal Health and McKesson distribution networks are capturing formulary gatekeeper roles previously held by academic medical center pharmacy directors. This concentration is most visible in Texas and Florida hospital systems where prostate cancer caseloads drive volume-based contracting.
Global Androgen Deprivation Therapy Market Segmentation
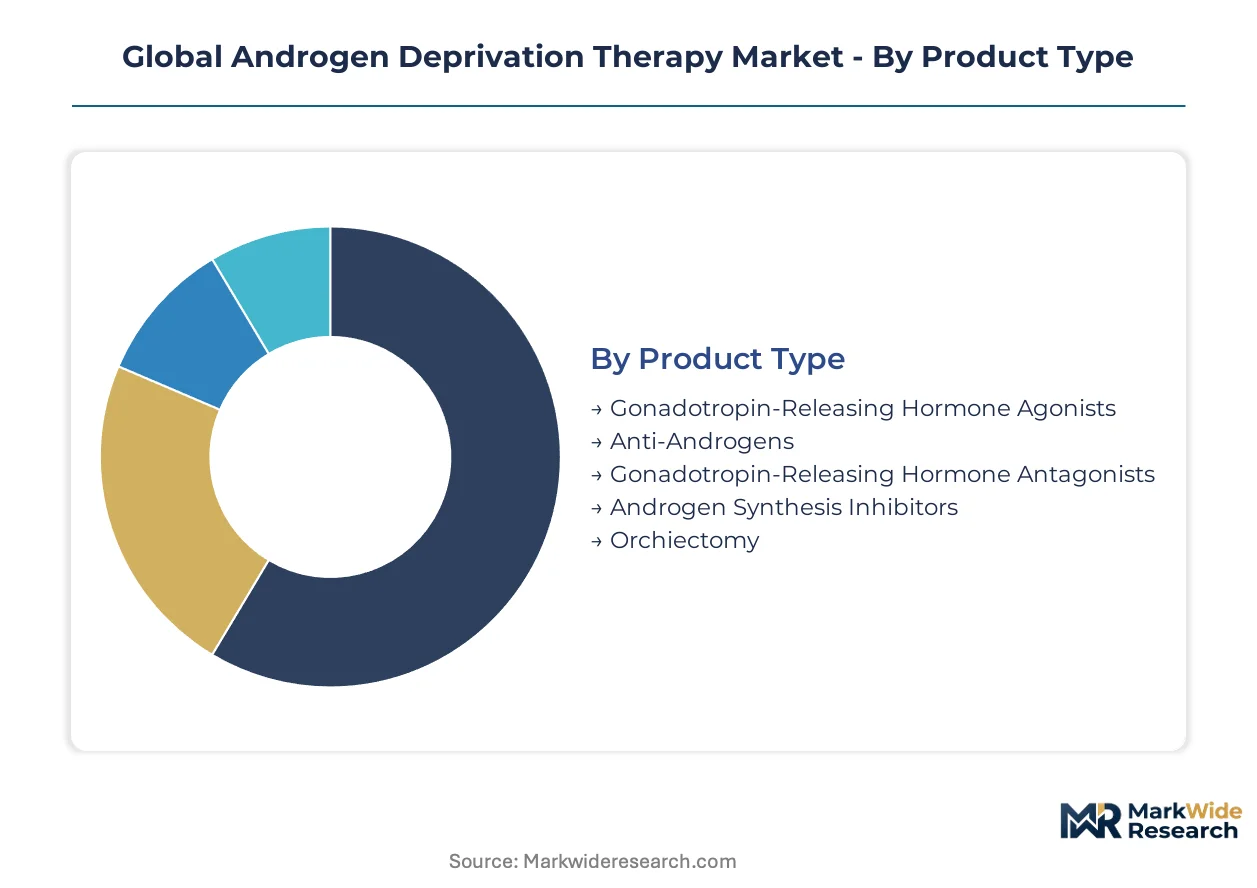
Androgen deprivation therapy segmentation reveals how reimbursement architecture and site-of-care economics allocate margin pools across formulation types and administration settings. Understanding these partitions exposes where manufacturing scale and regulatory investment yield sustainable returns.
Product Type:
GnRH antagonists and oral synthesis inhibitors command premium margin pools as they displace legacy agonist protocols in United States hospital formularies.
- Gonadotropin-Releasing Hormone Agonists:Leuprolide acetate depot injections in polylactic-co-glycolic acid microspheres remain the volume backbone, though Medicare reimbursement compression on physician-administered drugs erodes profitability per injection episode.
- Gonadotropin-Releasing Hormone Antagonists:Degarelix formulations eliminate testosterone flare without anti-androgen co-administration, capturing fastest share gains in Texas and Florida hospital systems where total cost-of-care metrics dominate formulary decisions.
- Anti-Androgens:Bicalutamide and enzalutamide receptor blockers serve as combination therapy anchors in metastatic settings.
- Androgen Synthesis Inhibitors:Abiraterone acetate tablets enable home-based administration, expanding reach into rural United States counties with limited infusion infrastructure.
- Orchiectomy:Surgical castration persists in price-sensitive segments and emergent markets where pharmaceutical access remains constrained.
GnRH agonists hold installed capacity. Antagonists are rotating up the share rankings.
Therapy Area:
Metastatic castration-resistant indications concentrate margin pools where combination regimens justify premium pricing against survival endpoints.
- Prostate Cancer:Hormone-sensitive disease management represents the foundational addressable population, with GnRH-based protocols initiating care in hospital oncology departments across Germany, France, and Italy.
- Metastatic Castration-Resistant Cancer:Advanced disease states command highest per-patient revenue as oral synthesis inhibitors layer onto depot foundations, with EMA real-world evidence requirements intensifying pre-launch investment in observational registry infrastructure.
- Advanced Prostate Carcinoma:Regional nodal involvement drives sustained therapy duration and repeat injection cycles.
- Benign Prostatic Hyperplasia:Non-malignant applications capture volume in ambulatory settings with abbreviated treatment courses.
- Hormone-Sensitive Prostate Conditions:Early intervention protocols are expanding eligible populations ahead of metastatic progression.
Metastatic castration-resistant applications concentrate value capture. Hormone-sensitive conditions are climbing the fastest.
End User:
Site-of-care migration from inpatient to ambulatory settings reallocates margin pools toward specialized urology clinics with streamlined injection protocols.
- Hospitals:Academic medical centers and community hospital systems in the United States remain dominant volume channels, though group purchasing organization consolidation through Cardinal Health and McKesson networks displaces individual physician preference in formulary gatekeeping.
- Specialized Urology Clinics:Standalone practices in Australian metropolitan areas and United States suburban corridors capture growing maintenance therapy volumes as six-month depot formulations reduce required visit frequency.
- Cancer Treatment Centers:Dedicated oncology facilities concentrate complex case management and combination therapy administration.
- Ambulatory Surgical Centers:Procedure-based settings handle orchiectomy volumes and implantable device placement.
- Diagnostic Laboratories:PSA monitoring and testosterone level assessment support therapy titration decisions.
Hospitals anchor installed capacity. Specialized urology clinics are gaining share fastest.
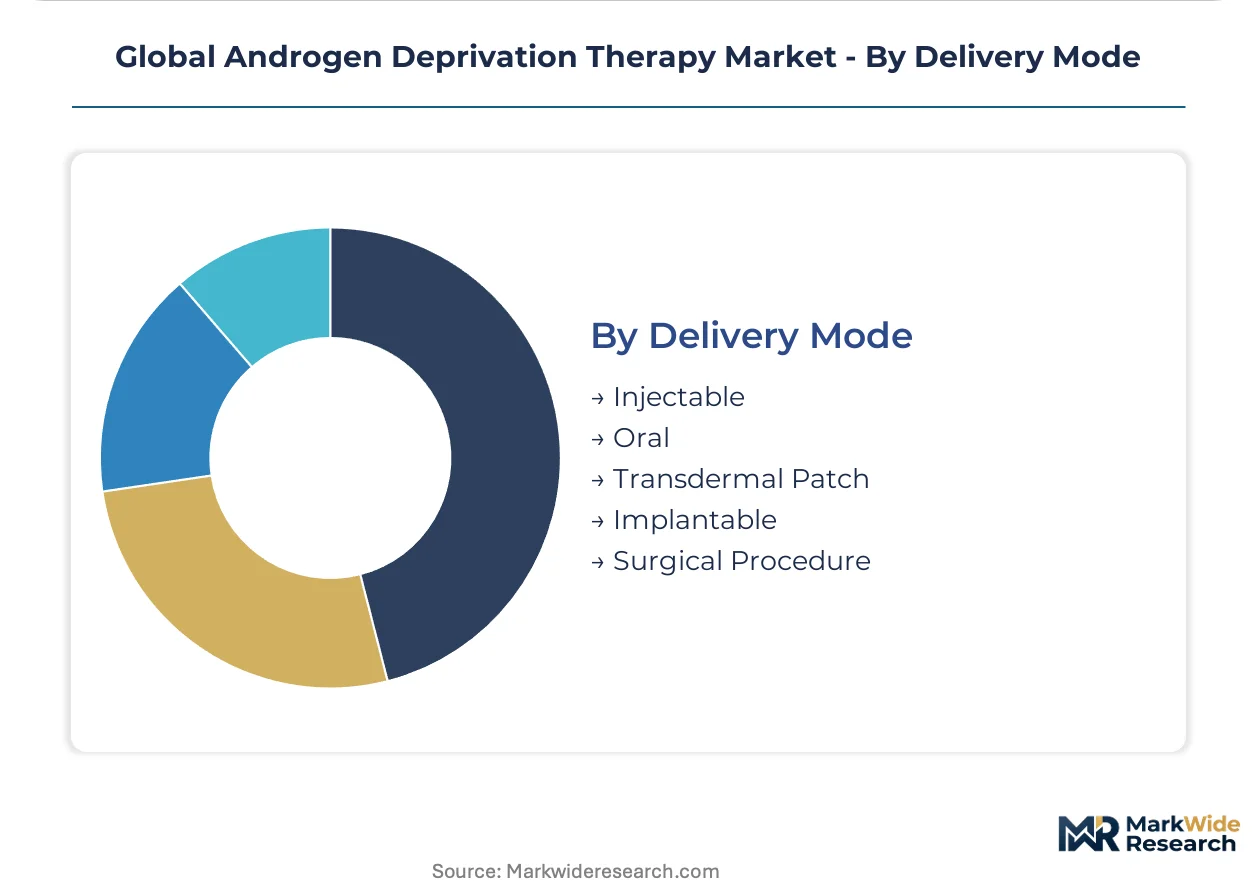
Delivery Mode:
Injectable formulations defend margin pools through Medicare reimbursement differentials, while oral modalities capture patient-directed preference in commercial payer segments.
- Injectable:Subcutaneous and intramuscular depot administrations in leuprolide microspheres dominate United States Medicare reimbursement structures, with polymer-based sustained-release matrices extending intervals from three to six months and compressing total healthcare utilization.
- Oral:Abiraterone and enzalutamide tablets penetrate private insurance populations in Brazil and India where clinic access constraints favor home-based administration, though Japan's PMDA Sakigake priority review creates regulatory arbitrage for novel oral entrants seeking early Asian market positioning.
- Transdermal Patch:Alternative non-invasive delivery remains limited by skin permeation challenges for peptide-based actives.
- Implantable:Biodegradable lactide-glycolide copolymer matrices miniaturize patient burden in select European markets.
- Surgical Procedure:Orchiectomy persists where pharmaceutical supply chains face disruption risk or patient preference favors definitive intervention.
Injectable formats hold installed capacity. Oral delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States patients least price-sensitive due to Medicare reimbursement structures while Indian and Brazilian markets exhibit acute sensitivity to out-of-pocket costs for long-acting injectables.
United States
Texas and Florida hospital systems drive volume concentration through group purchasing organization consolidation, with Cardinal Health and McKesson networks capturing formulary gatekeeper roles. The FDA's accelerated approval pathways compress development timelines for novel hormonal agents. Philadelphia-area specialty urology clinics in suburban corridors are adopting six-month depot formulations at accelerating pace as reimbursement differentials favor reduced injection frequency.
Germany
Bavarian and North Rhine-Westphalian hospital networks anchor European demand for GnRH-based protocols in prostate cancer management. The EMA's centralized marketing authorization procedure mandates real-world evidence submission, shifting pre-approval investment toward observational registry infrastructure. Frankfurt's pharmaceutical manufacturing cluster hosts captive API production facilities serving formulation sponsors seeking European Union-wide label claims.
Japan
Kanto region academic medical centers concentrate hormone-sensitive prostate cancer caseloads requiring first-line GnRH intervention. The PMDA Sakigake priority review system creates regulatory arbitrage opportunities for depot formulations seeking early Asian market entry ahead of European procedures. Osaka-based urology specialists are capturing growing maintenance therapy volumes as six-month formulations reduce required visit frequency.
Brazil
São Paulo's private insurance networks deepen penetration for oral synthesis inhibitors among patients seeking alternatives to clinic-dependent populations. ANVISA's fast-track priority review for oncology products creates first-mover positioning in Latin America's largest addressable patient pool. Rio de Janeiro metropolitan area cancer treatment centers concentrate complex case management and combination therapy administration for metastatic indications.
India
Maharashtra and Gujarat formulation manufacturers serve price-sensitive Asia-Pacific segments through domestic production of leuprolide acetate alternatives. The PLI scheme for APIs reduces import dependency for critical starting materials. Hyderabad's contract research organizations support bioequivalence studies for generic entrants targeting BIS certification requirements.
Global Androgen Deprivation Therapy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates commanding manufacturing scale advantages while mid-sized hormone specialists defend niche positioning through polymer-based delivery technologies. The market exhibits tiered concentration where vertical integration into biologics infrastructure separates volume leaders from formulation-dependent competitors. Three archetypes dominate: diversified pharmaceutical conglomerates with captive API networks, hormone therapy specialists focused on sustained-release matrices, and oncology-focused biotechs with novel mechanism assets. Competitive moves center on manufacturing capacity expansion for six-month depot formulations and strategic partnerships to secure leuprolide acetate supply.
Within the diversified pharmaceutical tier, Johnson & Johnson and Bayer occupy positions defined by integrated biologics infrastructure and European captive manufacturing networks respectively. Tolmar Pharmaceuticals exemplifies the hormone specialist archetype through polymer-based drug delivery concentration. Astellas Pharma represents the oncology-focused biotech positioning with novel hormonal agent development. These three anchors illustrate how competitive advantage flows from manufacturing scale, formulation technology, or regulatory pathway expertise rather than overlapping capabilities.
| Leading Market Players |
|---|
| Astellas Pharma |
| Tolmar Pharmaceuticals |
| Johnson & Johnson |
| Myovant Sciences |
| Ferring Pharmaceuticals |
| AstraZeneca |
| AbbVie |
| Viatris |
| Bayer |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Italian and Spanish contract manufacturing organizations and depot formulation sponsors lock in leuprolide acetate supply access while capping price visibility for sponsors facing Medicare reimbursement compression on physician-administered drugs in the United States.
Pricing Analysis
After-sales revenue from injection administration services and patient monitoring protocols drives lifetime value capture for clinic-based GnRH agonist protocols. The dominant pricing structure operates on a contract-based long-term offtake model for API supply paired with Medicare's average sales price plus 6% reimbursement for physician-administered formulations. Price differentiation stems from formulation interval duration and site-of-care economics, with six-month depots commanding premium positioning over three-month alternatives. Cost compression in the Medicare-reimbursed injectable tier is intensifying as reference pricing spreads across United States commercial payers. Oral synthesis inhibitor patients in private insurance segments exhibit lowest price sensitivity, while cash-pay populations in Indian and Brazilian markets face acute out-of-pocket burden for long-acting injectables.
Supply Chain Analysis
Italy and Spain anchor leuprolide acetate API production through specialized peptide synthesis contract manufacturing organizations, with Germany and Switzerland hosting sterile fill-finish operations for microsphere depot formulations. Raw material dependencies center on amino acid precursors, polylactic-co-glycolic acid polymers, and specialized aseptic packaging components. Single-source vulnerability concentrates in the Italian CMO network where sterile manufacturing talent scarcity delays capacity expansion timelines. Distribution runs through Cardinal Health and McKesson group purchasing organization networks in the United States, displacing individual hospital pharmacy procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aseptic filling capabilities for sustained-release microspheres sit in critically short supply relative to demand for six-month depot formulations, constraining expansion timelines for sponsors seeking manufacturing scale advantages.
For Market Incumbents: Fortify captive API supply positions through backward integration into leuprolide acetate precursor synthesis or exclusive offtake arrangements with Italian and Spanish contract manufacturers. Expand sterile filling capacity in German and Swiss manufacturing hubs before workforce gaps widen further. Biosimilar goserelin threats from South Korean manufacturers demand accelerated six-month formulation development to defend Medicare reimbursement differentials. For New Entrants and Emerging Players: Differentiate on subcutaneous autoinjector convergence with polymer-based sustained-release matrices, enabling six-month administration outside clinical settings. Target specialized urology clinics in Australian metropolitan areas and United States suburban corridors where maintenance therapy volumes concentrate and group purchasing organization consolidation has not yet captured formulary gatekeeping. Pursue Brazil's ANVISA fast-track oncology priority review to establish first-mover positioning in Latin America's largest addressable patient pool before European centralized procedures conclude. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hormone therapy specialists with polymer-based drug delivery platforms and established depot formulation franchises. Long-term viability over the coming decade hinges on manufacturing scale advantages in sustained-release matrices and regulatory pathway expertise across FDA, EMA, and PMDA jurisdictions. Acquisition targets should demonstrate captive API supply or exclusive CMO relationships rather than formulation-only positioning. Monitor Japan's PMDA Sakigake priority review awards as an inflection indicator for depot formulations achieving accelerated Asian market entry ahead of European competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Six-month depot capacity expansion in German sterile filling hubs captures Medicare reimbursement differentials. |
| Regulatory Approval Pathway | FDA Breakthrough Therapy Designation compresses Phase III-to-approval timelines for novel hormonal agents. |
| Backward Integration | Captive leuprolide acetate API production insulates against Italian CMO single-source disruption risk. |
| Licensing Agreement | Polymer-based delivery technology partnerships enable subcutaneous autoinjector convergence for clinic bypass. |
| Pipeline Diversification | Oral synthesis inhibitor development expands reach into rural United States counties with limited infusion infrastructure. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions underlying this analysis. Primary interviews with formulary directors at Texas and Florida hospital systems, combined with secondary validation through FDA filings, EMA centralized marketing authorization procedures, ClinicalTrials.gov entries, and Medicare reimbursement databases, established the evidentiary foundation. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-checked volume and value estimates.
Segmentation dimensions modeled span product type, therapy area, end user channel, and delivery mode across the projection horizon. Treatment line stratification, dosage form differentiation, administration route economics, and regional regulatory cluster dynamics informed the analytical framework. CAGRs were derived from patient population growth trajectories, reimbursement rate evolution, and formulation substitution patterns. Forecast inputs incorporated prostate cancer incidence projections, GnRH antagonist share rotation velocity, and oral synthesis inhibitor penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement differentials for long-acting injectables or accelerated FDA approval pathway continuity would require recalibration. Forecasts reflect assumptions regarding sterile manufacturing capacity expansion timelines, leuprolide acetate API supply stability, and group purchasing organization consolidation velocity. Recalibration cycles align with material shifts in reimbursement policy, regulatory approval timelines, and biosimilar substitution dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Anti-Viral Therapeutics Market