
 Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market | 2026-2036
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market Outlook
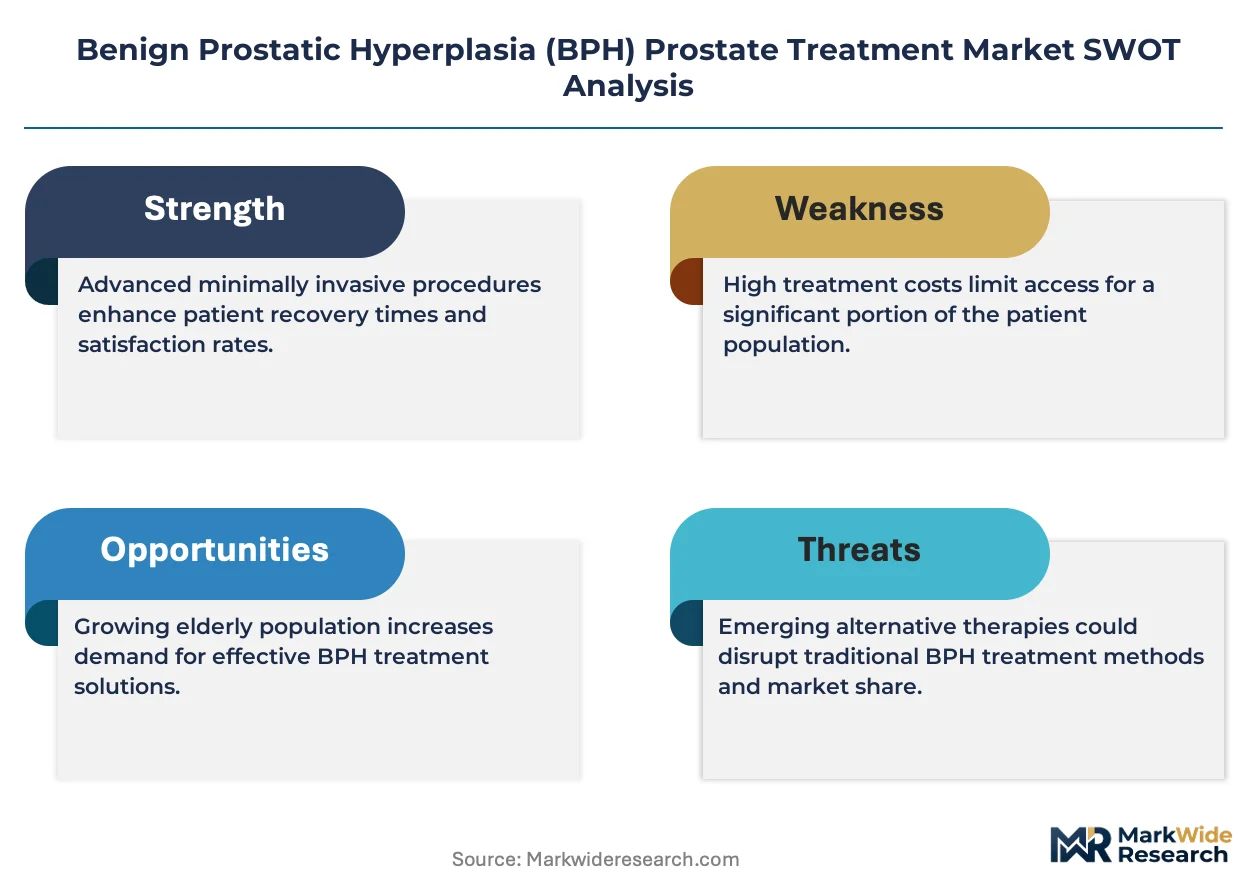
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in BPH surgical devices, elevating compliance costs for entrants while insulating incumbents with established quality systems. Boston Scientific Corporation leverages its electrophysiology manufacturing infrastructure to sustain catheter-based prostate therapy production at scale. PROCEPT BioRobotics Corporation differentiates through robotic waterjet ablation technology, occupying a niche between pharmacotherapy and conventional surgery. Eli Lilly & Company anchors the pharmacotherapy segment with established urology therapeutic portfolios.
Benign prostatic hyperplasia prostate treatment encompasses medical and interventional modalities designed to relieve lower urinary tract symptoms caused by prostate gland enlargement, including alpha-blockers, 5-alpha reductase inhibitors, transurethral resection systems, and laser vaporization platforms operating at 532 nm or 980 nm wavelengths. The primary purpose is to restore urinary flow while minimizing sexual dysfunction and inpatient recovery time. Medications still command the largest revenue pool due to chronic administration patterns, though minimally invasive treatments are capturing the fastest growth trajectory as ambulatory surgery centers expand capacity. Laser therapies concentrate margin pools in high-throughput urology practices with capital equipment amortization models, while surgical devices face pricing pressure from hospital value-analysis committees.
FDA 510(k) premarket notification and the European Medical Device Regulation shape product development timelines, with MDR clinical evidence requirements extending certification cycles for novel ablation technologies. The Centers for Medicare & Medicaid Services outpatient procedure reimbursement codes directly influence physician site-of-service decisions between hospital operating rooms and ambulatory settings. Stakeholders must monitor how FDA breakthrough device designations for photoselective vaporization systems alter competitive dynamics between established laser manufacturers and emerging robotic platforms.
Market Dynamics
Site-of-service migration toward ambulatory surgery centers is restructuring BPH procedural economics, compressing reimbursement differentials between hospital-based and outpatient settings while forcing device manufacturers to recalibrate capital equipment pricing for lower-acuity environments.
Growth Catalysts
- CMS outpatient reimbursement codes:The Centers for Medicare & Medicaid Services has expanded procedural coverage for laser ablation in ambulatory settings, redirecting case volume from inpatient facilities.
- Photoselective vaporization at 532 nm:Greenlight laser systems reduce intraoperative bleeding and catheterization time, accelerating same-day discharge protocols in high-throughput urology practices.
- Aging male demographics in the United States:The 65-plus population cohort drives symptomatic BPH prevalence, expanding the addressable patient pool for interventional therapies beyond pharmacological management.
Market Restraints
- Capital equipment amortization burdens:Laser platforms require substantial upfront investment, constraining adoption among independent urology groups without hospital system affiliation.
- European Medical Device Regulation clinical evidence requirements:MDR recertification timelines for ablation devices have extended by 12-18 months, delaying market entry for novel technologies.
- 5-alpha reductase inhibitor maintenance therapy:Chronic pharmaceutical management retains substantial patient share due to lower immediate cost exposure and reversible side-effect profiles.
Strategic Opportunities
- Underpenetrated ambulatory surgery center networks in Germany:Outpatient urology infrastructure remains fragmented, creating first-mover advantages for device manufacturers establishing direct procurement relationships.
- Robotic waterjet ablation convergence:Integration of automated tissue recognition with minimally invasive delivery systems occupies the therapeutic gap between medical management and transurethral resection.
- FDA breakthrough device designation pathway:Expedited review for next-generation photoselective systems compresses regulatory timelines and accelerates competitive positioning against established laser platforms.
Industry Challenges
- ISO 13485 quality management system implementation:Medical device manufacturers face substantial documentation and audit burdens to maintain certification across multiple notified bodies.
- Integration complexity with electronic health record systems:Robotic surgical platforms require seamless data interoperability with hospital information technology infrastructure, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market |
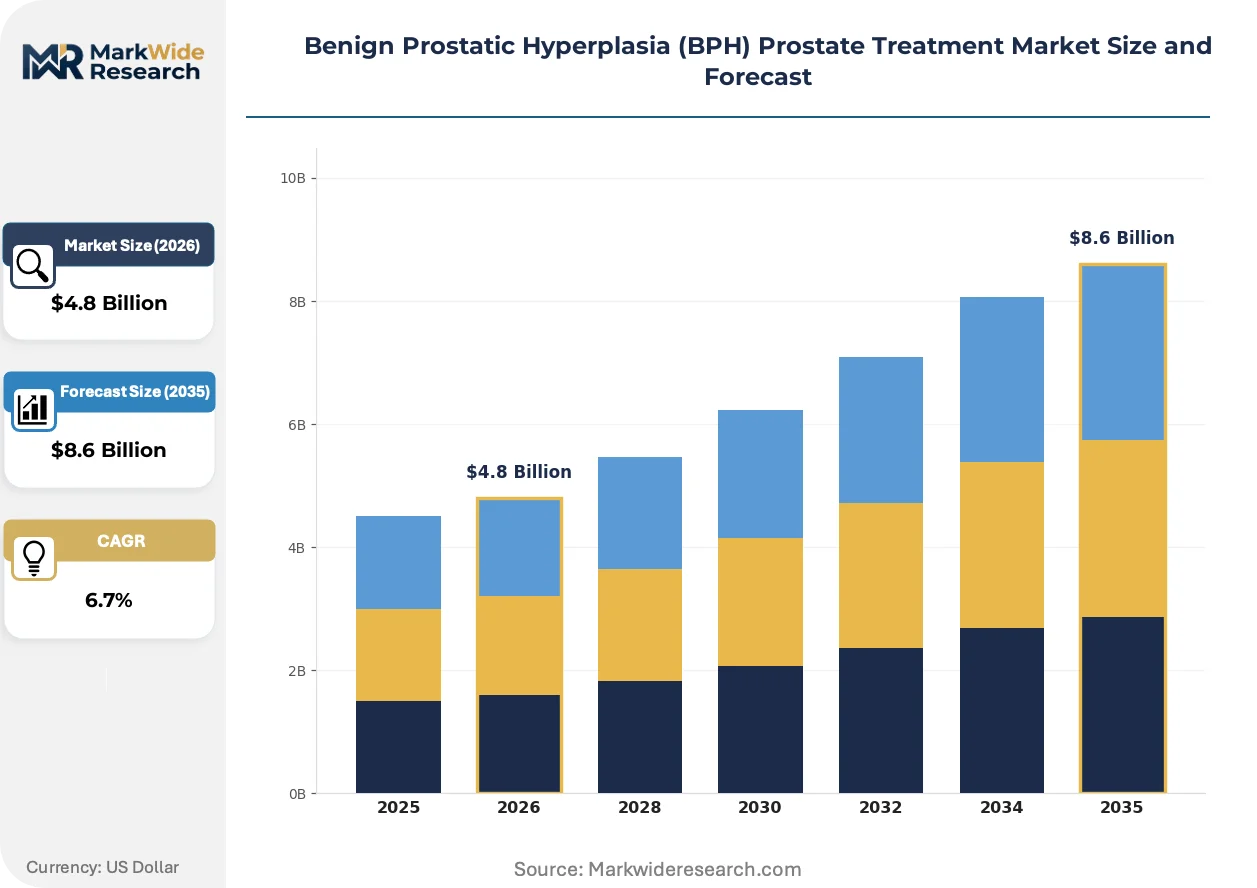
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
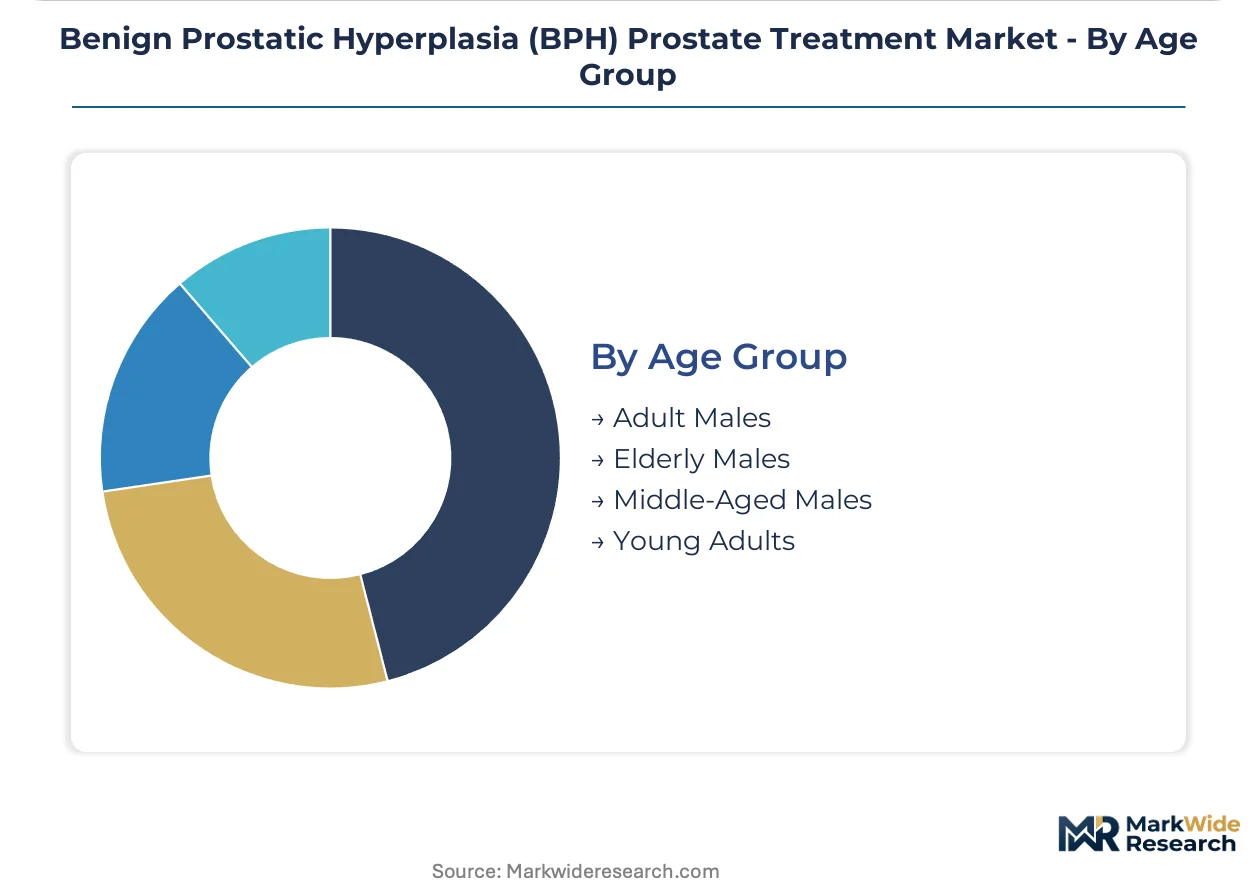
| Segmentation | Product Type: Medications, Surgical Devices, Minimally Invasive Treatments, Laser Therapies End User: Urologists, Hospitals, Ambulatory Surgery Centers, Urgent Care Clinics Treatment Method: Pharmacotherapy, Surgery, Radiofrequency Ablation, Photoselective Vaporization Age Group: Adult Males, Elderly Males, Middle-Aged Males, Young Adults |
| Companies Covered | Pfizer Inc., Boston Scientific Corporation, GlaxoSmithKline Plc., Teleflex Incorporated, Olympus Corporation, Sanofi S.A., Eli Lilly & Company, NeoTract Inc., PROCEPT BioRobotics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market Strategic Shifts
Technological substitution in BPH intervention is accelerating as energy-based therapies challenge mechanical resection dominance, while regulatory frameworks and procurement models co-evolve to accommodate outpatient procedural migration.
Waterjet robotic ablation is supplanting conventional transurethral resection in tertiary referral centers by preserving ejaculatory function while achieving equivalent urinary flow improvement. Ambulatory surgery centers in the United States are adopting these platforms at accelerating pace as case volume shifts from hospital operating rooms. The technology is compressing the competitive window for incremental laser vaporization improvements by offering differentiated clinical outcomes.
The European Medical Device Regulation has intensified clinical evidence requirements for novel ablation technologies, mandating prospective registry data that extends certification cycles. Manufacturers now face substantial post-market surveillance obligations that reshape product development resource allocation. High-throughput urology practices in France and Germany are responding by consolidating purchasing decisions around established CE-marked platforms with demonstrated long-term safety profiles.
Hospital value-analysis committees have assumed centralized control over capital equipment procurement, unbundling device selection from individual physician preference. Independent urology groups are losing direct purchasing authority as health system integration accelerates across the United States. This concentration is most visible in metropolitan markets where commercial urology group consolidation has created regional purchasing monopolies.
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market Segmentation
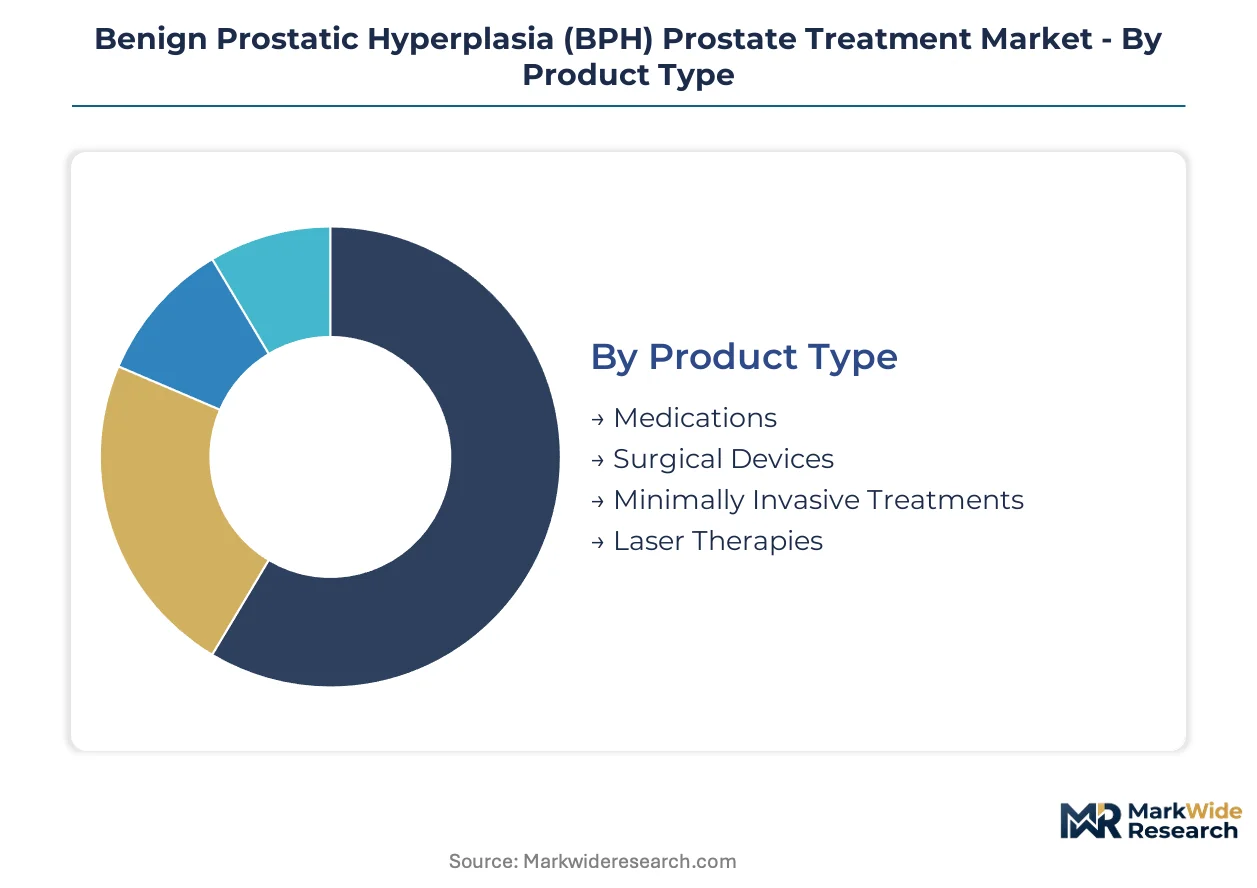
Channel configuration determines how BPH treatment modalities reach patients, with reimbursement codes and site-of-service economics dictating which segments flow through hospital systems versus ambulatory networks. Understanding these pathways reveals where manufacturers must align pricing and clinical evidence to capture procedural volume.
Product Type:
Channel mix varies sharply across product categories, with chronic medications flowing through retail pharmacy networks while capital equipment and consumables route through hospital value-analysis committees or ambulatory surgery center direct procurement.
- Medications:Alpha-blockers and 5-alpha reductase inhibitors distribute through retail pharmacy and specialty urology clinic dispensaries. Demand concentrates in the United States where Medicare Part D coverage drives chronic adherence patterns among elderly males with persistent lower urinary tract symptoms.
- Surgical Devices:Resectoscopes and electrocautery systems require hospital operating room integration and sterile processing infrastructure. Adoption clusters in integrated delivery networks where value-analysis committees centralize purchasing authority away from individual urologists.
- Minimally Invasive Treatments:Catheter-based delivery systems and implantable devices move through hybrid channels combining hospital outpatient departments with ambulatory surgery centers.
- Laser Therapies:Holmium and greenlight laser platforms with reusable fiber optics and capital equipment amortization models.
By volume, Medications leads. By expansion trajectory, Minimally Invasive Treatments is climbing the fastest as ambulatory migration accelerates.
End User:
Customer concentration patterns reveal where procedural economics favor high-throughput specialists over generalists, with reimbursement differentials and capital access separating institutional tiers.
- Urologists:Board-certified specialists in private practice or employed by health systems who control patient selection for interventional versus medical management. Volume concentrates in metropolitan markets where commercial group consolidation has created regional referral monopolies.
- Hospitals:Inpatient and outpatient departments with 24-hour emergency coverage and complex case capability. Demand clusters in tertiary centers managing complications from failed prior interventions or significant comorbidities requiring anesthesia support.
- Ambulatory Surgery Centers:Freestanding facilities optimized for same-day discharge protocols and lower overhead structures.
- Urgent Care Clinics:Walk-in settings handling acute urinary retention episodes and initial diagnostic workup before specialist referral.
By procedure count, Hospitals dominates. By volume shift, Ambulatory Surgery Centers is gaining share fastest as CMS reimbursement redirects cases.
Treatment Method:
Technology maturity curves separate established standards from emerging modalities, with clinical evidence thresholds and learning curves determining which methods penetrate which provider tiers.
- Pharmacotherapy:First-line medical management using alpha-adrenergic antagonists and 5-alpha reductase inhibitors requiring no procedural infrastructure. Demand concentrates among primary care gatekeepers and urologists managing patients with moderate symptoms prioritizing reversible interventions.
- Surgery:Transurethral resection of the prostate remains the reference standard for large gland volumes and refractory cases. Adoption clusters in academic medical centers training residents and managing complex anatomy.
- Radiofrequency Ablation:Thermal energy delivery via catheter systems for targeted tissue necrosis with preserved sexual function.
- Photoselective Vaporization:532 nm greenlight laser achieving hemostatic tissue removal with reduced irrigation requirements.
By patient share, Pharmacotherapy leads. By technology substitution speed, Photoselective Vaporization is expanding most quickly.
Age Group:
Disease prevalence and treatment tolerance vary across demographic cohorts, with symptom severity, life expectancy, and sexual function priorities shaping modality selection.
- Adult Males:Men aged 40-64 with early symptomatic disease and high preservation priorities for sexual function. Demand concentrates in concierge urology practices and direct-pay models where patients seek minimally invasive alternatives before disease progression.
- Elderly Males:Patients 65 and older with advanced gland enlargement, comorbid cardiovascular conditions, and anticoagulation requirements. Volume clusters in Medicare-dependent practices where same-day discharge and bleeding risk reduction drive laser platform adoption.
- Middle-Aged Males:The 50-64 transition cohort balancing career demands with emerging symptoms.
- Young Adults:Men under 40 with atypical presentations requiring differential diagnosis for alternative pathologies.
By absolute volume, Elderly Males leads. By treatment intensity growth, Adult Males is climbing fastest as earlier intervention norms take hold.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites Europe's distribution dominance for BPH surgical platforms, while direct procurement relationships with ambulatory surgery centers reshape continental market access patterns.
United States
Medicare Part D coverage expansion drives chronic medication adherence among elderly males with persistent lower urinary tract symptoms. FDA 510(k) premarket notification pathways compress regulatory timelines for novel laser ablation systems entering the market. High-throughput urology practices in metropolitan Texas and Florida markets are consolidating purchasing authority through commercial group integration.
Germany
Fragmented outpatient urology infrastructure creates first-mover opportunities for device manufacturers establishing direct procurement relationships with ambulatory networks. MDR clinical evidence requirements extend certification cycles for novel ablation technologies by 12-18 months. The Rhine-Ruhr metropolitan corridor concentrates purchasing decisions among integrated delivery networks with centralized value-analysis committees.
Japan
PMDA regulatory frameworks prioritize long-term safety data for energy-based prostate therapies entering the reimbursement system. METI industrial policy supports domestic manufacturing of precision surgical instruments for regional export. The Kansai region around Osaka anchors production capacity for reusable fiber optic delivery systems.
United Kingdom
NICE technology appraisal processes determine NHS funding eligibility for minimally invasive alternatives to transurethral resection. MHRA post-Brexit regulatory autonomy accelerates divergence from EU MDR harmonization timelines. The Greater Manchester health system integration creates regional purchasing monopolies for capital equipment procurement.
France
ANSM market surveillance obligations reshape post-launch clinical evidence collection for photoselective vaporization platforms. HAS reimbursement decisions concentrate adoption among high-volume academic medical centers with training mandates. The Île-de-France region dominates procedural volume through tertiary referral networks managing complex case complications.
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance capabilities, with public companies leveraging established quality management infrastructure while private innovators compress development cycles through focused therapeutic niches. The vendor base organizes around three strategic archetypes: diversified medical device conglomerates with electrophysiology manufacturing scale, robotic surgical platform specialists occupying minimally invasive gaps, and pharmaceutical incumbents with chronic disease management portfolios. Competitive dynamics center on M&A activity consolidating ambulatory surgery center purchasing relationships and technology licensing agreements accelerating platform convergence.
Within the diversified device tier, Boston Scientific Corporation and Olympus Corporation exemplify scale-driven positioning through catheter-based and visualization platform expertise. Among robotic specialists, PROCEPT BioRobotics Corporation occupies the automated tissue recognition niche between medical management and conventional surgery. Eli Lilly & Company anchors the pharmacotherapy segment with established urology therapeutic portfolios. These three representations illustrate how competitive positioning stratifies across intervention intensity rather than geographic origin.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Boston Scientific Corporation |
| GlaxoSmithKline Plc. |
| Teleflex Incorporated |
| Olympus Corporation |
| Sanofi S.A. |
| Eli Lilly & Company |
| NeoTract Inc. |
| PROCEPT BioRobotics Corporation |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fiber optic inventory cycles at German distributors concentrate procurement leverage among high-throughput urology practices, amplifying volume-discount power for integrated delivery networks while squeezing margins for independent ambulatory surgery centers without hospital system affiliation.
Pricing Analysis
Volume-discount tiering structures separate premium laser platforms with ISO 13485 certification and extended service contracts from standard electrocautery systems and economy-grade disposable catheters. Price differentiation hinges on FDA 510(k) clearance tier and bundled training packages, with hospital value-analysis committees extracting steeper concessions than independent urology groups. Cost compression in the economy catheter segment is intensifying because GPO consolidation is centralizing purchasing authority. Independent ambulatory surgery centers exhibit highest price sensitivity; academic medical centers with training mandates show lowest.
Supply Chain Analysis
United States and Germany anchor precision laser source manufacturing, while Japan feeds from specialized fiber optic drawing capabilities for reusable delivery systems. Raw material dependencies center on rare-earth doped fibers, medical-grade stainless steel, and semiconductor pump diodes. Single-source vulnerability concentrates in holmium laser crystal suppliers. Distribution runs through hospital value-analysis committees and ambulatory surgery center direct procurement channels, bypassing traditional distributor markups in consolidated metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as robotic waterjet ablation platforms displace incremental laser vaporization improvements, forcing incumbents to protect installed base economics against clinical outcome differentiation.
For Market Incumbents: Consolidate ambulatory surgery center purchasing relationships through capital equipment leasing programs that lock in consumable commitments. Deepen backward integration into fiber optic manufacturing to defend margin position against component cost volatility. Prioritize ISO 13485 certification maintenance as a barrier against emerging competitors facing MDR evidence requirements. For New Entrants and Emerging Players: Service-layer gaps in post-market surveillance support for MDR compliance create entry vectors for regulatory consulting bundling. Target Germany's fragmented outpatient urology infrastructure with direct procurement partnerships bypassing hospital system gatekeepers. Pursue FDA breakthrough device designation to compress review timelines against established laser manufacturers. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management play because aging demographics sustain procedural volume growth regardless of technology substitution cycles. Acquisition targets should display robotic platform integration capabilities with automated tissue recognition. Monitor CMS outpatient reimbursement code expansions as the inflection signal for ambulatory surgery center capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses competitive windows against established Greenlight laser platforms. |
| CE Marking Pathway under MDR | Prospective registry requirements extend certification cycles, favoring incumbents with quality systems. |
| Hospital System Partnership | Value-analysis committee access determines capital equipment placement in consolidated metropolitan markets. |
| Software Companion Development | Electronic health record integration extends robotic platform deployment timelines but locks in switching costs. |
| Reimbursement Strategy | CMS outpatient procedure codes directly influence site-of-service migration toward ambulatory settings. |
Study Parameters
A spread of perspectives from urology practice administrators, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CE marking notifications. Bottom-up procedure volume estimates triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include treatment modality intensity, site-of-service configuration, patient age cohort, and regional regulatory cluster complexity. CAGRs derived from procedure volume trajectories and ASP erosion patterns across laser, robotic, and pharmaceutical categories. Forecast inputs incorporated ambulatory surgery center capacity expansion pipelines and MDR certification timeline delays.
Underlying assumptions cover sustained Medicare outpatient reimbursement parity, with deviation risk concentrated in FDA regulatory pathway changes or photoselective vaporization safety signals. Forecasts reflect these assumptions without guaranteed outcomes. Recalibration cycles align with material shifts in CMS coding decisions or MDR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
India Urology Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Urinary Tract Infection Testing Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Nordic Urinary Catheters Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Urinary Retention Therapeutics Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Hematuria Treatment Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Botulinum Toxin in Urology Market
Urology
Europe Bladder Disorders Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Global Nephrology and Urology Devices Market