
 Voiding Cystourethrogram Market | 2026-2036
Voiding Cystourethrogram Market Size, Share, and Industry Trends Forecast 2026-2036
Voiding Cystourethrogram Market Analytics
Multi-source procurement for digital fluoroscopy components is pivoting toward integrated system partnerships. GE Healthcare leverages captive detector manufacturing to control cost positions across hospital networks. Siemens Healthineers anchors European installed bases with service-locked upgrade pathways. Philips Healthcare competes through hybrid catheterization lab imaging platforms that extend into urology suites.
A voiding cystourethrogram is a fluoroscopic imaging study using iodinated contrast instilled via catheter to visualize the bladder and urethra during voiding, capturing dynamic pressure-flow relationships at 15-30 frames per second. The procedure primarily detects vesicoureteral reflux, urethral strictures, and bladder outlet obstruction in pediatric and adult populations. Imaging systems command the dominant margin pool as flat-panel detector replacements accelerate, while disposable supplies including urinary catheters and contrast delivery sets generate recurring revenue streams tied to procedure volume. Pediatric applications sustain higher per-study reimbursement complexity, whereas outpatient migration pressures capital equipment utilization rates.
FDA radiation safety requirements under the Mammography Quality Standards Act framework and Joint Commission diagnostic imaging accreditation shape equipment upgrade cycles and site certification. EPA fluoroscopy performance standards and state-level radiation control programs further constrain analog system retention. Stakeholders must weigh detector replacement economics against full-system migration as reimbursement compression intersects with dose-reduction mandates.
Market Dynamics
Digital flat-panel detector retrofits are compressing replacement cycles for analog fluoroscopy systems, forcing hospitals to weigh partial upgrades against full-platform migrations under tightening radiation safety mandates.
Growth Catalysts
- Pediatric urology volume:Tertiary hospital networks in the United States, Germany, and Japan are expanding dedicated pediatric imaging suites to address congenital urinary tract anomalies, driving procedure throughput and equipment utilization.
- FDA ALARA compliance:The FDA's As Low As Reasonably Achievable radiation framework mandates dose-tracking documentation, compelling imaging departments to retire high-dose analog systems and adopt pulsed fluoroscopy with automatic exposure control.
- Digital detector maturation:Solid-state cesium iodide and gadolinium oxysulfide scintillator technologies have reached cost parity with image intensifier chains, removing the capital barrier to dose-reduction upgrades.
Market Restraints
- Xenon supply concentration:High-purity xenon gas for detector ionization chambers concentrates in Russian and Ukrainian extraction facilities, exposing manufacturers to geopolitical input cost volatility and allocation constraints.
- Joint Commission accreditation friction:Diagnostic imaging accreditation requirements impose 18-24 month site certification timelines for new fluoroscopy installations, delaying revenue recognition for capital equipment vendors.
- Ultrasound substitution:Contrast-enhanced voiding urosonography is displacing low-complexity reflux assessments in European pediatric centers, compressing addressable procedure volume for fluoroscopic systems.
Strategic Opportunities
- Outpatient migration:Ambulatory surgery centers in Florida, Texas, and California are installing compact C-arm fluoroscopy units for same-day voiding studies, opening a channel previously dominated by inpatient radiology departments.
- Artificial intelligence integration:Machine learning algorithms for automated reflux grading and radiation dose optimization are converging with digital detector platforms, creating premium pricing tiers for intelligent workflow systems.
- Japanese geriatric urology:METI reimbursement adjustments for post-prostatectomy incontinence diagnostics are expanding adult voiding cystourethrogram indications beyond the traditional pediatric concentration.
Industry Challenges
- Pediatric radiologist scarcity:Fellowship-trained specialists capable of interpreting dynamic voiding studies are concentrated in academic medical centers, creating geographic access gaps and study backlogs.
- Legacy PACS integration:Digital detector upgrades must interface with decade-old picture archiving systems, requiring costly middleware development and testing cycles that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voiding Cystourethrogram Market |
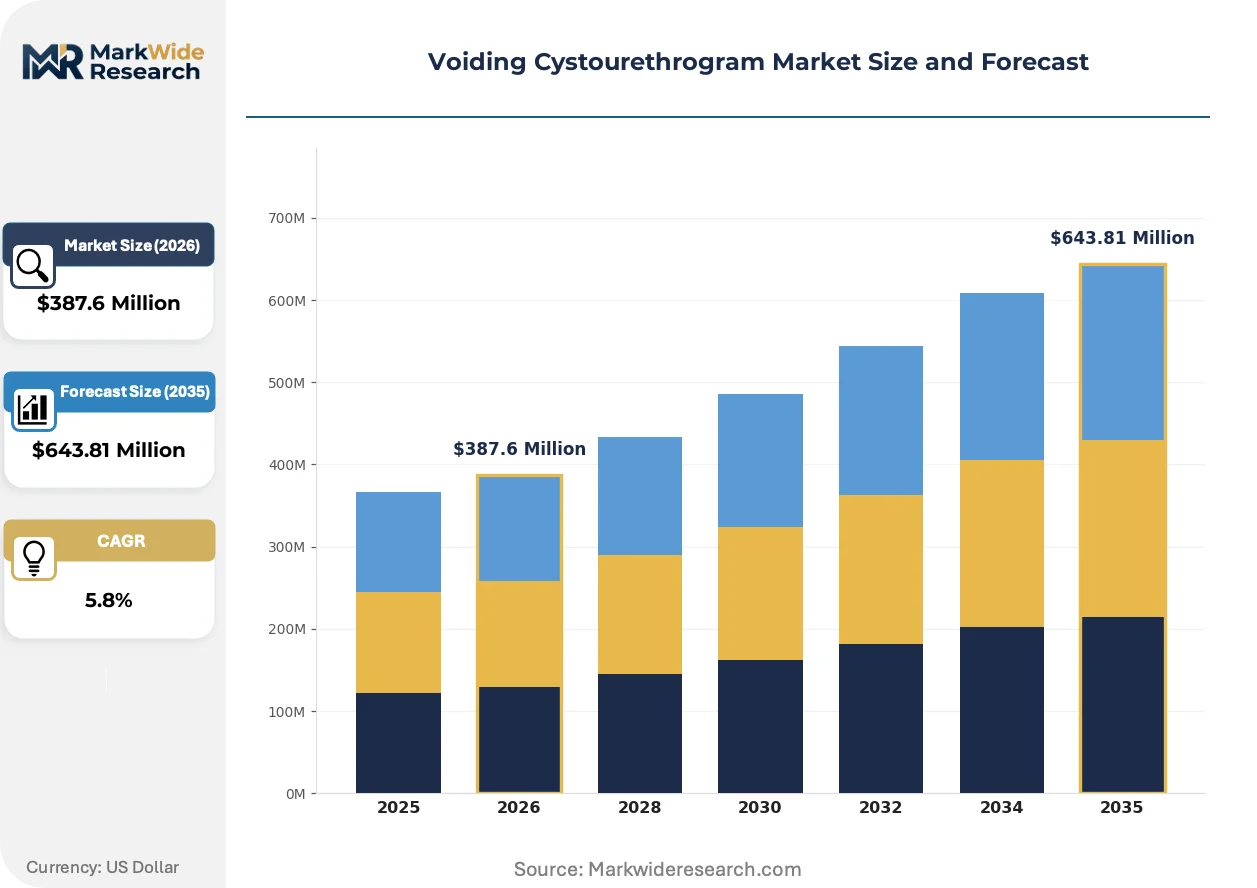
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contrast Agents, Imaging Systems, Disposable Supplies, Accessories Application: Pediatric Patients, Adult Patients, Outpatient, Inpatient End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Mobile Imaging, Standalone Systems, Integrated Systems, Point-of-Care |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Shimadzu Corporation, Merit Medical, Canon Medical Systems, Carestream Health, Hitachi Medical Systems, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voiding Cystourethrogram Market Evolving Landscape
Wireless detector technology is dissolving the fixed-room constraint of traditional fluoroscopy, enabling point-of-care urologic imaging in settings previously dependent on centralized radiology infrastructure.
Portable flat-panel detectors with battery-powered operation and 5 GHz wireless transmission are decentralizing voiding cystourethrogram procedures from dedicated fluoroscopy suites to emergency departments and outpatient clinics. Pediatric hospitals in the United States are deploying these systems for bedside reflux screening in neonatal intensive care units, reducing patient transport risks. The shift is compressing capital equipment utilization metrics while expanding addressable procedure volume into non-traditional clinical settings.
EPA fluoroscopy performance standards under 40 CFR Part 1020 are mandating maximum exposure rates and beam quality specifications that analog systems cannot satisfy. Equipment manufacturers are responding with automatic beam filtration and last-image-hold features that reduce operator dose. Imaging departments in California, Texas, and New York are prioritizing compliant system replacements to avoid state radiation control program enforcement actions.
Hospital procurement committees are unbundling service contracts from equipment purchases, negotiating separate multi-vendor maintenance agreements for detector, generator, and software subsystems. This behavior is fragmenting the traditional single-source vendor relationship and pressuring OEM service margins. The pattern is most pronounced in United States hospital networks with centralized capital equipment committees and independent biomedical engineering departments.
Voiding Cystourethrogram Market Segmentation
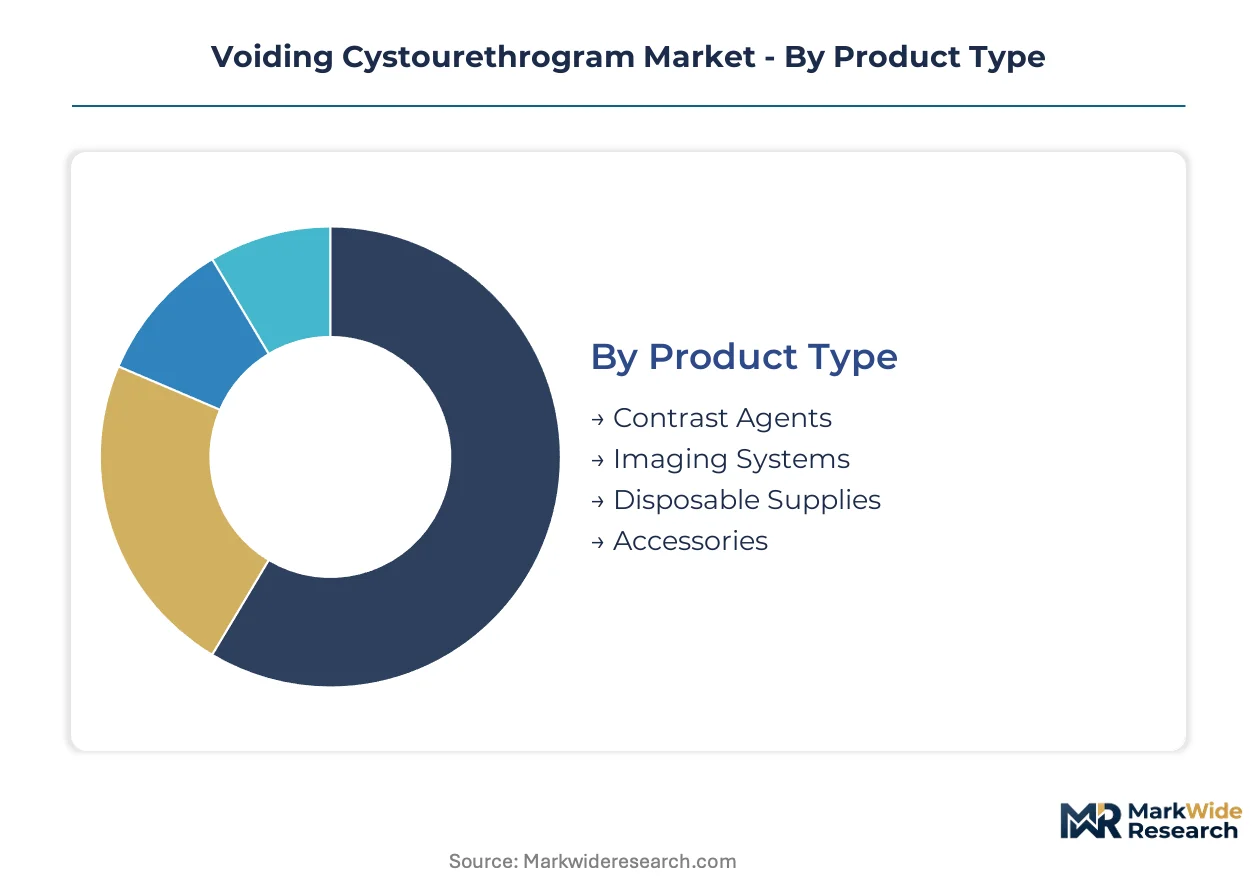
Procurement committees in tertiary hospitals and ambulatory networks evaluate voiding cystourethrogram equipment across four critical dimensions. Product specifications, patient population served, care setting, and deployment flexibility each trigger distinct vendor selection criteria and pricing negotiations.
Product Type:
Capital allocation decisions separate high-margin imaging platforms from recurring consumable streams.
- Contrast Agents:Iodinated formulations with low osmolality profiles dominate pediatric applications due to reduced adverse event profiles. Demand concentrates in United States hospital networks where FDA adverse event reporting requirements elevate specification thresholds for pediatric formulations.
- Imaging Systems:Digital flat-panel fluoroscopy units with automatic exposure control and pulsed acquisition modes command premium positioning. Procurement in Germany and Japan prioritizes detector replacement pathways over full-system migration as dose-reduction mandates compress replacement cycles.
- Disposable Supplies:Urinary catheters and contrast delivery sets generate procedure-tied recurring revenue with lower capital barriers.
- Accessories:Drapes, tubing sets, and positioning aids complete sterile field requirements.
Volume sits with Imaging Systems; growth tilts toward Disposable Supplies.
Application:
Reimbursement complexity and clinical acuity stratify addressable procedure economics.
- Pediatric Patients:Congenital urinary tract anomaly assessments require fellowship-trained interpretation and specialized equipment protocols. Tertiary children's hospitals in the United States sustain highest per-study reimbursement rates amid Joint Commission diagnostic imaging accreditation requirements.
- Adult Patients:Post-prostatectomy incontinence and neurogenic bladder evaluations expand indications beyond traditional pediatric concentration. METI reimbursement adjustments in Japan are accelerating adult procedure volume.
- Outpatient:Same-day discharge protocols compress capital equipment utilization metrics while expanding access points.
- Inpatient:Acute care settings retain higher complexity cases requiring anesthesia support.
Procedure volume concentrates in Pediatric Patients; expansion is steepest in Adult Patients.
End User:
Site certification timelines and service contract structures differentiate customer acquisition economics.
- Hospitals:Integrated radiology departments with captive pediatric urology services dominate installed base. United States academic medical centers anchor replacement demand through centralized capital equipment committees.
- Diagnostic Centers:Independent imaging facilities compete on throughput and turnaround time with leaner staffing models.
- Ambulatory Surgical Centers:Compact C-arm installations in Florida, Texas, and California enable same-day voiding studies outside traditional hospital infrastructure.
- Research Institutions:Protocol development and training missions sustain specialized equipment configurations.
Equipment concentration remains with Hospitals; Ambulatory Surgical Centers are gaining share fastest.
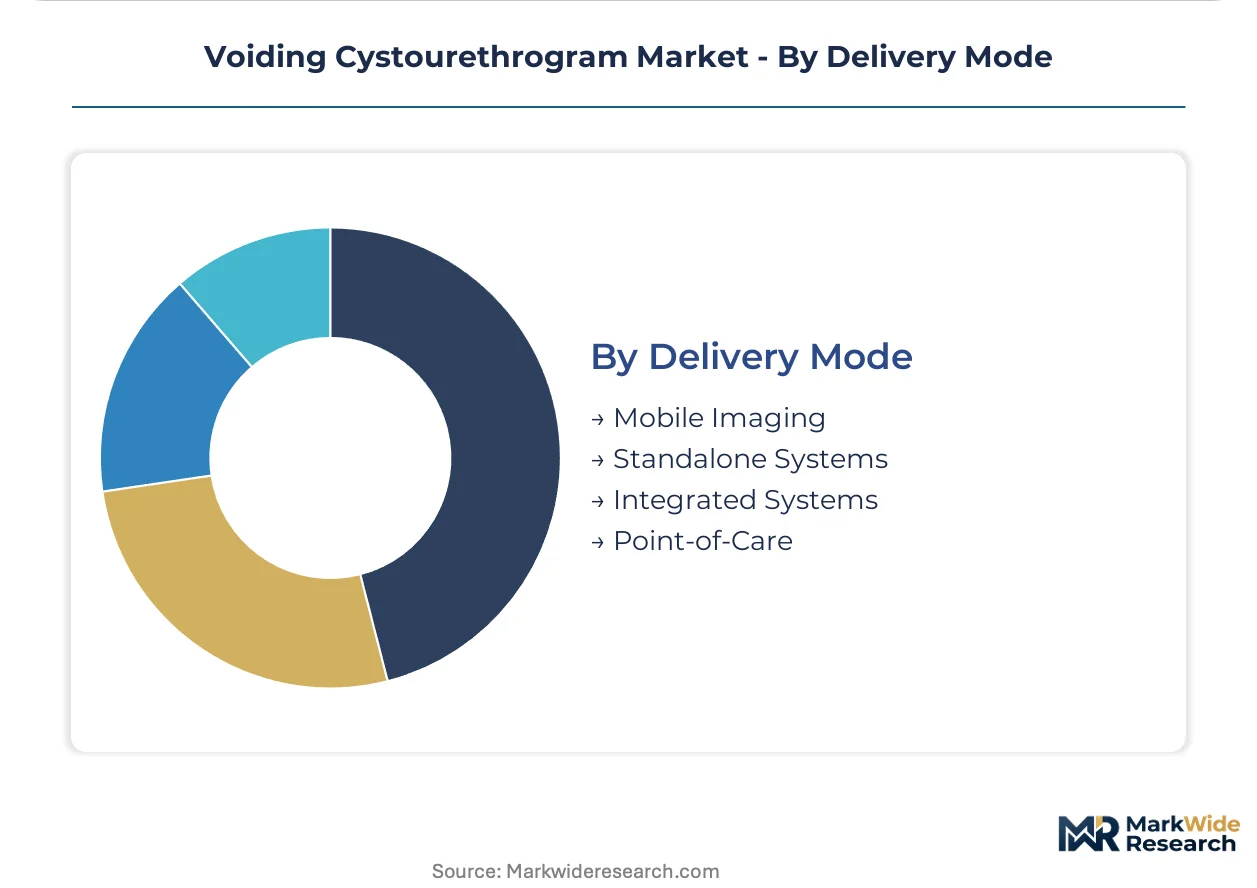
Delivery Mode:
Deployment architecture determines capital intensity and clinical workflow integration depth.
- Mobile Imaging:Wireless flat-panel detectors with battery-powered operation dissolve fixed-room constraints. Neonatal intensive care units in United States pediatric hospitals deploy these systems for bedside reflux screening.
- Standalone Systems:Dedicated fluoroscopy suites retain highest image quality specifications for complex diagnostic cases.
- Integrated Systems:Hybrid catheterization lab platforms extend into urology suites through shared detector infrastructure.
- Point-of-Care:Emergency department and outpatient clinic deployments compress patient transport risks.
Installed base centers on Standalone Systems; Point-of-Care configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for voiding cystourethrogram equipment concentrates in tertiary hospital networks across the United States, Germany, and Japan where structured reimbursement for pediatric urology diagnostics sustains capital investment cycles. Procurement committees in these markets prioritize dose-reduction compliance and digital detector upgrade pathways over full-system replacement.
United States
Pediatric urology departments at academic medical centers in Boston, Philadelphia, and Houston drive procedure volume for congenital anomaly assessments. FDA ALARA guidelines mandate dose-tracking documentation that accelerates analog system retirement. Texas Medical Center anchors one of the highest-density fluoroscopy installations globally, with centralized capital committees negotiating multi-vendor service contracts.
Germany
Tertiary children's hospitals in Munich, Heidelberg, and Berlin sustain replacement demand through detector-upgrade pathways rather than full-platform migrations. EPA-equivalent radiation safety standards under national implementation rules constrain analog retention timelines. The Baden-Württemberg medical device cluster hosts service-locked upgrade programs that preserve installed base relationships.
Japan
METI reimbursement adjustments for post-prostatectomy incontinence diagnostics are expanding adult voiding cystourethrogram indications beyond traditional pediatric concentration. Tokyo and Osaka metropolitan hospital networks prioritize hybrid catheterization lab platforms that extend into urology suites. Chubu region manufacturers supply solid-state scintillator components to domestic OEMs.
United Kingdom
NHS England specialized commissioning frameworks for pediatric urology concentrate complex diagnostic procedures at designated tertiary centers in London, Manchester, and Birmingham. MHRA guidance on fluoroscopy equipment lifecycle management compresses replacement windows for non-digital systems. The Oxford-Cambridge arc sustains research-protocol demand for specialized imaging configurations.
South Korea
MFDS medical device registration requirements for radiation-emitting equipment impose structured upgrade timelines on hospital procurement committees. Seoul National University Hospital and Samsung Medical Center anchor demand for premium digital fluoroscopy with automatic exposure control. Gyeonggi Province ambulatory networks are piloting compact C-arm installations for same-day voiding studies.
Voiding Cystourethrogram Market Competitive Landscape
Service-locked upgrade pathways dominate the current landscape as vendors compete to preserve installed base relationships against unbundled procurement trends. The market structures around three tiers: diversified imaging conglomerates with captive detector manufacturing, specialized urology-focused equipment suppliers, and regional service integrators. Strategic archetypes include full-platform vendors competing on integrated workflow systems, component specialists supplying detector subassemblies, and third-party service firms capturing maintenance revenue from fragmented multi-vendor installations. M&A activity concentrates on digital detector technology acquisitions, while geographic expansion targets ambulatory surgery center channels in high-growth states.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Philips Healthcare represent the dominant archetype competing through integrated system partnerships. GE Healthcare leverages in-house detector production to control cost positions across United States hospital networks. Siemens Healthineers anchors European installed bases with service-locked upgrade pathways that reduce customer switching. Philips Healthcare competes through hybrid catheterization lab platforms extending into urology suites, capturing shared infrastructure demand from cardiac and urologic imaging departments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Shimadzu Corporation |
| Merit Medical |
| Canon Medical Systems |
| Carestream Health |
| Hitachi Medical Systems |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Hospital procurement committee unbundling of service contracts from equipment purchases is forcing OEMs to restructure pricing architectures and absorb margin compression on standalone system sales. This demand-side shift toward multi-vendor maintenance agreements compresses bundled premium pricing and accelerates component-level cost transparency across detector, generator, and software subsystems.
Pricing Analysis
Volume concentrates in mid-tier digital fluoroscopy systems while margins pool in premium configurations with AI-integrated workflow automation and dose-tracking compliance. Price differentiation hinges on FDA ALARA certification tier and service contract bundling depth, with pediatric-focused tertiary hospitals showing lowest price sensitivity due to Joint Commission accreditation requirements. Pricing pressure stems from detector replacement economics competing against full-system migration decisions. Ambulatory surgery centers exhibit highest price sensitivity, driving demand for compact C-arm configurations with unbundled service terms.
Supply Chain Analysis
Direct-to-hospital channels handle large health system procurement while specialized distributors serve independent diagnostic centers and ambulatory networks. Manufacturing concentrates in Japan, Germany, and the United States for solid-state scintillator components and flat-panel detector assemblies. High-purity xenon gas for ionization chambers draws from Russian and Ukrainian extraction facilities, creating single-source vulnerability for detector manufacturers. Supply chain risk centers on geopolitical allocation constraints for noble gas inputs. Distribution runs through OEM-captive service organizations and third-party biomedical engineering contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive detector manufacturing and service-locked installed base relationships, with reimbursement compression and radiation safety mandates forcing subscale players toward exit or acquisition.
For Market Incumbents: Deploy service-locked upgrade pathways to preserve hospital network relationships against unbundled procurement trends. Capture pediatric urology department expansions through dose-reduction compliance bundling. Counter ultrasound substitution threats with AI-integrated workflow premium positioning. Deepen backward integration into scintillator component supply to offset xenon input volatility. For New Entrants and Emerging Players: Capture ambulatory surgery center channel whitespace in Florida, Texas, and California through compact C-arm configurations with aggressive unbundled pricing. Target wireless detector point-of-care deployments in neonatal intensive care units where transport risk reduction commands premium positioning. Pursue third-party service contracts on fragmented multi-vendor installations as entry wedge. For Investors and Strategic Acquirers: Re-rating potential sits with detector technology specialists given FDA ALARA compliance acceleration and digital retrofit cycle compression. Long-term viability favors platforms with hybrid catheterization lab extensibility beyond urology into cardiac imaging. Monitor METI reimbursement adjustment implementation in Japan as adult indication expansion signal.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Technology Acquisition | Captures solid-state scintillator IP amid digital retrofit cycle acceleration. |
| AI Workflow Integration | Enables premium pricing tiers through automated reflux grading and dose optimization. |
| Ambulatory Channel Partnership | Opens same-day voiding study access points outside hospital radiology infrastructure. |
| Service Contract Unbundling Response | Defends margin position through component-level maintenance agreement restructuring. |
| Hybrid Platform Extension | Leverages shared catheterization lab infrastructure across cardiac and urologic imaging departments. |
Research Methodology
Trade association filings, hospital procurement databases, and regulatory submission records formed the secondary backbone for market sizing and technology trend validation. Primary interviews with pediatric radiologists, hospital biomedical engineers, GPO contracts managers, and fluoroscopy equipment procurement committees were triangulated against secondary sources. Bottom-up procedure volume estimates and top-down equipment shipment analysis were cross-referenced to anchor market value calculations.
Bottom-up modeling of pediatric and adult procedure volumes across inpatient, outpatient, and ambulatory settings was reconciled with top-down OEM revenue segmentation. Product type, application, end user, and delivery mode dimensions structured the forecast framework across the analysis window. CAGRs were derived from equipment replacement cycle compression and dose-reduction mandate implementation timelines. Reimbursement policy trajectories and radiation safety standard adoption curves served as industry-specific forecast inputs.
The model holds under stable reimbursement structures and gradual ALARA compliance adoption; deviation in xenon supply disruption or rapid ultrasound substitution would shift equipment demand trajectories. Forecasts reflect documented assumptions regarding detector cost parity achievement and Joint Commission accreditation timeline stability. Periodic stress-testing of base assumptions is recommended given geopolitical input volatility and regulatory enforcement variability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Middle East and Africa Bladder Disorders Market
Urology
Europe Bladder Disorders Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Hematuria Treatment Market
Urology
India Urology Market
Urology
Disposable Ureteroscope Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Suprapubic Catheters Market
Urology
Self-Intermittent Catheters Market
Urology
Varicocele Treatment Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Urinary Bag Market
Urology
Global Bladder Cancer Market
Urology
Urinary Tract Infection (UTI) Treatment Market