
 Prostate Cancer Therapeutics Market | 2026-2036
Prostate Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Prostate Cancer Therapeutics Market Intelligence
The increasing prevalence of risk-sharing agreements between large pharmaceutical companies and specialized biotech firms is reconfiguring the competitive landscape. This model allows for shared R&D risk and accelerates drug development timelines. Johnson & Johnson leverages its extensive commercialization infrastructure for new oncology assets. Bayer AG specializes in developing targeted therapies and radiopharmaceuticals, while AstraZeneca competes through its strong pipeline in immunotherapy.
Prostate cancer therapeutics encompass a range of pharmacological agents designed to inhibit tumor growth and progression in the prostate gland. These treatments often function by targeting specific pathways, such as androgen receptor signaling, or by directly inducing cancer cell death through mechanisms like chemotherapy. Hormonal therapy remains a foundational treatment, but targeted therapy and immunotherapy are experiencing significant uptake. The approach for metastatic cancer differs greatly from localized disease, prioritizing disease management.
Market access is governed by stringent regulatory approvals from bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA. These agencies set high efficacy and safety standards for new drug approvals, influencing R&D timelines and costs. Stakeholders must navigate evolving reimbursement policies and the increasing emphasis on real-world evidence to secure market access and justify pricing.
Market Dynamics
The central structural force shaping the market is the pivot from broad-spectrum treatments to precision oncology. This evolution prioritizes therapies targeting specific genetic mutations and androgen receptor signaling pathways, fundamentally altering clinical practice and R&D investment strategies.
Growth Catalysts
- Favorable Regulatory Pathways:The FDA's Fast Track and EMA's PRIME programs expedite review for novel drugs addressing unmet needs in advanced disease, shortening development timelines.
- Advances in Diagnostic Imaging:Integration of PSMA-PET scans improves detection of metastatic disease, expanding the patient population eligible for targeted radiopharmaceuticals and other advanced therapies.
- Aging Demographics:Rising incidence in aging populations, particularly in Japan and Western Europe, expands the patient base requiring long-term management and sequential therapies.
Market Restraints
- High Treatment Costs:The substantial cost of novel biologics and radiopharmaceuticals creates reimbursement hurdles, limiting patient access in healthcare systems with strict budget controls.
- Development of Treatment Resistance:Cancer cells often develop resistance to androgen receptor-targeted agents, limiting the long-term efficacy of foundational therapies and requiring new mechanisms of action.
- Complex Clinical Trial Requirements:Proving a survival advantage requires large, lengthy clinical trials, posing a high financial barrier for smaller biopharmaceutical firms seeking market entry.
Strategic Opportunities
- Untapped Markets in Asia:Expanding access in large, underserved markets like China and India presents a growth opportunity as healthcare infrastructure and incomes improve.
- Combination Therapy Regimens:Exploring novel combinations of immunotherapies with PARP inhibitors and radioligands can overcome resistance, creating new intellectual property and treatment standards.
- Orphan Drug Designations:Securing orphan drug status from the FDA or EMA for therapies targeting rare subtypes provides market exclusivity and other development incentives.
Industry Challenges
- Radiopharmaceutical Expertise Scarcity:A shortage of nuclear medicine physicians and radiochemists needed to administer advanced radioligand therapies creates a significant bottleneck for treatment scalability and widespread adoption.
- Navigating Patent Cliffs:The impending patent expirations for several blockbuster hormonal therapies introduce intense pressure from generic and biosimilar competition, threatening revenue streams for established products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostate Cancer Therapeutics Market |
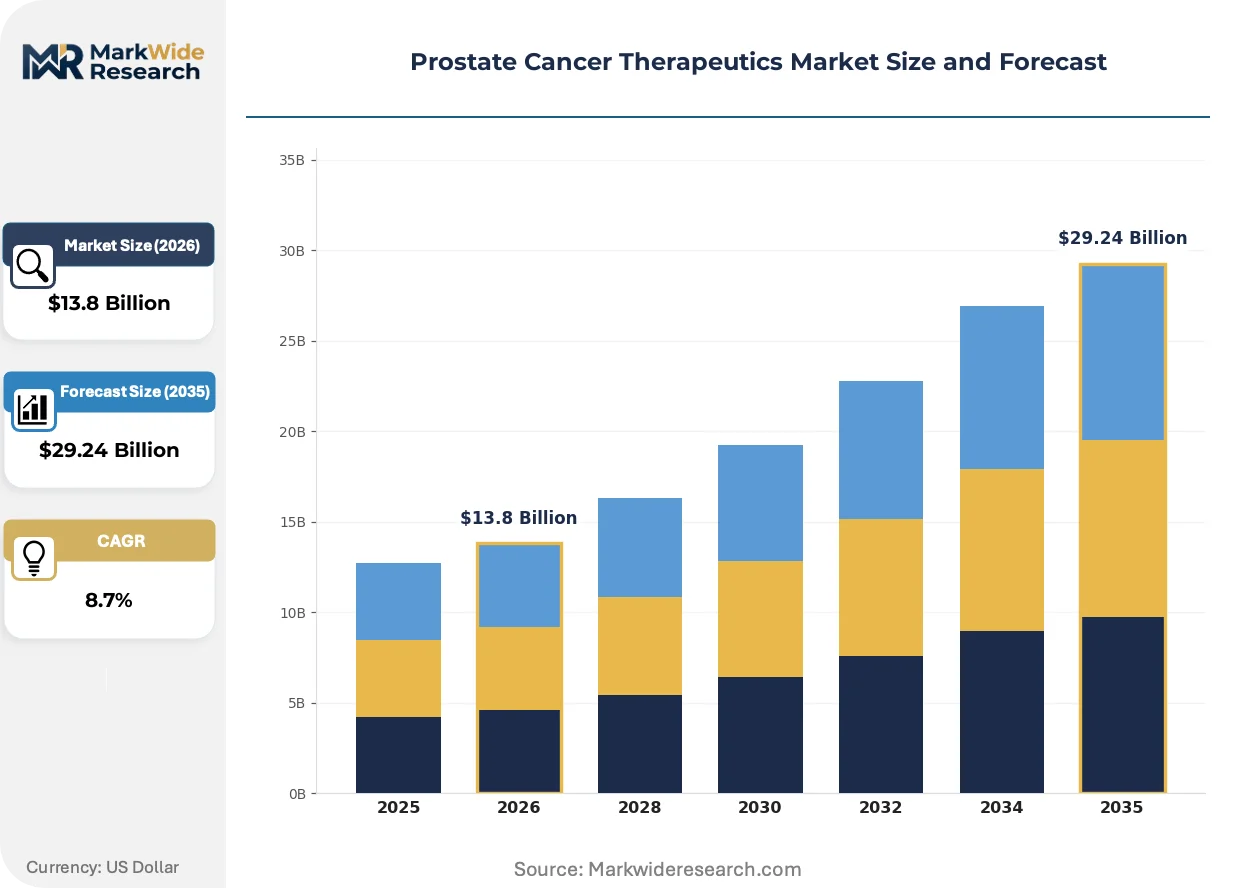
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $29.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Chemotherapy, Immunotherapy, Targeted Therapy, Radiopharmaceuticals Application: Localized Cancer, Advanced Cancer, Metastatic Cancer, Castration-Resistant Cancer, Hormone-Sensitive Cancer End User: Oncology Clinics, Cancer Research Institutes, Diagnostic Laboratories, Specialized Treatment Centers Delivery Mode: Oral, Intravenous, Intramuscular, Subcutaneous, Implantable |
| Companies Covered | Johnson & Johnson, Pfizer, Bayer AG, Astellas Pharma, AstraZeneca, Novartis AG, Merck & Co., Sanofi, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostate Cancer Therapeutics Market Strategic Shifts & Innovations
The convergence of genomic sequencing with therapeutic development is actively redefining treatment protocols for prostate cancer. This shift enables a more personalized approach, moving beyond organ-based classification to treatment based on specific molecular biomarkers.
Radioligand therapy (RLT) delivers targeted radiation to cancer cells expressing markers like PSMA. Oncologists are adopting RLT for patients with advanced metastatic disease who have failed other treatments. The treatment paradigm for late-stage prostate cancer is migrating from systemic chemotherapy with significant side effects to highly precise, molecularly-targeted radiation.
Regulatory bodies, including the US FDA and EMA, increasingly emphasize using real-world evidence (RWE) in decision-making. This policy compels manufacturers to systematically collect data from sources like electronic health records for post-approval studies. RWE is becoming critical for justifying reimbursement, supporting label expansions, and monitoring long-term safety profiles.
A behavioral shift towards shared decision-making is altering the physician-patient dynamic. This trend moves away from a purely physician-directed plan towards a collaborative approach where patient quality-of-life is weighed alongside clinical efficacy. This is most prominent in the United States and parts of Europe, influenced by empowered patient advocacy groups.
Prostate Cancer Therapeutics Market Segmentation
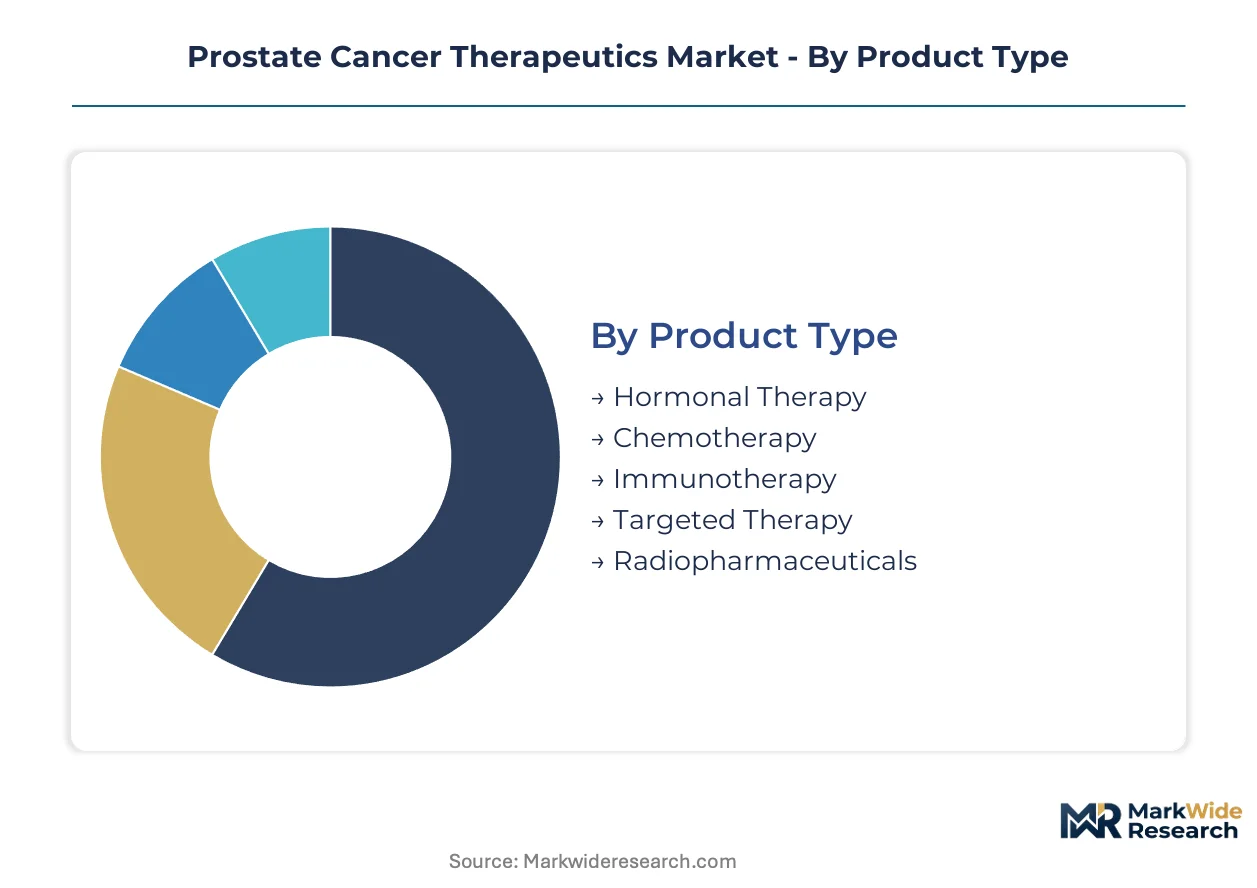
The prostate cancer therapeutics market is meticulously segmented to reflect the diverse treatment modalities, patient populations, and healthcare delivery channels. Understanding these distinct segments provides a granular view of market dynamics and highlights areas of concentrated demand and innovation. This detailed breakdown aids stakeholders in identifying specific therapeutic gaps and strategic investment opportunities within the complex oncology landscape.
Product Type:
Product type differentiation delineates the various pharmacological approaches employed to manage prostate cancer.
- Hormonal Therapy:These agents modulate androgen receptor signaling, either by blocking androgen production or inhibiting receptor binding, forming the backbone of prostate cancer treatment. Demand for these foundational therapies remains high in both early and advanced disease stages across the United States and Western Europe, driven by established efficacy.
- Radiopharmaceuticals:These therapies deliver targeted radiation directly to cancer cells expressing specific markers, such as PSMA, offering precise tumor destruction with reduced systemic toxicity. Adoption is accelerating in advanced metastatic settings, particularly in Germany and Japan, where advanced diagnostic imaging facilitates patient selection.
- Chemotherapy:Cytotoxic drugs interfere with cancer cell division, primarily used in advanced, castration-resistant prostate cancer when hormonal therapies fail.
- Immunotherapy:These treatments harness the body's immune system to recognize and destroy cancer cells, showing promise in specific patient subsets.
- Targeted Therapy:These agents block specific molecular pathways involved in cancer growth, offering a more precise approach to treatment.
Hormonal Therapy holds installed capacity. Radiopharmaceuticals are rotating up the share rankings.
Application:
Clinical application segments outline the specific stages and forms of prostate cancer addressed by different therapeutic interventions.
- Metastatic Cancer:Characterized by cancer spread beyond the prostate, requiring systemic treatments to manage widespread disease and improve patient outcomes. Novel agents for metastatic disease, particularly radioligand therapies, are experiencing rapid uptake in the United States and France, driven by improved survival data.
- Castration-Resistant Cancer:This advanced form progresses despite androgen deprivation therapy, necessitating new treatment approaches to overcome hormonal resistance. Therapies for castration-resistant prostate cancer are gaining significant traction in Japan and the United Kingdom, where aging populations contribute to higher incidence.
- Localized Cancer:Confined within the prostate gland, often managed with surgery, radiation, or active surveillance.
- Advanced Cancer:Encompasses both locally advanced and metastatic disease, requiring more aggressive or systemic treatment strategies.
- Hormone-Sensitive Cancer:Responds to treatments that lower androgen levels, representing the initial phase of systemic therapy.
Targeted therapies for metastatic disease demonstrate the steepest expansion trajectory. Localized cancer treatments maintain a steady, foundational demand.
End User:
Customer type segmentation identifies the primary healthcare facilities and research organizations administering or studying prostate cancer treatments.
- Oncology Clinics:These specialized medical facilities provide comprehensive cancer care, including diagnosis, treatment, and follow-up for prostate cancer patients. Oncology clinics in urban centers across the United States and Germany manage the largest volume of patients, benefiting from established referral networks.
- Specialized Treatment Centers:Institutions focusing on specific cancer types or advanced therapies, often integrating research with clinical practice for complex cases. These centers, particularly in academic settings in Canada and Australia, are crucial for the adoption of novel radiopharmaceutical and targeted therapies.
- Cancer Research Institutes:Organizations dedicated to understanding cancer biology and developing new therapeutic interventions through clinical trials.
- Diagnostic Laboratories:Facilities performing tests to identify prostate cancer, stage the disease, and monitor treatment response.
Oncology clinics lead in patient volume across most regions. Specialized treatment centers are expanding their infrastructure to handle complex cases.
Delivery Mode:
Delivery mode options categorize the methods by which prostate cancer therapeutics are administered to patients.
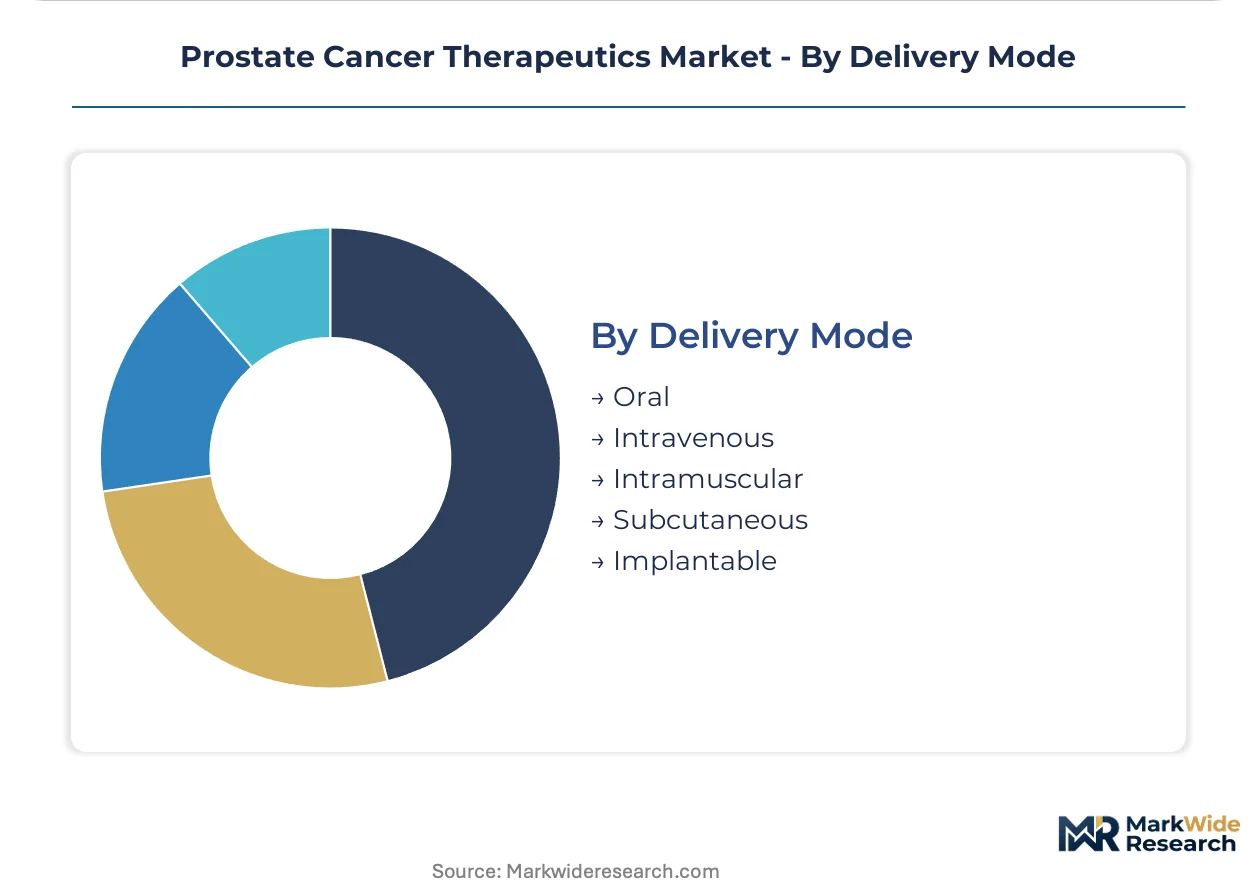
- Oral:Medications taken by mouth, offering convenience for long-term management and home administration, enhancing patient adherence. Oral hormonal therapies are widely prescribed in outpatient settings across Europe and the United States, favored for their ease of use.
- Intravenous:Therapies administered directly into a vein, ensuring rapid and complete bioavailability, commonly used for chemotherapy and some targeted agents. Intravenous administration remains essential for acute treatments and advanced disease protocols in hospital and clinic environments globally, particularly for biologics.
- Intramuscular:Medications injected into a muscle, providing a sustained release over time for certain hormonal agents.
- Subcutaneous:Injections administered just under the skin, offering a less invasive option for some biological therapies.
- Implantable:Devices surgically placed to deliver drugs continuously over an extended period, typically for hormonal suppression.
Oral formulations provide convenience for long-term management. Intravenous administration remains critical for acute and advanced disease protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The prostate cancer therapeutics market exhibits a complex global trade balance, with certain regions demonstrating significant net import of advanced therapies while others focus on domestic production and export. Demand concentration is particularly high in developed economies, driven by established healthcare systems and an aging demographic requiring specialized oncology care.
United States
Demand for novel radioligand therapies and immunotherapies drives market expansion in the United States. The US FDA's expedited review programs accelerate access for innovative prostate cancer treatments. Major biopharmaceutical clusters in Boston and San Francisco lead in R&D, attracting significant investment in oncology drug development.
Germany
Germany’s market for prostate cancer therapeutics is propelled by high adoption rates for advanced diagnostic imaging and targeted radiopharmaceuticals. The European Medicines Agency (EMA) influences drug approval and market access across the region. Oncology clinics in cities like Munich and Berlin are early adopters of new treatment protocols.
Japan
Aging demographics and a high incidence of castration-resistant prostate cancer are key demand drivers in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates drug approvals, emphasizing real-world evidence for treatment efficacy. Research institutions in Tokyo and Osaka contribute to the development of novel molecularly targeted agents.
France
Rapid uptake of novel agents for metastatic prostate cancer, particularly radioligand therapies, characterizes the French market. France adheres to EMA regulations for drug approval and reimbursement policies. Paris and Lyon host significant oncology research centers, fostering clinical trials for advanced therapeutic options.
China
China presents a significant growth opportunity for prostate cancer therapeutics, driven by improving healthcare infrastructure and rising incomes. The National Medical Products Administration (NMPA) streamlines approvals for innovative oncology drugs. Pharmaceutical hubs in Shanghai and Beijing are expanding local manufacturing and R&D capabilities.
Prostate Cancer Therapeutics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying key active pharmaceutical ingredients and manufacturing services. The market structure for prostate cancer therapeutics is largely consolidated among a few major pharmaceutical companies, complemented by specialized biotech firms. Strategic partnerships are a dominant competitive move, allowing larger entities to leverage the innovative pipelines of smaller biotechs while mitigating R&D risk. Portfolio diversification into targeted therapies and radiopharmaceuticals also shapes competitive positioning.
Johnson & Johnson, a US-based multinational corporation, exemplifies a platform integrator, leveraging its extensive commercialization infrastructure for new oncology assets. Bayer AG, a German multinational, occupies a strong position in developing targeted therapies and radiopharmaceuticals. AstraZeneca, a British-Swedish multinational pharmaceutical and biotechnology company, sits within the immunotherapy segment, anchoring its strategy on a robust pipeline in this area.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Bayer AG |
| Astellas Pharma |
| AstraZeneca |
| Novartis AG |
| Merck & Co. |
| Sanofi |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Radiopharmaceutical expertise scarcity determines both pricing tier spreads and the supply chain shape for advanced prostate cancer treatments. This constraint influences market access and the cost of specialized therapies.
Pricing Analysis
Oncology clinics anchor value-based pricing for prostate cancer therapeutics. Price differentiation stems from robust clinical efficacy data and stringent regulatory approval status from bodies like the US FDA. Pricing softness reflects increasing reimbursement hurdles in healthcare systems with strict budget controls. Specialized treatment centers for advanced disease demonstrate lower price sensitivity, while public health systems exhibit high sensitivity.
Supply Chain Analysis
Specialized CDMOs hold significant manufacturing capacity for prostate cancer therapeutics. Geographic supply concentrates in India, China, and the United States for active pharmaceutical ingredients. Single-source vulnerability for novel radiopharmaceutical precursors creates a structural risk. Distribution runs through hospital pharmacies and specialized oncology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prostate cancer therapeutics market faces significant constraints from a shortage of specialized radiopharmaceutical expertise. This capability gap necessitates targeted strategic interventions across all stakeholder groups.
For Market Incumbents:Pre-empt impending patent cliffs for blockbuster hormonal therapies by accelerating R&D into novel combination therapy regimens. Invest in specialized radiopharmaceutical production capabilities to mitigate supply bottlenecks and control costs. Diversify product portfolios to counter generic and biosimilar competition. Johnson & Johnson could leverage its commercialization infrastructure for new oncology assets.
For New Entrants and Emerging Players:Establish a beachhead in underserved markets like China by securing NMPA approvals for innovative oncology drugs. Target therapies for rare prostate cancer subtypes to leverage orphan drug designations and market exclusivity. Focus on developing novel mechanisms of action to overcome treatment resistance in castration-resistant cancer. Strategic partnerships with local pharmaceutical companies can accelerate market entry.
For Investors and Strategic Acquirers:Increasing regulatory emphasis on real-world evidence reshapes the acquisition landscape, favoring companies with robust data collection capabilities. Long-term viability hinges on investments in precision oncology and therapies addressing treatment resistance. Seek specialized biotech firms developing novel radioligand therapies or combination regimens. Successful Phase 3 trial readouts for advanced therapies serve as a critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Combination Therapies | Accelerates development of novel regimens to overcome treatment resistance. |
| Regulatory Approval Pathway Optimization | Expedites market access for innovative drugs addressing unmet needs. |
| Licensing Agreements with Biotech Firms | Accesses innovative pipelines while mitigating R&D risk for larger entities. |
| Radiopharmaceutical Manufacturing Scale-Up | Addresses scarcity of specialized production capacity for advanced treatments. |
| Pipeline Diversification into Immunotherapy | Expands treatment options beyond hormonal therapies for specific patient subsets. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary research. Primary data involved conversations with oncology key opinion leaders, hospital procurement managers, and pharmaceutical R&D executives. Secondary data sources included US FDA filings, EMA submissions, and clinical trial registries. This approach facilitated bottom-up and top-down triangulation for robust market sizing and forecasting.
Forecast inputs considered disease incidence rates, treatment uptake, and regulatory approvals across the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, and delivery mode. Compound Annual Growth Rates were derived from historical trends and projected future adoption rates. PSMA-PET scan adoption rates and patent expiry schedules served as critical industry-specific inputs.
Stress conditions across regulatory policy shifts, clinical trial outcomes, and reimbursement changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding future clinical trial success. Quarterly review of drug approval rates and patient access metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Skin Cancer Therapeutics Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market