
 Medically Prescribed Apps Market | 2026-2036
Medically Prescribed Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Medically Prescribed Apps Market Outlook
App distribution through hospital procurement channels is tilting toward integrated electronic health record ecosystems. Epic Systems Corporation leverages its dominant EHR footprint to embed prescribed apps directly into clinical workflows. Cerner Corporation competes by extending its platform architecture to third-party therapeutic developers. Philips Healthcare anchors its position through specialized cardiology and respiratory monitoring applications that integrate with existing device infrastructure.
Medically prescribed apps are software-based medical interventions requiring clinical validation, regulatory clearance, and physician authorization before patient use, typically incorporating algorithms for symptom tracking, dose optimization, or behavioral intervention. These tools serve primarily to extend care beyond clinical settings while generating structured data for treatment adjustment. Chronic disease management applications command the largest addressable base given sustained patient engagement requirements and recurring reimbursement eligibility. Mental health support platforms represent the fastest-expanding category as asynchronous therapy models gain payer acceptance. The wearable devices segment concentrates margin pools where continuous physiological monitoring enables outcome-based contracting with insurers.
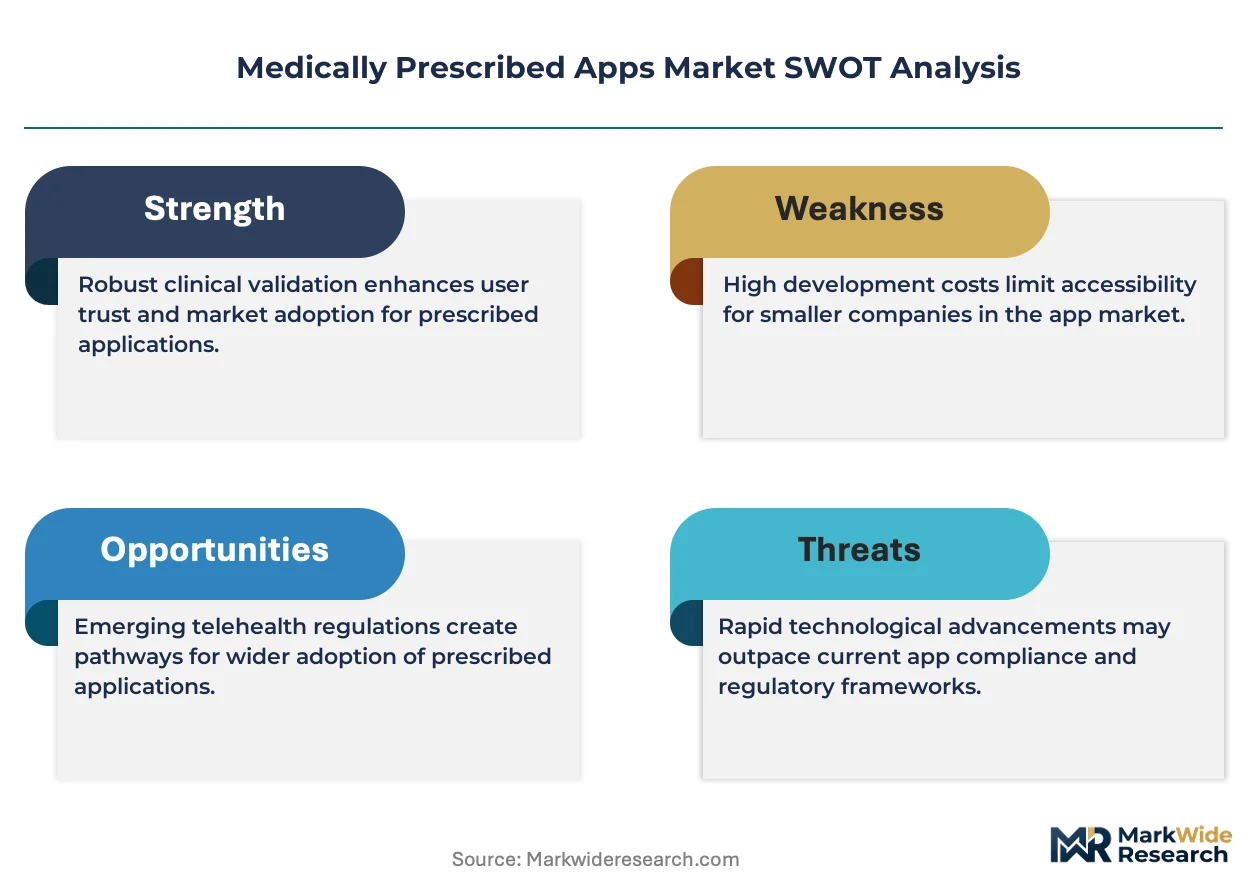
The FDA Digital Health Pre-Certification Program and HIPAA security rule collectively determine which developers achieve market access in the United States, with clinical evidence thresholds rising alongside data protection requirements. Germany's BfArM digital health applications directory and the EU Medical Device Regulation create parallel compliance pathways that shape product design priorities for European market entry. Stakeholders must monitor evolving evidence standards for software interventions as payers shift from pilot coverage to sustained reimbursement decisions based on real-world outcome data.
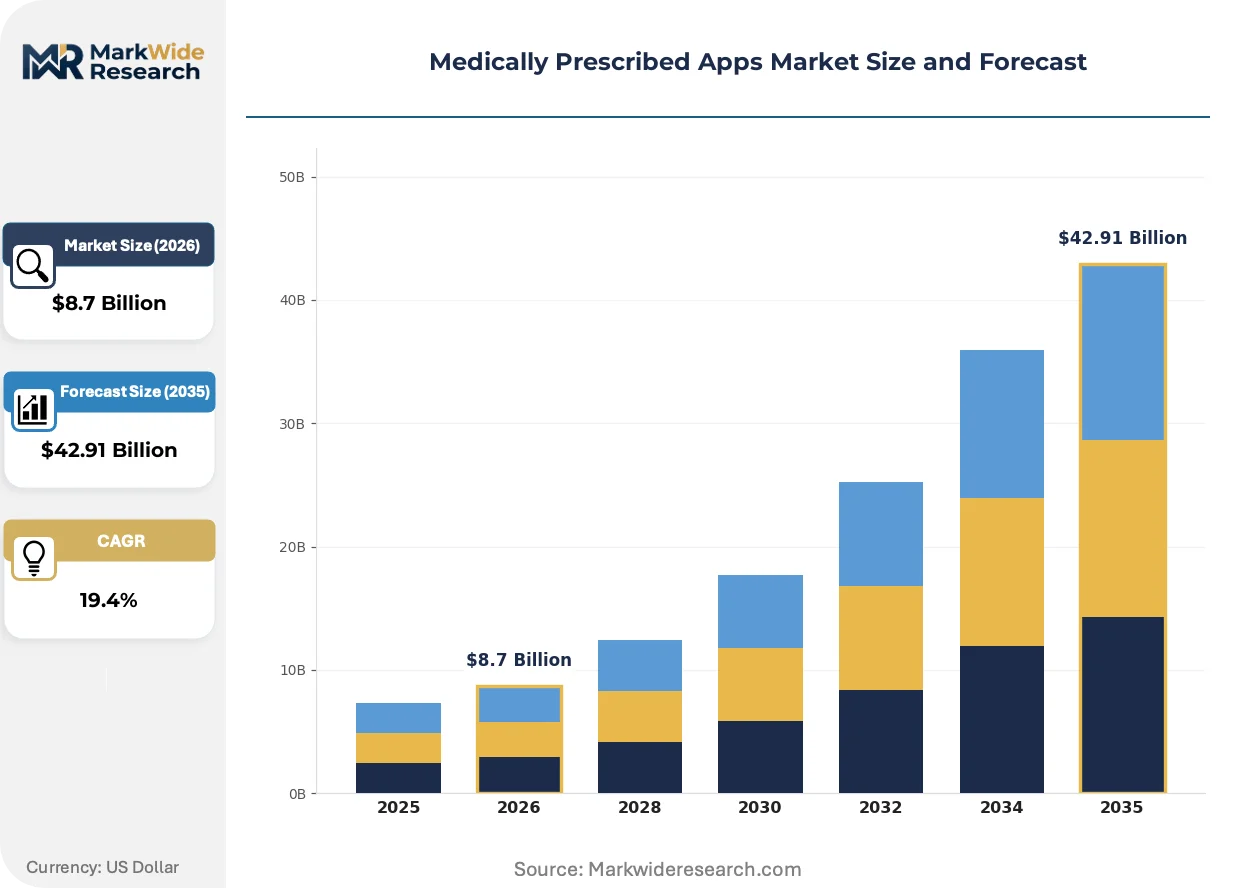
Market Dynamics
Reimbursement pathway fragmentation is the dominant structural force reshaping medically prescribed apps, as payers demand real-world evidence before granting sustained coverage for software-based interventions.
Growth Catalysts
- Statutory health insurance frameworks:Germany's BfArM digital health applications directory creates predictable reimbursement channels for validated therapeutic software.
- Chronic disease prevalence:Diabetes and cardiovascular patient populations require continuous remote monitoring that prescription-grade applications deliver cost-effectively.
- FDA Digital Health Pre-Certification:The streamlined regulatory pathway accelerates market entry for clinically validated software interventions in the United States.
Market Restraints
- Clinical evidence requirements:Randomized controlled trial costs for software interventions match pharmaceutical development expenses without equivalent patent protection.
- Data localization mandates:EU GDPR and member-state health data laws fragment cloud infrastructure requirements across European markets.
- Physician workflow friction:Electronic health record integration complexity slows adoption in health systems running legacy Cerner or Epic configurations.
Strategic Opportunities
- Pediatric mental health:Regulatory gaps in child-specific digital therapeutics create first-mover advantages for validated cognitive behavioral therapy platforms.
- Japan's PMDA software guidance:The regulator's 2024 clarification on SaMD classification reduces uncertainty for foreign developers entering the market.
- Remote patient monitoring convergence:Integration of continuous glucose monitors with dose-optimization algorithms enables outcome-based contracting with Medicare Advantage plans.
Industry Challenges
- Interoperability certification timelines:HL7 FHIR compliance validation delays product launches by 8-14 months in multi-hospital deployments.
- Behavioral science talent scarcity:Clinical psychologists with software product development experience command premium compensation that strains development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medically Prescribed Apps Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Medication Management, Chronic Disease Management, Mental Health Support, Fitness Tracking End User: Patients, Healthcare Providers, Caregivers, Pharmacies Platform: iOS, Android, Web, Wearable Devices Functionality: Tracking, Reminders, Virtual Consultations, Health Monitoring |
| Companies Covered | Apple Inc, Epic Systems Corporation, Cerner Corporation, Samsung Electronics, Medtronic plc, Philips Healthcare, Allscripts Healthcare Solutions, IBM Watson Health, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medically Prescribed Apps Market Strategic Shifts
Algorithmic personalization is compressing development cycles and reshaping competitive differentiation in prescription-grade therapeutics. Three convergent forces are accelerating this transformation.
Generative AI is collapsing the cost structure for adaptive cognitive behavioral therapy content. Mental health platforms deploy large language models to generate personalized intervention scripts in real time. Hospital systems in California and Massachusetts are piloting these tools for anxiety and depression management.
EU Medical Device Regulation Article 10 clinical evaluation requirements are forcing developers to maintain post-market surveillance infrastructure. The mandate elevates compliance costs for smaller software houses. German and French regulators are prioritizing cardiovascular and respiratory applications for enhanced scrutiny.
Subscription fatigue among health systems is driving unbundling of digital therapeutic formularies. Payers in the United Kingdom and Netherlands now reimburse individual modules rather than platform licenses. This fragmentation favors specialized developers with narrow, high-efficacy indications over broad-suite vendors.
Medically Prescribed Apps Market Segmentation
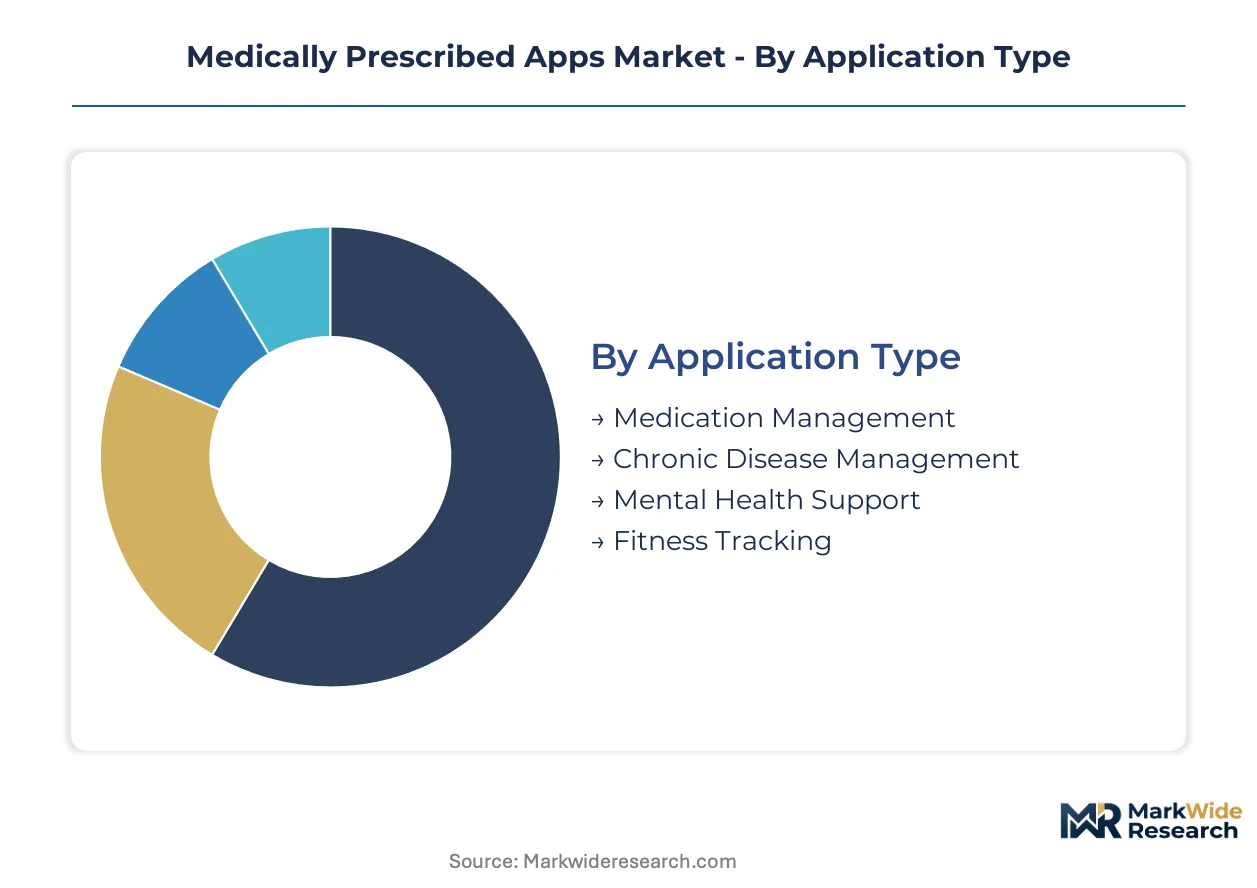
Segmentation in medically prescribed apps reveals how reimbursement pathways, clinical validation requirements, and integration complexity reshape competitive positioning across patient-facing and provider-facing use cases. Distinct segments carry divergent evidence burdens and pricing power.
Application Type:
The use-case spectrum spans acute intervention through longitudinal maintenance, with chronic conditions commanding sustained engagement models.
- Medication Management:Dose-optimization algorithms and adherence tracking for polypharmacy patients. Demand concentrates in Medicare Advantage plans seeking reduced hospitalization rates through timely refill alerts and interaction warnings.
- Chronic Disease Management:Symptom tracking and behavioral coaching for diabetes, cardiovascular, and respiratory conditions. German statutory health insurance reimbursement under BfArM directory rules accelerates deployment for validated diabetes platforms.
- Mental Health Support:Cognitive behavioral therapy modules and mood monitoring tools.
- Fitness Tracking:Activity and physiological data collection integrated with clinical workflows.
The dominant share belongs to Chronic Disease Management, while Mental Health Support is closing the gap fastest.
End User:
Cost tier differentiation separates consumer-paid wellness tools from enterprise-procured clinical interventions.
- Patients:Direct prescription recipients engaging with therapeutic software under physician oversight. Out-of-pocket payment persists in markets lacking statutory reimbursement frameworks.
- Healthcare Providers:Hospital systems and physician practices integrating apps into EHR workflows. Epic and Cerner procurement channels demand HL7 FHIR compliance that elevates vendor qualification costs.
- Caregivers:Family members and home health aides monitoring patient adherence remotely.
- Pharmacies:Retail and specialty pharmacy chains dispensing digital therapeutics alongside traditional medications.
Healthcare Providers capture the largest procurement volume, though Patients represent the steepest expansion trajectory as direct-to-consumer pathways mature.
Platform:
Distribution concentration reflects device ecosystem control and data sovereignty requirements.
- iOS:Apple's HealthKit integration and stringent privacy architecture attract hospital systems prioritizing HIPAA-aligned data handling. FDA-cleared apps launch disproportionately on this platform.
- Android:Google's broader device penetration supports population-scale deployment in public health initiatives. Fragmentation across manufacturer skins complicates clinical validation consistency.
- Web:Browser-based access bypassing app store gatekeepers.
- Wearable Devices:Continuous physiological monitoring enabling outcome-based contracting.
Wearable Devices command premium pricing through hardware-software bundling, while Web platforms gain share fastest among health systems seeking interoperability flexibility.
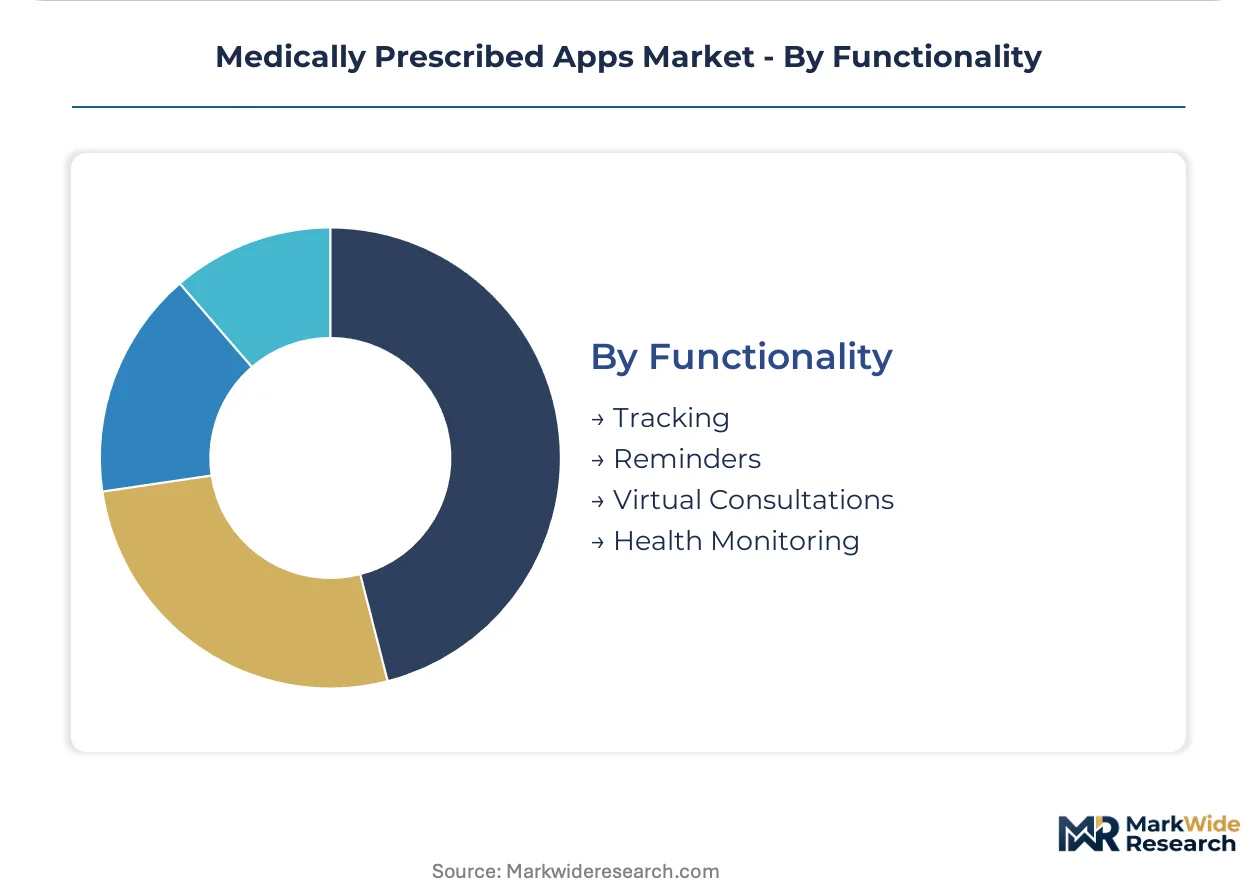
Functionality:
Maturity gradients separate established tracking capabilities from emerging virtual care modalities.
- Tracking:Structured data capture for symptoms, medications, and biometrics. German DiGA framework mandates this functionality as baseline for reimbursement eligibility.
- Reminders:Push notification systems for dosing and appointment adherence. Limited differentiation compresses margins toward commodity levels.
- Virtual Consultations:Asynchronous and synchronous provider-patient communication.
- Health Monitoring:Real-time physiological surveillance with automated escalation protocols.
Tracking holds established revenue concentration, with Virtual Consultations expanding most quickly as asynchronous therapy models secure payer acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors market expansion through its FDA Digital Health Pre-Certification Program, which streamlines software-based medical treatment approvals. Germany's statutory health insurance reimbursement frameworks create parallel demand centers in Europe.
United States
Medicare Advantage plans drive procurement volume for chronic disease management applications with outcome-based contracting models. The FDA's Pre-Certification Program accelerates market entry timelines for clinically validated software interventions. Hospital systems in California and Massachusetts pilot generative AI-powered mental health platforms for anxiety and depression management.
Germany
The BfArM digital health applications directory establishes predictable reimbursement channels for prescription-grade therapeutic software. Statutory health insurance coverage mandates under the Digital Healthcare Act reshape developer compliance priorities. Berlin and Munich health tech clusters concentrate validation infrastructure for diabetes and cardiovascular monitoring platforms seeking DiGA approval.
Japan
Aging demographics and chronic disease prevalence expand the addressable patient base for remote monitoring solutions. The PMDA's 2024 clarification on Software as a Medical Device classification reduces regulatory uncertainty for foreign developers. Tokyo and Osaka metropolitan hospitals integrate prescribed apps into existing electronic health record workflows.
United Kingdom
NHS England's digital therapeutic formularies drive procurement through specialized commissioning frameworks. The National Institute for Health and Care Excellence evaluates real-world evidence for sustained software reimbursement decisions. London health systems unbundle platform licenses into reimbursable individual modules for cardiovascular and respiratory applications.
France
The ANSM and CNIL jointly oversee clinical validation and data protection requirements for prescription-grade applications. Statutory reimbursement pathways under the French Social Security system expand for validated mental health and chronic disease platforms. Paris and Lyon hospital networks prioritize HL7 FHIR-compliant solutions for EHR integration.
Medically Prescribed Apps Market Competitive Environment
On the supply side, the industry is consolidating around electronic health record ecosystem control and specialized therapeutic validation capabilities. Epic Systems Corporation and Cerner Corporation anchor procurement channels through embedded workflow integration. Three archetypes dominate: EHR-native platforms, device-integrated specialists, and standalone therapeutic developers. Competitive moves concentrate on strategic partnerships with hospital systems and regulatory pre-certification investments.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation occupy positions as workflow gatekeepers for hospital procurement. Apple Inc exemplifies the consumer-device-to-clinical-bridge archetype through HealthKit integration and privacy-aligned data architecture. Philips Healthcare anchors the device-integrated specialist category, leveraging cardiology and respiratory monitoring infrastructure.
| Leading Market Players |
|---|
| Apple Inc |
| Epic Systems Corporation |
| Cerner Corporation |
| Samsung Electronics |
| Medtronic plc |
| Philips Healthcare |
| Allscripts Healthcare Solutions |
| IBM Watson Health |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Berlin and Munich health tech clusters concentrate validation infrastructure for diabetes and cardiovascular platforms seeking DiGA approval, concentrating supply-side leverage among developers with established BfArM directory listings and compressing margins for aspirants facing 18-24 month compliance timelines.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital system licenses from individual patient subscriptions, with three-tier pricing stratifying across premium EHR-integrated suites, standard standalone modules, and economy direct-to-consumer offerings. Price differentiation hinges on HL7 FHIR certification grade and Epic Systems workflow embedding depth. Pricing pressure intensifies as NHS England and Dutch payers unbundle platform licenses into reimbursable individual modules. Medicare Advantage plans exhibit highest price sensitivity due to outcome-based contracting exposure, while German statutory insurers show lowest sensitivity given mandated DiGA coverage.
Supply Chain Analysis
Export-control regimes around AI training data and clinical algorithm IP limit technology flows between US and EU development centers, fragmenting cloud infrastructure deployment. Software engineering talent concentrates in the United States, Germany, and Israel. Raw material dependencies include cloud compute capacity, behavioral science expertise, and regulatory affairs specialists. Supply chain risk centers on single-source vulnerability for Epic and Cerner EHR integration certification. Distribution runs through hospital procurement committees and pharmacy dispensing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medically prescribed apps market represents high-growth disruption as FDA Digital Health Pre-Certification and Germany's DiGA framework simultaneously compress regulatory timelines and validate software-based reimbursement at scale.
For Market Incumbents: Build regulatory pre-certification moats by accelerating FDA Pre-Cert pathway completion and securing BfArM directory permanence before evidence requirements harden. Deepen vertical integration into continuous glucose monitor hardware to enable outcome-based Medicare Advantage contracting. Counter emerging standalone therapeutic developers by embedding proprietary algorithms directly into Epic and Cerner workflow modules. For New Entrants and Emerging Players: Pursue pediatric mental health applications where regulatory gaps in child-specific cognitive behavioral therapy platforms create first-mover advantages. Target Japan's PMDA-clarified Software as a Medical Device pathway where 2024 guidance reduced foreign developer uncertainty. Deploy direct-to-patient go-to-market models in markets lacking statutory reimbursement frameworks. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because EHR-native workflow control and specialized therapeutic validation capabilities are concentrating procurement leverage among three archetypes. Target acquisition candidates with established HL7 FHIR compliance and hospital system pilot contracts. Watch for inflection when CMS expands remote patient monitoring reimbursement codes beyond chronic disease management.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | FDA Pre-Cert pathway completion accelerates market entry timelines for clinically validated software interventions. |
| EHR Workflow Integration Partnership | Epic Systems and Cerner Corporation procurement channels demand HL7 FHIR compliance for clinical embedding. |
| Outcome-Based Contracting Model | Medicare Advantage plans structure reimbursement around hospitalization rate reductions from dose-optimization algorithms. |
| Generative AI Content Infrastructure | Large language models collapse adaptive cognitive behavioral therapy content generation costs for mental health platforms. |
| Post-Market Surveillance Buildout | EU MDR Article 10 mandates elevate compliance costs and favor developers with sustained clinical evidence infrastructure. |
Study Parameters
Cross-validation between primary interviews with digital health executives and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and payer access specialists combined with BfArM DiGA directory records, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up platform deployment estimates and top-down addressable patient population sizing complete the triangulation.
Calibration against historical BfArM approval velocities and FDA Pre-Cert pilot program timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include application type, end user archetype, platform ecosystem, and functionality maturity. CAGRs derive from regression analysis of reimbursement pathway expansion rates and EHR penetration curves. Forecast inputs incorporate statutory insurance coverage mandates and continuous glucose monitor integration adoption patterns.
Macroeconomic conditions sit as an overlay; deviation in health system IT capital expenditure cycles or statutory insurance fund solvency would shift the trajectory. Forecasts reflect documented assumptions around regulatory pathway stability and payer evidence standard evolution. Material shifts in FDA Pre-Cert program scope or EU MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
North America Patient Support Technology Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Digital Healthcare Solutions Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market