
 United States Nuclear Imaging Market | 2026-2036
United States Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Nuclear Imaging Market Analytics
Aftermarket service revenue is narrowing as original equipment manufacturers tighten control over parts distribution and field engineering networks. GE Healthcare leverages its installed base of PET-CT and SPECT systems to sustain recurring service contracts across hospital networks. Siemens Healthineers anchors its position through proprietary detector technology and direct-to-site technical support infrastructure. Cardinal Health competes by controlling radiopharmaceutical logistics and dose calibration services that tie customers to long-term supply agreements.
United States nuclear imaging encompasses diagnostic modalities that employ radiolabeled tracers to visualize physiological function at the molecular level, with systems typically achieving spatial resolution below 5 millimeters for PET and energy discrimination of 140 keV for technetium-99m SPECT. These technologies enable non-invasive assessment of myocardial perfusion, tumor metabolism, and cerebral blood flow to guide therapeutic decisions. Hybrid imaging systems combining PET with magnetic resonance or computed tomography dominate capital expenditure allocations due to their superior anatomical co-registration and premium reimbursement profiles. Positron emission tomography leads growth in oncology applications where fluorodeoxyglucose protocols have become standard for staging and treatment response monitoring. Detector technology represents a concentrated margin pool as cadmium-zinc-telluride semiconductor arrays displace conventional sodium iodide crystals in next-generation SPECT platforms.
The FDA and Nuclear Regulatory Commission jointly govern radiopharmaceutical approval, manufacturing quality, and clinical use protocols, with the FDA's current good manufacturing practice requirements raising barriers for compounders seeking to enter the positron emitter supply chain. State-level radioactive materials licenses administered under NRC agreements further fragment market access and create compliance overhead for multi-site operators. Stakeholders must monitor evolving CMS reimbursement determinations for theranostic pairings and decide whether to build in-house cyclotron capacity or rely on centralized commercial radiopharmacy networks.
Market Dynamics
The FDA's updated current good manufacturing practice requirements for radiopharmaceutical production are tightening supplier qualification standards and forcing compounders to either upgrade in-house cyclotron capacity or exit the positron emitter supply chain entirely.
Growth Catalysts
- Theranostic Pairing Expansion:CMS reimbursement determinations for matched diagnostic-therapeutic protocols are accelerating hospital investment in lutetium-177 and gallium-68 production capabilities.
- Hybrid System Demand:Cardiology departments in academic medical centers are driving capital expenditure toward PET-MR and PET-CT platforms with sub-5 millimeter resolution.
- Semiconductor Detector Migration:Cadmium-zinc-telluride arrays are replacing sodium iodide crystals in next-generation SPECT systems, improving energy discrimination at 140 keV for technetium-99m protocols.
Market Restraints
- Molybdenum-99 Supply Concentration:Reactor-dependent production of technetium-99m generators concentrates in a handful of aging facilities outside the United States, creating vulnerability to unplanned outages.
- NRC Agreement State Fragmentation:Radioactive materials licensing administered across individual state jurisdictions generates compliance overhead for multi-site operators seeking uniform protocols.
- Reimbursement Compression:CMS fee schedule adjustments for myocardial perfusion imaging are constraining revenue per procedure for hospital-based nuclear medicine departments.
Strategic Opportunities
- Centralized Radiopharmacy Networks:Commercial dose calibration and logistics services offer compounders a path to serve dispersed imaging centers without captive cyclotron investment.
- Fluorodeoxyglucose Protocol Standardization:Oncology staging applications present expansion potential as community hospitals seek PET-CT access without academic medical center referral requirements.
- Northeast Corridor Cluster Density:Massachusetts, New York, and Pennsylvania research institutions create concentrated demand for advanced molecular imaging and tracer development partnerships.
Industry Challenges
- Cyclotron Engineering Talent Scarcity:Field service networks for particle accelerator maintenance face recruitment gaps as experienced technicians approach retirement without sufficient pipeline replacement.
- Legacy SPECT Integration Friction:Hospital networks with installed sodium iodide detector bases encounter workflow disruption when introducing semiconductor-equipped platforms with different calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Nuclear Imaging Market |
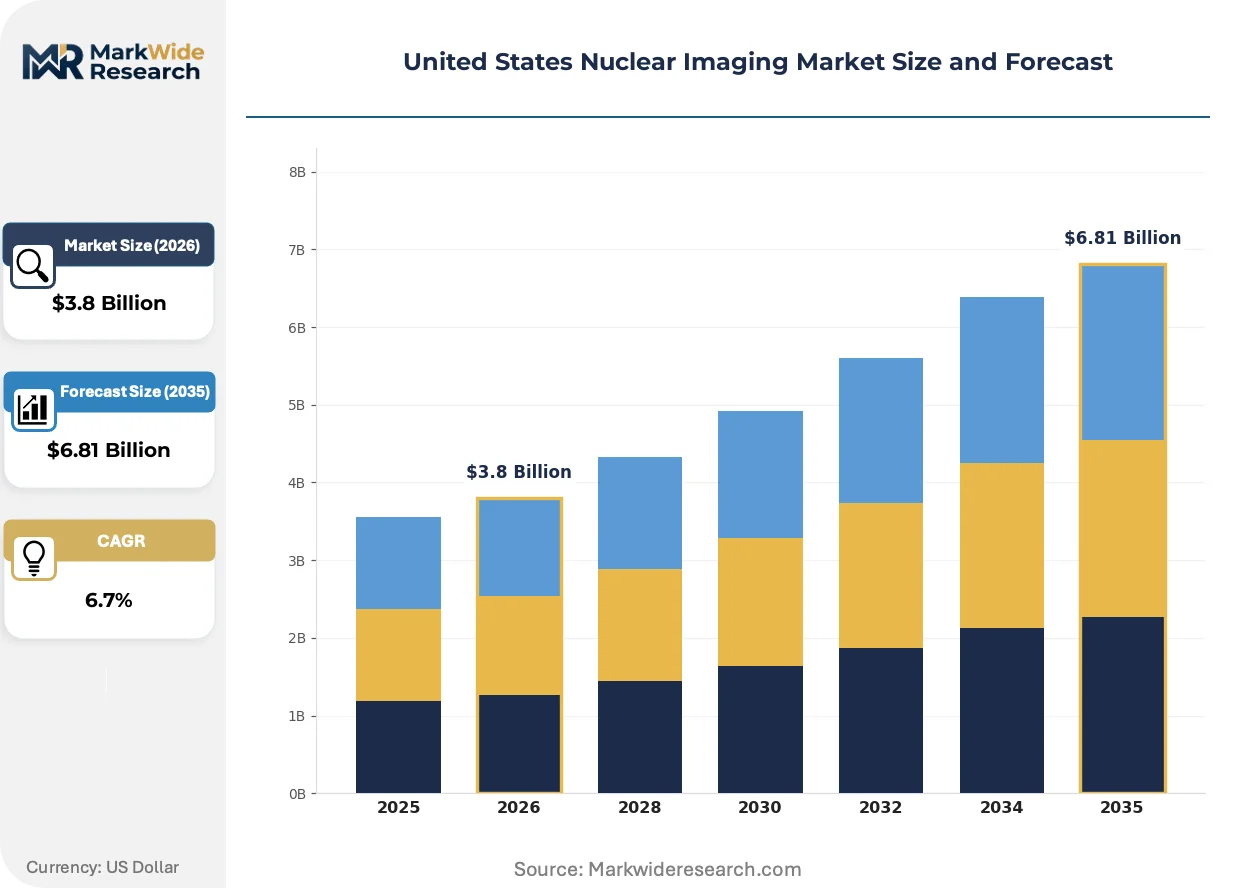
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging Systems, Radioisotope Generators End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Facilities Technology: Contrast Enhancement, Image Reconstruction, 3D Imaging, Detector Technology Application: Cardiology, Oncology, Neurology, Infectious Diseases |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems Corporation, Cardinal Health, Curium Pharma, Novartis (Advanced Accelerator Applications), Lantheus Holdings, Bracco Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Nuclear Imaging Market Evolving Landscape
Detector semiconductorization and regulatory tightening around radiopharmaceutical manufacturing quality are compressing margins for compounders while opening service revenue streams for logistics-specialized distributors.
Cadmium-zinc-telluride semiconductor detector arrays are replacing conventional sodium iodide crystals in premium SPECT platforms. Academic medical centers and large hospital networks with high myocardial perfusion volumes are adopting these systems fastest. The technology is rendering obsolete the energy resolution limitations that previously forced trade-offs between sensitivity and specificity in technetium-99m protocols.
The FDA's current good manufacturing practice enforcement for positron-emitting radiopharmaceuticals is raising barriers to compounder market entry. Facilities lacking validated quality systems face disqualification from supplying fluorodeoxyglucose and other PET tracers. Smaller regional radiopharmacies are responding by consolidating into centralized commercial networks with dedicated quality infrastructure.
Service contract unbundling is separating hardware maintenance from radiopharmaceutical supply agreements. Hospital procurement departments are negotiating direct detector calibration and field engineering relationships independent of tracer sourcing. This pattern concentrates in the Northeast corridor where multi-site health systems operate sufficient imaging volume to justify fragmented vendor relationships.
United States Nuclear Imaging Market Segmentation
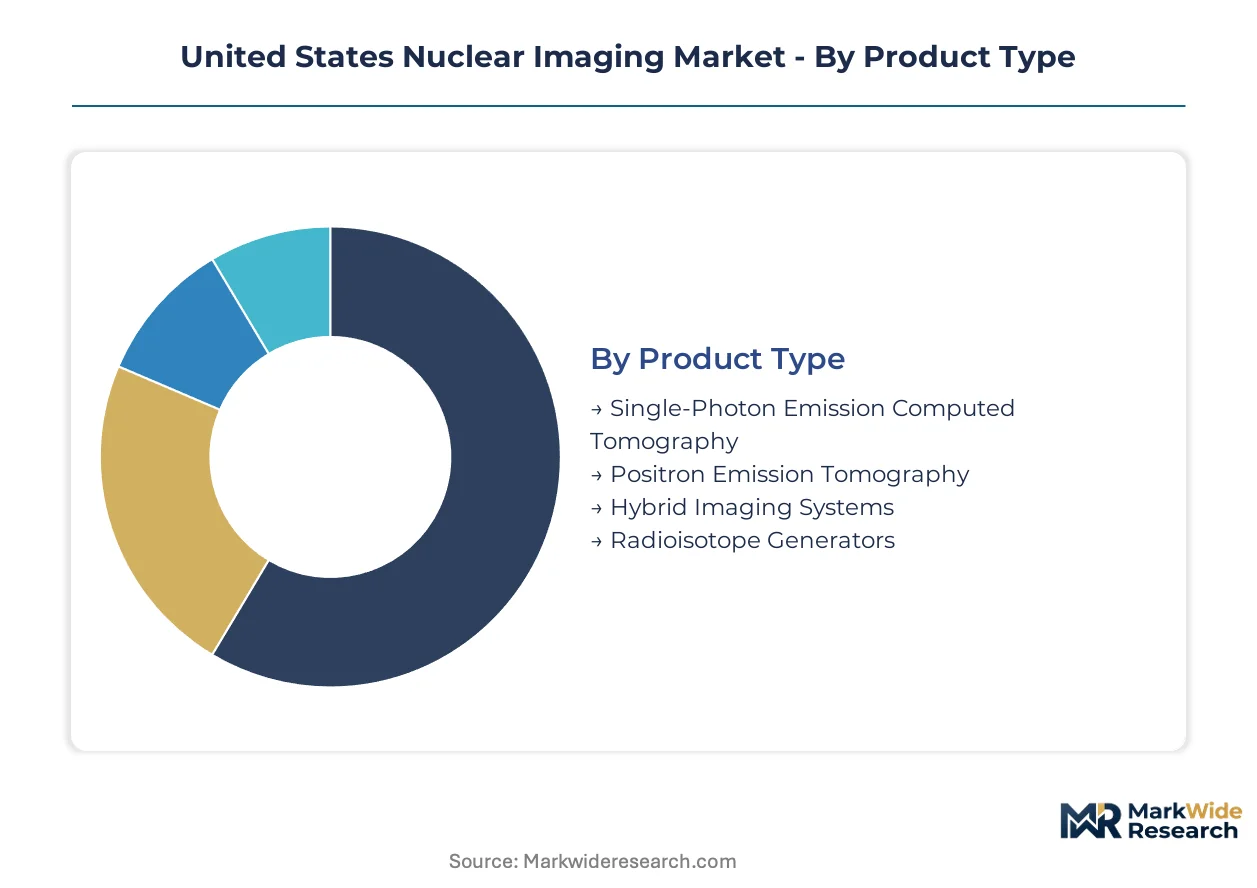
Segmentation in United States nuclear imaging reveals distinct service intensity profiles across product categories, with hybrid systems demanding multi-year maintenance commitments and radiopharmaceutical supply chains requiring continuous calibration support. Understanding these structural differences guides procurement strategy and vendor selection for hospital networks.
Product Type:
After-sales-service intensity varies dramatically across product categories, with hybrid platforms consuming 15-25% of initial capital cost annually in maintenance contracts while generator-based products rely on consumable replenishment models.
- Single-Photon Emission Computed Tomography:Conventional sodium iodide detector arrays and newer cadmium-zinc-telluride semiconductor configurations serve myocardial perfusion and bone scan protocols. Academic medical centers in the Northeast corridor favor semiconductor-equipped platforms for improved energy discrimination at 140 keV, though legacy sodium iodide bases in community hospitals create upgrade friction.
- Positron Emission Tomography:Ring-detector geometries with lutetium oxyorthosilicate crystals achieve sub-5 millimeter spatial resolution for fluorodeoxyglucose oncology staging. Demand concentrates in hospital networks seeking CMS-reimbursable cancer diagnostics without academic referral dependency, driving community hospital capital allocations.
- Hybrid Imaging Systems:PET-CT and PET-MR platforms combine functional and anatomical imaging.
- Radioisotope Generators:Molybdenum-99/technetium-99m systems dominate diagnostic tracer supply.
By volume, Single-Photon Emission Computed Tomography leads. By growth pace, Hybrid Imaging Systems is ahead.
End User:
Procurement authority and service contracting patterns diverge sharply across customer types, with integrated delivery networks centralizing purchasing for hospitals while independent imaging centers negotiate tracer supply and maintenance separately.
- Hospitals:Inpatient and emergency departments drive high-throughput myocardial perfusion imaging for chest pain protocols. Multi-site health systems in Massachusetts, New York, and Pennsylvania leverage volume concentration to unbundle hardware maintenance from radiopharmaceutical supply agreements.
- Diagnostic Imaging Centers:Freestanding facilities focus on outpatient oncology staging and cardiac stress testing. These operators depend on commercial radiopharmacy networks for dose calibration and logistics, avoiding captive cyclotron investment while facing reimbursement compression from CMS fee schedule adjustments.
- Research Institutions:Academic medical centers pioneer tracer development and theranostic protocols.
- Outpatient Facilities:Ambulatory settings handle routine bone scans and limited cardiac imaging.
Hospitals command the largest installed base. Diagnostic Imaging Centers are expanding most quickly as vertical integration pressures mount.
Technology:
Margin concentration follows proprietary control points, with detector materials and reconstruction algorithms representing the most defensible intellectual property positions.
- Contrast Enhancement:Radiolabeled tracer optimization for target tissue specificity.
- Image Reconstruction:Iterative algorithms reduce noise and acquisition time.
- 3D Imaging:Volumetric acquisition protocols improve diagnostic confidence.
- Detector Technology:Semiconductor arrays displace conventional crystals.
Detector Technology captures the premium pricing tier. Image Reconstruction is gaining share fastest as software-defined performance differentiation intensifies.
Application:
Reimbursement stability and procedure volume growth rates determine capital allocation priority across clinical domains.
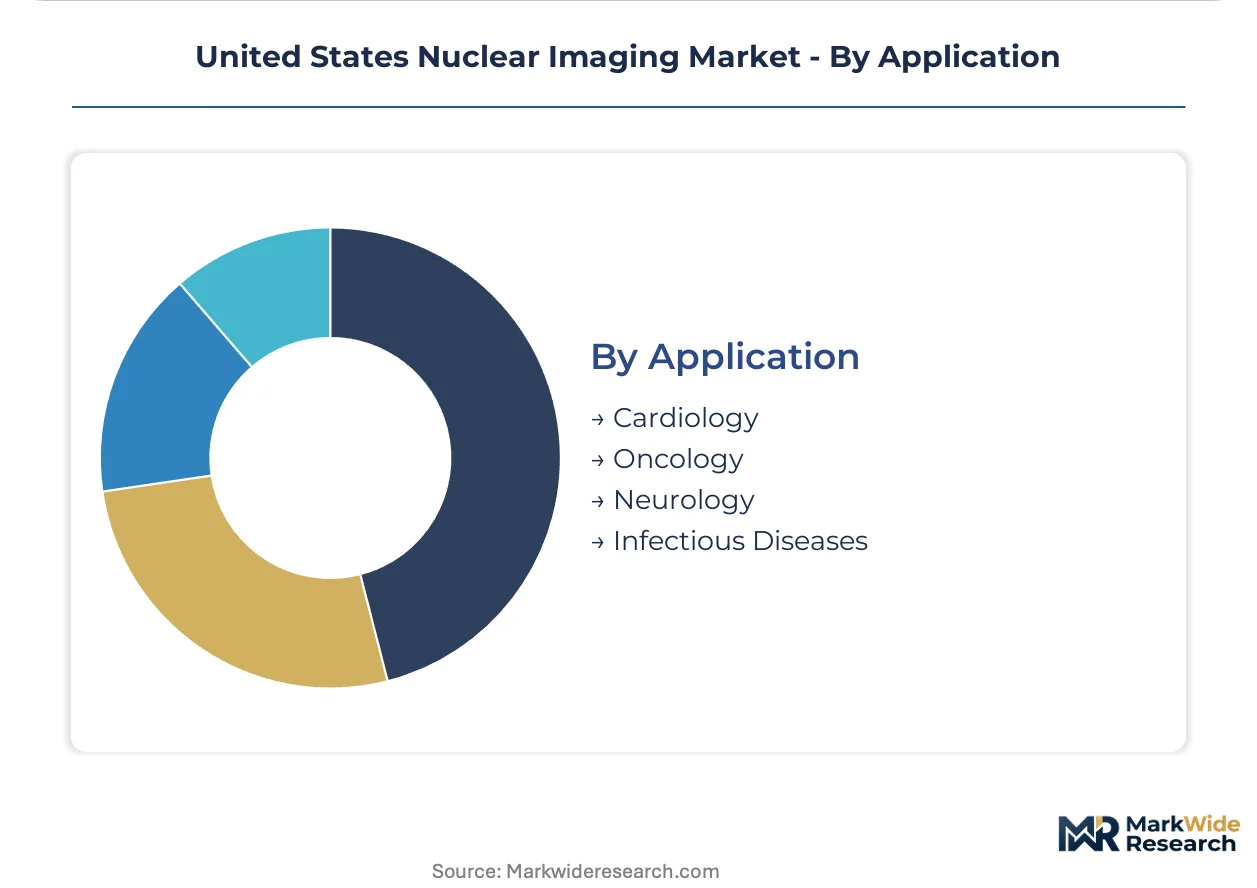
- Cardiology:Myocardial perfusion imaging remains the highest-volume nuclear medicine application. Academic medical center cardiology departments anchor demand for advanced hybrid systems with sub-5 millimeter resolution, though CMS fee schedule constraints pressure revenue per procedure.
- Oncology:Fluorodeoxyglucose PET-CT protocols have become standard for cancer staging and treatment response monitoring. Community hospitals outside major research clusters drive expansion as they seek PET-CT access without patient referral to academic centers.
- Neurology:Cerebral blood flow and amyloid plaque imaging serve dementia evaluation.
- Infectious Diseases:White blood cell labeling and specific tracer applications support infection localization.
Cardiology maintains the largest procedure volume. Oncology follows the steepest expansion trajectory as community hospital PET-CT penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United States diverge sharply between the research-intensive Northeast corridor and volume-driven Sun Belt markets. Academic medical centers concentrate advanced hybrid system procurement in coastal metropolitan clusters. Community hospital networks in interior states prioritize accessible PET-CT platforms for oncology staging without referral dependency.
Northeast Corridor
Massachusetts, New York, and Pennsylvania host the densest concentration of nuclear medicine research institutions. NRC Agreement State licensing variations across these jurisdictions generate compliance overhead for multi-site operators seeking uniform protocols. Boston and New York City anchor demand for theranostic pairing capabilities and gallium-68 production infrastructure.
Southeast
Florida and Georgia health systems drive outpatient imaging volume through freestanding cardiac stress testing centers. CMS fee schedule adjustments for myocardial perfusion imaging constrain revenue per procedure across hospital-based departments. Atlanta and Miami metropolitan areas concentrate commercial radiopharmacy networks serving dispersed imaging centers.
Texas
The state's independent imaging center sector expands PET-CT access for community oncology staging outside academic referral networks. FDA current good manufacturing practice enforcement raises barriers for regional compounders seeking positron emitter supply chain entry. Houston and Dallas medical centers leverage volume concentration to unbundle hardware maintenance from tracer sourcing agreements.
California
Academic medical centers in Los Angeles and San Francisco pioneer semiconductor detector migration in SPECT platforms. State-level radioactive materials licensing administered under NRC agreements fragments market access for multi-site operators. Northern California research clusters drive demand for advanced molecular imaging partnerships.
Midwest
Illinois and Ohio hospital networks maintain substantial installed bases of legacy sodium iodide detector systems. Reimbursement compression from CMS fee schedule adjustments pressures capital allocation for upgrade cycles. Chicago anchors regional radiopharmacy distribution serving community hospitals across the Great Lakes basin.
United States Nuclear Imaging Market Competitive Landscape
Capability concentration sits with detector technology specialists; scale advantage sits with diversified health technology conglomerates. The market structures around three tiers: integrated imaging system manufacturers controlling proprietary hardware platforms, radiopharmaceutical compounders managing cyclotron networks and dose logistics, and independent service providers unbundling maintenance from supply agreements. Strategic moves center on tightening parts distribution control to capture aftermarket revenue and consolidating regional radiopharmacies into centralized quality-validated networks.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions anchoring installed base service relationships across hospital networks. Cardinal Health exemplifies the radiopharmaceutical logistics archetype, with dose calibration and distribution infrastructure tying customers to long-term supply agreements. These three companies represent distinct competitive vectors: hardware platform control, proprietary detector technology, and commercial radiopharmacy network density.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Cardinal Health |
| Curium Pharma |
| Novartis (Advanced Accelerator Applications) |
| Lantheus Holdings |
| Bracco Imaging |
| Others |
Value Network & Pricing Analysis
Cyclotron undercapacity in the Northeast corridor concentrates radiopharmaceutical pricing power with compounders possessing validated FDA current good manufacturing practice infrastructure, while reimbursement compression from CMS fee schedule adjustments constrains downstream price realization for hospital-based imaging departments.
Pricing Analysis
Long-term offtake agreements dominate radiopharmaceutical supply contracts, with three-tier pricing structure across premium, standard, and economy levels differentiating validated quality systems from regional compounders. Price differentiation stems from FDA certification tier and after-sales service bundling. Cost compression in standard-tier SPECT maintenance contracts is intensifying because original equipment manufacturers are tightening parts distribution control. Community hospital networks exhibit highest price sensitivity, while academic medical centers prioritize resolution specifications over procurement cost.
Supply Chain Analysis
Upstream molybdenum-99 feedstock production concentrates in Canada, the Netherlands, and South Africa, with aging reactor infrastructure creating single-source vulnerability for technetium-99m generator supply. The United States nuclear imaging supply chain draws from semiconductor detector materials anchored in Japan and Germany, alongside lutetium oxyorthosilicate crystal production. Tariff exposure on imported isotope production equipment represents a structural risk. Distribution runs through centralized commercial radiopharmacy networks serving dispersed imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as CMS reimbursement determinations for theranostic pairings restore capital allocation confidence to hospital procurement committees.
For Market Incumbents: Build switching-cost moats through proprietary detector calibration protocols and direct-to-site technical support infrastructure. Tighten control over cadmium-zinc-telluride semiconductor parts distribution to capture aftermarket revenue streams threatened by independent service providers. Expand cyclotron capacity in Pennsylvania and Massachusetts to secure positron emitter supply chain positioning against FDA quality enforcement. For New Entrants and Emerging Players: Build out centralized radiopharmacy networks serving diagnostic imaging centers in the Southeast and Texas, where community hospital PET-CT penetration remains below academic medical center density. Target Florida and Georgia outpatient cardiac stress testing facilities with dose calibration and logistics services that avoid captive cyclotron investment. Pursue hospital procurement committee access through unbundled service contracts separating hardware maintenance from tracer sourcing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid imaging system manufacturing as semiconductor detector R&D and cyclotron quality infrastructure demands escalate. Long-term viability favors compounders with validated FDA current good manufacturing practice systems and multi-site health system supply agreements. Monitor CMS reimbursement determinations for lutetium-177 theranostic protocols as the signal for cyclotron capacity investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Quality System Validation | Validated current good manufacturing practice infrastructure secures positron emitter supply chain access against regulatory disqualification. |
| Semiconductor Detector Migration | Cadmium-zinc-telluride array adoption in SPECT platforms displaces sodium iodide crystals and commands premium pricing tiers. |
| Centralized Radiopharmacy Consolidation | Commercial dose calibration networks achieve scale economies that regional compounders cannot replicate under FDA enforcement. |
| Hybrid System Service Unbundling | Separating hardware maintenance from tracer sourcing concentrates procurement leverage in multi-site health systems. |
| Theranostic Pairing Investment | Lutetium-177 and gallium-68 production capabilities capture CMS-reimbursable diagnostic-therapeutic protocol demand. |
Research Methodology
A spread of perspectives from cyclotron operations managers, hospital nuclear medicine department heads, GPO contracts managers, and FDA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary field engagement with biomedical engineers and radiopharmacy compounders was cross-referenced against CMS Medicare reimbursement databases, FDA guidance documents, NRC licensing records, and hospital procurement system data. Bottom-up volume modeling across installed base segments was reconciled with top-down capital expenditure tracking from health system financial disclosures.
Demand-supply balance dynamics across cyclotron capacity, semiconductor detector fabrication, and isotope generator production anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end user category, detector technology tier, and clinical application area. CAGRs were derived from procedure volume trajectories and capital replacement cycle analysis, with specific inputs from myocardial perfusion imaging reimbursement trends and PET-CT penetration rates in community hospital settings.
Stress conditions across molybdenum-99 reactor outage scenarios, FDA quality enforcement intensity, and CMS fee schedule revision magnitude were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against state-level radioactive materials licensing data and health system capital budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Europe Nuclear Imaging Devices Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Teleradiology Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Precision Cancer Imaging Market