
 Central Pontine Myelinolysis Market | 2026-2036
Central Pontine Myelinolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Central Pontine Myelinolysis Market Outlook
Asset-light leasing models for high-field MRI systems is reconfiguring how smaller hospitals enter the CPM diagnostic space without capital-intensive purchases. Siemens Healthcare GmbH leverages its installed base of neuroimaging platforms to sustain service revenue streams across tertiary care networks. GE Healthcare competes through embedded AI-assisted diffusion-weighted imaging protocols that reduce scan interpretation time. Philips Healthcare anchors its position in rehabilitation-focused monitoring devices that track patient recovery trajectories post-diagnosis.
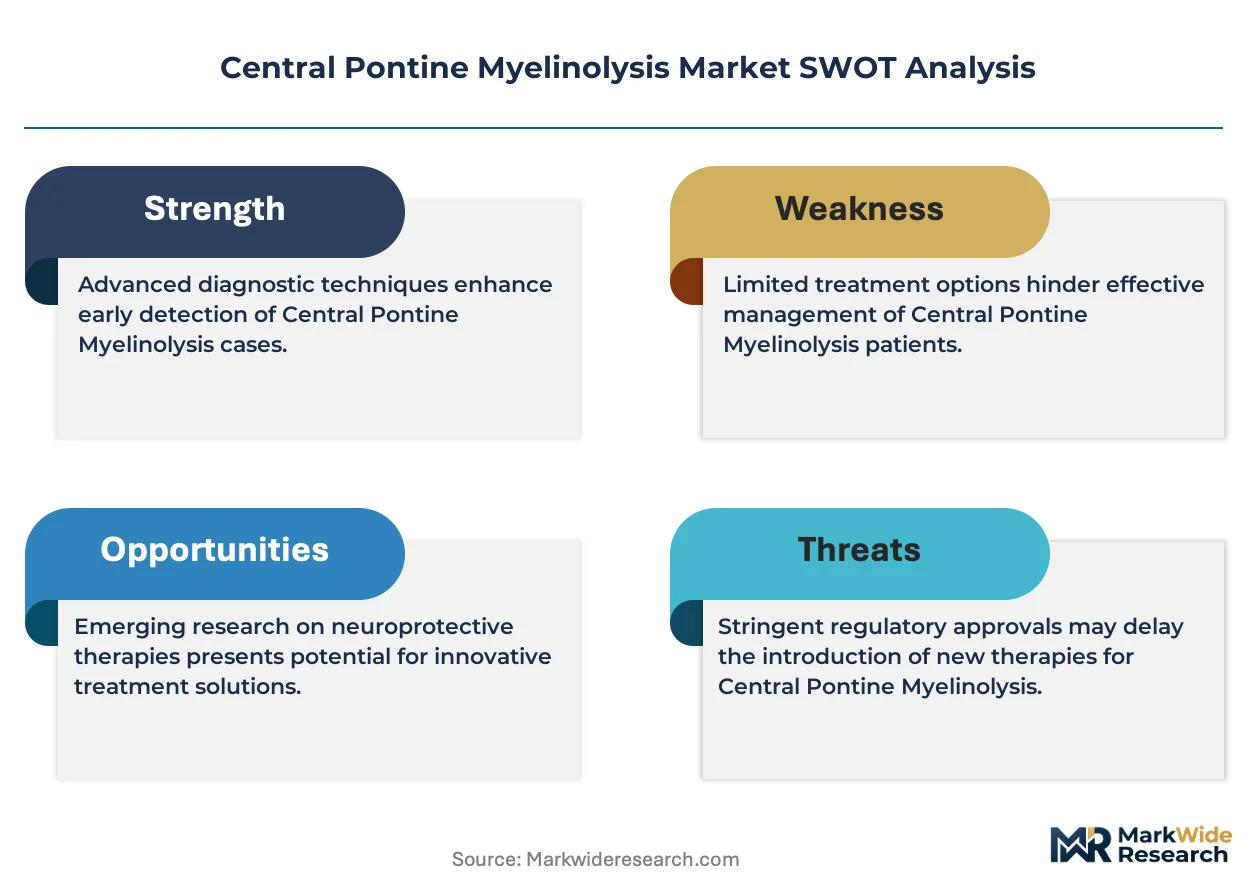
Central pontine myelinolysis denotes an acute, non-inflammatory demyelinating lesion centered on the pons, typically arising from rapid osmotic shifts—most commonly iatrogenic correction of chronic hyponatremia—visible on T2-weighted and FLAIR MRI sequences as symmetric trident-shaped hyperintensities. Its primary clinical purpose demands precise neuroimaging differentiation from stroke, encephalitis, and metabolic encephalopathies to guide immediate supportive management and prevent irreversible pontine damage. Diagnostic equipment dominates value capture given the irreplaceable role of MRI in confirming osmotic demyelination, while nutritional support represents the fastest-expanding segment as protocols emphasizing controlled sodium correction gain protocol adoption. Supportive therapy remains the mature, high-volume treatment category, though intravenous immunoglobulin is gaining investigational traction in atypical or refractory presentations.
The FDA oversees orphan drug designation pathways that reduce regulatory barriers for novel CPM therapeutics, while CMS reimbursement frameworks shape which diagnostic and rehabilitation services achieve sustainable hospital adoption. The EU MDR and EMA's rare disease incentives create parallel but distinct compliance requirements for manufacturers seeking European market access. Stakeholders must monitor how evolving neurocritical care guidelines reconcile sodium correction rates with emerging neuroprotective adjuncts.
Market Dynamics
The Central Pontine Myelinolysis market is being fundamentally restructured by the FDA's orphan drug designation pathway, which compresses clinical trial timelines and attracts venture capital into previously neglected neuroprotective therapeutics. This regulatory mechanism is redrawing competitive boundaries between diagnostic equipment manufacturers and emerging biopharma developers.
Growth Catalysts
- Orphan Drug Incentives:The FDA's seven-year market exclusivity provision for CPM therapeutics is drawing private equity into rare disease drug development pipelines previously deemed commercially unviable.
- Neurocritical Care Expansion:Tertiary hospitals across the United States are establishing dedicated osmotic demyelination management protocols that bundle advanced MRI diagnostics with specialized nursing units.
- Diffusion Tensor Imaging:High-resolution DTI protocols are enabling pre-symptomatic detection of pontine microstructural changes, expanding the addressable patient population beyond acute presentation cases.
Market Restraints
- Helium Supply Concentration:MRI system operation depends on helium sourced primarily from Qatar and the United States, creating vulnerability to export restrictions and price volatility for diagnostic providers.
- Reimbursement Compression:CMS diagnostic-related group classifications for CPM do not adequately differentiate complex osmotic demyelination cases from standard stroke protocols, limiting hospital investment in specialized care pathways.
- Clinical Trial Recruitment:The ultra-rare incidence of CPM forces sponsors to maintain multi-site international protocols, inflating per-patient study costs and extending regulatory submission timelines.
Strategic Opportunities
- Rehabilitation Technology Integration:Wearable neurostimulation devices paired with AI-driven gait analysis represent unclaimed white space in post-acute CPM recovery management.
- EMA Parallel Pathways:The European Medicines Agency's PRIME designation offers accelerated assessment for neuroprotective candidates, creating a regulatory bridge for US-developed therapies seeking dual-market approval.
- Telestroke Network Penetration:Rural hospital systems lacking on-site neuroradiology expertise present untapped demand for cloud-based MRI interpretation services with CPM-specific diagnostic algorithms.
Industry Challenges
- Neurocritical Care Specialist Scarcity:Board-certified neurointensivists remain concentrated in academic medical centers, constraining protocol standardization across community hospital settings.
- Legacy PACS Integration:Picture archiving systems deployed before 2018 lack native support for quantitative diffusion mapping, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Pontine Myelinolysis Market |
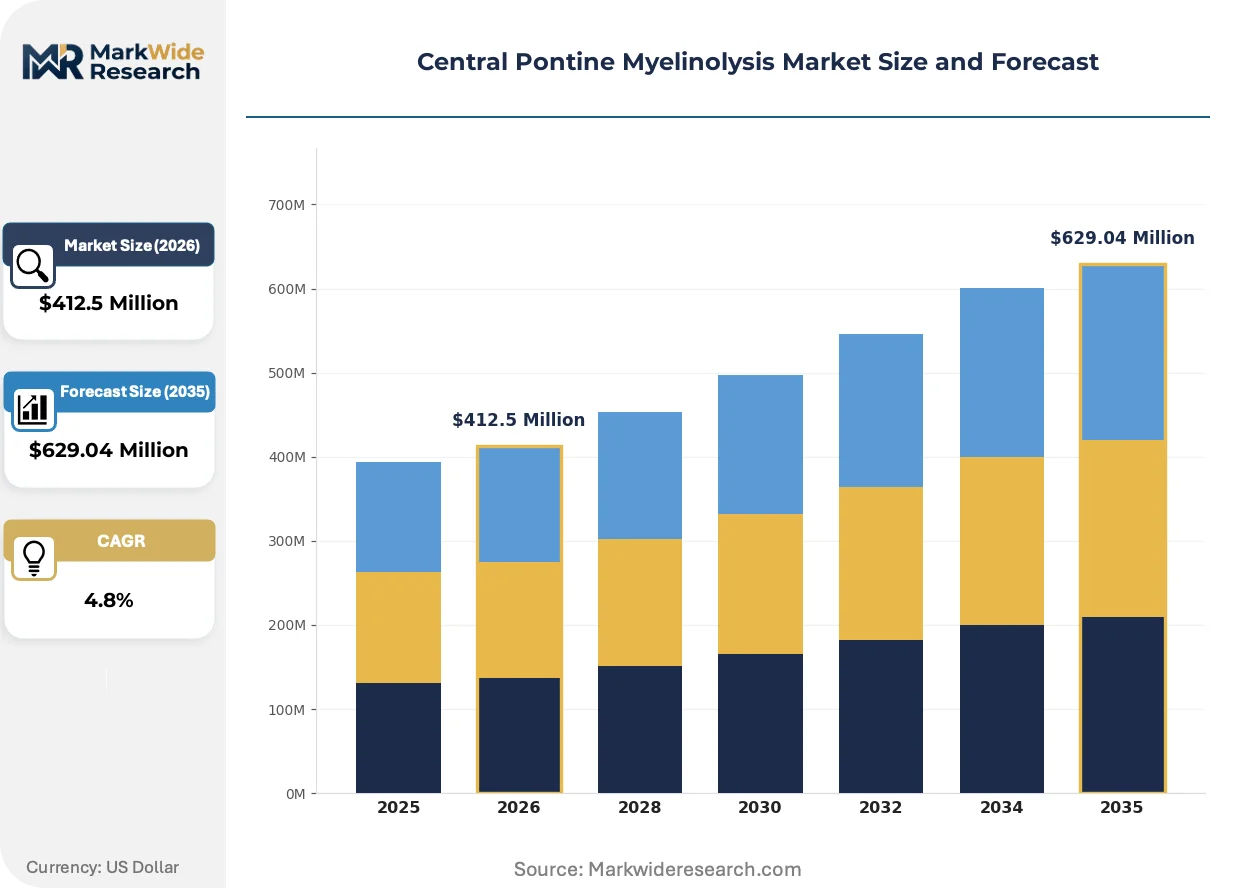
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Supportive Therapy, Corticosteroids, Intravenous Immunoglobulin, Plasmapheresis Care Setting: Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Care Patient Demographics: Adults, Pediatric, Elderly, Individuals with Comorbidities Product Type: Pharmaceuticals, Nutritional Support, Diagnostic Equipment, Monitoring Devices |
| Companies Covered | Fujifilm Holdings Corporation, GE Healthcare, Siemens Healthcare GmbH, Philips Healthcare, Shimadzu Corporation, Toshiba Medical Systems Corporation, Carestream Health, Hitachi Medical Corporation, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Pontine Myelinolysis Market Strategic Shifts
Artificial intelligence is penetrating neuroimaging workflows at an accelerating pace, compressing diagnostic timelines and redefining the economic relationship between equipment manufacturers and hospital radiology departments. Three distinct vectors are reshaping how CPM is detected, managed, and reimbursed.
Quantitative susceptibility mapping is collapsing the diagnostic window for osmotic demyelination by detecting paramagnetic iron deposition in pontine lesions invisible to conventional T2-FLAIR sequences. Academic medical centers in Boston and San Francisco are deploying QSM protocols within 24 hours of suspected hyponatremia correction. This capability is collapsing the distinction between research-grade and clinical-grade neuroimaging, forcing equipment vendors to bundle advanced reconstruction algorithms with standard MRI sales.
The FDA's breakthrough device designation pathway is accelerating clearance timelines for AI-assisted diffusion analysis tools that flag pontine hyperintensity patterns. Manufacturers gaining this designation secure prioritized review and enhanced CMS reimbursement coding discussions. Neurology departments at Cleveland Clinic and Mayo Clinic are piloting these algorithms to reduce attending radiologist interpretation burden during overnight shifts.
Hospital procurement committees are unbundling MRI hardware purchases from long-term service contracts, favoring third-party independent service organizations for preventive maintenance. This shift fragments vendor revenue streams and compresses margins on aftermarket parts. The pattern is most pronounced in the southeastern United States, where health system consolidation has centralized capital equipment decision-making.
Central Pontine Myelinolysis Market Segmentation
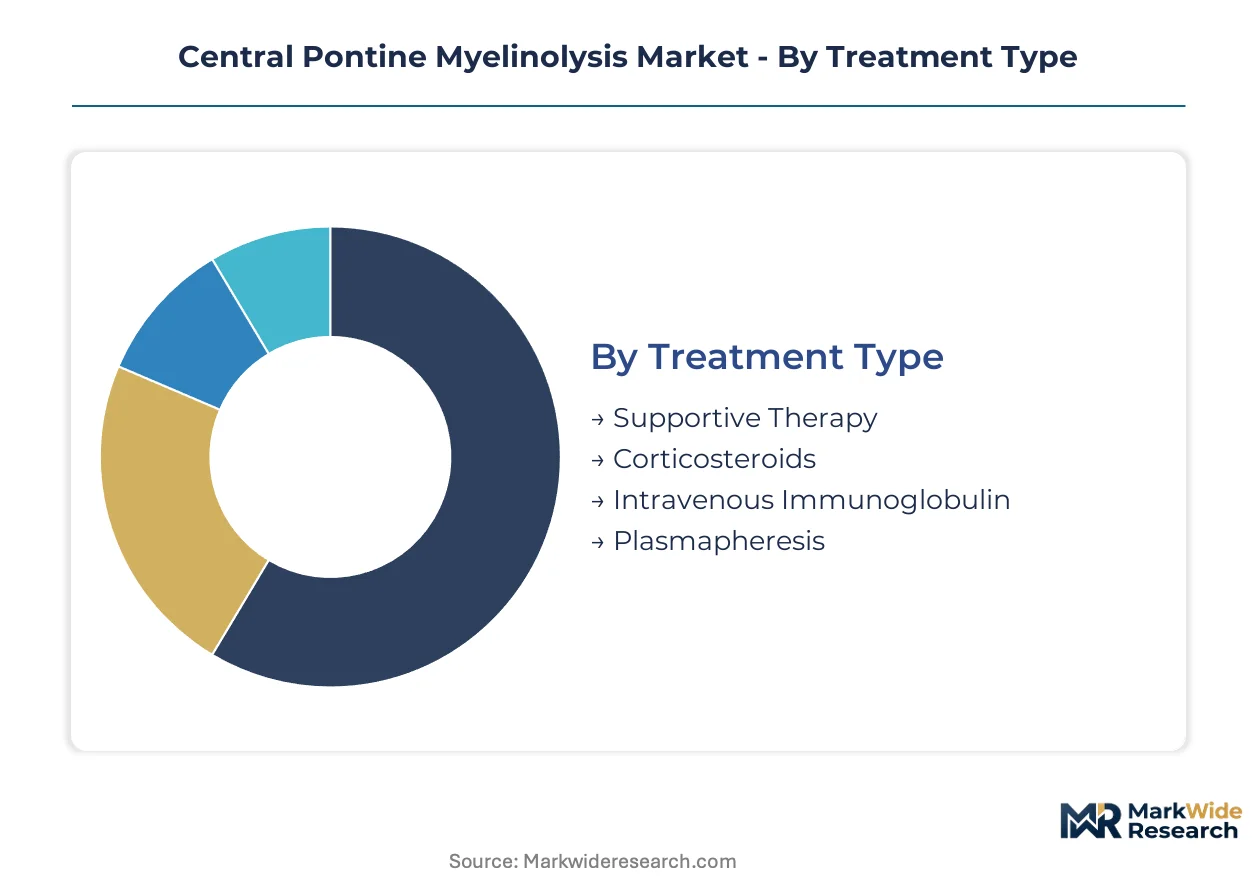
Segmentation in the Central Pontine Myelinolysis market reflects distinct clinical workflows, from acute neurocritical care through post-acute rehabilitation. Each category captures how patient acuity, care venue, and therapeutic modality intersect to determine procurement priorities and reimbursement pathways.
Treatment Type:
The maturity spectrum spans well-established supportive protocols to emerging immunomodulatory interventions with investigational status.
- Supportive Therapy:Encompasses controlled sodium correction, mechanical ventilation, and fluid management to stabilize osmotic gradients. Demand concentrates in tertiary hospital neurocritical care units across the United States, driven by protocol standardization efforts from professional societies. This segment retains volume leadership; Intravenous Immunoglobulin holds the steepest expansion curve.
- Intravenous Immunoglobulin:High-dose polyclonal antibody therapy targeting immune-mediated components of atypical osmotic demyelination. Adoption is accelerating in academic medical centers with neuroimmunology subspecialty programs, supported by FDA orphan drug incentives for refractory presentations.
- Corticosteroids:Methylprednisolone and dexamethasone protocols for inflammatory modulation in select CPM variants.
- Plasmapheresis:Therapeutic plasma exchange reserved for severe or rapidly progressive cases with suspected autoimmune overlap.
Supportive therapy commands the largest patient volume; IVIG is climbing the fastest as evidence accumulates for refractory cases.
Care Setting:
Cost tier differentiation separates capital-intensive inpatient infrastructure from lower-acuity outpatient alternatives.
- Hospitals:Tertiary and quaternary facilities with dedicated neurocritical care units, advanced MRI capability, and board-certified neurointensivist staffing. Demand concentrates in US academic medical centers clustered in Boston, Baltimore, and Houston, where specialized osmotic demyelination protocols have achieved institutional adoption.
- Rehabilitation Centers:Post-acute facilities delivering neurorehabilitation for motor and cognitive sequelae. Growth is fastest in the southeastern United States, where health system consolidation has centralized step-down care for complex neurological conditions.
- Outpatient Clinics:Neurology practices managing stable patients with residual symptoms.
- Home Care:Skilled nursing and physical therapy services for chronic disability management.
Hospitals absorb the highest per-patient costs; rehabilitation centers are gaining share fastest as bundled payment models incentivize earlier transition.
Patient Demographics:
Application focus varies across age-related physiological vulnerability and comorbidity burden.
- Adults:Working-age patients presenting with iatrogenic hyponatremia correction, typically post-surgical or psychiatric medication-related. This population drives diagnostic equipment demand in community hospital settings where neurocritical care protocols are expanding.
- Elderly:Patients over 65 with diminished osmoregulatory reserve and polypharmacy interactions. Concentrated demand in Florida, Arizona, and California retirement corridors, where specialized geriatric neurocritical care units are proliferating.
- Pediatric:Rare presentations in children with metabolic disorders or severe dehydration.
- Individuals with Comorbidities:Patients with liver transplantation, alcohol use disorder, or malnutrition predisposing to osmotic demyelination.
Adults represent the largest addressable population; elderly patients show the steepest expansion trajectory as population aging intensifies.
Product Type:
Margin structure separates high-value diagnostic capital equipment from consumable nutritional and pharmaceutical products.
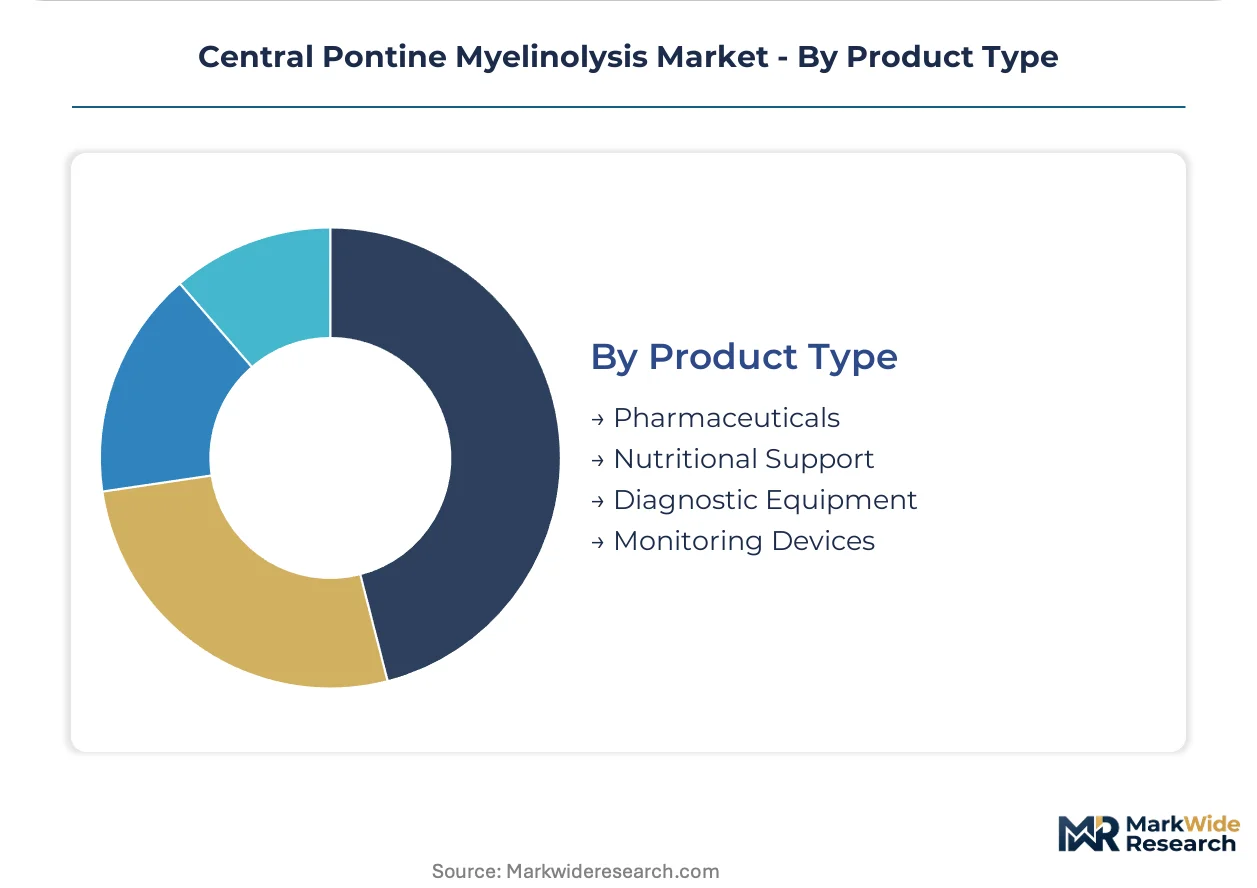
- Diagnostic Equipment:MRI systems with neuroimaging coils, diffusion tensor imaging capability, and quantitative susceptibility mapping. Demand concentrates in US hospital systems pursuing neurocritical care designation, where CMS reimbursement differentiates advanced imaging protocols.
- Nutritional Support:Enteral and parenteral formulations emphasizing controlled electrolyte delivery and thiamine supplementation. Fastest growth in integrated health networks standardizing sodium correction protocols across emergency and inpatient departments.
- Pharmaceuticals:Generic supportive medications and emerging neuroprotective candidates.
- Monitoring Devices:Wearable neurostimulation and gait analysis systems for post-acute recovery tracking.
Diagnostic equipment captures the highest unit margins; nutritional support is expanding most quickly as protocol adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial diagnostic equipment trade surplus in neuroimaging systems, while Germany and Japan anchor component exports for high-field MRI magnets. Import dependence concentrates in helium for cryogenic cooling, with Qatar and the United States supplying nearly all global demand.
United States
FDA orphan drug incentives are accelerating neuroprotective therapeutic development for refractory CPM presentations. CMS reimbursement frameworks shape hospital adoption of advanced MRI protocols through diagnostic-related group classifications. Academic medical centers in Boston and Houston have established dedicated osmotic demyelination management units with bundled care pathways.
Germany
Siemens Healthcare GmbH leverages its installed neuroimaging base to sustain service revenue across tertiary care networks throughout Bavaria and Baden-Württemberg. EU MDR compliance requirements and EMA rare disease incentives create parallel regulatory pathways for manufacturers seeking European market access. The Rhine-Ruhr metropolitan region concentrates specialized neurocritical care infrastructure with standardized sodium correction protocols.
Japan
PMDA accelerated review pathways support domestic development of AI-assisted diffusion-weighted imaging algorithms for early demyelination detection. METI industrial policy prioritizes medical device export competitiveness in neuroimaging equipment. Tokyo and Osaka academic hospitals lead adoption of quantitative susceptibility mapping for pre-symptomatic pontine lesion identification.
United Kingdom
NHS England specialized commissioning frameworks determine which neurocritical care services receive sustainable reimbursement for complex osmotic demyelination cases. MHRA post-Brexit regulatory autonomy enables streamlined approval for breakthrough diagnostic devices. The Greater Manchester and London neurosciences clusters are piloting telestroke network extensions for rural MRI interpretation.
China
NMPA innovative medical device approval pathways are compressing clearance timelines for domestically manufactured high-field MRI systems. National health reform initiatives expand neurocritical care capacity in tertiary hospitals across the Yangtze River Delta. Shanghai and Beijing medical centers are deploying AI-assisted diagnostic algorithms for pontine hyperintensity pattern recognition.
Central Pontine Myelinolysis Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in magnet and coil fabrication. The vendor base concentrates around multinational imaging conglomerates with established hospital procurement relationships, while mid-tier regional manufacturers compete on price-sensitive replacement cycles. Three archetypes dominate: full-stack diagnostic platform providers, independent software vendors for AI-assisted interpretation, and third-party service organizations unbundling maintenance contracts. Competitive dynamics center on strategic partnerships between equipment manufacturers and academic medical centers for protocol development, alongside vertical integration into helium recycling to secure cryogenic supply chains.
Among full-stack platform providers, Siemens Healthcare GmbH, GE Healthcare, and Philips Healthcare occupy positions representing distinct strategic vectors in neuroimaging. Siemens exemplifies the installed-base service model, anchoring recurring revenue through long-term hospital contracts. GE represents the AI-embedded protocol approach, integrating algorithm-assisted interpretation directly into scanner workflows. Philips sits within the rehabilitation-focused monitoring tier, extending hardware footprints into post-acute recovery tracking.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Siemens Healthcare GmbH |
| Philips Healthcare |
| Shimadzu Corporation |
| Toshiba Medical Systems Corporation |
| Carestream Health |
| Hitachi Medical Corporation |
| Roche |
| Others |
Value Chain & Pricing Dynamics
The Qatar-US helium corridor governs cryogenic logistics costs for MRI system operations, concentrating pricing power among diagnostic equipment vendors with captive helium recycling infrastructure while forcing tiered service contract differentiation across hospital buyer segments.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations around total cost-of-ownership models spanning hardware acquisition, preventive maintenance, and software upgrade entitlements. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with bundled neurocritical care protocols from community hospitals purchasing on replacement cycles. Cost compression in the economy tier is intensifying because third-party independent service organizations are unbundling maintenance from original equipment manufacturer contracts. Community hospital systems exhibit highest price sensitivity due to capital constraint; academic medical centers demonstrate lowest sensitivity given bundled reimbursement pathways.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements between MRI magnet fabricators and downstream system integrators, compressing working capital for component specialists. Geographic supply concentrates in Germany for gradient coil assemblies, Japan for superconducting wire, and the United States for helium liquefaction infrastructure. Raw material dependencies encompass niobium-titanium superconductors, high-purity helium, and rare-earth permanent magnets. Single-source vulnerability in Qatar's helium export capacity poses structural risk. Distribution runs through authorized dealer networks with regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Central Pontine Myelinolysis market functions as a service-attach opportunity where AI-assisted diagnostic software subscriptions are expanding faster than MRI hardware replacement demand, creating recurring revenue pools that offset capital equipment margin compression.
For Market Incumbents: Build installed-base moats through long-term neuroimaging service contracts that embed quantitative susceptibility mapping upgrades. Incumbent MRI manufacturers should consolidate aftermarket parts distribution to counter third-party independent service organization encroachment. Threat from cloud-based MRI interpretation platforms demands defensive software companion development. Channel control over tertiary hospital procurement committees remains the critical lever. For New Entrants and Emerging Players: Rural telestroke networks in the southeastern United States represent the most penetrable entry point for AI-assisted diffusion analysis tools lacking on-site neuroradiology expertise. Post-acute rehabilitation monitoring devices for gait analysis and neurostimulation tracking offer unclaimed white space with lower regulatory barriers than diagnostic equipment. Go-to-market angle should target health system consolidation decision-makers with outcome-based contracting for bundled post-CPM recovery management. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent software vendors with FDA breakthrough device designation for pontine hyperintensity detection algorithms. Long-term viability hinges on neurocritical care protocol standardization expanding addressable patient populations beyond acute presentation cases. Acquisition target archetype: AI-assisted diagnostic platforms with CMS reimbursement coding discussions underway. Signal to watch: FDA orphan drug designation announcements for neuroprotective therapeutics indicating expanded therapeutic investment into the CPM ecosystem.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recycling Infrastructure Investment | Captive helium recovery systems insulate MRI operators from Qatar export volatility and price spikes. |
| AI-Assisted Diffusion Analysis FDA Submission | Breakthrough device designation accelerates CMS reimbursement coding for overnight radiology shift support. |
| Neurocritical Care Unit Partnership | Bundled care pathway agreements with academic medical centers lock in multi-year equipment refresh cycles. |
| Third-Party Service Organization Acquisition | Consolidating independent maintenance providers defends aftermarket revenue against unbundling trends. |
| Rehabilitation Monitoring Device Launch | Wearable neurostimulation platforms extend hardware footprints into post-acute recovery tracking segments. |
Study Parameters
A spread of perspectives from neurocritical care intensivists, hospital procurement managers, neuroradiology department heads, and biomedical equipment engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS diagnostic-related group classifications, and hospital capital expenditure disclosures. Bottom-up patient volume estimates triangulated with top-down neuroimaging equipment shipment data.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning treatment type, care setting, patient demographics, and product category. CAGRs derived from fitted growth curves calibrated to historical adoption patterns for orphan disease diagnostics and neurocritical care infrastructure expansion. Industry-specific inputs encompassed neuroimaging protocol standardization timelines and helium supply contract durations.
Practitioners should monitor FDA orphan drug designation velocity, CMS reimbursement coding updates for quantitative susceptibility mapping, and Qatar helium export policy shifts for early signals requiring forecast adjustment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Major Depressive Disorder (MDD) Treatment Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Chronic Urticaria Market