
 Pyoderma Gangrenosum Therapeutics Market | 2026-2036
Pyoderma Gangrenosum Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pyoderma Gangrenosum Therapeutics Market Intelligence
Specialist biopharmaceutical R&D capacity in the United States is rebalancing the pipeline toward targeted biologics for rare inflammatory skin diseases. AbbVie leverages its immunology portfolio to address autoimmune-related manifestations of the condition. Pfizer competes through its broad pipeline and established presence in inflammatory disorders. UCB specializes in developing novel therapies for severe chronic diseases, extending its expertise into niche dermatological indications.
Pyoderma gangrenosum therapeutics encompass a range of treatments for a rare, ulcerative skin condition characterized by painful, rapidly progressing skin necrosis. These therapies primarily aim to modulate the neutrophilic inflammatory response, a key pathophysiological feature of the disease. Biologics, particularly TNF inhibitors, command the highest value share due to their targeted mechanism and efficacy in refractory cases. Hospitals remain the primary end-user setting for initial diagnosis and management of acute presentations, while specialty clinics handle long-term care.
Market access and clinical development are governed by orphan drug regulations from the FDA in the United States and the EMA in Europe. In Japan, the PMDA's framework for rare diseases influences trial design and approval pathways for new therapeutics. Future investment decisions will hinge on demonstrating superior efficacy and safety profiles compared to existing off-label systemic corticosteroids and immunosuppressants.
Market Dynamics
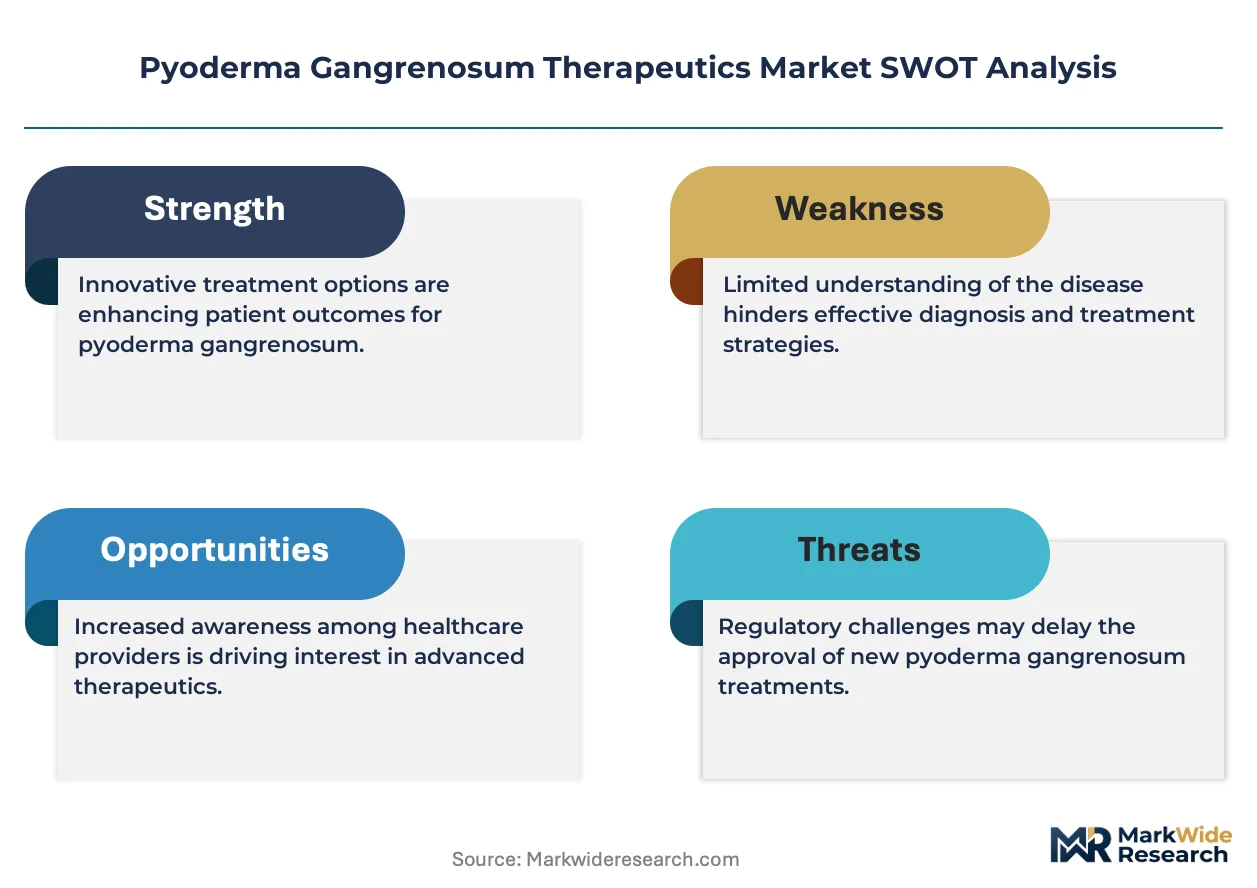
The pyoderma gangrenosum therapeutics market is defined by the high cost and clinical complexity of treatment, creating a structural tension between expensive, targeted biologics and established, inexpensive off-label systemic corticosteroids. This dynamic shapes all aspects of market access and R&D investment.
Growth Catalysts
- Orphan Drug Frameworks:Regulatory incentives provided by the FDA in the United States and the EMA in Europe, such as market exclusivity and fee reductions, encourage investment in developing therapies for rare conditions like pyoderma gangrenosum.
- Specialty Clinic Expansion:The increasing number of specialized dermatology and rheumatology clinics provides dedicated infrastructure for managing chronic cases, improving long-term treatment adherence and outcomes, which supports the use of advanced therapeutics.
- Improved Diagnostic Tools:Advances in histopathology and the exclusion of other mimickers of ulcerative skin disease are leading to more accurate and timely diagnosis, expanding the addressable patient population for approved therapies.
Market Restraints
- High Cost of Biologics:The significant expense associated with biologic therapies, particularly TNF inhibitors, creates substantial reimbursement hurdles and limits patient access, especially in healthcare systems with stringent cost-containment measures.
- Lack of Definitive Biomarkers:The absence of a specific diagnostic biomarker for pyoderma gangrenosum leads to diagnostic delays and misdiagnosis, often resulting in inappropriate initial treatments and hindering recruitment for clinical trials.
- Off-Label Competition:Widespread, long-standing use of lower-cost, off-label systemic corticosteroids and conventional immunosuppressants presents a significant substitution threat, particularly for less severe cases or in markets with limited reimbursement for biologics.
Strategic Opportunities
- Targeted Patient Subpopulations:Developing therapies for specific pyoderma gangrenosum phenotypes, such as those associated with underlying inflammatory bowel disease or rheumatoid arthritis, offers a path for demonstrating superior efficacy and securing niche market positioning.
- Geographic Market Development:There is a significant opportunity for market education and therapy introduction in large Asia-Pacific countries, including Japan, where rising healthcare standards and frameworks like the PMDA's can support new drug approvals.
- AI-Powered Diagnostics:Integrating artificial intelligence with dermatoscopic imaging could create decision-support tools that help non-specialists differentiate pyoderma gangrenosum from other ulcerative conditions, accelerating correct diagnosis and treatment initiation.
Industry Challenges
- Patient Recruitment Rarity:The low prevalence of pyoderma gangrenosum makes it exceptionally difficult and time-consuming to recruit a sufficient number of patients for statistically significant, placebo-controlled clinical trials, delaying new product development.
- Reimbursement Heterogeneity:Manufacturers face the challenge of navigating disparate and complex reimbursement requirements for high-cost orphan drugs across national and regional payers in Europe and the United States, complicating market access strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyoderma Gangrenosum Therapeutics Market |
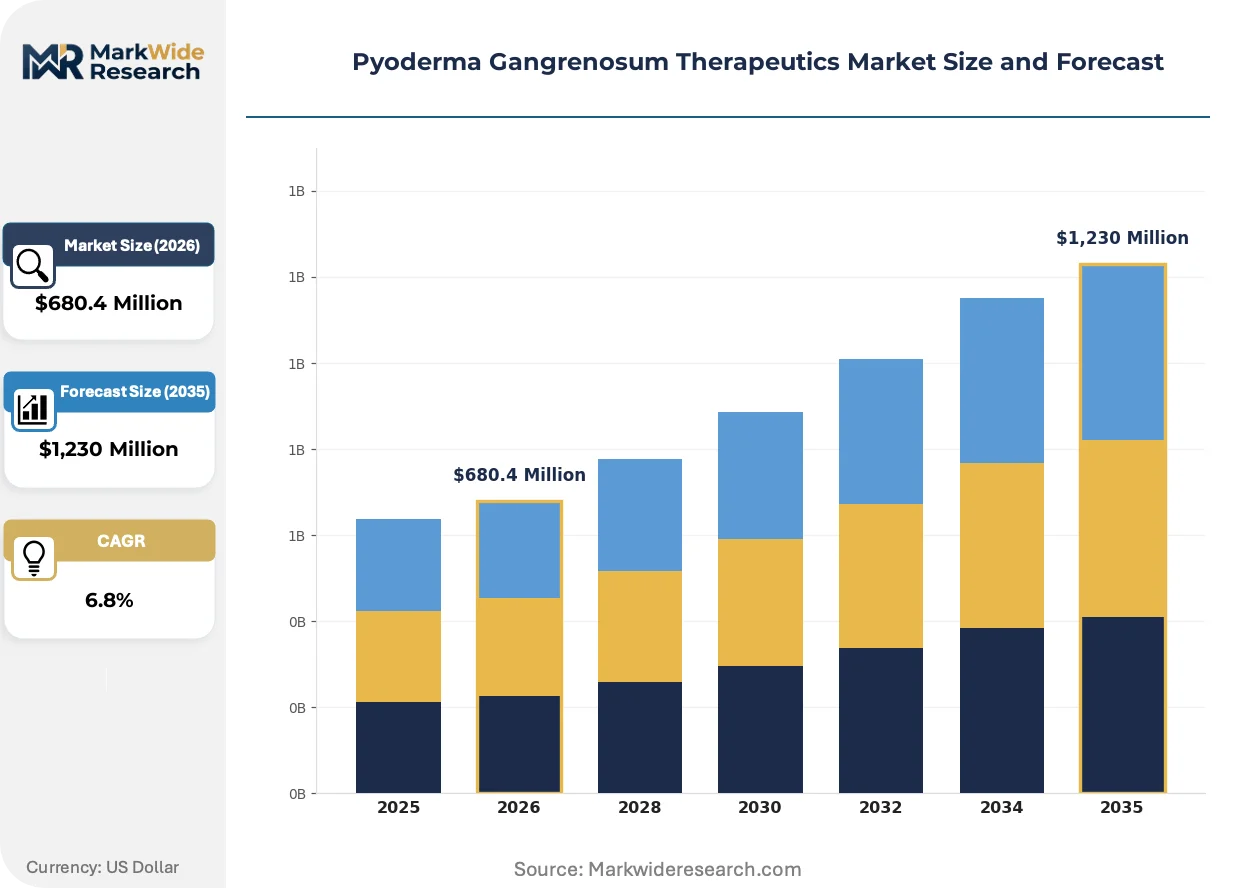
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,230 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Immunosuppressants, Corticosteroids, Antibiotics, Topical Agents Therapy Area: Autoimmune Disorders, Inflammatory Skin Diseases, Rare Disorders, Dermatological Conditions End User: Hospitals, Specialty Clinics, Dermatology Centers, Research Institutes Delivery Mode: Oral, Intravenous, Topical, Subcutaneous |
| Companies Covered | AbbVie Inc., Novartis AG, Pfizer Inc., Johnson & Johnson, Amgen Inc., Merck & Co., Inc., GlaxoSmithKline plc, UCB, Takeda Pharmaceutical Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyoderma Gangrenosum Therapeutics Market Strategic Shifts & Innovations
A fundamental shift toward precision medicine is reshaping therapeutic development, moving away from broad immunosuppression towards pathway-specific interventions. This evolution influences clinical trial design, regulatory strategy, and the very definition of treatment success in pyoderma gangrenosum.
Targeted biologics, such as inhibitors of specific interleukins like IL-1, represent the next frontier beyond broad-spectrum TNF blockade. Specialist biopharmaceutical developers are advancing these agents through clinical trials for refractory pyoderma gangrenosum cases. This development is modularizing the treatment paradigm, enabling clinicians to select therapies that correspond to a patient's specific inflammatory cytokine profile.
The European Medicines Agency's PRIME (PRIority MEdicines) scheme provides early and enhanced scientific and regulatory support to medicines targeting unmet needs. This program accelerates the assessment timeline for promising therapies designed for rare diseases like pyoderma gangrenosum. Consequently, drug developers targeting the EU market are increasingly aligning their clinical evidence packages with PRIME eligibility criteria to gain a competitive advantage.
A clear behavioral shift is underway as long-term disease management migrates from hospital inpatient settings to outpatient specialty clinics. This trend is disrupting hospital-centric pharmaceutical distribution models and empowering specialized dermatology and rheumatology centers. This transition is most visible in the United States and Germany, where reimbursement models and infrastructure favor outpatient care for chronic inflammatory conditions.
Pyoderma Gangrenosum Therapeutics Market Segmentation
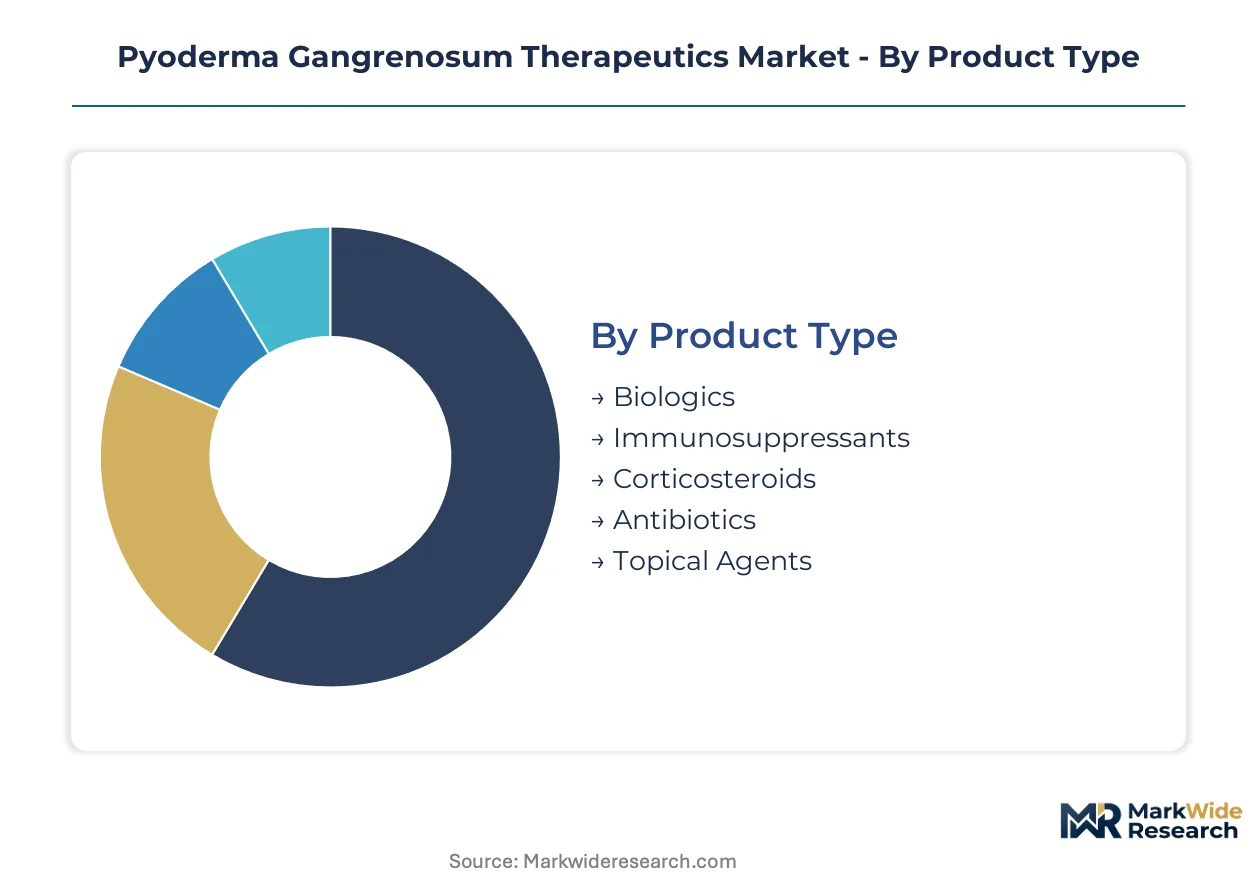
The pyoderma gangrenosum therapeutics market is categorized by various dimensions that reflect treatment approaches, patient demographics, and healthcare infrastructure. Understanding these segments helps to delineate the specific drivers and constraints influencing therapeutic adoption and market evolution across different regions.
Product Type:
Patient response profiles and cost considerations primarily differentiate buyers across product types in pyoderma gangrenosum therapeutics.
- Biologics:These advanced therapies target specific inflammatory pathways, such as TNF-alpha, to modulate the immune response. Demand concentrates in the United States due to high reimbursement rates for targeted treatments in refractory pyoderma gangrenosum cases.
- Immunosuppressants:These systemic agents broadly suppress the immune system, offering a non-specific reduction in inflammatory activity.
- Corticosteroids:Systemic corticosteroids are powerful anti-inflammatory agents used as first-line treatment for acute flares. Their widespread off-label use in Germany is driven by established clinical practice and cost-effectiveness.
- Antibiotics:Antibiotics address secondary bacterial infections frequently associated with pyoderma gangrenosum lesions.
- Topical Agents:These formulations are applied directly to the skin, offering localized anti-inflammatory or antiseptic effects for milder cases.
Volume sits with Corticosteroids; growth tilts toward Biologics.
Therapy Area:
The specific disease etiology and clinical presentation dictate the therapeutic application within this market.
- Autoimmune Disorders:This area encompasses conditions where the immune system mistakenly attacks healthy body tissues, often underlying pyoderma gangrenosum.
- Inflammatory Skin Diseases:Pyoderma gangrenosum falls under this category, characterized by chronic inflammation leading to skin damage. The United States market exhibits significant investment in novel biologics for complex inflammatory skin diseases.
- Rare Disorders:Pyoderma gangrenosum is classified as a rare disease, benefiting from orphan drug designations that incentivize therapeutic development. Regulatory frameworks from the FDA and EMA specifically support drug development for rare disorders.
- Dermatological Conditions:This broad category includes all diseases affecting the skin, hair, and nails, providing a general context for pyoderma gangrenosum.
Targeted interventions for Rare Disorders are expanding most quickly, while Dermatological Conditions represent a foundational segment.
End User:
The organizational capacity for patient management and treatment complexity defines end-user engagement.
- Hospitals:These institutions manage acute presentations and severe cases requiring inpatient care and complex medical interventions. Hospitals in Germany serve as primary referral centers for initial diagnosis and management of pyoderma gangrenosum.
- Specialty Clinics:Dedicated dermatology and rheumatology clinics provide long-term management, advanced therapeutic administration, and follow-up care for chronic conditions. The expansion of specialty clinics in the United States supports the sustained use of advanced biologics.
- Dermatology Centers:These specialized outpatient facilities focus on skin conditions, offering diagnostic services and various treatment modalities.
- Research Institutes:Academic and private research entities conduct clinical trials and fundamental studies to advance understanding and treatment of pyoderma gangrenosum.
Hospitals maintain a high patient throughput, whereas Specialty Clinics are demonstrating the steepest expansion trajectory.
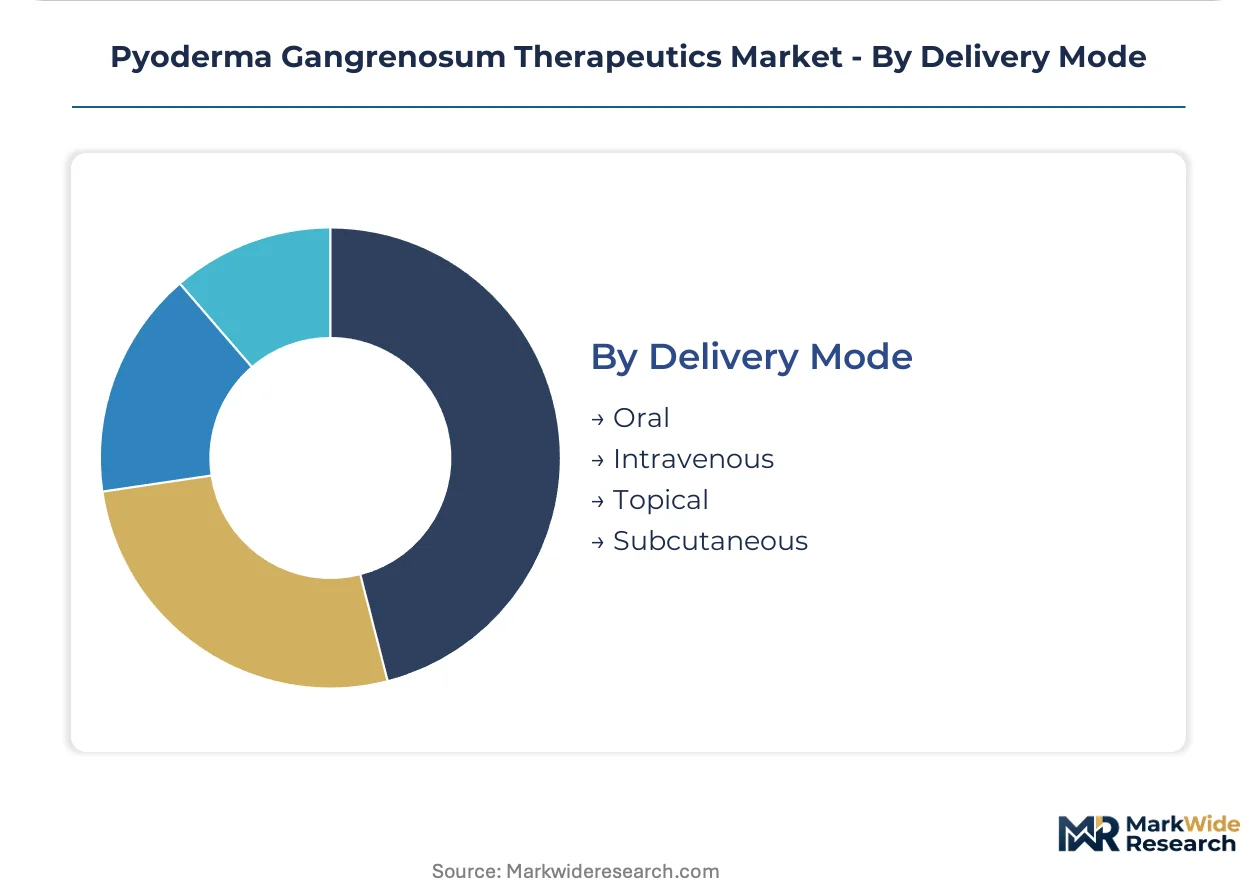
Delivery Mode:
Patient convenience and drug bioavailability drive the maturity and preference for various delivery modes.
- Oral:Oral medications offer systemic absorption and patient convenience for home administration. This mode remains prevalent for corticosteroids and some immunosuppressants in Europe.
- Intravenous:Intravenous administration ensures rapid and complete systemic drug delivery, typically used for acute interventions or biologics requiring hospital-based infusion. Hospitals in the United States frequently utilize intravenous delivery for initial biologic therapies.
- Topical:Topical agents are applied directly to the skin lesions, providing localized treatment with minimal systemic exposure.
- Subcutaneous:Subcutaneous injections allow for self-administration at home, enhancing patient adherence for long-term biologic therapies.
Traditional Oral administration retains significant volume, but Subcutaneous options are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist biopharmaceutical R&D capacity in the United States anchors the global pyoderma gangrenosum therapeutics market. This market exhibits varied demand and regulatory landscapes across key geographies. Different healthcare infrastructures and reimbursement policies influence therapeutic adoption.
United States
Demand for advanced biologics is high due to significant biopharmaceutical R&D investment and robust reimbursement for targeted treatments. The FDA's orphan drug designation framework incentivizes development for rare dermatological conditions. Boston's biotech hub drives innovation in rare disease therapies, attracting significant capital.
Germany
Germany's advanced dermatological care infrastructure and high reimbursement rates support specialized treatments. EMA's orphan drug regulations influence market access for novel therapies across Europe. Berlin's medical centers serve as primary referral sites for initial diagnosis and management of complex skin conditions.
Japan
Rising healthcare standards and increasing focus on rare diseases create opportunities for new therapy introduction in Japan. The PMDA's framework for rare diseases influences trial design and approval pathways. Tokyo's pharmaceutical research facilities contribute to novel drug development, particularly for unmet needs.
France
Unmet medical needs in rare dermatological conditions drive interest in innovative therapies within France. The European Medicines Agency's PRIME scheme accelerates assessment timelines for promising rare disease drugs. Paris-Saclay's life sciences cluster fosters research into targeted biologics, enhancing therapeutic options.
China
China's large patient population and rising healthcare expenditure present a significant opportunity for market education and therapy introduction. The NMPA's evolving drug approval pathways increasingly support rare disease treatments. Shanghai's biopharmaceutical parks are becoming centers for clinical trial activity for advanced therapeutics.
Pyoderma Gangrenosum Therapeutics Market Key Industry Players
Global majors compete with regional champions across R&D capacity and market access strategies in the pyoderma gangrenosum therapeutics market. This market exhibits a consolidated structure among a few large pharmaceutical firms, alongside specialist biopharmaceutical developers focusing on niche indications. Strategic archetypes include diversified immunology powerhouses and targeted rare disease innovators. Portfolio diversification and strategic partnerships represent dominant competitive moves for market expansion.
Leading global pharmaceutical firms, such as AbbVie Inc., Pfizer Inc., and UCB, exemplify this market's competitive dynamics. These companies leverage extensive R&D capabilities and established immunology portfolios to address autoimmune-related manifestations of pyoderma gangrenosum. Their broad pipelines and global presence enable them to navigate complex regulatory landscapes and secure market access for advanced therapies. These players often pursue geographic expansion into emerging markets to broaden their patient reach.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Amgen Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| UCB |
| Takeda Pharmaceutical Company Ltd. |
| Others |
Cost & Logistics Intelligence
The European Medicines Agency's PRIME scheme gates access for novel therapies, impacting both qualified supply and premium-tier pricing for orphan drugs. This regulatory framework ensures that promising treatments for rare conditions like pyoderma gangrenosum gain accelerated assessment, influencing market entry and pricing power.
Pricing Analysis
Warranty and service bundling for biologic therapies often dictates the overall cost structure for healthcare providers and patients. The dominant pricing structure for advanced biologics leans towards value-based models, reflecting demonstrated efficacy in refractory cases. Price differentiation stems from drug efficacy profiles and the specific patient population targeted, especially for conditions like pyoderma gangrenosum. Pricing pressure stems from the widespread availability of lower-cost, off-label systemic corticosteroids. Hospitals and specialty clinics are particularly sensitive to the overall cost of biologics, while patients with severe, refractory pyoderma gangrenosum prioritize efficacy over cost.
Supply Chain Analysis
Logistics and freight costs for temperature-sensitive biologic drugs represent a significant component of the overall supply chain expense. Geographic supply concentration for active pharmaceutical ingredients (APIs) for biologics primarily resides in countries like the United States, Germany, and Switzerland. Raw material dependencies include specialized cell cultures and purification reagents. Single-source vulnerability for rare disease therapeutics presents a structural supply chain risk. Distribution runs through a network of specialized pharmaceutical distributors and hospital pharmacies, designed to handle cold chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity bottlenecks in specialized manufacturing for biologics create a supply-constrained market, propping up pricing for advanced pyoderma gangrenosum therapeutics.
For Market Incumbents: Anchor pipeline development in targeted biologics for specific pyoderma gangrenosum phenotypes, such as those associated with inflammatory bowel disease. Pursue strategic partnerships with specialized dermatology clinics to enhance patient access and real-world data collection. This strategy defends against emerging biosimilar threats and reinforces market leadership in complex inflammatory skin diseases. Invest in advanced diagnostic tools to solidify market positioning.
For New Entrants and Emerging Players: The FDA's orphan drug designation framework in the United States opens a window for novel therapies addressing unmet needs in pyoderma gangrenosum. Target underpenetrated geographic markets like China, focusing on market education and establishing early-stage clinical trial infrastructure. Develop AI-powered diagnostic solutions to accelerate correct diagnosis, offering a compelling go-to-market angle for non-specialists. Focus on therapies that demonstrate superior safety profiles over existing immunosuppressants.
For Investors and Strategic Acquirers: Increased investment in precision medicine approaches for rare inflammatory skin diseases is the leading indicator that this market will see sustained growth over the next 5-10 years. Acquisition targets should include specialist biopharmaceutical firms with late-stage clinical assets or novel diagnostic platforms. A signal to watch includes regulatory approvals for non-TNF inhibitor biologics, indicating a shift in treatment paradigms and expanding addressable markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for IL-1 Inhibitors | Advances pathway-specific treatments for refractory pyoderma gangrenosum cases, improving patient outcomes. |
| Regulatory Approval Pathway Acceleration (PRIME Scheme) | Expedites market entry for promising rare disease therapies in Europe, securing competitive advantage. |
| Manufacturing Scale-Up for Biologics | Ensures consistent supply for high-demand targeted therapies, meeting growing patient needs. |
| Strategic Partnership with AI Diagnostics Firms | Integrates advanced diagnostic capabilities, improving diagnosis accuracy and treatment initiation. |
| Geographic Expansion into Asia-Pacific Markets | Broadens patient reach and captures new revenue streams in regions with rising healthcare standards. |
Research Approach
Document review covered FDA filings, EMA submissions, and relevant clinical trial registries, complemented by interviews with dermatology key opinion leaders, hospital formulary directors, and specialty clinic administrators. This approach integrated insights from drug development executives and payer access specialists. Secondary data sources included pharmaceutical industry reports, academic publications on rare dermatological conditions, and government health agency statistics. Bottom-up and top-down triangulation validated market size estimations.
The model produced volume and value projections across the analysis window, reflecting the complex interplay of treatment adoption and reimbursement policies. Segmentation dimensions modeled included product type, therapy area, end user, and delivery mode, alongside regional regulatory frameworks. Compound annual growth rates were derived from historical market trends and projected shifts in clinical practice. Forecast inputs included anticipated new drug approvals and changes in diagnostic accuracy for pyoderma gangrenosum.
The model assumes a particular technology adoption path; alternative pathways for targeted biologics would alter the outlook. Forecasts reflect assumptions regarding regulatory incentives and evolving treatment guidelines. Specific risk factors, such as unexpected clinical trial failures or changes in reimbursement policies, could revise these projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market