
 Hepatic Encephalopathy Treatment Market | 2026-2036
Hepatic Encephalopathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatic Encephalopathy Treatment Market Foresight
Good Manufacturing Practice certification for active pharmaceutical ingredients is collapsing as a baseline barrier, forcing smaller compounders out of the ammonia-scavenger supply base. Mallinckrodt leverages its vertically integrated rare-disease infrastructure to sustain dominance in intravenous ammonia management. Salix Pharmaceuticals anchors the oral segment through deep formulary control across academic medical centers. Norgine competes in Europe with specialized distribution to hepatology wards.
Hepatic encephalopathy treatment encompasses pharmacological interventions that reduce blood ammonia levels or modulate gut flora to prevent neuropsychiatric deterioration in liver failure patients; formulations range from synthetic disaccharides like lactulose to minimally absorbed antibiotics such as rifaximin, with dosing titrated against West Haven criteria severity staging. The product-type dimension shows lactulose occupying the volume base as generic saturation erodes margin, while rifaximin commands premium positioning in recurrent HE prophylaxis. Hospital pharmacy channels control the majority of value capture due to infusion-based acute management protocols, though home-care routes are expanding as oral maintenance regimens lengthen.
FDA orphan-drug designations and EMA conditional marketing authorizations shape which developers can advance novel ammonia scavengers through pivotal trials. The EU MDR and updated FDA guidance on hepatic impairment pharmacokinetics are raising the evidentiary threshold for new entrants. Stakeholders must monitor how payer formularies reconcile the cost of recurrent HE hospitalizations against preventive oral therapy spend.
Market Dynamics
Hospital-based gastroenterology departments are expanding adoption of ammonia-lowering protocols, tightening the link between acute liver failure management and formulary decisions. This institutional shift is compressing development timelines for novel therapeutics while elevating evidence requirements for market access.
Growth Catalysts
- EMA Conditional Marketing Authorizations:These pathways accelerate novel ammonia scavengers through pivotal trials, enabling earlier patient access in Europe.
- Specialist hepatology infrastructure:Concentrated patient volumes in the United States, Germany, and Japan drive protocol standardization and premium therapy uptake.
- Recurrent HE hospitalization costs:Payer formularies increasingly reconcile preventive oral therapy spend against acute episode expenses, shifting reimbursement logic.
Market Restraints
- Active pharmaceutical ingredient GMP certification collapse:Baseline quality barriers are forcing smaller compounders out of the ammonia-scavenger supply base, concentrating sourcing risk.
- FDA hepatic impairment pharmacokinetics guidance:Updated evidentiary thresholds are extending new entrant development cycles and raising trial costs.
- Generic lactulose saturation:Erosion of margin in the volume-base segment limits reinvestment capacity for established oral therapy manufacturers.
Strategic Opportunities
- Home-care route expansion:Oral maintenance regimen lengthening is opening ambulatory channels beyond traditional hospital pharmacy capture.
- EU MDR compliance services:Device-therapeutic convergence in ammonia monitoring creates adjacent revenue streams for diagnostic-therapy bundling.
- Japan's liver transplant network density:Specialist infrastructure concentration enables targeted premium positioning for recurrent HE prophylaxis.
Industry Challenges
- West Haven criteria standardization:Severity staging heterogeneity complicates dosing titration protocols and trial endpoint alignment across clinical sites.
- Orphan-drug exclusivity navigation:FDA designation requirements are reshaping competitive entry sequencing and patent strategy complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatic Encephalopathy Treatment Market |
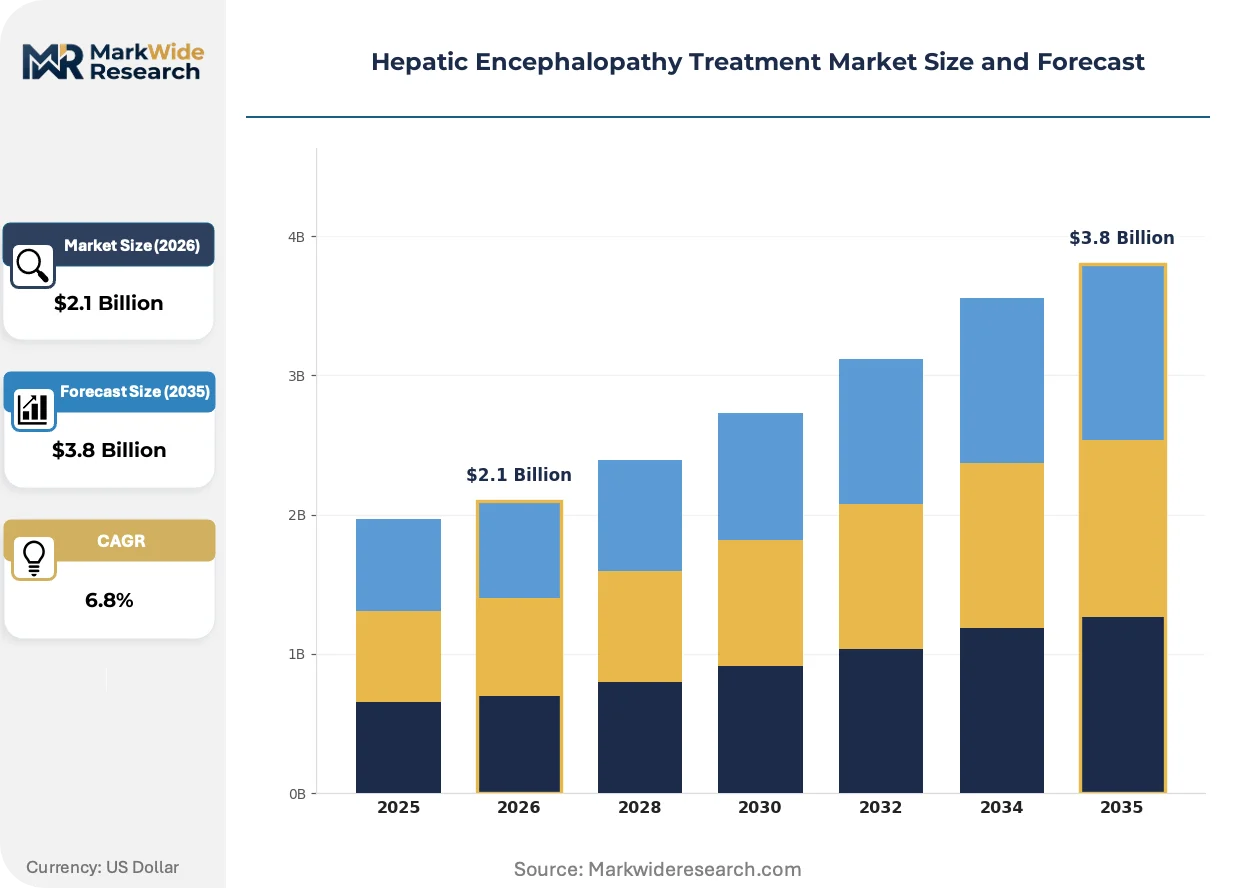
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactulose, Rifaximin, Branched-Chain Amino Acids, Zinc End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Administration Route: Oral, Intravenous, Sublingual, Rectal Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Mallinckrodt, Salix Pharmaceuticals, Bausch Health Companies Inc., Lupin, Norgine, ASKA Pharmaceutical Group, Ltd., Swedish Orphan Biovitrum AB, Umecrine, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatic Encephalopathy Treatment Market Shifts & Advancements
Clinical practice is pivoting toward integrated ammonia management platforms that combine pharmacological intervention with real-time metabolic monitoring. This convergence is redefining competitive differentiation beyond molecule-level efficacy claims.
Next-generation ammonia scavengers are decomposing the traditional acute-versus-chronic therapy binary. These molecules function across inpatient and outpatient settings with tunable dosing profiles. Academic medical centers in the United States are piloting these agents in transitional care protocols. The structural consequence is compressing the addressable market for single-setting legacy formulations.
REACH substance registration requirements are tightening excipient sourcing transparency for European formulations. Manufacturers must now document full supply chain chemical composition for gut-modulating therapies. The oral antibiotic segment faces particular scrutiny due to polymer coating materials. German hospital pharmacies are demanding pre-submitted regulatory dossiers before formulary inclusion.
Integrated service contracts now bundle ammonia-lowering drugs with dietetic counseling and monitoring devices. Hospital procurement departments in Japan are replacing transactional purchasing with episode-based agreements. This restructuring shifts margin capture toward outcome accountability and away from volume-based rebates. Specialist hepatology wards in Tokyo and Osaka are piloting these models first.
Hepatic Encephalopathy Treatment Market Segmentation
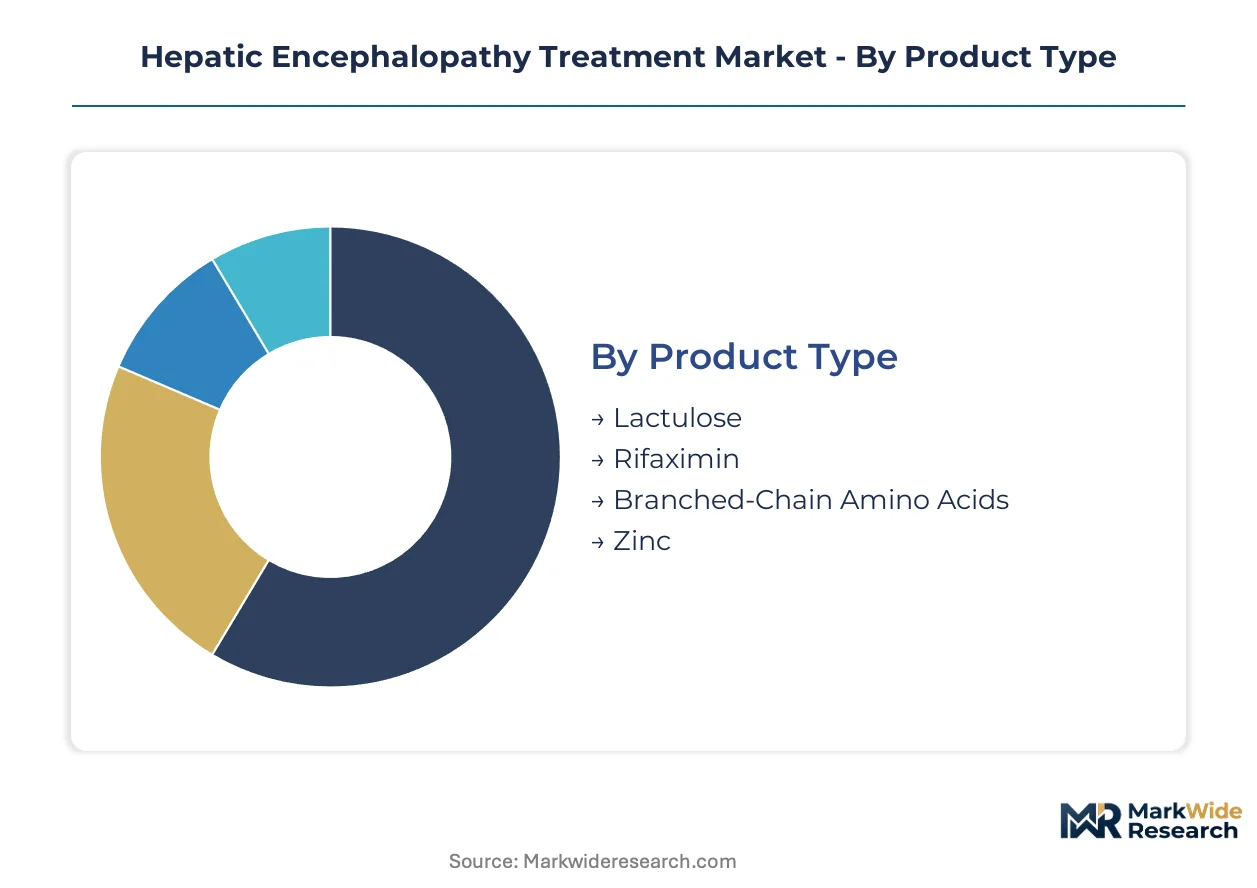
Segmentation in hepatic encephalopathy treatment reveals how regulatory pathways, reimbursement structures, and care settings fragment commercial opportunity. Each dimension carries distinct FDA and EMA evidentiary requirements that reshape manufacturer investment priorities.
Product Type:
FDA orphan-drug designations and EMA conditional marketing authorizations create divergent development timelines across molecular categories.
- Lactulose:Synthetic disaccharide that acidifies colonic contents and traps ammonia as ammonium ions for fecal excretion. Hospital formularies in the United States and Germany favor this first-line agent for acute episode management despite generic saturation eroding manufacturer margins.
- Rifaximin:Minimally absorbed oral antibiotic modulating gut flora to reduce ammonia-producing bacterial load. Recurrent HE prophylaxis protocols in Japanese academic medical centers drive premium positioning where transplant network density supports specialist prescribing.
- Branched-Chain Amino Acids:Nutritional supplementation correcting plasma amino acid imbalances in chronic liver failure.
- Zinc:Trace element cofactor for urea cycle enzymes with variable bioavailability in hepatic impairment.
Established volume favors Lactulose; emerging adoption favors Rifaximin.
End User:
Cost tier stratification separates acute intervention sites from maintenance care settings.
- Hospitals:Gastroenterology departments and intensive care units manage acute HE episodes through infusion-based ammonia-lowering protocols. These facilities capture majority value through episode-based reimbursement structures in Germany and Japan.
- Clinics:Outpatient hepatology practices titrate oral maintenance therapy against West Haven criteria staging.
- Home Care:Ambulatory channels lengthening oral maintenance regimens expand beyond traditional hospital pharmacy capture.
- Long-term Care Facilities:Institutional settings managing cirrhosis patients with recurrent neuropsychiatric episodes.
Margin concentration sits with Hospitals; volume expansion favors Home Care.
Administration Route:
Application urgency dictates route selection across the severity spectrum.
- Oral:Maintenance dosing for chronic HE management and recurrent episode prevention. Patient compliance and titration flexibility drive formulary placement in outpatient settings.
- Intravenous:Rapid ammonia reduction in acute liver failure and grade III-IV encephalopathy. Mallinckrodt's vertically integrated rare-disease infrastructure sustains dominance in this channel.
- Sublingual:Alternative absorption pathway bypassing first-pass hepatic metabolism.
- Rectal:Administration when oral intake is contraindicated in acute decompensation.
Revenue intensity clusters around Intravenous; access expansion favors Oral.
Distribution Channel:
Customer type and procurement sophistication reshape channel economics.
- Retail Pharmacy:Community dispensing of maintenance oral therapies with generic lactulose saturation compressing margin.
- Online Pharmacy:Direct-to-patient fulfillment growing for stable chronic regimens.
- Hospital Pharmacy:Controlled distribution of acute care formulations with integrated ammonia monitoring device bundling emerging in Japanese procurement.
- Wholesalers:Bulk logistics for multi-site health system consolidation.
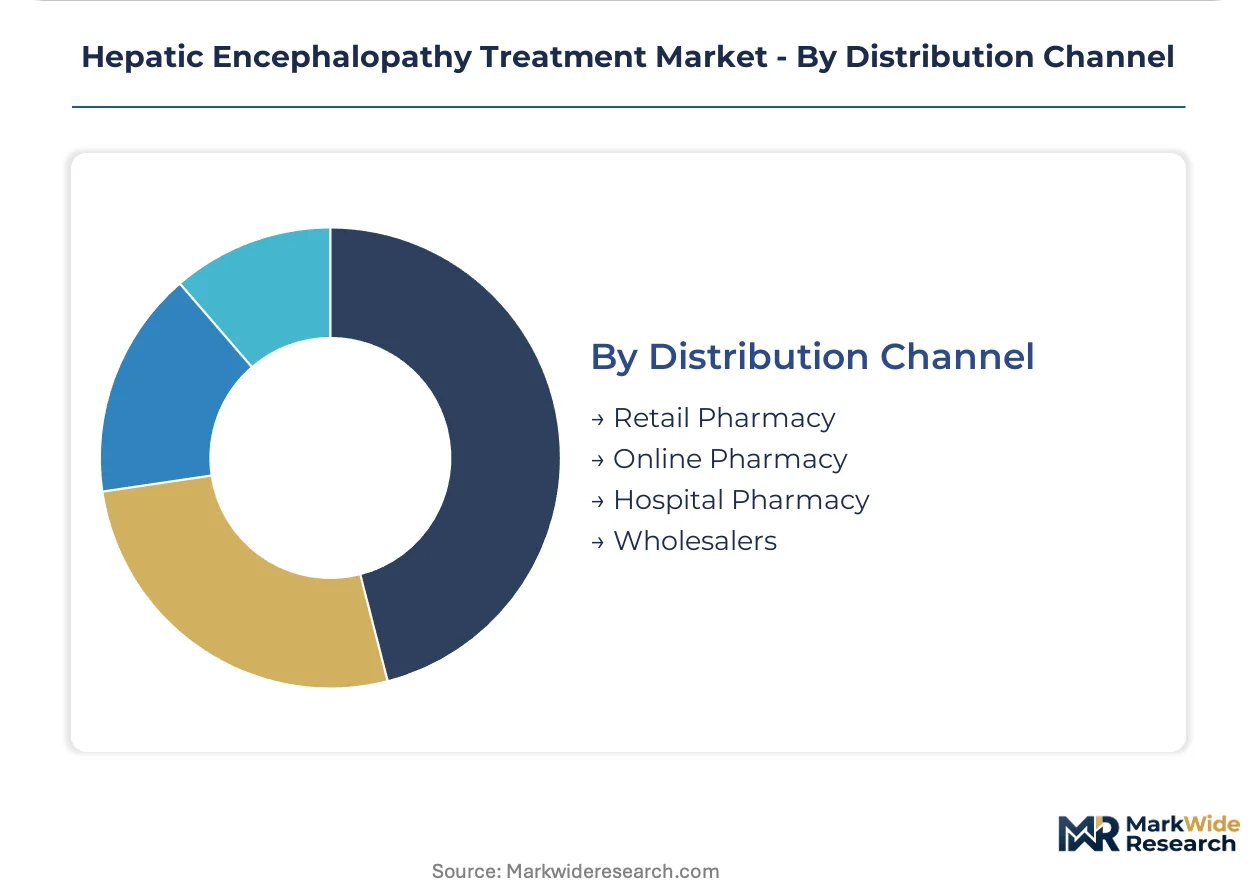
Value capture concentrates in Hospital Pharmacy; convenience positioning favors Online Pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and transplant networks concentrate procurement power for ammonia-lowering therapies. Hospital pharmacy directors in tertiary liver centers negotiate formulary placement against episode-based reimbursement benchmarks.
United States
Specialist hepatology wards at Mayo Clinic Rochester and Mount Sinai New York drive protocol standardization for recurrent HE prophylaxis. FDA orphan-drug designation pathways compress development timelines for novel ammonia scavengers. Integrated delivery networks in Texas and California are piloting bundled payment models that link drug costs to hospitalization avoidance.
Germany
University hospitals in Berlin and Hamburg anchor European adoption of EMA conditional marketing authorizations for acute ammonia management. REACH substance registration requirements tighten excipient sourcing transparency for gut-modulating therapies. The German hospital pharmacy association demands pre-submitted regulatory dossiers before formulary inclusion of polymer-coated oral antibiotics.
Japan
Metropolitan transplant centers in Tokyo and Osaka concentrate patient volumes for premium rifaximin positioning. PMDA guidance on hepatic impairment pharmacokinetics shapes evidentiary requirements for new molecular entities. Episode-based procurement contracts at Keio University Hospital bundle ammonia-lowering drugs with monitoring devices.
United Kingdom
NHS England specialized commissioning frameworks concentrate HE treatment decisions at seven designated liver centers. NICE technology appraisals evaluate preventive oral therapy spend against acute episode costs. The Royal Free London and Birmingham Queen Elizabeth hospitals pilot integrated ammonia management platforms combining pharmacological and metabolic monitoring interventions.
India
CDSCO accelerated approval pathways enable earlier access to generic lactulose formulations for volume-base segment expansion. Tertiary liver centers at All India Institute of Medical Sciences Delhi and Christian Medical College Vellore manage acute decompensation episodes through cost-optimized ammonia-lowering protocols. State government health insurance schemes in Maharashtra and Tamil Nadu increasingly cover chronic HE maintenance regimens.
Hepatic Encephalopathy Treatment Market Competitive Landscape
Player mix skews toward vertically integrated rare-disease specialists and oral therapy formulators with deep academic medical center relationships. The competitive structure concentrates value capture in two channels: intravenous acute management and recurrent prophylaxis maintenance. Three archetypes dominate: ammonia-scavenger developers with orphan-drug infrastructure, disaccharide manufacturers competing on cost position, and minimally absorbed antibiotic specialists commanding premium pricing. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and episode-based contracting with hospital procurement departments.
Within the rare-disease infrastructure tier, Mallinckrodt occupies a position exemplifying captive supply chain control over intravenous ammonia management. Salix Pharmaceuticals and Norgine sit within distinct geographic anchoring strategies—Salix representing deep formulary penetration across United States academic centers, Norgine exemplifying specialized distribution to European hepatology wards. These three entities collectively illustrate how competitive differentiation flows from channel-specific infrastructure rather than molecule-level efficacy alone.
| Leading Market Players |
|---|
| Mallinckrodt |
| Salix Pharmaceuticals |
| Bausch Health Companies Inc. |
| Lupin |
| Norgine |
| ASKA Pharmaceutical Group, Ltd. |
| Swedish Orphan Biovitrum AB |
| Umecrine |
| AbbVie |
| Others |
Supply & Pricing Matrix
API sourcing substitution from Indian contract manufacturers to European captive facilities simultaneously reshapes supply geography and pricing economics for ammonia scavengers, compressing margin structures for oral therapy producers while elevating cost bases for intravenous formulations. This geographic rebalancing forces compounders to absorb REACH compliance costs or cede hospital formulary slots to vertically integrated competitors.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers indexed to European chemical feedstock benchmarks dominate procurement for intravenous ammonia scavengers. Three-tier pricing structure across premium, standard, and economy levels separates Mallinckrodt's orphan-drug infrastructure from Salix's formulary-controlled oral segment and generic lactulose compounders. Pricing pressure stems from generic saturation in the volume-base segment, forcing established manufacturers toward episode-based contracting. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement structures, while retail pharmacy channels face acute margin compression.
Supply Chain Analysis
Inbound logistics costs through Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate working capital requirements for gut-modulating therapy manufacturers. Active pharmaceutical ingredient supply concentrates in India, China, and Switzerland, with branched-chain amino acid precursors drawing from fermentation facilities in South Korea and Japan. Single-source vulnerability in polymer coating materials for rifaximin formulations creates formulation bottlenecks. Distribution runs through hospital pharmacy controlled channels for acute care, with home-care routes expanding through specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated service contracts bundling ammonia-lowering drugs with metabolic monitoring devices represent a service-attach opportunity expanding faster than molecule sales alone. Hospital procurement departments in Japan and Germany are replacing transactional purchasing with episode-based agreements that shift margin capture toward outcome accountability.
For Market Incumbents: Compound formulary control through backward integration into GMP-certified active pharmaceutical ingredient production, securing supply against REACH-driven excipient transparency requirements. Defend hospital pharmacy slots by embedding ammonia monitoring devices within procurement contracts, neutralizing price competition from generic lactulose compounders. Mallinckrodt's rare-disease infrastructure exemplifies this captive supply model.
For New Entrants and Emerging Players: Anchor in home-care route expansion for oral maintenance regimens, where formulary barriers are lower and patient compliance monitoring creates recurring revenue attachment. Target ambulatory hepatology practices in United States integrated delivery networks with transitional care protocols bridging acute and chronic management. Pursue EMA conditional marketing authorization pathways to accelerate European market access ahead of FDA hepatic impairment pharmacokinetics requirements.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated rare-disease specialists with orphan-drug infrastructure over standalone formulation plays. Long-term viability across the projection horizon hinges on episode-based contracting capabilities and diagnostic-therapy bundling expertise. Monitor PMDA guidance evolution on hepatic impairment pharmacokinetics as the signal for Japanese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan-Drug Infrastructure Acquisition | Captive GMP-certified API supply secures hospital formulary positioning against REACH compliance failures. |
| Episode-Based Contracting Pilot | Japanese university hospitals bundle ammonia scavengers with monitoring devices, shifting margin to outcomes. |
| EMA Conditional Marketing Authorization | Accelerated European access for novel ammonia scavengers precedes FDA hepatic impairment requirements. |
| Home-Care Distribution Partnership | Specialized distributors for oral maintenance regimens bypass saturated retail pharmacy channels. |
| Diagnostic-Therapy Bundling | Real-time ammonia monitoring integration with drug procurement contracts locks in hospital pharmacy slots. |
Research Methodology
Cross-validation between formulary database analysis and hospital procurement contract reviews anchors the qualitative findings on episode-based reimbursement evolution. Primary interviews with hepatology department heads, hospital pharmacy directors, regulatory affairs leads at ammonia-scavenger developers, and payer access specialists combined with secondary validation from FDA orphan-drug designations, EMA conditional marketing authorization records, ClinicalTrials.gov entries, and PMDA guidance documents. Bottom-up patient volume modeling and top-down pharmaceutical spending triangulation established market sizing boundaries.
Sensitivity analysis on ammonia-lowering protocol adoption rates and generic lactulose penetration shapes the forecast framework across the projection horizon. Segmentation dimensions modeled include product type, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from epidemiological projections for cirrhosis prevalence and hospitalization cost elasticity analysis. Forecast inputs incorporate West Haven criteria severity staging heterogeneity and transplant network density variations.
Underlying assumptions cover stable FDA and EMA evidentiary requirements, with deviation risk concentrated in hepatic impairment pharmacokinetics guidance updates and REACH substance registration enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Hunter Syndrome Treatment Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market