
 Wilms Tumor Treatment Market | 2026-2036
Wilms Tumor Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Wilms Tumor Treatment Market Analytics
Good Manufacturing Practice certification for pediatric oncology biologics is redrawing competitive boundaries in nephroblastoma therapy supply. Pfizer Inc. leverages its vertically integrated oncology manufacturing network to sustain consistent supply of platinum-based chemotherapies. Novartis AG anchors its position through specialized pediatric formulation capabilities that differentiate it from generic competitors. Bristol-Myers Squibb Company competes via concentrated investment in immuno-oncology platforms applicable to rare pediatric malignancies.
Wilms tumor treatment encompasses multimodal therapeutic interventions targeting nephroblastoma, the most common renal malignancy in children, typically involving surgical resection combined with adjuvant chemotherapy regimens based on vincristine, dactinomycin, and doxorubicin. The primary purpose centers on achieving complete tumor eradication while preserving renal function and minimizing long-term cardiotoxicity in developing patients. Chemotherapy dominates current revenue pools due to established protocol adherence across cooperative oncology groups, while targeted therapy represents the fastest-expanding segment as kinase inhibitors demonstrate efficacy in relapsed cases. Intravenous delivery mode maintains structural priority in hospital settings, though oral formulations are gaining traction in maintenance phases to reduce inpatient burden.
The FDA's pediatric investigational plan requirements and EMA's pediatric regulation framework collectively shape clinical trial design and market entry pathways for novel Wilms tumor therapies. The National Cancer Institute's Children's Oncology Group protocol standards further dictate treatment algorithms that manufacturers must align with to achieve formulary placement. Stakeholders must monitor biomarker-driven stratification trials that could resegment first-line therapy selection criteria.
Market Dynamics
The Wilms tumor treatment landscape is being fundamentally altered by biomarker-driven stratification trials that are resegmenting first-line therapy selection criteria across cooperative oncology groups. These precision-medicine protocols are compressing the historical dominance of standardized chemotherapy regimens and creating new competitive entry points for targeted agents.
Growth Catalysts
- FDA Pediatric Oncology Drug Development Pathway:This accelerated approval mechanism shortens time-to-market for novel nephroblastoma therapies, incentivizing manufacturer investment in rare pediatric malignancy pipelines.
- Children's Oncology Group Protocol Standardization:Harmonized treatment algorithms across North American pediatric cancer centers create predictable demand volumes for aligned therapeutic formulations.
- Japan's Clustering of Specialized Pediatric Cancer Centers:Concentrated expertise in Tokyo, Osaka, and Nagoya generates referral gravity that sustains high-volume utilization of advanced nephroblastoma interventions.
Market Restraints
- Platinum Supply Concentration:Cisplatin and carboplatin production depends on concentrated South African and Russian mining operations, exposing chemotherapy supply chains to geopolitical disruption risk.
- EMA Pediatric Investigation Plan Requirements:Mandatory pediatric study obligations for adult oncology drugs create regulatory friction that delays label expansion into nephroblastoma indications.
- Cardiotoxicity Surveillance Burden:Mandatory long-term echocardiographic monitoring for doxorubicin-exposed survivors imposes persistent cost structures on healthcare systems and families.
Strategic Opportunities
- Oral Formulation Development:Maintenance-phase oral chemotherapy alternatives to intravenous delivery reduce inpatient burden and open ambulatory care channel expansion.
- Relapsed/Refractory Kinase Inhibitor Positioning:Targeted therapy development for WT1-mutant and anaplastic histology subsets addresses unmet need in salvage settings.
- Germany's Pediatric Cancer Center Network:Dense concentration of specialized nephroblastoma treatment capacity in Heidelberg, Hamburg, and Berlin creates partnership opportunities for protocol-aligned manufacturers.
Industry Challenges
- Pediatric Formulation Manufacturing Complexity:Age-appropriate dosing flexibility and palatability requirements demand specialized production capabilities that generic manufacturers rarely maintain.
- Multi-Stakeholder Protocol Adherence:Cooperative group trial enrollment, institutional review board coordination, and family consent processes create execution complexity for novel therapy integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wilms Tumor Treatment Market |
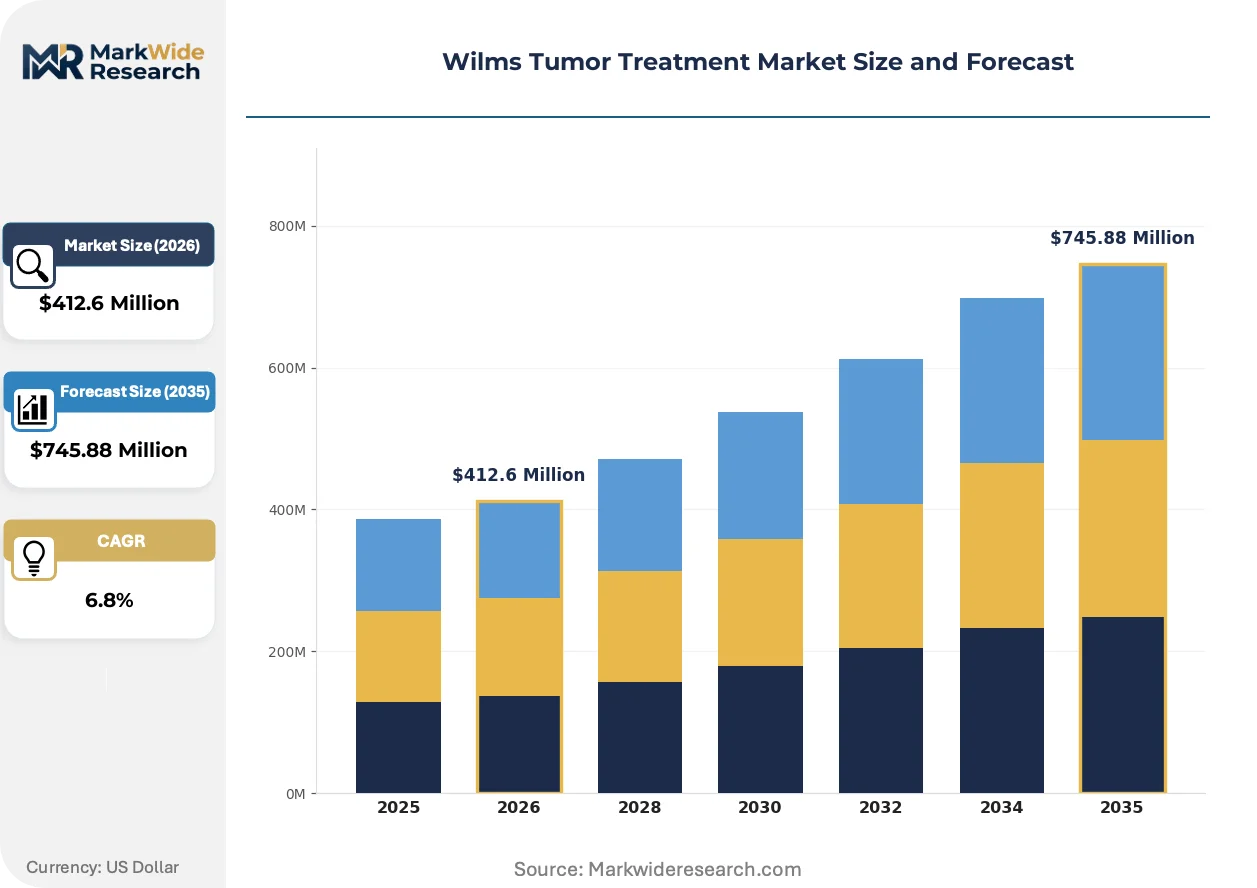
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Radiation Therapy, Targeted Therapy Delivery Mode: Intravenous, Oral, Intramuscular, Local End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Age Group: Children, Adolescents, Young Adults, Others |
| Companies Covered | Pfizer Inc., Amneal Pharmaceuticals LLC, Teva Pharmaceuticals Limited, Sandoz International GmbH, Fresenius Kabi AG, Merck & Co. Inc., Bristol-Myers Squibb Company, Novartis AG, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wilms Tumor Treatment Market Evolving Landscape
Liquid biopsy technologies and minimal residual disease monitoring are compressing the timeline for treatment response assessment in nephroblastoma management. These innovations are shifting decision-making from radiographic endpoints to molecular surveillance, with significant implications for therapy duration and intensity modulation.
Next-generation sequencing panels for Wilms tumor molecular subtyping are miniaturizing the diagnostic pathway from tissue acquisition to risk stratification. Pediatric oncology departments at institutions including St. Jude Children's Research Hospital and Boston Children's Hospital are adopting rapid turnaround protocols. This compression is enabling earlier escalation to intensified regimens or de-escalation to reduce toxicity exposure.
EMA's pediatric regulation framework is mandating earlier and more comprehensive pediatric investigation plans for oncology drug developers. Manufacturers must now submit pediatric study designs concurrently with adult Phase I initiation, not post-approval. Small-molecule developers targeting renal malignancies are responding by embedding nephroblastoma cohorts into basket trial designs to satisfy regulatory obligations.
Hospital-at-home programs for low-risk nephroblastoma maintenance are displacing traditional inpatient chemotherapy administration in select pediatric cancer centers. Home infusion nursing services and remote patient monitoring platforms are substituting for bed-based care in vincristine and dactinomycin cycles. This channel shift is most visible in United States academic medical centers with established pediatric home health infrastructure.
Wilms Tumor Treatment Market Segmentation
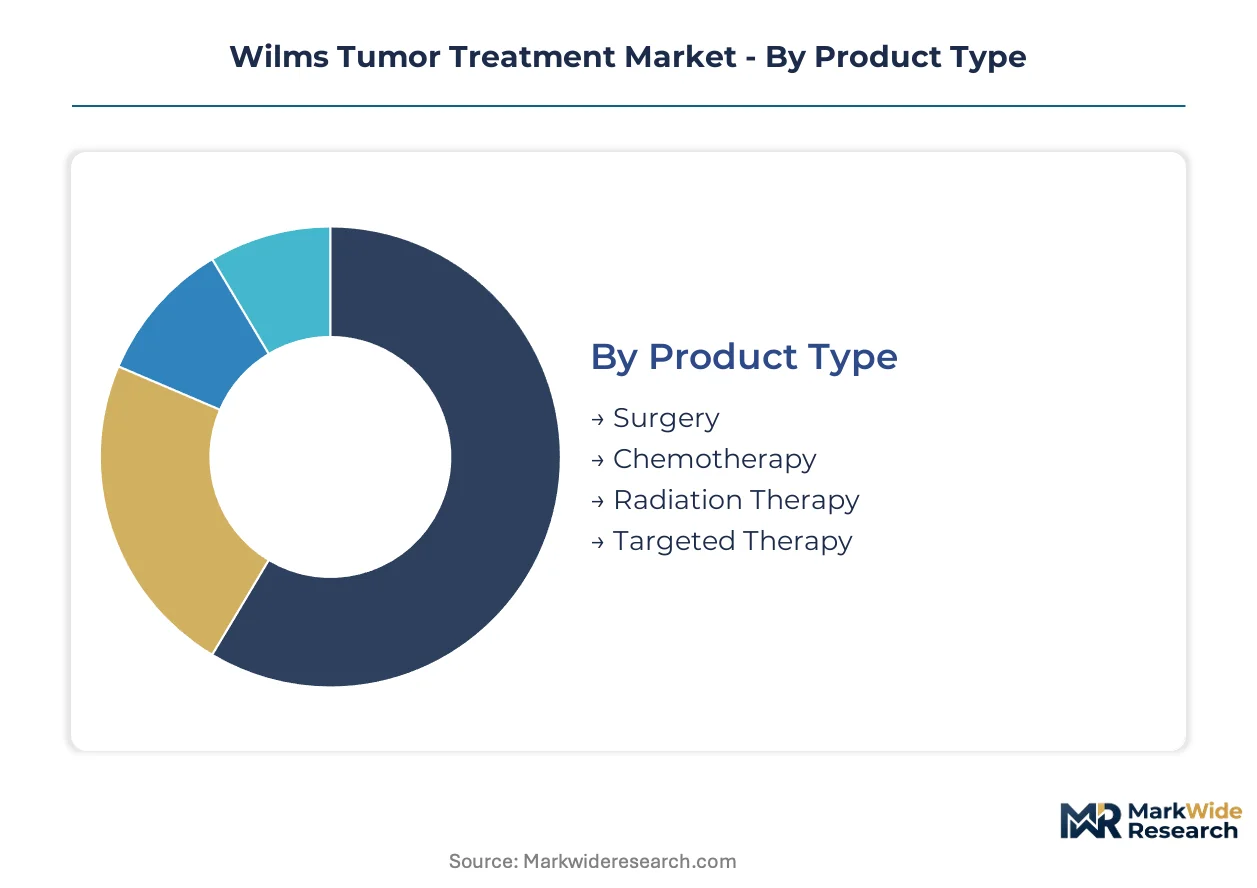
Wilms tumor treatment segmentation reveals how therapeutic modalities, delivery infrastructure, and patient demographics intersect to shape procurement patterns across pediatric oncology networks. Manufacturers must align formulation development with the specific requirements of hospital-based acute care versus emerging ambulatory channels.
Product Type:
Geographic demand for nephroblastoma interventions concentrates in domestic markets where specialized pediatric cancer centers cluster, while export-led segments serve markets building treatment capacity through international cooperative protocols.
- Surgery:Nephrectomy and nephron-sparing procedures constitute the foundational curative intervention, typically performed at regional referral centers in the United States, Germany, and Japan. Demand concentrates in academic medical centers with dedicated pediatric urology and surgical oncology teams, driven by protocol mandates for complete resection prior to chemotherapy initiation.
- Chemotherapy:Platinum-based regimens combining vincristine, dactinomycin, and doxorubicin generate the dominant revenue pool across North American and European treatment networks. Procurement volumes track Children's Oncology Group protocol enrollment, with supply security concerns elevated due to concentrated cisplatin precursor mining.
- Radiation Therapy:Adjuvant radiotherapy targets flank and whole-lung fields for anaplastic histology and metastatic presentations. Utilization concentrates in proton and photon centers affiliated with major pediatric hospitals.
- Targeted Therapy:Kinase inhibitors for relapsed WT1-mutant and anaplastic subsets address salvage settings where conventional regimens fail. Development pipelines focus on basket trial designs satisfying FDA and EMA pediatric investigation requirements.
Chemotherapy holds the largest share; momentum sits with targeted therapy.
Delivery Mode:
Cost tier differentiation separates acute inpatient administration from emerging ambulatory alternatives that reduce healthcare system burden and family displacement.
- Intravenous:Hospital-based infusion dominates induction and intensification phases, requiring central line access and cardiac monitoring capabilities. United States pediatric oncology departments maintain structural priority for IV delivery in St. Jude and Dana-Farber affiliated networks.
- Oral:Maintenance-phase oral formulations of chemotherapy agents are gaining traction in low-risk nephroblastoma protocols. Germany's dense pediatric cancer center network in Heidelberg and Hamburg pilots home administration programs to displace inpatient bed utilization.
- Intramuscular:Limited application for specific supportive care agents in resource-constrained settings without vascular access infrastructure.
- Local:Intratumoral or regional delivery modalities remain investigational within early-phase clinical trials.
Intravenous delivery commands current volumes; oral alternatives are climbing the fastest.
End User:
Customer type segmentation maps procurement authority from consolidated hospital systems to fragmented home health providers with divergent technical requirements.
- Hospitals:Tertiary pediatric centers with dedicated oncology units manage complex multimodal protocols and long-term survivorship surveillance. Japan's clustering in Tokyo, Osaka, and Nagoya generates concentrated high-volume demand.
- Oncology Clinics:Specialized outpatient facilities handle maintenance therapy and surveillance imaging for stabilized patients.
- Research Institutions:St. Jude Children's Research Hospital and Boston Children's Hospital drive biomarker-driven stratification trials that reshape first-line selection criteria.
- Home Care:Emerging channel for low-risk maintenance administration supported by remote monitoring platforms and infusion nursing services in United States academic medical centers with established pediatric home health infrastructure.
Hospitals retain the dominant procurement position; home care represents the steepest expansion trajectory.
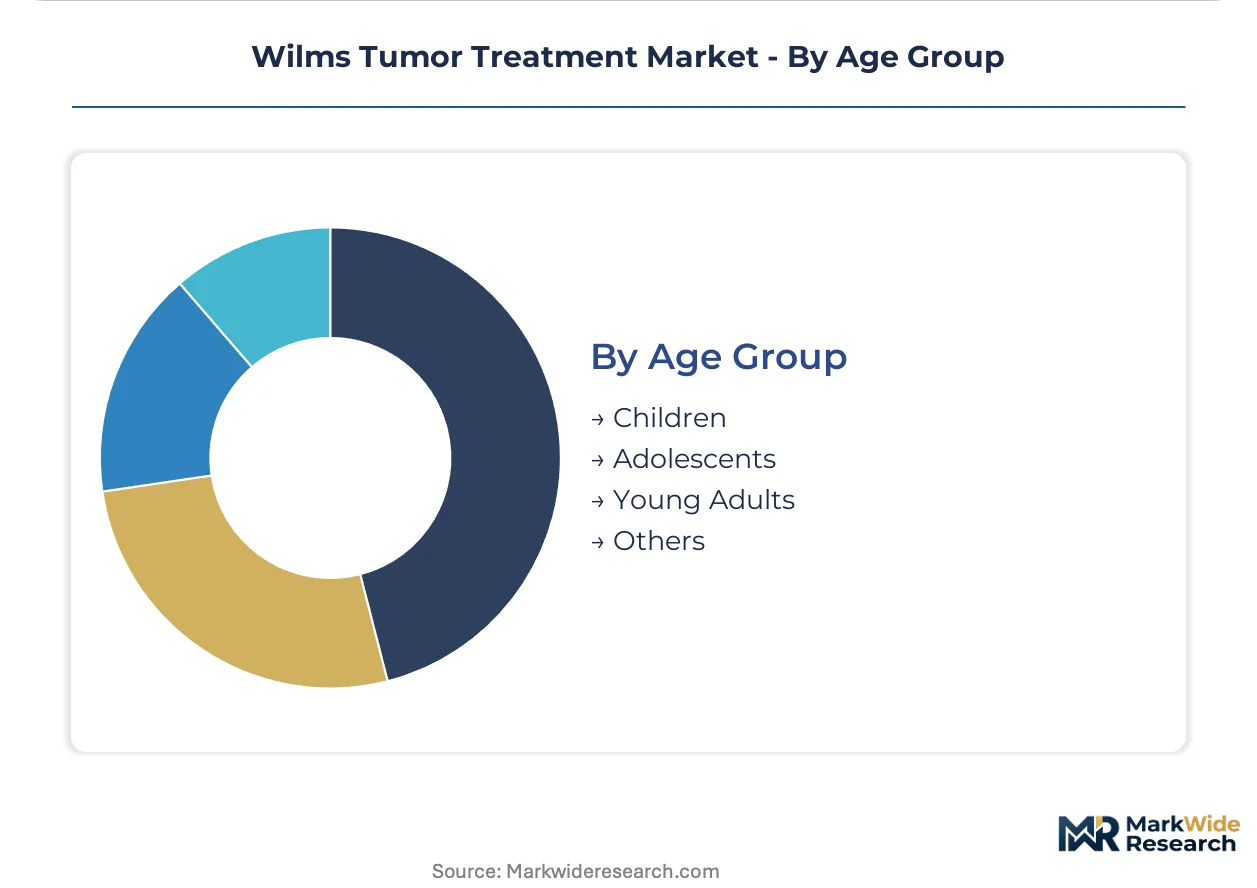
Age Group:
Application focus varies across developmental stages, with formulation requirements and dosing complexity scaling with patient age and physiological maturity.
- Children:Peak incidence occurs in children aged 3-4 years, driving demand for age-appropriate dosing flexibility and palatable oral formulations. FDA's pediatric oncology drug development pathway prioritizes this demographic.
- Adolescents:Transitional care requirements bridge pediatric and adult oncology protocols, complicating trial enrollment and long-term follow-up coordination.
- Young Adults:Rare presentations in this cohort often default to adult renal cell carcinoma protocols with limited nephroblastoma-specific evidence.
- Others:Neonatal and adult presentations constitute edge cases managed through individualized treatment planning.
Children capture the predominant clinical focus; adolescents present the most complex care coordination challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric oncology departments in the United States, Germany, and Japan concentrate specialized nephroblastoma treatment capacity. Referral gravity clusters around academic medical centers with dedicated surgical oncology and nephrology teams.
United States
St. Jude Children's Research Hospital and Dana-Farber Cancer Institute anchor multimodal protocol development and biomarker-driven stratification trials. FDA's pediatric oncology drug development pathway accelerates novel therapy approvals through priority review vouchers. Philadelphia, Memphis, and Boston generate concentrated demand for platinum-based chemotherapy and targeted salvage agents.
Germany
Heidelberg University Hospital, Hamburg-Eppendorf Medical Center, and Charité Berlin sustain Europe's densest pediatric cancer center network for nephroblastoma management. EMA's pediatric investigation plan requirements shape clinical trial design for label expansion into Wilms tumor indications. The German Childhood Cancer Registry enables rapid protocol iteration across 46 specialized treatment units.
Japan
National Center for Child Health and Development in Tokyo, Osaka University Hospital, and Nagoya University Hospital concentrate national expertise in nephroblastoma surgery and adjuvant therapy. PMDA's sakigake designation system expedites access to innovative pediatric oncology drugs. The Japanese Pediatric Oncology Group standardizes treatment algorithms across 15 regional core hospitals.
United Kingdom
Great Ormond Street Hospital and Royal Marsden NHS Foundation Trust coordinate the UK Children's Cancer Study Group nephroblastoma trials. MHRA's pediatric regulation framework aligns with EMA requirements for concurrent pediatric study submission. London, Manchester, and Birmingham academic centers drive maintenance-phase oral formulation pilots.
Canada
The Hospital for Sick Children in Toronto and BC Children's Hospital anchor C17 Council pediatric oncology network coordination for nephroblastoma management. Health Canada's pediatric drug development guidance supports accelerated review pathways for rare pediatric malignancies. Montreal and Calgary centers participate in COG protocol harmonization for cross-border trial enrollment.
Wilms Tumor Treatment Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical conglomerates with established oncology manufacturing networks and specialized pediatric formulation capabilities. Tiered competitive structure separates GMP-certified biologics manufacturers from generic chemotherapy suppliers. Strategic archetypes include platinum-based chemotherapy specialists, kinase inhibitor developers for relapsed settings, and immuno-oncology platform investors. Dominant competitive moves encompass backward integration into active pharmaceutical ingredient supply and partnership formation with cooperative oncology groups for protocol alignment.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novartis AG occupy positions as archetypal oncology manufacturers with dedicated pediatric capabilities. Bristol-Myers Squibb Company exemplifies the immuno-oncology investment pattern applicable to rare pediatric malignancies. Sandoz International GmbH and Fresenius Kabi AG represent generic and hospital-focused supply specialists respectively. Teva Pharmaceuticals Limited and Amneal Pharmaceuticals LLC sit within the multisource chemotherapy segment serving maintenance-phase demand.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Amneal Pharmaceuticals LLC |
| Teva Pharmaceuticals Limited |
| Sandoz International GmbH |
| Fresenius Kabi AG |
| Merck & Co. Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
Good Manufacturing Practice certification for pediatric oncology biologics gates both supply qualification and price differentiation simultaneously, separating GMP-certified manufacturers from generic chemotherapy suppliers while compressing margins for non-certified entrants unable to meet FDA and EMA pediatric formulation standards.
Pricing Analysis
Cost-plus contracts with platinum price indexation dominate procurement for cisplatin and carboplatin regimens across North American pediatric oncology networks. Three-tier pricing structure across premium, standard, and economy levels separates patented kinase inhibitors from branded chemotherapies and multisource generics. Pricing pressure stems from concentrated South African and Russian platinum mining exposing contracts to commodity volatility. Hospital procurement committees exhibit highest price sensitivity for maintenance-phase oral formulations, while research institutions prioritize protocol alignment over unit cost.
Supply Chain Analysis
South Africa and Russia anchor platinum group metal extraction for cisplatin precursor supply, with India and China feeding active pharmaceutical ingredient synthesis for vincristine and dactinomycin. Manufacturing draws from concentrated mining operations and specialized fermentation capacity for microbial-derived oncology agents. Single-source vulnerability in platinum concentrate refining exposes chemotherapy supply chains to geopolitical disruption. Distribution runs through hospital-based pharmacy networks and specialized pediatric oncology wholesalers with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker-driven stratification trials are compressing standardized chemotherapy dominance, creating high-growth disruption as WT1-mutant and anaplastic histology subsets open targeted therapy entry points.
For Market Incumbents: Secure backward integration into platinum group metal sourcing to buffer against South African and Russian supply concentration. Anchor formulary position through Children's Oncology Group protocol alignment and pediatric formulation capability investment. Defend against kinase inhibitor displacement by embedding biomarker-driven cohorts into existing trial infrastructure.
For New Entrants and Emerging Players: Maintenance-phase oral formulation gaps in Germany's dense pediatric cancer center network offer white-space penetration before incumbent oral programs mature. Target relapsed/refractory WT1-mutant subsets where no approved targeted therapy exists. Pursue EMA pediatric investigation plan compliance as the primary go-to-market credential.
For Investors and Strategic Acquirers: FDA's pediatric oncology drug development pathway reshapes the acquisition landscape by shortening time-to-market for rare pediatric malignancy assets. Five-to-ten-year viability favors developers with concurrent adult and pediatric trial designs. Signal to monitor: PMDA sakigake designation awards indicating Japanese regulatory prioritization of nephroblastoma pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | GMP certification for age-appropriate dosing separates qualified suppliers from generic competitors in EMA-regulated markets. |
| Biomarker-Driven Trial Design | WT1-mutant cohort embedding satisfies FDA pediatric investigation requirements while opening salvage therapy positioning. |
| Platinum Supply Security | Upstream control over South African and Russian concentrate sourcing mitigates chemotherapy production disruption risk. |
| Hospital-at-Home Program Partnership | Home infusion nursing alliances with St. Jude and Dana-Farber networks displace inpatient bed utilization for maintenance phases. |
| Cooperative Group Alignment | Children's Oncology Group protocol adherence secures predictable demand volumes across North American pediatric centers. |
Research Methodology
Operator-level perspectives from pediatric oncologists, hospital pharmacy directors, regulatory affairs specialists, and formulary committee chairs anchored the qualitative base. Primary interviews combined with secondary validation from FDA pediatric oncology filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov biomarker-driven trial registries, and Children's Oncology Group protocol documentation. Bottom-up demand modeling across treatment lines, dosage forms, and regional regulatory clusters triangulated against top-down pharmaceutical procurement database analysis.
Sensitivity analysis tested forecast robustness across platinum price volatility scenarios and pediatric regulatory pathway acceleration assumptions. Segmentation dimensions modeled encompassed product type, delivery mode, end user, and age group across the projection horizon. CAGRs derived from protocol enrollment trajectories, biomarker prevalence estimates, and formulation adoption curves in maintenance-phase settings.
Underlying assumptions cover cooperative group trial adherence rates and regulatory pathway timelines, with deviation risk concentrated in platinum supply disruption and biomarker stratification protocol adoption speed. Recalibration cycles align with material shifts in FDA pediatric priority review voucher awards and EMA pediatric investigation plan submission patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Asbestosis Treatment Market