
 Acute Intermittent Porphyria Market | 2026-2036
Acute Intermittent Porphyria Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Intermittent Porphyria Market Analysis
The specialized clinical genetics workforce is rotating toward rare metabolic disease programs as academic medical centers expand porphyria fellowship tracks. Alnylam Pharmaceuticals leverages RNA interference platforms to sustain leadership in givosiran-based maintenance therapy. Recordati Rare Diseases anchors European distribution through its heme arginate supply chain for acute attack management.
Acute intermittent porphyria constitutes a hepatic disorder arising from porphobilinogen deaminase deficiency, characterized by accumulation of porphyrin precursors that trigger neurovisceral attacks; therapeutic intervention centers on heme replacement, ALA synthase inhibition, and symptom control. Givosiran dominates long-term maintenance segments by suppressing aminolevulinic acid synthase 1, while intravenous heme arginate retains primacy in acute attack management due to rapid cytochrome restoration. Subcutaneous administration routes are gaining traction in homecare settings as patients seek to reduce hospital dependency.
FDA orphan drug exclusivity and EMA rare disease designation frameworks shape development economics by extending market protection and streamlining clinical trial requirements for ultra-rare indications. The EU F-Gas Regulation and US EPA manufacturing standards constrain production site selection for heme-based therapies, concentrating supply among qualified facilities. Japan's PMDA Sakigake designation accelerates local access timelines for novel porphyria interventions. Stakeholders must monitor evolving payer evidence requirements for gene therapy candidates entering late-stage development.
Market Dynamics
RNA interference platforms are restructuring therapeutic development economics by compressing clinical timelines and redirecting specialty clinic investment toward metabolic disease infrastructure. This molecular modality is displacing conventional enzyme replacement strategies in maintenance therapy segments.
Growth Catalysts
- Orphan Drug Incentives:FDA exclusivity extensions and EMA rare disease protocols accelerate trial design and reduce regulatory friction for ultra-rare hepatic disorders.
- Specialty Clinic Networks:Academic medical centers in the United States, Germany, and Japan are establishing dedicated porphyria fellowship tracks that concentrate diagnostic expertise.
- Subcutaneous Administration:Homecare delivery routes reduce hospital dependency and expand addressable patient populations beyond tertiary care centers.
Market Restraints
- Heme Supply Concentration:EU F-Gas Regulation and US EPA manufacturing standards constrain qualified production sites to a handful of specialized facilities.
- Diagnostic Latency:Porphobilinogen deaminase deficiency requires specialized genetic testing that many regional hospitals cannot perform, delaying treatment initiation.
- Reimbursement Complexity:Ultra-rare disease coding gaps in national health systems create prior authorization friction for novel RNA therapeutics.
Strategic Opportunities
- Gene Therapy Pipelines:Late-stage candidates targeting hepatic porphyrin metabolism could capture curative-intent positioning ahead of chronic maintenance paradigms.
- Japan Sakigake Pathway:PMDA accelerated review timelines enable first-molecule advantage in Asian markets with established rare disease infrastructure.
- Integrated Care Models:Telemedicine-linked specialty clinics in rural United States regions address geographic access barriers for attack-prone patients.
Industry Challenges
- Clinical Genetics Workforce Gap:Fellowship-trained metabolic specialists remain concentrated at academic centers, limiting community hospital diagnostic capacity.
- Biomanufacturing Scale-Up:RNA synthesis and lipid nanoparticle formulation require capital-intensive facilities with limited contract manufacturing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Intermittent Porphyria Market |
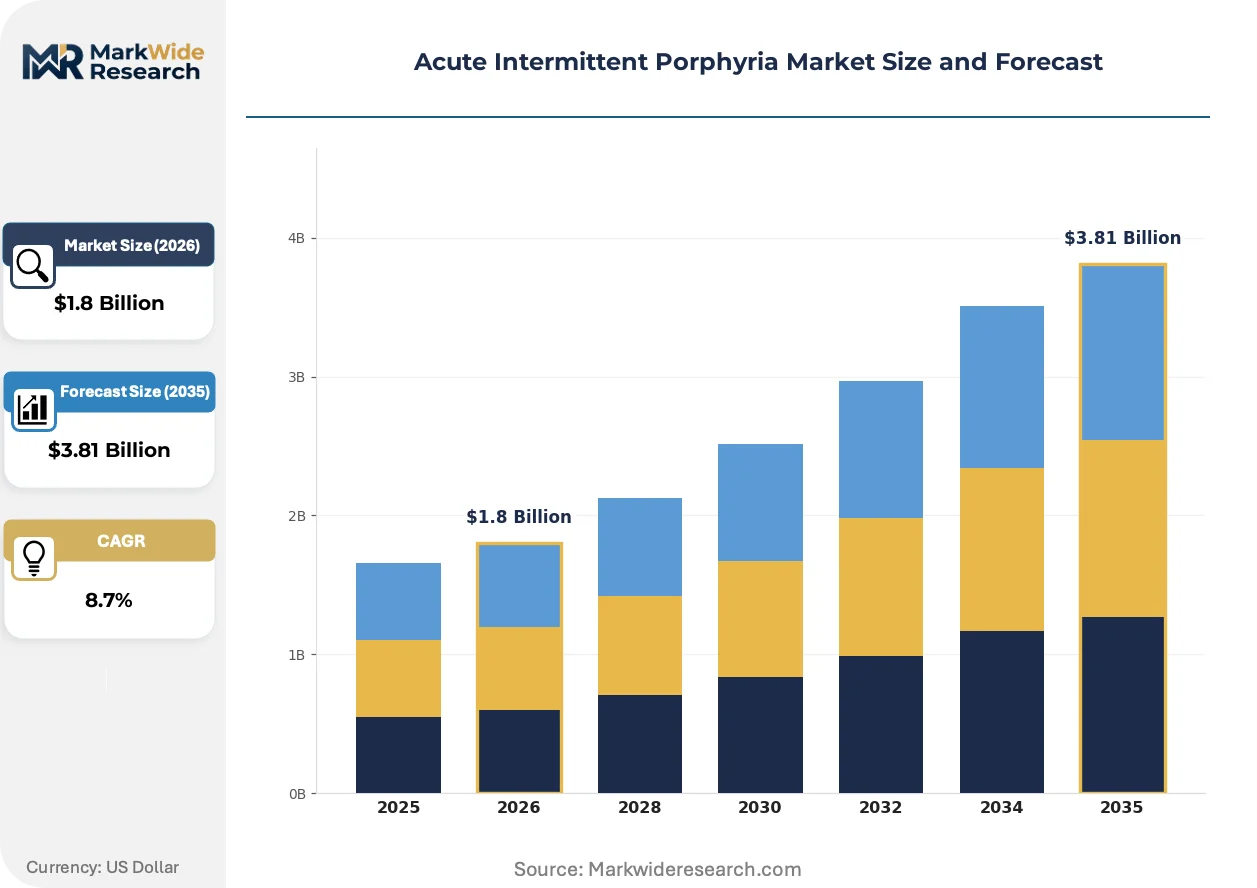
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protoporphyrin, Heme Arginate, Givosiran, Other Therapies End User: Hospitals, Specialty Clinics, Homecare Settings, Ambulance Services Treatment Stage: Acute Attack Management, Long-term Maintenance, Preventive Care, Follow-up Treatment Drug Administration Route: Intravenous, Oral, Subcutaneous, Other Routes |
| Companies Covered | Alnylam Pharmaceuticals, Recordati Rare Diseases, Mitsubishi Tanabe Pharma Corporation, CLINUVEL PHARMACEUTICALS LTD, Pfizer, Bristol-Myers Squibb, Horizon Therapeutics, Dicerna Pharmaceuticals, Moderna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Intermittent Porphyria Market Emerging Trajectories
Therapeutic modality competition is intensifying as RNA platforms mature and gene editing approaches enter clinical validation. Regulatory frameworks are adapting to accommodate single-patient trial designs and real-world evidence requirements.
RNA interference technology is bifurcating the maintenance therapy landscape between chronic suppression and curative intervention timelines. Specialty clinics in the United States and Germany are adopting subcutaneous givosiran protocols for stable patients, while reserving intravenous heme arginate for acute attack rescue. This modality split is compressing hospital admission frequency and reallocating reimbursement toward outpatient drug administration.
EMA's F-Gas Regulation and US EPA manufacturing standards are tightening environmental compliance for heme-based production, forcing supply chain consolidation among qualified European and North American facilities. The regulatory burden is elevating qualification costs for new market entrants. Heme arginate suppliers are responding by securing multi-year manufacturing agreements with academic medical center networks.
Patient advocacy organizations are reshaping trial recruitment and endpoint design by demanding attack-frequency reduction over biomarker substitution. United States-based specialty clinics are integrating patient-reported outcome measures into standard care protocols. This behavioral shift is visible most acutely in Germany, where national health technology assessment bodies now require quality-of-life data for orphan drug reimbursement decisions.
Acute Intermittent Porphyria Market Segmentation
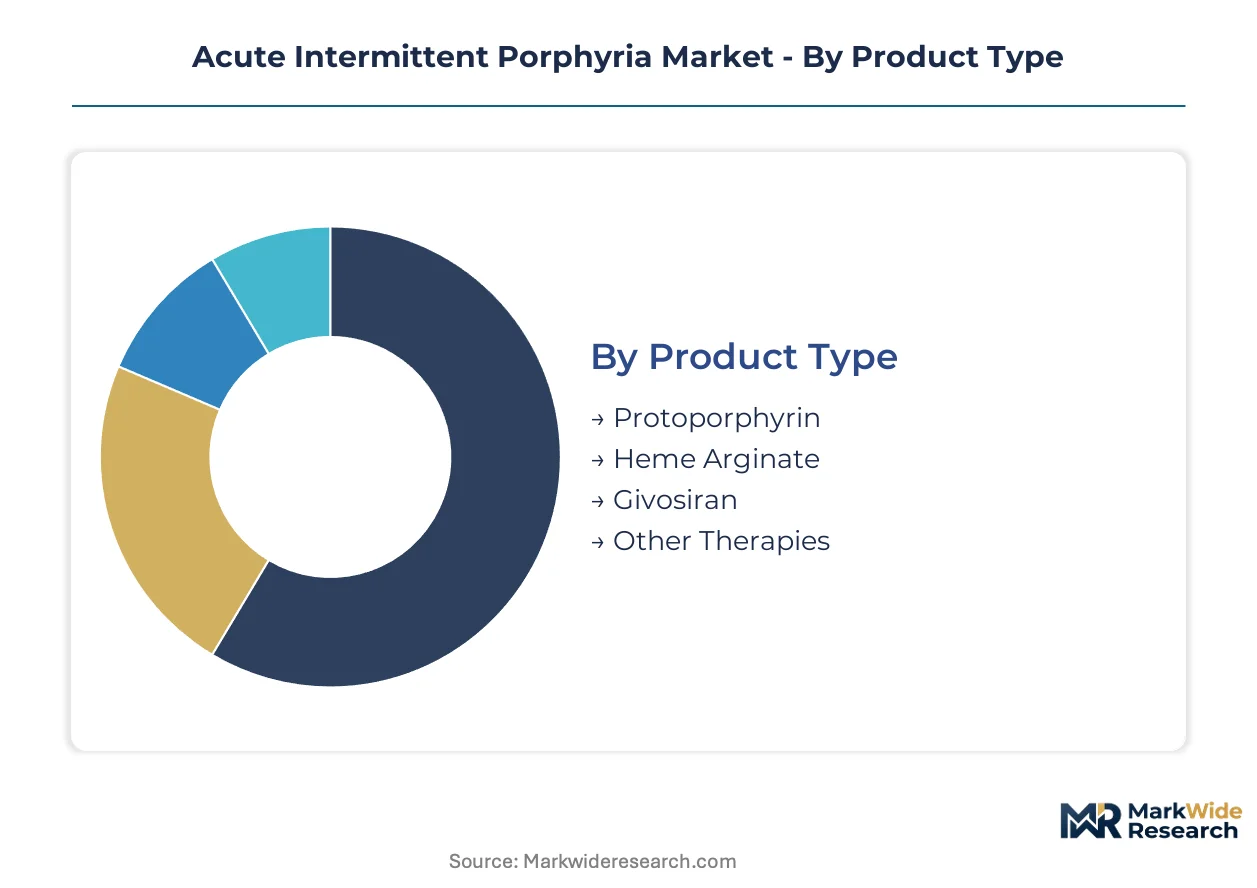
Therapeutic modality splits in acute intermittent porphyria create distinct margin pools based on treatment setting, administration complexity, and reimbursement tier. RNA-based maintenance therapies command premium positioning against rescue heme formulations, while homecare delivery routes are compressing hospital admission economics.
Product Type:
Margin concentration tracks toward chronic suppression agents with patent-protected mechanisms, while acute rescue formulations face manufacturing qualification barriers that limit competitive entry.
- Givosiran:RNA interference agent suppressing hepatic ALA synthase 1 expression through subcutaneous delivery. Specialty clinics in the United States and Germany are expanding fellowship-trained metabolic programs to manage patient selection and monitoring protocols for this maintenance therapy.
- Heme Arginate:Intravenous heme formulation restoring cytochrome synthesis during acute neurovisceral attacks. Recordati Rare Diseases maintains European supply chain dominance through qualified manufacturing agreements with academic medical center networks constrained by EMA F-Gas Regulation compliance requirements.
- Protoporphyrin:Photodynamic precursor with limited therapeutic application in erythropoietic porphyria variants rather than acute intermittent forms.
- Other Therapies:Symptomatic management agents including analgesics, antiemetics, and hydration protocols deployed as adjunctive care.
The dominant share belongs to Givosiran, while Heme Arginate retains critical infrastructure positioning despite slower volume expansion.
End User:
Patient acuity and reimbursement authorization complexity determine site-of-care economics, with stable maintenance patients shifting toward lower-cost settings.
- Specialty Clinics:Academic medical centers with dedicated porphyria fellowship tracks concentrate diagnostic expertise and long-term monitoring for RNA therapy candidates. These sites capture recurring administration revenue through established metabolic disease infrastructure in the United States, Germany, and Japan.
- Homecare Settings:Subcutaneous givosiran protocols enable stable patients to self-administer maintenance doses outside tertiary facilities. PMDA Sakigake designation in Japan is accelerating homecare reimbursement frameworks for ultra-rare disease management.
- Hospitals:Emergency departments manage acute attack rescue with intravenous heme arginate and intensive monitoring for neurological complications.
- Ambulance Services:Pre-hospital transport coordinates rapid transfer to qualified centers during severe neurovisceral episodes requiring specialized intervention.
Specialty Clinics anchor current revenue concentration, though Homecare Settings are gaining share fastest as subcutaneous protocols mature.
Treatment Stage:
Chronic disease management creates recurring revenue streams against episodic rescue interventions, with preventive positioning emerging as a competitive battleground.
- Long-term Maintenance:Chronic ALA synthase suppression through scheduled RNA therapy administration. Patient advocacy organizations in Germany have secured quality-of-life data requirements in national health technology assessment frameworks for orphan drug reimbursement decisions.
- Acute Attack Management:Rapid cytochrome restoration during neurovisceral crises requiring hospital-based intravenous therapy. FDA orphan drug exclusivity frameworks protect qualified heme arginate suppliers from generic competition in rescue segments.
- Preventive Care:Trigger avoidance counseling and metabolic monitoring to reduce attack frequency in diagnosed patients.
- Follow-up Treatment:Post-attack recovery protocols addressing residual neurological symptoms and rehabilitation needs.
Long-term Maintenance commands the steepest expansion trajectory, while Acute Attack Management retains essential infrastructure positioning.
Drug Administration Route:
Route selection directly determines care setting economics, with patient preference and reimbursement tier driving modality substitution patterns.
- Subcutaneous:Monthly givosiran injections enabling outpatient or home-based maintenance without hospital admission. US specialty clinics are establishing telemedicine-linked monitoring protocols to support rural patient access to this administration mode.
- Intravenous:Heme arginate infusion requiring qualified infusion centers with emergency backup capacity for acute attack rescue. EU F-Gas Regulation and US EPA manufacturing standards constrain production site qualification, elevating supply concentration among established facilities.
- Oral:Limited application for symptomatic adjuncts rather than disease-modifying therapy in acute intermittent porphyria.
- Other Routes:Investigational delivery mechanisms including implantable devices and depot formulations in early development.
Intravenous administration retains dominant infrastructure investment, though Subcutaneous delivery is climbing the fastest as patient preference shifts toward hospital-independent care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where specialized diagnostic networks and orphan drug reimbursement frameworks command premium positioning against Japan's accelerating but price-controlled market access pathways.
United States
Academic medical centers in Boston and Houston anchor specialized porphyria fellowship programs that concentrate diagnostic expertise. FDA orphan drug exclusivity extensions protect RNA therapeutic developers from competitive entry for seven years. The Mayo Clinic Rochester campus coordinates multi-site telemedicine networks extending subcutaneous givosiran protocols to rural attack-prone patients across the Upper Midwest.
Germany
University hospitals in Munich and Heidelberg maintain Europe's densest concentration of metabolic disease specialists. EMA rare disease designation protocols streamline clinical trial requirements for hepatic porphyrin metabolism interventions. The national health technology assessment body in Cologne now mandates quality-of-life endpoint data for orphan drug reimbursement decisions, reshaping trial design requirements.
Japan
PMDA Sakigake designation accelerates review timelines for novel porphyria therapeutics seeking priority market access. METI coordinates rare disease infrastructure investments linking Tokyo academic centers to regional prefectural hospitals. Osaka-based specialty clinics are piloting homecare reimbursement frameworks for ultra-rare disease management, expanding addressable patient populations beyond tertiary facilities.
United Kingdom
NHS England's specialized commissioning frameworks concentrate acute intermittent porphyria treatment at designated metabolic centers in London and Manchester. The MHRA operates post-Brexit recognition pathways for EMA-approved orphan therapeutics. Cambridge clusters host contract research organizations supporting RNA synthesis scale-up for European clinical trial supply.
Switzerland
Swissmedic maintains accelerated access pathways for ultra-rare disease therapeutics targeting hepatic metabolic disorders. Basel anchors European pharmaceutical R&D infrastructure with specialized lipid nanoparticle formulation capabilities. University Hospital Zurich coordinates alpine-region patient referral networks extending diagnostic access to northern Italian and Austrian border populations.
Acute Intermittent Porphyria Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the acute intermittent porphyria therapeutic landscape. RNA interference platform specialists command premium positioning through patent-protected chronic suppression mechanisms, while established heme formulation suppliers anchor rescue therapy segments through manufacturing qualification barriers. The market structure bifurcates between innovation-driven biopharmaceutical developers and supply-concentrated rare disease distributors. Dominant competitive moves include strategic partnerships securing multi-year manufacturing agreements and portfolio diversification into gene therapy pipelines targeting curative-intent positioning.
Within the RNA platform leadership tier, Alnylam Pharmaceuticals exemplifies technology-driven market positioning through sustained givosiran-based maintenance therapy development. Among European rare disease distributors, Recordati Rare Diseases occupies a central position exemplifying supply chain concentration strategies for heme arginate acute rescue formulations. Mitsubishi Tanabe Pharma Corporation represents the Asia-Pacific market access archetype, situating within regulatory pathway navigation for PMDA-accelerated review frameworks. These three anchors illustrate the geographic and modality-based competitive segmentation structuring therapeutic development investment priorities.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals |
| Recordati Rare Diseases |
| Mitsubishi Tanabe Pharma Corporation |
| CLINUVEL PHARMACEUTICALS LTD |
| Pfizer |
| Bristol-Myers Squibb |
| Horizon Therapeutics |
| Dicerna Pharmaceuticals |
| Moderna |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety day manufacturing lead times for heme arginate active pharmaceutical ingredient concentrate pricing power among qualified European suppliers, while subcutaneous RNA therapy inventory cycles of fifteen to thirty days enable more flexible contracting structures in United States specialty clinic networks.
Pricing Analysis
The customization-premium spread separates standard heme arginate formulations from patient-specific dosing protocols configured for severe attack histories. Three-tier pricing structure across premium, standard, and economy levels tracks patent status, with RNA-based maintenance therapies commanding top positioning against commoditized rescue formulations. Cost compression in acute rescue segments is intensifying because manufacturing qualification barriers limit competitive entry. Academic medical centers show lowest price sensitivity due to bundled reimbursement frameworks, while regional hospitals face highest sensitivity from constrained formulary budgets.
Supply Chain Analysis
Strategic-stockpile preferences dominate heme arginate procurement as EU F-Gas Regulation compliance constrains qualified production to Italy, Spain, and the United Kingdom. Raw material dependencies center on bovine-derived heme precursors, specialized lipid nanoparticle formulations, and clinical-grade sodium hydroxide. Single-source vulnerability runs through Recordati's European heme arginate manufacturing network. Distribution runs through academic medical center consortia with cold-chain logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States specialty clinic networks as Mayo Clinic and Houston Methodist consolidate multi-site porphyria fellowship programs, reducing fragmentation among treatment-naïve referral sources.
For Market Incumbents: Shield RNA therapy market position by deepening manufacturing agreements with qualified lipid nanoparticle suppliers in Basel and Cambridge clusters. Secure multi-year heme arginate supply contracts before EU F-Gas Regulation tightening accelerates. Gene therapy pipeline entrants represent the primary substitution threat requiring portfolio diversification into curative-intent candidates. For New Entrants and Emerging Players: Differentiate on homecare delivery infrastructure rather than molecule innovation. Japan's PMDA Sakigake pathway offers the most penetrable regulatory geography for first-molecule advantage. Target prefectural hospital networks outside Tokyo through telemedicine-linked metabolic specialist partnerships as the specific go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents with dormant rare disease assets awaiting RNA platform integration. Long-term viability hinges on chronic maintenance-to-curative transition timelines compressing addressable duration. Watch FDA gene therapy breakthrough designation frequency as the inflection indicator signaling pipeline maturation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | RNA synthesis capacity expansion in Basel addresses lipid nanoparticle formulation bottlenecks for European clinical supply. |
| Regulatory Approval Pathway | PMDA Sakigake designation accelerates Japanese market access timelines for subcutaneous maintenance protocols. |
| Long-term Supply Agreement | Multi-year heme arginate contracts with academic medical centers secure qualified manufacturing allocation under EPA standards. |
| Pipeline Diversification | Gene therapy candidates targeting hepatic porphyrin metabolism capture curative positioning ahead of chronic suppression paradigms. |
| Licensing Agreement | Technology partnerships with lipid nanoparticle specialists enable RNA platform expansion into adjacent hepatic metabolic disorders. |
Methodological Framework
The analysis maps RNA therapeutic development, heme formulation manufacturing, and specialty clinic care delivery, each validated through metabolic disease specialists, regulatory affairs leads at orphan drug developers, hospital formulary directors, and payer access specialists. Primary interview findings triangulate against FDA orphan drug designations, EMA rare disease protocol submissions, ClinicalTrials.gov entries, and national health technology assessment frameworks. Bottom-up patient population estimates reconcile with top-down therapeutic revenue projections.
Consistency checks validate volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions include therapeutic modality, administration route, treatment stage, and regional regulatory cluster. CAGRs derive from patient prevalence modeling, therapy penetration assumptions, and pricing trajectory analysis. Forecast inputs incorporate specialty clinic fellowship expansion rates and homecare reimbursement policy evolution.
Material uncertainties — gene therapy clinical trial outcomes, EU F-Gas Regulation enforcement intensity, and Japan homecare reimbursement framework finalization — sit outside the modeled envelope. Forecasts reflect assumptions about attack frequency reduction endpoints satisfying payer evidence requirements. Revision becomes warranted when gene therapy breakthrough designation velocity crosses thresholds indicating curative paradigm displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market