
 Metabolic Disorders Therapeutics Market | 2026-2036
Metabolic Disorders Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Metabolic Disorders Therapeutics Market Analysis
The patient base for metabolic disorder treatments is broadening beyond traditional diabetes clinics into employer wellness networks and retail pharmacy settings. Novo Nordisk A/S leverages its manufacturing scale to supply GLP-1 therapies across multiple continents. Eli Lilly and Company anchors its position through R&D intensity in obesity drug pipelines. Sanofi S.A. competes through established insulin distribution networks that reach emerging markets.
Metabolic disorders therapeutics encompasses pharmacological interventions targeting dysregulated energy homeostasis, including peptide-based biologics requiring cold-chain distribution and small-molecule enzyme modulators formulated for oral bioavailability. These agents restore glycemic control, lipid metabolism, or appetite regulation in chronic endocrine conditions. GLP-1 Agonists and SGLT2 Inhibitors command premium pricing due to demonstrated cardiovascular outcomes, while the Injectable delivery mode captures the highest margin pools despite patient compliance challenges. The Oral segment sustains volume leadership in dyslipidemia and hypertension maintenance therapy.
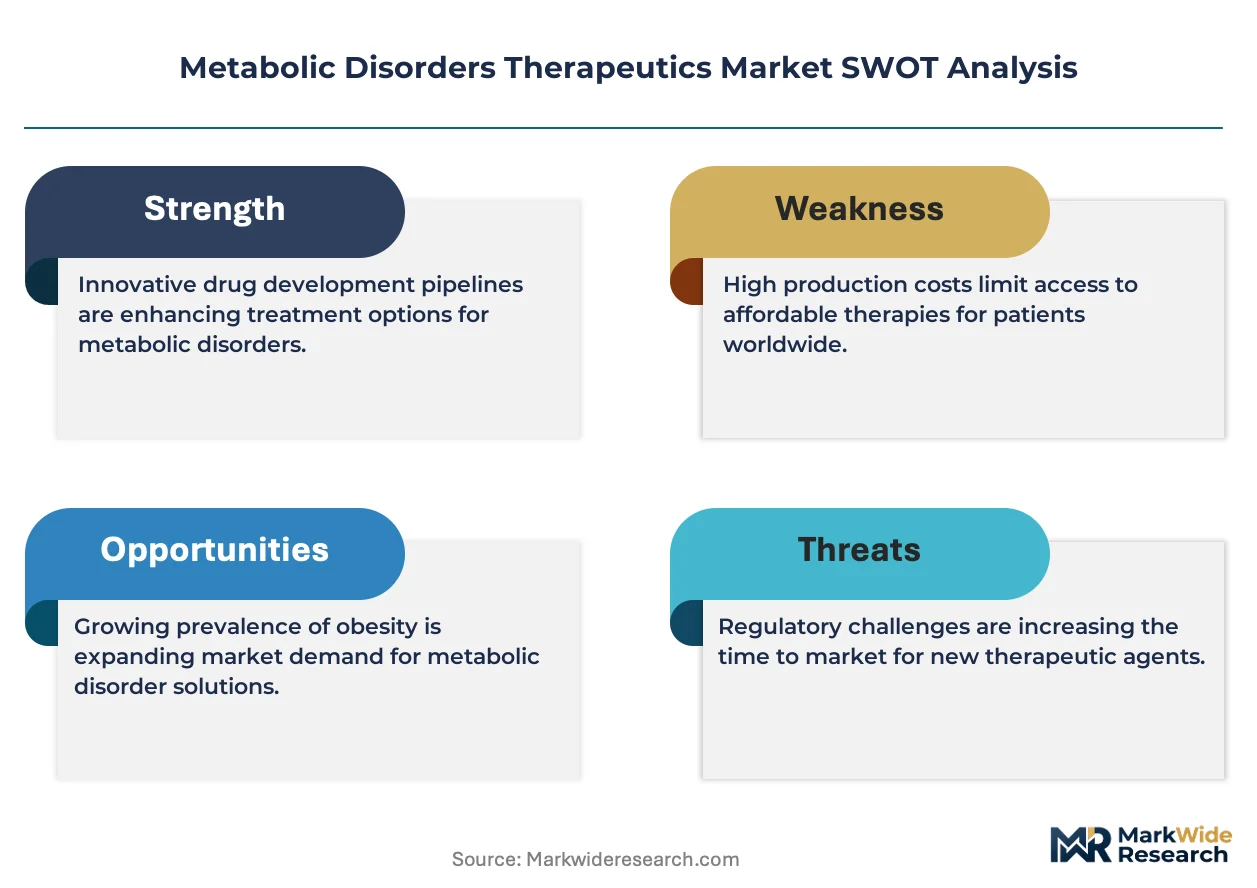
FDA, EMA, and WHO frameworks govern clinical trial endpoints, manufacturing quality, and post-market surveillance for metabolic therapies, with accelerated review pathways reshaping competitive timelines for obesity indications. The FDA's risk evaluation and mitigation strategies for thiazolidinediones and similar drug classes continue to influence prescriber behavior and formulary placement decisions. Stakeholders must monitor evolving pharmacovigilance requirements and payer evidence demands as the therapy area expands from glucose management to weight-related comorbidities.
Market Dynamics
Hospital procurement consolidation across the United States and Germany is compressing supplier margins while accelerating formulary decisions for GLP-1 receptor agonists, fundamentally restructuring how metabolic therapies reach patients.
Growth Catalysts
- Medicare Reimbursement Expansion:The Inflation Reduction Act provisions in the United States are extending coverage for injectable obesity treatments, pulling millions of new patients into addressable pools.
- EMA Accelerated Pathways:The European Medicines Agency's priority medicines scheme is compressing development timelines for cardiovascular outcome trials, rewarding sponsors with demonstrated heart failure benefits.
- Employer Wellness Integration:Large self-insured employers in the United States are embedding GLP-1 therapies into chronic disease management programs, creating direct-to-patient distribution channels outside traditional pharmacy benefit managers.
Market Restraints
- Cold-Chain Distribution Costs:Peptide-based biologics require continuous refrigeration from manufacturing through last-mile delivery, inflating logistics expenditures by 40-60% versus small-molecule alternatives.
- API Concentration in China:Active pharmaceutical ingredient synthesis for SGLT2 inhibitors concentrates in Zhejiang and Jiangsu provinces, exposing formulators to geopolitical supply interruptions.
- Thiazolidinedione REMS Legacy:FDA risk evaluation and mitigation strategies for legacy insulin sensitizers continue depressing prescriber confidence in oral metabolic drug classes.
Strategic Opportunities
- Oral GLP-1 Formulations:Small-molecule agonists eliminating injection requirements are expanding into patient populations with needle aversion, particularly in Japan where injection stigma remains pronounced.
- Non-Alcoholic Steatohepatitis Indications:Regulatory pathways for liver disease endpoints are opening new prescriber segments in hepatology clinics previously unreachable through diabetes-focused detailing.
- Retail Pharmacy Clinics:CVS Health and Walgreens are building metabolic disorder management capabilities, creating alternative access points independent of hospital system formularies.
Industry Challenges
- Peptide Manufacturing Scale-Up:Fermentation capacity for GLP-1 analogs requires 18-24 month facility qualification timelines, constraining supply response to demand surges.
- Pharmacovigilance Signal Management:Post-market surveillance for thyroid C-cell tumors in rodent models demands dedicated epidemiology teams and regulatory liaison functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metabolic Disorders Therapeutics Market |
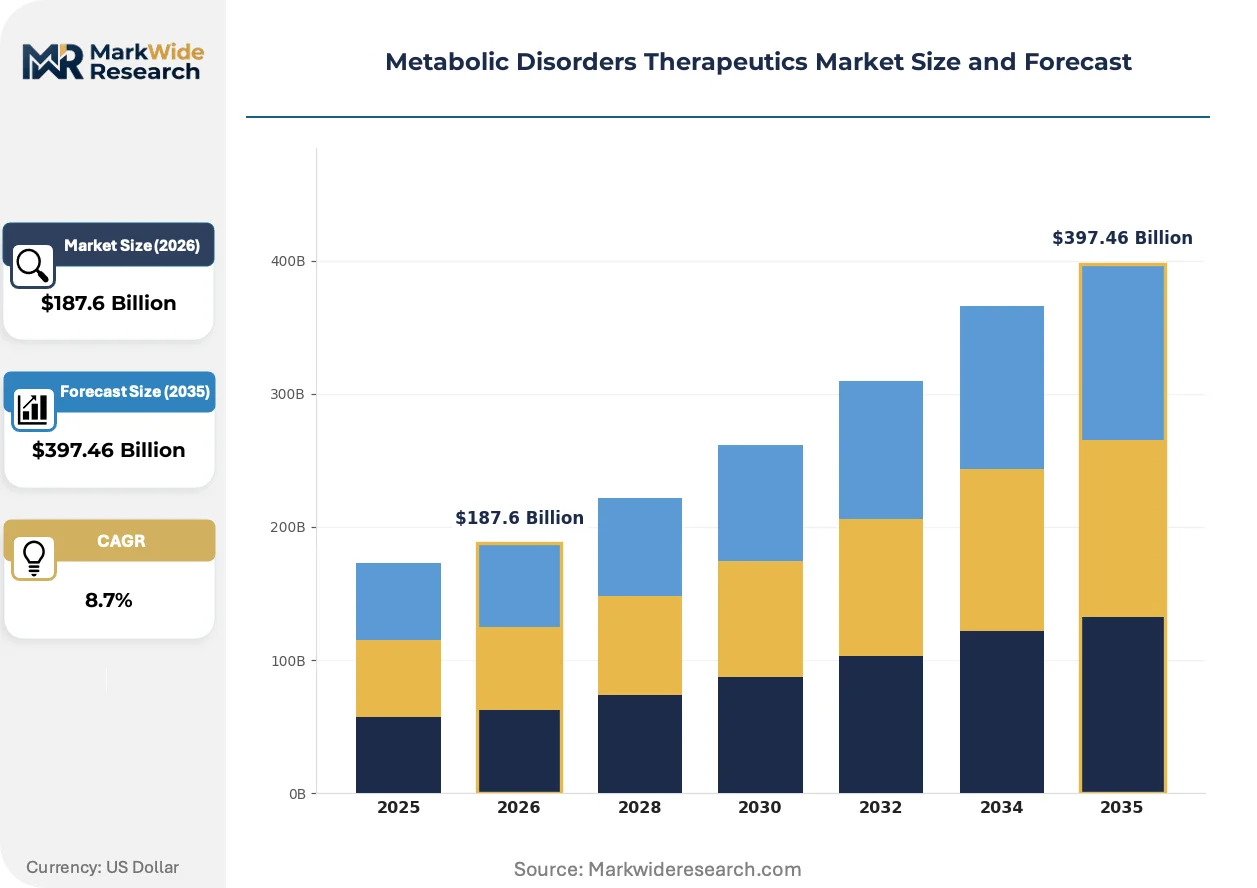
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, SGLT2 Inhibitors, DPP-4 Inhibitors Therapy Area: Diabetes, Obesity, Dyslipidemia, Hypertension Delivery Mode: Injectable, Oral, Transdermal, Inhalation End User: Hospitals, Clinics, Home Care, Long-term Care Facilities |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi S.A., Boehringer Ingelheim GmbH, Merck KGaA, AstraZeneca PLC, AbbVie Inc., Amgen Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metabolic Disorders Therapeutics Market Emerging Trajectories
Biologic manufacturing scale and regulatory science are converging to compress development cycles while expanding therapeutic indications beyond glucose control into cardiovascular and renal protection domains.
Dual GIP/GLP-1 receptor agonists are expanding into obesity management with superior weight loss efficacy versus single-target predecessors. Employer health plans and Medicare Advantage programs are adopting these agents as first-line interventions for patients with BMI thresholds above 35. The technology is expanding into cardiovascular risk reduction claims, forcing payers to recalculate total cost of ownership models beyond simple pharmacy spend.
The FDA's draft guidance on cardiovascular outcomes trials for obesity therapeutics is requiring sponsors to demonstrate MACE reduction before broad label expansion. This industrial consequence is extending Phase III durations by 12-18 months for agents without pre-existing diabetes indications. The United States market is responding through adaptive trial designs and real-world evidence supplementation to satisfy payers demanding outcome guarantees.
Direct-to-consumer telehealth platforms are disintermediating traditional endocrinology referrals for initial metabolic therapy prescriptions. Ro, Hims & Hers Health, and similar virtual care providers are capturing medication initiation decisions previously controlled by specialist physicians. This channel shift is most visible in the United States where state-level prescribing regulations permit asynchronous consultations, bypassing geographic access constraints in rural markets.
Metabolic Disorders Therapeutics Market Segmentation
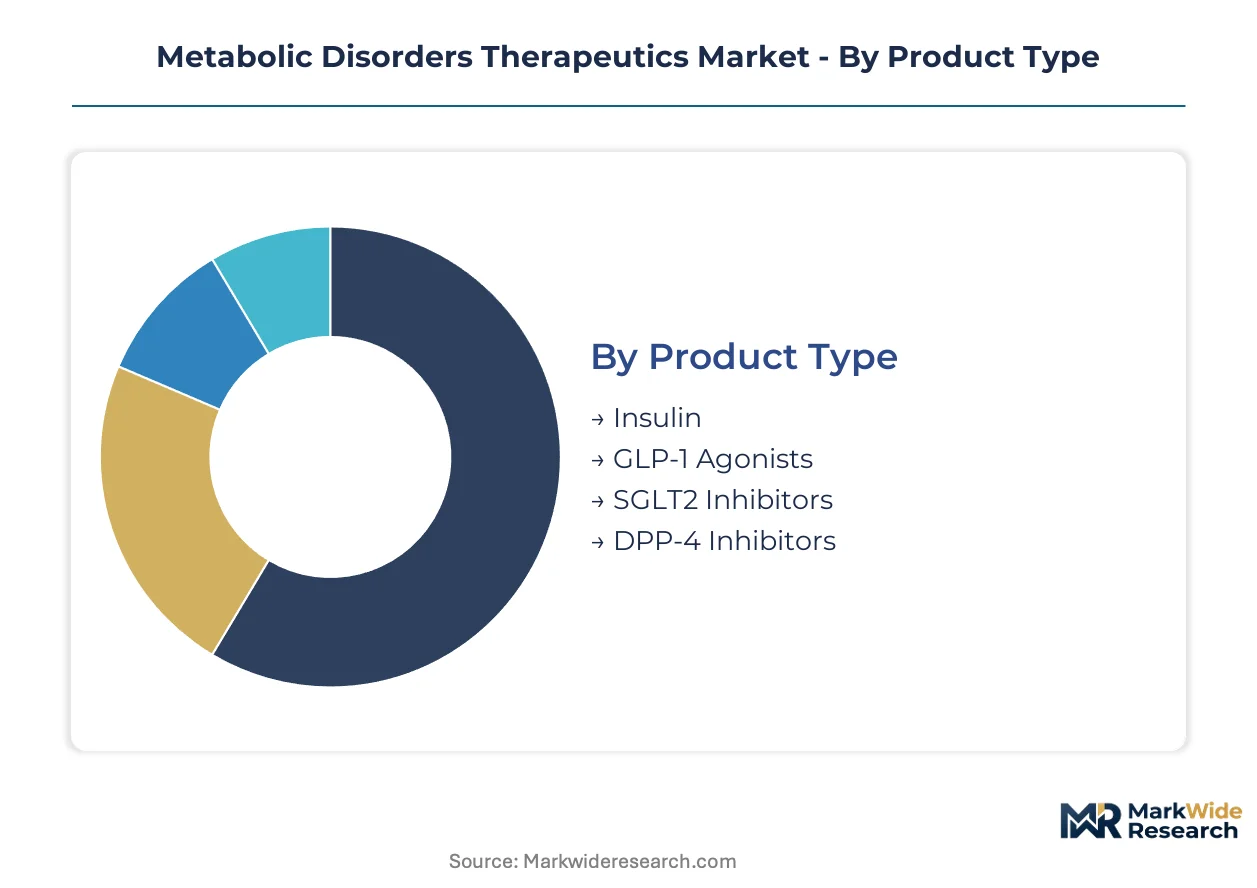
Metabolic disorder therapeutics segment along four critical dimensions that determine regulatory pathway complexity, reimbursement eligibility, and supply chain configuration. Each category carries distinct certification burdens and margin profiles that shape competitive positioning across patient access channels.
Product Type:
FDA and EMA approval requirements diverge sharply across product categories, with peptide biologics demanding extensive immunogenicity profiling and small molecules requiring cardiovascular outcome validation for premium formulary placement.
- GLP-1 Agonists:Peptide-based biologics mimicking incretin hormones to stimulate glucose-dependent insulin secretion and suppress appetite. Hospital systems in the United States and employer wellness programs are concentrating procurement for these agents as cardiovascular outcome data expands label indications.
- Insulin:Recombinant protein therapies manufactured through microbial or mammalian cell culture, spanning rapid-acting analogs to long-acting basal formulations. Emerging market demand in India and Brazil continues to anchor volume leadership despite biosimilar compression in European tenders.
- SGLT2 Inhibitors:Small-molecule sodium-glucose cotransporter blockers with demonstrated heart failure benefits.
- DPP-4 Inhibitors:Oral enzyme inhibitors extending endogenous incretin half-life for glycemic control.
Leading the category by volume: Insulin. Growing fastest: GLP-1 Agonists.
Therapy Area:
Reimbursement codes and clinical trial endpoints vary substantially across indication categories, with obesity therapies now requiring cardiovascular risk reduction evidence under FDA draft guidance while diabetes maintains established HbA1c benchmarks.
- Obesity:Pharmacological weight management interventions targeting BMI reduction and metabolic comorbidity prevention. Medicare Advantage plans and large self-insured employers in the United States are embedding these therapies into chronic disease management programs.
- Diabetes:Glucose-lowering therapies spanning Type 1 insulin replacement and Type 2 combination regimens. Hospital consolidation across Germany and the United States is compressing supplier margins while accelerating formulary decisions.
- Dyslipidemia:Lipid-modifying agents addressing elevated cholesterol and triglyceride levels.
- Hypertension:Antihypertensive therapies with metabolic comorbidity considerations.
Obesity applications are climbing the fastest as regulatory pathways mature; diabetes retains the largest installed patient base.
Delivery Mode:
Cold-chain infrastructure requirements and patient compliance economics create divergent margin structures across administration routes, with injectable formats commanding premium pricing despite adherence challenges.
- Injectable:Parenteral administration via subcutaneous injection for peptide biologics and insulin analogs requiring continuous refrigeration. The United States retail pharmacy channel and home delivery services are expanding capacity for temperature-controlled distribution.
- Oral:Small-molecule formulations enabling patient self-administration without cold-chain dependency. Volume concentrates in dyslipidemia and hypertension maintenance therapy across pharmacy benefit manager networks.
- Transdermal:Patch-based delivery systems for sustained hormone or drug release.
- Inhalation:Pulmonary administration routes for rapid-acting metabolic agents.
Injectable formats dominate revenue pools; oral delivery sustains the widest geographic reach.
End User:
Procurement authority and reimbursement mechanisms differ fundamentally across care settings, with hospital systems leveraging consolidated purchasing power while home care channels bypass traditional formulary controls.
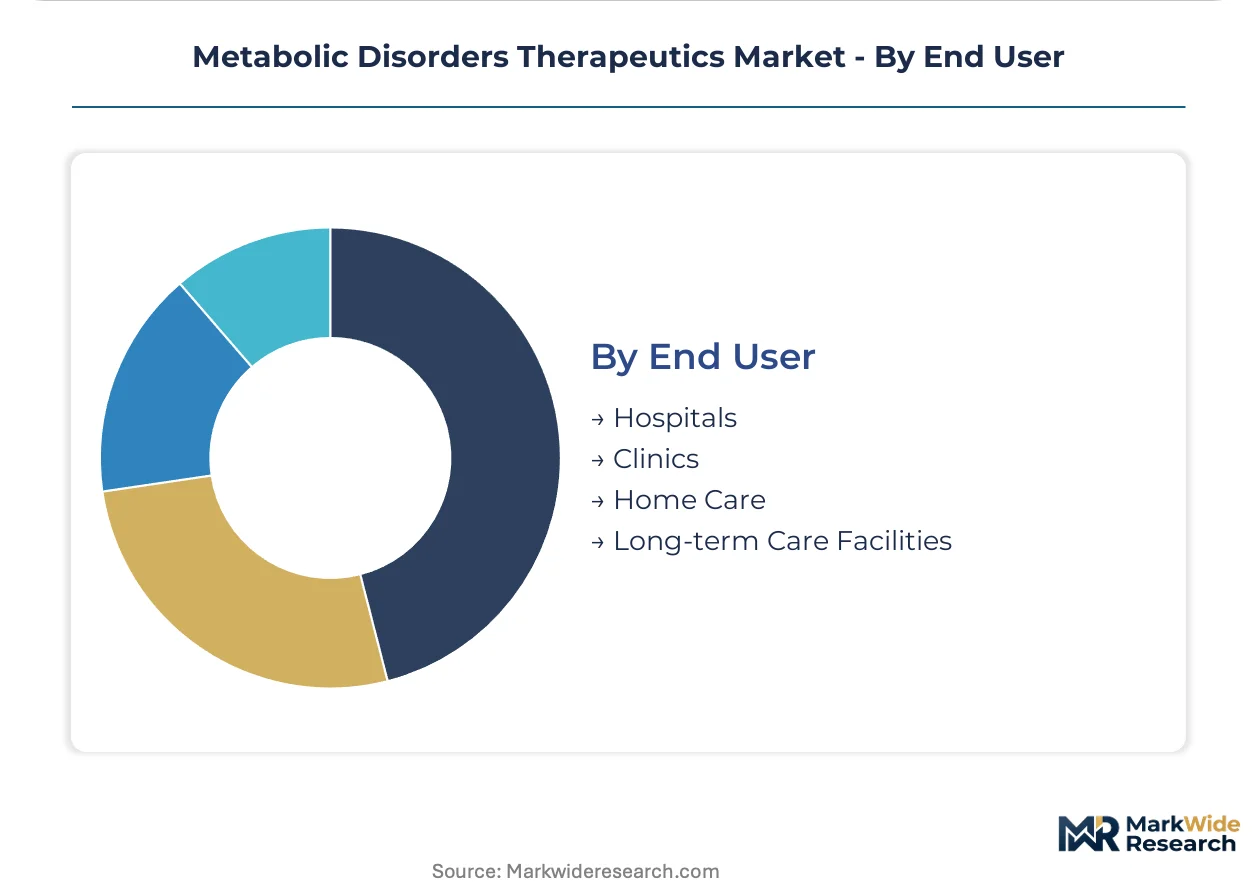
- Hospitals:Acute care institutions with consolidated procurement committees managing inpatient metabolic therapy protocols. Health system consolidation in the United States and Germany is restructuring supplier access and compressing price points.
- Home Care:Patient-directed administration settings including residential and ambulatory environments. Direct-to-consumer telehealth platforms in the United States are disintermediating traditional endocrinology referrals for initial prescription decisions.
- Clinics:Outpatient specialty and primary care facilities.
- Long-term Care Facilities:Skilled nursing and assisted living environments managing chronic metabolic conditions.
Hospitals anchor procurement volume; home care channels are gaining share fastest as distribution models evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States employer wellness programs and Medicare reimbursement shifts concentrate demand for injectable metabolic therapies, while European hospital procurement consolidation and Asian manufacturing clusters reshape supply geography.
United States
Employer-sponsored wellness programs and Medicare Advantage plans are embedding GLP-1 therapies into chronic disease management, pulling millions into addressable pools. The Inflation Reduction Act provisions extend coverage for injectable obesity treatments through CMS reimbursement codes. The Boston-Cambridge biotech corridor anchors peptide manufacturing scale-up for fermentation-based analog production.
Germany
Hospital system consolidation across Bavaria and North Rhine-Westphalia is compressing supplier margins while accelerating formulary decisions for cardiovascular outcome therapies. The EMA's priority medicines scheme operates from Amsterdam but governs German market access timelines for heart failure benefit claims. The Rhine-Main pharmaceutical cluster near Frankfurt sustains insulin distribution infrastructure reaching Central and Eastern European markets.
China
Domestic demand for SGLT2 inhibitors and oral hypoglycemics is climbing as urban diabetes prevalence rises in coastal provinces. The NMPA accelerates review pathways for cardiovascular outcome trials under national pharmacovigilance frameworks. Zhejiang and Jiangsu provinces concentrate active pharmaceutical ingredient synthesis, exposing formulators to supply interruption risks from environmental compliance inspections.
Japan
Injection stigma among aging populations is driving demand for oral GLP-1 formulations and small-molecule enzyme modulators. The PMDA maintains stringent post-market surveillance requirements for thyroid C-cell tumor signals in rodent models. The Kansai region around Osaka anchors domestic manufacturing for DPP-4 inhibitors and fixed-dose combination therapies.
India
Price-sensitive diabetes markets in Maharashtra and Gujarat sustain high-volume insulin demand despite biosimilar compression. The CDSCO harmonizes with WHO prequalification standards for generic metabolic drug exports to African markets. The Hyderabad-Visakhapatnam corridor hosts contract manufacturing for oral hypoglycemic active pharmaceutical ingredients.
Metabolic Disorders Therapeutics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue oral formulation breakthroughs and non-alcoholic steatohepatitis indications. The vendor base concentrates around three archetypes: fermentation-scale peptide manufacturers, small-molecule cardiovascular outcome specialists, and integrated insulin distribution networks. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic partnerships with retail pharmacy clinic operators.
Within the fermentation-scale tier, Novo Nordisk A/S and Eli Lilly and Company exemplify manufacturing depth for GLP-1 receptor agonists. Sanofi S.A. occupies a position anchoring insulin distribution reach into emerging markets. These three entities represent distinct strategic postures: peptide biologic scale, R&D intensity in obesity pipelines, and established channel infrastructure respectively.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi S.A. |
| Boehringer Ingelheim GmbH |
| Merck KGaA |
| AstraZeneca PLC |
| AbbVie Inc. |
| Amgen Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply Flow & Price Mechanics
Peptide biologics versus small-molecule oral formulations bifurcate the metabolic therapeutics landscape, with GLP-1 agonists commanding premium reimbursement through demonstrated cardiovascular outcomes while generic insulin and SGLT2 inhibitors face tender compression. This tier divergence maps directly onto supply chain architecture: fermentation-based manufacturing demands 18-24 month facility qualifications and continuous cold-chain distribution, whereas small-molecule production leverages concentrated API synthesis in Zhejiang and Jiangsu provinces with standard pharmaceutical logistics.
Pricing Analysis
Volume leadership rests with oral small molecules in dyslipidemia and hypertension maintenance, while margin concentration sits with injectable GLP-1 agonists in obesity and diabetes management. Pricing stratifies across cardiovascular outcome certification tiers, with FDA-recognized MACE reduction claims unlocking premium formulary placement. Cost compression in the insulin segment intensifies as biosimilar entrants and hospital procurement consolidation in Germany and the United States squeeze originator margins. Employer wellness programs and Medicare Advantage plans exhibit lowest price sensitivity for obesity therapies with weight-loss efficacy thresholds above 15%, while emerging market tenders for human insulin demonstrate highest sensitivity to per-unit cost.
Supply Chain Analysis
Direct-to-patient channels through telehealth platforms and retail pharmacy clinics are disintermediating traditional wholesale distribution for initial GLP-1 prescriptions. Active pharmaceutical ingredient synthesis draws from China for SGLT2 inhibitors, India for oral hypoglycemics, and Denmark for insulin analogs. Fermentation capacity for peptide biologics rests on microbial and mammalian cell culture inputs, with single-source vulnerability concentrated in qualified sterile fill-finish facilities. Tariff exposure on Chinese API imports and environmental compliance inspections in Jiangsu province constitute structural supply risks. Distribution runs through hospital system formularies in the United States and Germany, home delivery services for temperature-controlled biologics, and pharmacy benefit manager networks for oral maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metabolic disorders therapeutics is consolidating around manufacturing scale and cardiovascular outcome data, with hospital procurement centralization and FDA draft guidance on obesity MACE requirements forcing subscale players toward exit or acquisition. Peptide fermentation capacity constraints and pharmacovigilance infrastructure costs are the dominant pressures accelerating this consolidation.
For Market Incumbents: To counter biosimilar compression in insulin and emerging oral GLP-1 threats, anchor position through backward integration into API production in Zhejiang and captive supply of fermentation capacity for dual GIP/GLP-1 analogs. Prioritize cardiovascular outcome trial investment to secure premium reimbursement tiers under FDA draft guidance, while consolidating hospital system formulary access through integrated distribution partnerships with CVS Health and Walgreens clinic networks.
For New Entrants and Emerging Players: Launch via direct-to-consumer telehealth channels targeting needle-averse patient populations in Japan and employer wellness program carve-outs in the United States. White-space opportunities concentrate in non-alcoholic steatohepatitis indications reaching hepatology clinics previously inaccessible through diabetes-focused detailing, and oral small-molecule GLP-1 formulations eliminating cold-chain dependency for rural and emerging market access.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap fermentation specialists possessing qualified peptide manufacturing capacity given GLP-1 demand surges and 18-24 month facility qualification timelines constraining supply response. Long-term viability over the next decade hinges on cardiovascular outcome data generation and pharmacovigilance infrastructure for thyroid C-cell tumor signal management. Watch for FDA obesity label expansion decisions and EMA priority medicines scheme approvals as inflection indicators for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Fermentation capacity expansion in Boston-Cambridge corridor addresses GLP-1 supply constraints. |
| Cardiovascular Outcome Trial Advancement | MACE reduction data unlocks premium Medicare reimbursement under FDA draft guidance. |
| Oral Formulation Development | Small-molecule GLP-1 agonists bypass injection stigma in Japan and cold-chain costs. |
| Retail Pharmacy Partnership | CVS Health and Walgreens clinic integration creates alternative access points outside hospital formularies. |
| API Backward Integration | In-house production of SGLT2 inhibitor precursors mitigates Zhejiang supply interruption risks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA 510(k) submissions, EMA assessment reports, ClinicalTrials.gov entries, and CMS Medicare reimbursement databases supplied quantitative anchors. Bottom-up patient population modeling and top-down pharmaceutical expenditure reconciliation triangulated market sizing across the analysis window.
Reconciliation of prescription volume data, wholesale acquisition cost trends, and patient access program enrollment produced segmented forecasts. The analytical framework modeled therapy area, product type, delivery mode, and end user dimensions across the projection horizon, with CAGRs derived from elasticity-adjusted adoption curves and regulatory timeline probabilities. Peptide manufacturing capacity expansion schedules and cardiovascular outcome trial readout dates fed industry-specific scenario inputs.
Regulatory pathway delays, API supply interruptions, and reimbursement policy reversals are the dominant revision risks. Forecasts reflect documented assumptions regarding EMA priority medicines scheme utilization rates and employer wellness program GLP-1 adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Healthcare Specialty Enzymes Market