
 Neurosyphilis Market | 2026-2036
Neurosyphilis Market Size, Share, and Industry Trends Forecast 2026-2036
Neurosyphilis Market Outlook
The gap between premium molecular diagnostics and commodity serological testing is realigning procurement patterns across hospital networks. Abbott leverages its integrated diagnostic platform to sustain leadership in automated immunoassay systems. Pfizer anchors the antibiotic segment through established penicillin G manufacturing scale. Sanofi competes in adjacent neuroinfectious disease portfolios that extend its hospital channel control.
Neurosyphilis represents central nervous system invasion by Treponema pallidum, manifesting as meningitis, general paresis, or tabes dorsalis with cerebrospinal fluid pleocytosis and reactive serology as diagnostic hallmarks. The condition demands prompt intravenous penicillin G to prevent irreversible neurological damage. Diagnostic Kits lead revenue contribution as hospitals shift toward rapid testing and PCR-based confirmation, while Antibiotics retain stable volume through mandatory first-line protocols. Research Laboratories represent the fastest-growing end user as translational studies on neuroinflammatory biomarkers expand.
The FDA governs in vitro diagnostic approvals and antimicrobial labeling for neurosyphilis indications, while the EMA coordinates centralized assessments across EU member states. WHO guidelines on syphilis elimination targets shape national screening mandates that expand addressable testing volume. Stakeholders must monitor evolving resistance surveillance data and diagnostic algorithm updates that could redirect capital toward next-generation molecular platforms.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while accelerating automated platform adoption across infectious disease diagnostics. Network-level standardization mandates favor integrated diagnostic systems over fragmented point-of-care devices.
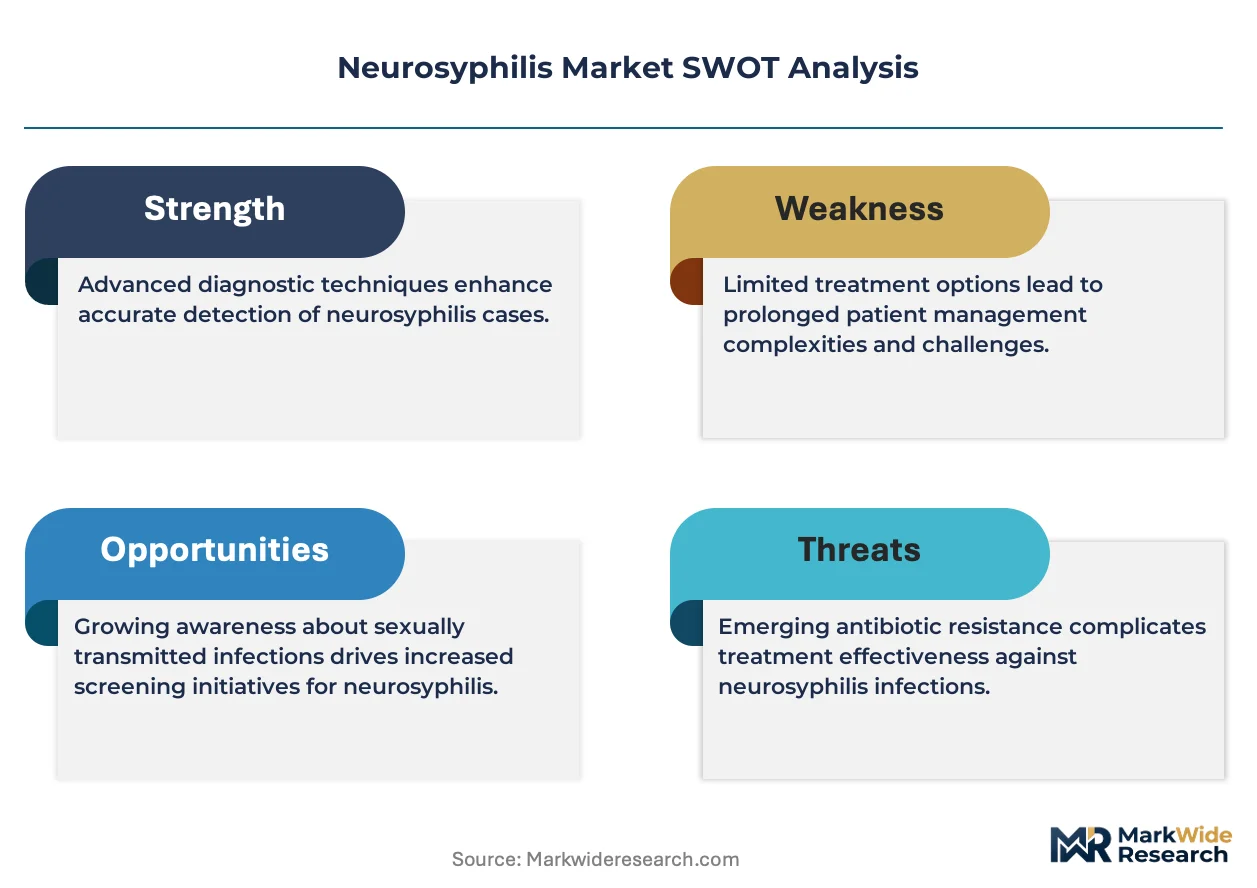
Growth Catalysts
- WHO syphilis elimination targets:National screening mandates in the United States and Western Europe expand routine testing volume in prenatal and HIV-care settings.
- PCR-based confirmation protocols:Reference laboratories accelerate molecular diagnostic adoption to resolve serological ambiguity in neuroinvasive disease staging.
- Hospital network consolidation:Integrated delivery systems in Germany and France centralize purchasing authority toward automated immunoassay platforms.
Market Restraints
- Penicillin G supply concentration:Manufacturing of the first-line antibiotic depends on a limited base of sterile injectable facilities in the United States and Europe.
- Serological test commoditization:Non-treponemal assays face price erosion as procurement shifts to high-volume tenders.
- Diagnostic algorithm complexity:Discordance between treponemal and non-treponemal results prolongs confirmatory testing timelines.
Strategic Opportunities
- Research laboratory expansion:Translational studies on neuroinflammatory biomarkers in the United States create demand for specialized molecular panels.
- CE-IVDR transition window:The European Union's new in vitro diagnostic regulation creates first-mover advantage for compliant manufacturers.
- Multiplex platform convergence:Combination of PCR and serological readouts on single instruments reduces capital footprint for mid-tier hospitals.
Industry Challenges
- Laboratory technologist scarcity:Specialized microbiology and molecular diagnostics expertise shortages constrain test throughput expansion.
- CSF collection protocol standardization:Variability in lumbar puncture practices across hospital systems complicates biomarker validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurosyphilis Market |
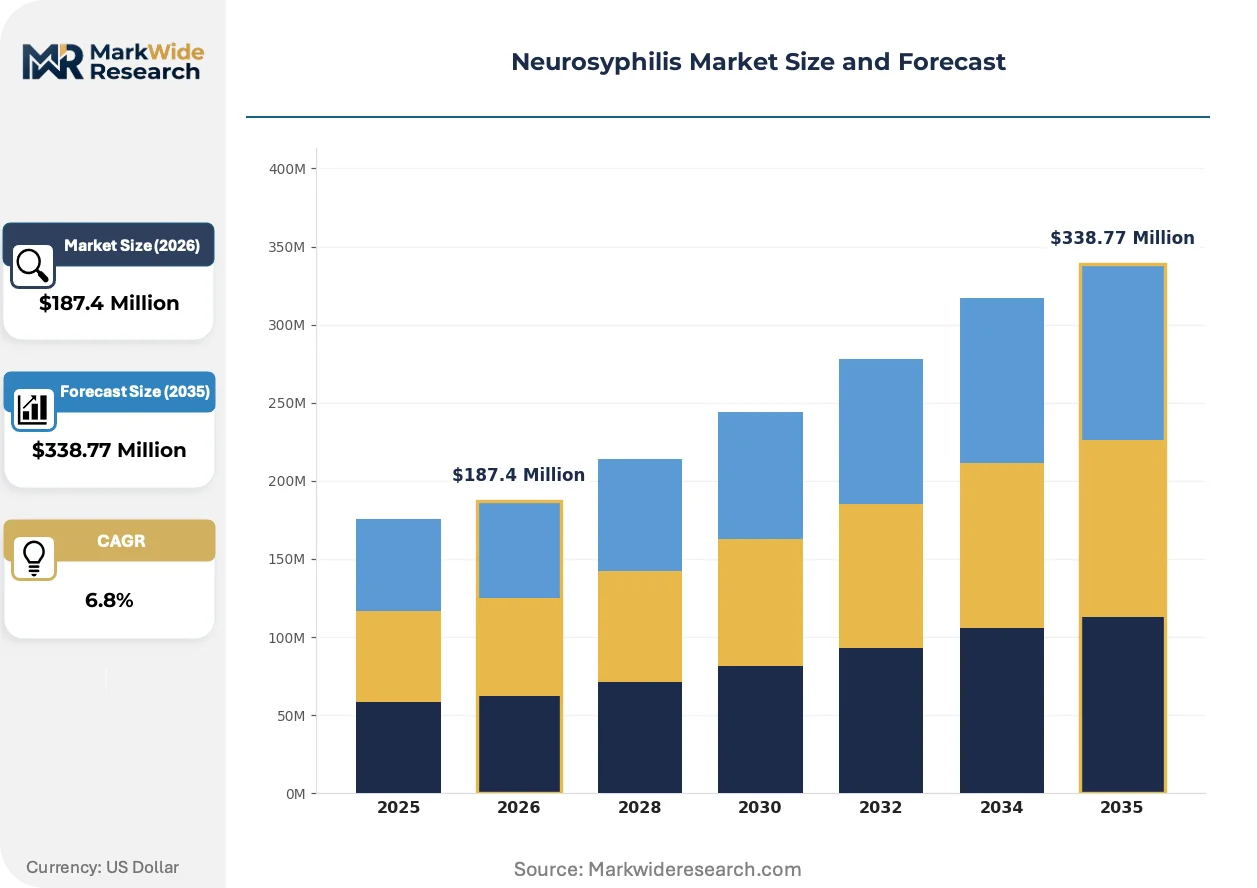
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiretrovirals, Diagnostic Kits, Supportive Therapy End User: Hospitals, Clinics, Research Laboratories, Home Care Settings Administration Route: Intravenous, Intramuscular, Oral, Topical Technology: Enzyme-Linked Immunosorbent Assay, PCR, Rapid Testing, Microscopy |
| Companies Covered | Abbott, Pfizer, Novartis, Sanofi, GlaxoSmithKline, Bayer, Eli Lilly and Company, Bristol-Myers Squibb, Merck & Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurosyphilis Market Strategic Shifts
Diagnostic platform architecture is converging toward modular systems capable of serological screening and molecular confirmation. This unification responds to pressure for faster turnaround in emergency neurology settings.
Automated chemiluminescence immunoassays are unifying screening and reflex testing workflows. Large hospital networks in the United States and Germany deploy these platforms to reduce manual sample handling. The technology is unifying previously separate serology and molecular departments into centralized infectious disease laboratories.
The FDA's updated guidance on syphilis serological assays tightens analytical performance requirements. Manufacturers must demonstrate improved sensitivity in early infection stages. European manufacturers face parallel pressure from EMA's infectious disease diagnostic quality standards, accelerating investment in recombinant antigen production.
Hospital procurement committees now bundle diagnostic reagents with service contracts spanning multiple instrument generations. Reference laboratories in France and the United Kingdom lead this shift away from transactional purchasing. Academic medical centers in the United States follow, consolidating vendor relationships to secure priority technical support during instrument transitions.
Neurosyphilis Market Segmentation
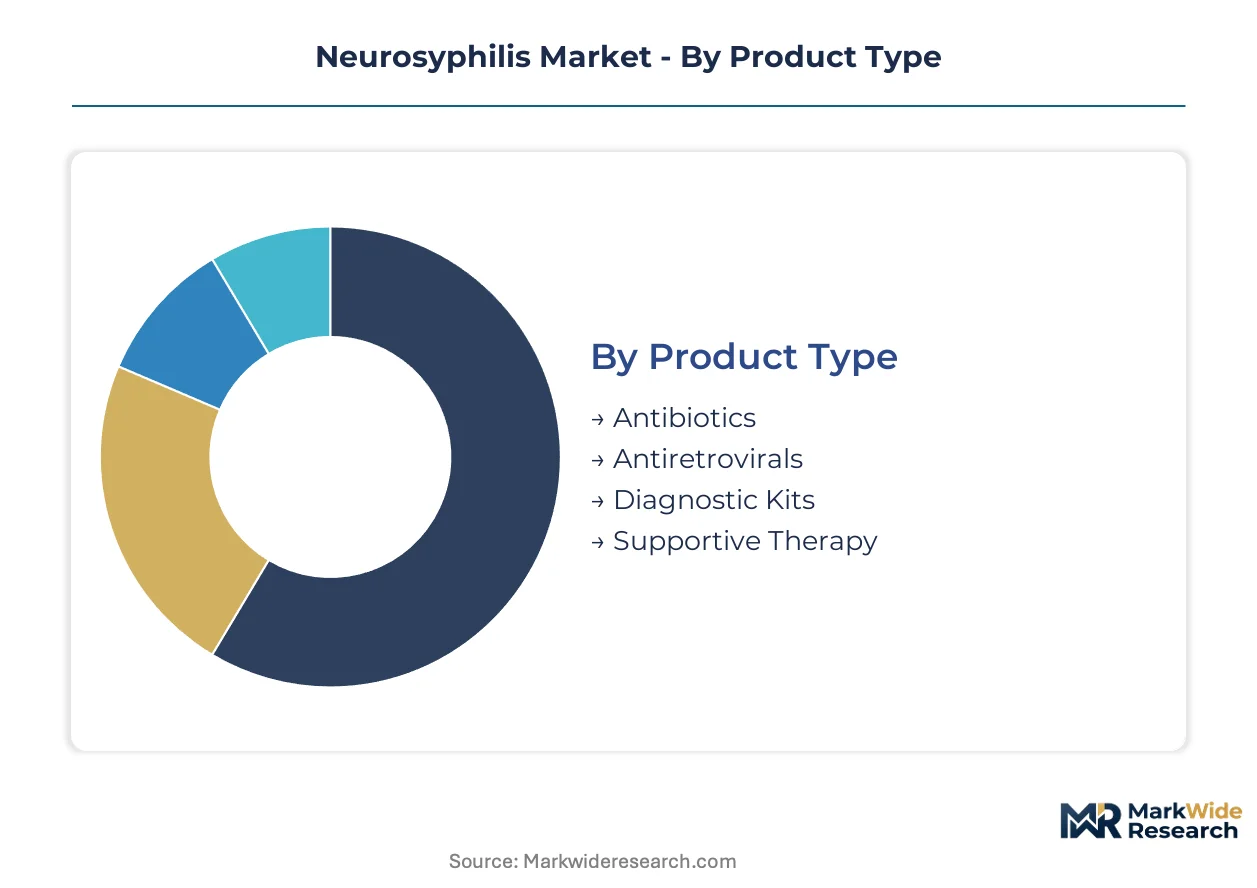
Neurosyphilis treatment and detection spans divergent regulatory pathways, from FDA-cleared diagnostic platforms to sterile injectable manufacturing governed by cGMP. Procurement patterns differ sharply between hospital formulary committees and research grant funding streams.
Product Type:
FDA antimicrobial labeling and CE-IVDR certification burdens vary substantially across therapeutic versus diagnostic segments, shaping vendor investment priorities and margin structures.
- Diagnostic Kits:Automated immunoassay and PCR-based platforms require FDA 510(k) or CE-IVDR technical documentation with clinical sensitivity demonstrations. Hospital laboratories in the United States and Germany concentrate procurement toward integrated systems that unify screening and confirmation workflows.
- Antibiotics:Intravenous penicillin G dominates first-line protocols with sterile injectable manufacturing subject to FDA cGMP and EMA GMP inspections. Supply concentrates in a limited base of United States and European facilities with validated aseptic processing lines.
- Antiretrovirals:Co-administration in HIV-coinfected patients follows antiretroviral therapy guidelines without neurosyphilis-specific approvals.
- Supportive Therapy:Adjunctive corticosteroids and analgesics address inflammatory complications through standard hospital pharmacy procurement.
Leading the category by volume: Diagnostic Kits. Growing fastest: Antibiotics through mandatory first-line protocols.
End User:
Customer type determines purchasing authority concentration, from centralized hospital procurement committees to decentralized principal investigator grant allocations.
- Hospitals:Integrated delivery networks in France and Germany centralize infectious disease diagnostic purchasing toward multi-year service contracts. Emergency neurology departments drive rapid testing demand with turnaround time mandates under two hours.
- Research Laboratories:Academic medical centers in the United States expand translational studies on neuroinflammatory biomarkers, creating demand for specialized molecular panels and CSF analytics. NIH and institutional funding cycles shape capital equipment refresh timelines.
- Clinics:Outpatient settings rely on referral patterns to hospital reference laboratories for confirmatory testing.
- Home Care Settings:Limited to oral antibiotic completion after initial hospital-based intravenous induction.
Highest procurement authority: Hospitals. Steepest expansion trajectory: Research Laboratories.
Administration Route:
Route selection ties directly to disease staging and CNS penetration requirements, with intravenous delivery mandatory for neuroinvasive infection.
- Intravenous:Penicillin G infusion achieves therapeutic CSF concentrations required for neurosyphilis clearance. Hospital infusion centers in the United States manage multi-day administration protocols with pharmacy oversight of sterile compounding.
- Intramuscular:Benzathine penicillin serves early syphilis without CNS involvement but fails to achieve adequate CSF levels for neuroinvasive disease.
- Oral:Doxycycline alternatives apply only in penicillin-allergic patients with demonstrated compliance and non-pregnant status.
- Topical:No established efficacy for systemic or CNS treponemal infection.
Dominant by clinical mandate: Intravenous. Alternative route gaining protocol attention: Intramuscular for staging-differentiated care.
Technology:
Platform selection reflects the tension between serological screening throughput and molecular confirmation specificity in reference laboratory workflows.
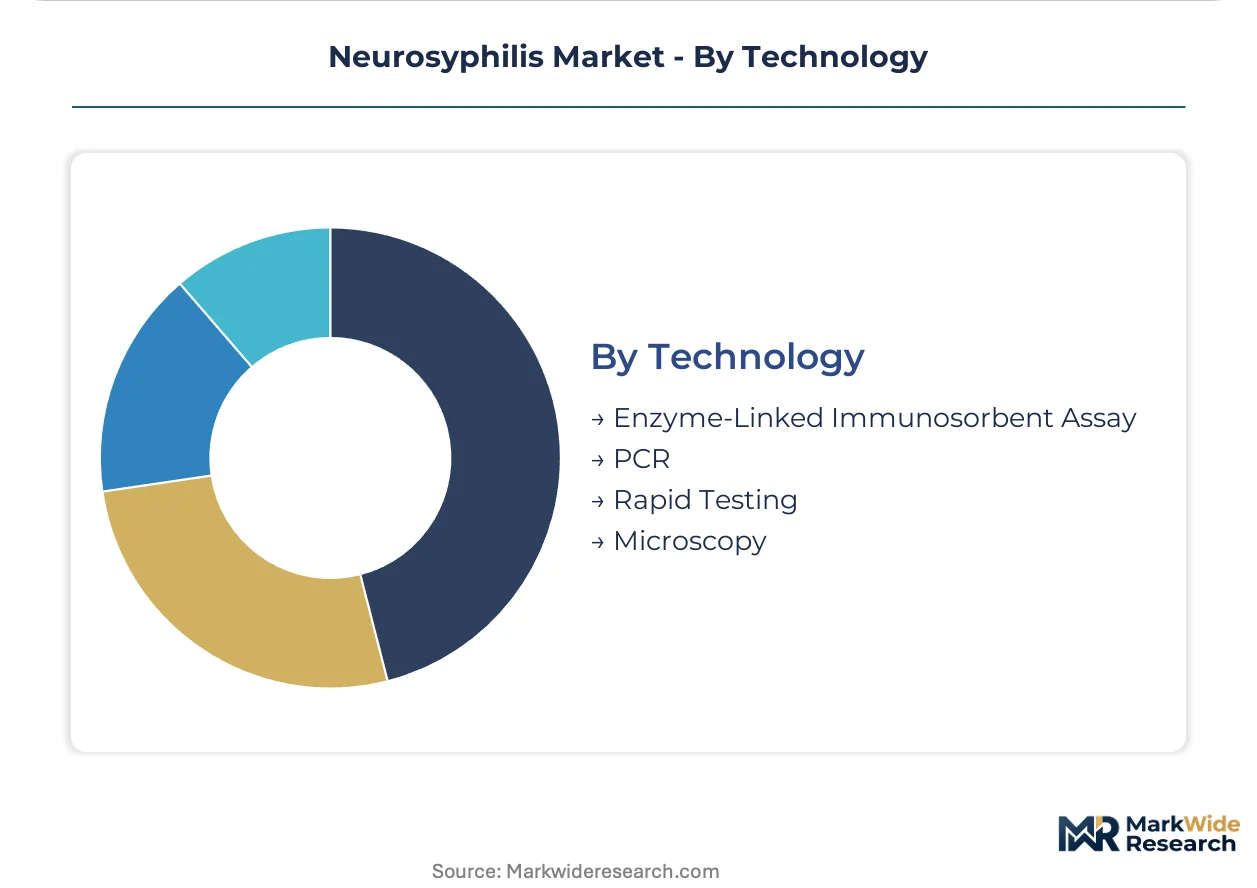
- PCR:Nucleic acid amplification detects Treponema pallidum DNA in CSF with superior specificity for neuroinvasive staging. Reference laboratories in the United Kingdom and United States accelerate adoption to resolve serological discordance in HIV-coinfected patients.
- Enzyme-Linked Immunosorbent Assay:Chemiluminescence immunoassays automate high-volume screening with FDA-updated sensitivity requirements for early infection detection.
- Rapid Testing:Point-of-care treponemal assays serve emergency department triage with limited CSF applicability.
- Microscopy:Dark-field and fluorescent antibody techniques retain niche utility in lesion-based diagnosis without CSF deployment.
Highest revenue concentration: Enzyme-Linked Immunosorbent Assay. Gaining share fastest: PCR.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor concentrates neurosyphilis research funding and reference laboratory capacity. Hospital networks across the United States and Western Europe drive diagnostic procurement standardization. Manufacturing of sterile injectable antibiotics clusters in FDA-inspected facilities near Philadelphia and Frankfurt.
United States
Integrated delivery networks in Texas and California centralize infectious disease diagnostic purchasing toward multi-year service contracts. The FDA governs in vitro diagnostic approvals and antimicrobial labeling for neurosyphilis indications. NIH-funded translational studies at Johns Hopkins and Massachusetts General Hospital expand CSF biomarker research demand.
Germany
Hospital network consolidation in North Rhine-Westphalia and Bavaria accelerates automated platform adoption across infectious disease diagnostics. EMA coordinates centralized assessments for CE-IVDR technical documentation across EU member states. Siemens Healthineers and Roche Diagnostics anchor diagnostic manufacturing in the Mannheim and Basel corridor.
United Kingdom
Reference laboratories in London and Manchester accelerate PCR-based confirmation to resolve serological discordance in HIV-coinfected patients. NHS England's national screening mandates expand routine testing volume in prenatal and sexual health settings. Academic medical centers in Oxford and Cambridge drive neuroinflammatory biomarker panel development.
France
Hospital procurement committees in Île-de-France bundle diagnostic reagents with multi-generation service contracts. ANSM enforces post-market surveillance for in vitro diagnostic performance. Sanofi maintains headquarters and hospital channel infrastructure in the Paris metropolitan area for adjacent neuroinfectious disease portfolios.
Switzerland
Roche Diagnostics anchors automated immunoassay manufacturing and R&D in the Basel pharmaceutical cluster. Swissmedic coordinates with EMA on parallel review pathways for molecular diagnostic platforms. The Lake Geneva corridor concentrates sterile injectable antibiotic manufacturing for European distribution.
Neurosyphilis Market Competitive Environment
Premium-margin players sit above commodity-margin players across diagnostic platform integration and sterile manufacturing scale. The market structures around three tiers: integrated diagnostic conglomerates, specialized antibiotic manufacturers, and research-focused biopharmaceutical firms. Strategic archetypes include platform consolidators leveraging hospital network standardization, sterile injectable specialists defending manufacturing capacity, and biomarker developers capturing research laboratory expansion. Dominant competitive moves center on multi-year service contract bundling and regulatory first-mover positioning through CE-IVDR compliance.
Within the integrated diagnostic tier, Abbott exemplifies platform consolidation through its automated immunoassay systems. Pfizer anchors the antibiotic segment as a sterile injectable manufacturer with established penicillin G production scale. Sanofi occupies a position bridging hospital channel control with adjacent neuroinfectious disease portfolio extension.
| Leading Market Players |
|---|
| Abbott |
| Pfizer |
| Novartis |
| Sanofi |
| GlaxoSmithKline |
| Bayer |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Merck & Co |
| Others |
Value Chain & Pricing Dynamics
WHO syphilis elimination mandates gate both qualified diagnostic supply and premium-tier pricing access for manufacturers seeking hospital network contracts. Procurement committees in the United States and Germany bundle multi-year service agreements with automated platform deployments, compressing margins for non-compliant vendors while rewarding integrated systems with pricing power.
Pricing Analysis
Throughput-based pricing anchors diagnostic platform contracts, with hospitals paying per-test fees scaled to annual volume commitments. Price differentiation rests on FDA clearance tier and multi-analyte capability, separating integrated immunoassay-PCR systems from standalone serology kits. Pricing pressure stems from tender consolidation across French and German hospital networks, eroding spot-purchase premiums. Research laboratories show least price sensitivity due to grant-funded capital cycles, while mid-tier hospitals face acute budget constraints.
Supply Chain Analysis
Direct-to-hospital channels handle diagnostic platform demand, with reference laboratories in the United Kingdom and United States anchoring molecular test distribution. Sterile injectable manufacturing concentrates in FDA-inspected facilities near Philadelphia and Frankfurt, drawing from specialized fermentation feedstocks and aseptic processing lines. Single-source vulnerability characterizes penicillin G supply, as validated facilities in the United States and Switzerland tether European hospital formularies to concentrated production nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neurosyphilis market sits in a technology-transition phase, with PCR-based confirmation protocols displacing serological ambiguity in reference laboratory workflows.
For Market Incumbents: Hedge against platform commoditization by deepening service contract bundling across instrument generations, locking hospital networks into multi-year reagent supply. Accelerate CE-IVDR technical documentation investment to capture first-mover advantage as European regulatory deadlines approach. Counter emerging molecular specialists by integrating serological and nucleic acid testing on unified automated workflows.
For New Entrants and Emerging Players: The gap between premium integrated platforms and economy-tier point-of-care devices opens white-space at mid-tier hospital laboratories seeking modular upgrade paths. Target academic medical centers in the United States with specialized CSF biomarker panels for translational research applications. Pursue strategic partnerships with established reference laboratories to secure distribution without capital-intensive field service infrastructure.
For Investors and Strategic Acquirers: FDA guidance updates on syphilis serological sensitivity requirements are the leading indicator that recombinant antigen production capabilities will command acquisition premiums. Long-term viability favors vertically integrated diagnostic manufacturers with captive immunoassay and molecular platform development. Monitor EMA centralized assessment timelines as signals of European market access velocity for platform consolidators.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Technical Documentation | First-mover positioning secures European hospital procurement committee preference ahead of regulatory deadlines. |
| Multi-Generational Service Contracting | Bundled reagent supply with priority technical support locks hospital network purchasing authority. |
| PCR-Serology Platform Convergence | Unified instruments reduce capital footprint for mid-tier emergency neurology departments. |
| Sterile Injectable Capacity Expansion | Validated aseptic processing lines in FDA-inspected facilities defend antibiotic supply concentration. |
| CSF Biomarker Panel Development | Specialized molecular analytics capture NIH-funded translational research demand at academic medical centers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this neurosyphilis market assessment. Primary interviews with diagnostic platform engineers, hospital laboratory directors, infectious disease specialists, and sterile manufacturing quality officers combined with FDA 510(k) databases, EMA submission portals, and hospital procurement contract registries. Bottom-up test volume modeling and top-down therapeutic expenditure triangulation validated segment-level outputs.
Data-stream reconciliation across diagnostic kit shipments, antibiotic dispensing records, and research laboratory capital equipment orders informed the analytical framework. Segmentation dimensions spanned product type, end user, administration route, and technology platform across the projection horizon. CAGRs derived from trend extrapolation of screening mandate expansion and molecular adoption curves, with sensitivity analysis around penicillin G supply disruption scenarios and diagnostic algorithm update timelines.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time hospital procurement tender outcomes introduce uncertainty bands around near-term pricing trajectories. Forecasts reflect documented assumptions regarding WHO elimination target adherence and screening protocol standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Metabolic Disorders Therapeutics Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Congenital Neutropenia Treatment Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Barotrauma Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market