
 Granulomatosis with Polyangiitis Treatment Market | 2026-2036
Granulomatosis with Polyangiitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Granulomatosis with Polyangiitis Treatment Market Intelligence
The EU Green Deal is decoupling rare disease treatment priorities from traditional volume-based pharmaceutical models across European healthcare systems. F. Hoffmann-La Roche Ltd leverages its deep immunology pipeline to sustain leadership in biologic development for ANCA-associated vasculitis. Bristol-Myers Squibb anchors its position through specialized oncology and immunology manufacturing scale. Pfizer Inc. competes by extending its inflammation and immunology franchise into niche autoimmune indications with high unmet need.
Granulomatosis with polyangiitis treatment encompasses pharmacologic and procedural interventions targeting necrotizing granulomatous inflammation of small vessels, typically combining rituximab or cyclophosphamide with high-dose glucocorticoids to induce remission in severe multisystem disease. Biologics now command the highest margin pools as payers accept premium pricing for targeted B-cell depletion therapies that reduce relapse rates versus conventional immunosuppressants. Intravenous administration dominates hospital-based remission induction, while subcutaneous biologics are gaining traction in outpatient rheumatology centers seeking to shift care from infusion suites to lower-cost settings.
The FDA orphan drug program accelerates development timelines and extends exclusivity for GPA therapies, while the EMA's parallel scientific advice pathway streamlines cross-Atlantic regulatory alignment for rare disease sponsors. Health Canada and the TGA increasingly reference FDA and EMA determinations, creating a consolidated Western regulatory front that shapes global clinical trial design and market access sequencing. Stakeholders must monitor how CMS reimbursement recalibration for hospital outpatient biologic administration reshapes site-of-care economics and manufacturer channel strategy.
Market Dynamics
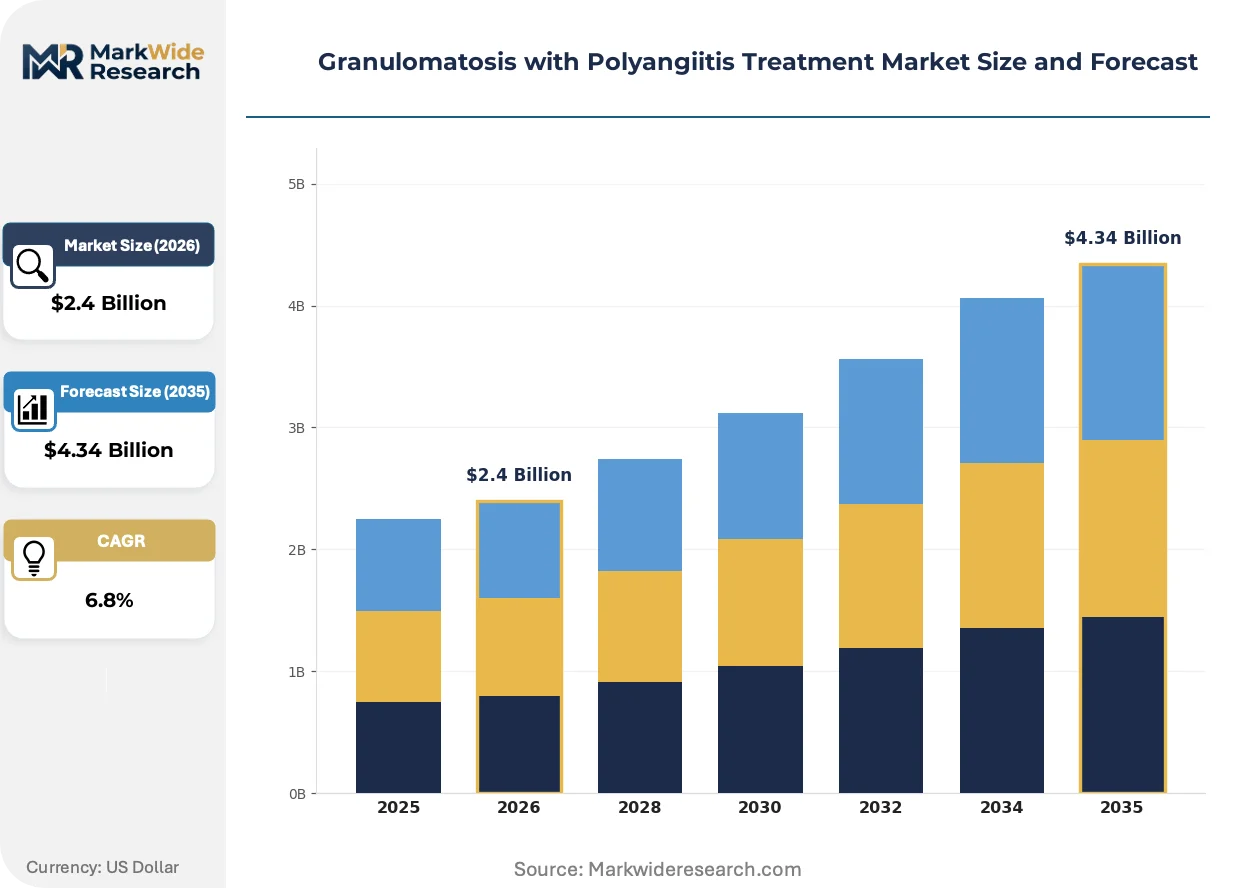
The transition from cyclophosphamide-based regimens to rituximab-dominated protocols has fundamentally restructured treatment economics, compressing hospitalization duration while elevating outpatient biologic administration as the dominant care setting.
Growth Catalysts
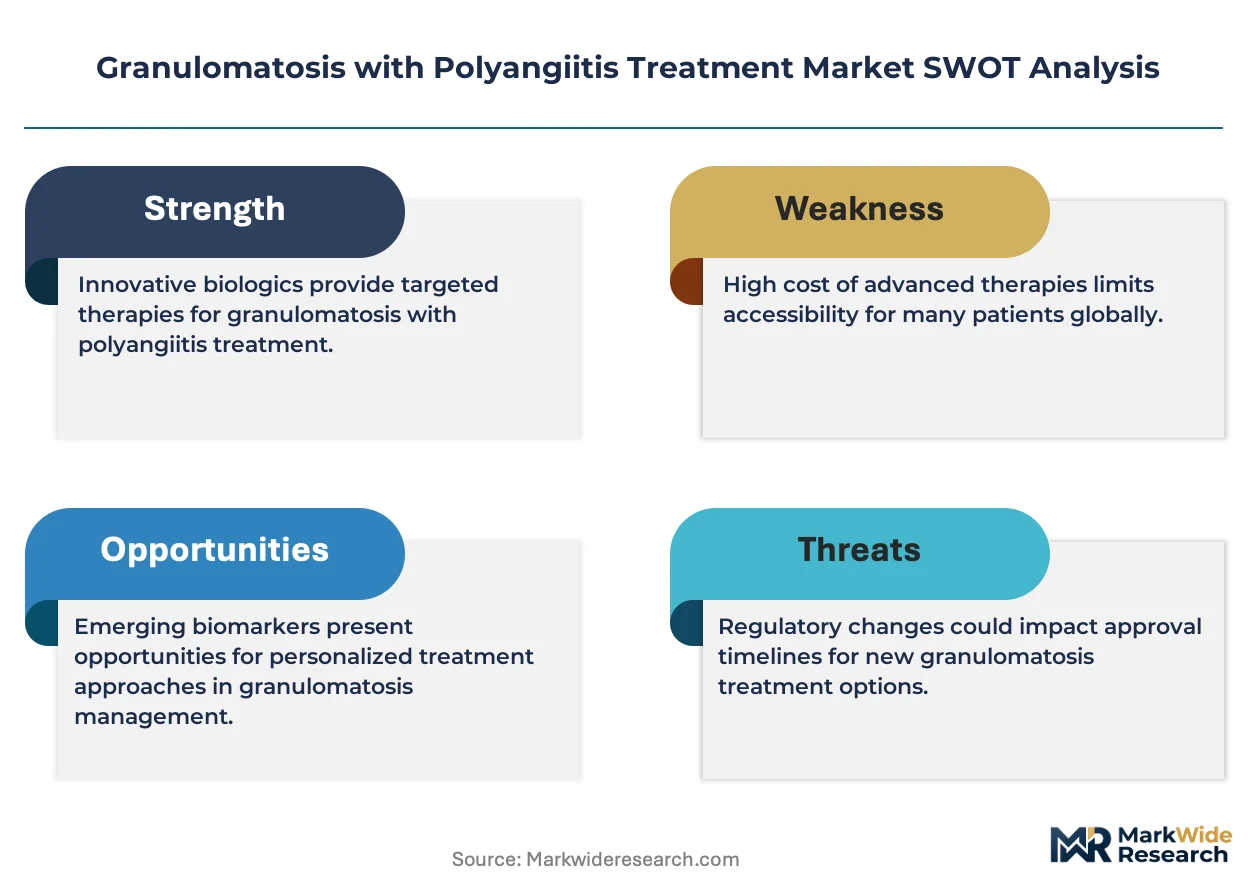
- FDA Orphan Drug Designation:The framework grants seven-year market exclusivity and tax credits for rare disease trials, accelerating sponsor investment in ANCA-associated vasculitis pipelines.
- Specialty Clinic Expansion:Outpatient rheumatology centers in the United States are deploying dedicated infusion infrastructure to capture shifting site-of-care demand.
- Subcutaneous Formulation Development:Self-administered biologics are reducing dependency on hospital-based infusion suites and enabling home-based remission maintenance.
Market Restraints
- Biologic Manufacturing Concentration:Monoclonal antibody production clusters in contract manufacturing organizations across Switzerland and Ireland, creating single-source vulnerability.
- Glucocorticoid Taper Complexity:Prolonged corticosteroid exposure generates diabetes and osteoporosis complications that complicate long-term patient adherence.
- EMA Parallel Assessment Burden:Divergent evidentiary requirements between FDA and EMA scientific advice pathways extend regulatory preparation timelines for sponsors.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan's PMDA streamlined review pathway for rare diseases offers faster access than standard biologic approval timelines.
- Companion Diagnostic Integration:PR3-ANCA versus MPO-ANCA stratification tools enable precision dosing that reduces relapse-driven retreatment costs.
- Telemedicine-Enabled Monitoring:Virtual rheumatology consultations are expanding reach into rural and underserved regions within established markets.
Industry Challenges
- Vasculitis Specialist Scarcity:Fellowship-trained rheumatologists with ANCA-associated disease expertise concentrate in academic medical centers, limiting community access.
- Reimbursement Coding Fragmentation:CMS biologic administration codes separate drug cost from infusion services, creating claims complexity that delays provider payment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granulomatosis with Polyangiitis Treatment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucocorticoids, Immunosuppressants, Biologics, Plasma Exchange Therapy Area: Vasculitis Management, Immune Modulation, Anti-Inflammatory, Remission Induction End User: Specialty Clinics, Rheumatology Centers, Outpatient Facilities, Research Institutions Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | F. Hoffmann-La Roche Ltd, Amgen Inc., Pfizer Inc., Novartis AG, Biogen, Bristol-Myers Squibb, GlaxoSmithKline, Sanofi, Takeda Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granulomatosis with Polyangiitis Treatment Market Strategic Shifts & Innovations
Biologic administration is migrating from hospital infusion centers to ambulatory settings, while regulatory frameworks converge on accelerated rare disease pathways and payers recalibrate value metrics around relapse prevention rather than initial remission rates.
Subcutaneous rituximab formulations are expanding into maintenance therapy protocols previously dominated by intravenous delivery. Community rheumatology practices in Germany and the United States are adopting these alternatives to reduce facility fee exposure. The shift is compressing per-patient treatment costs while preserving manufacturer margin through reduced site-of-care overhead.
The EU Green Deal is redirecting pharmaceutical procurement criteria toward carbon footprint disclosure and sustainable manufacturing certification. EMA guidance on environmental risk assessments now factors into marketing authorization renewals for biologics. Sponsors with energy-intensive monoclonal antibody production are investing in renewable-powered facilities to maintain formulary access across European hospital systems.
Patient advocacy networks are consolidating purchasing influence through specialty pharmacy consortiums that negotiate direct manufacturer contracts. These aggregators bypass traditional wholesale distribution in the United States and extract volume-based rebates previously captured by pharmacy benefit managers. The model is most visible in integrated delivery networks where rheumatology departments align procurement with system-wide specialty pharmacy operations.
Granulomatosis with Polyangiitis Treatment Market Segmentation
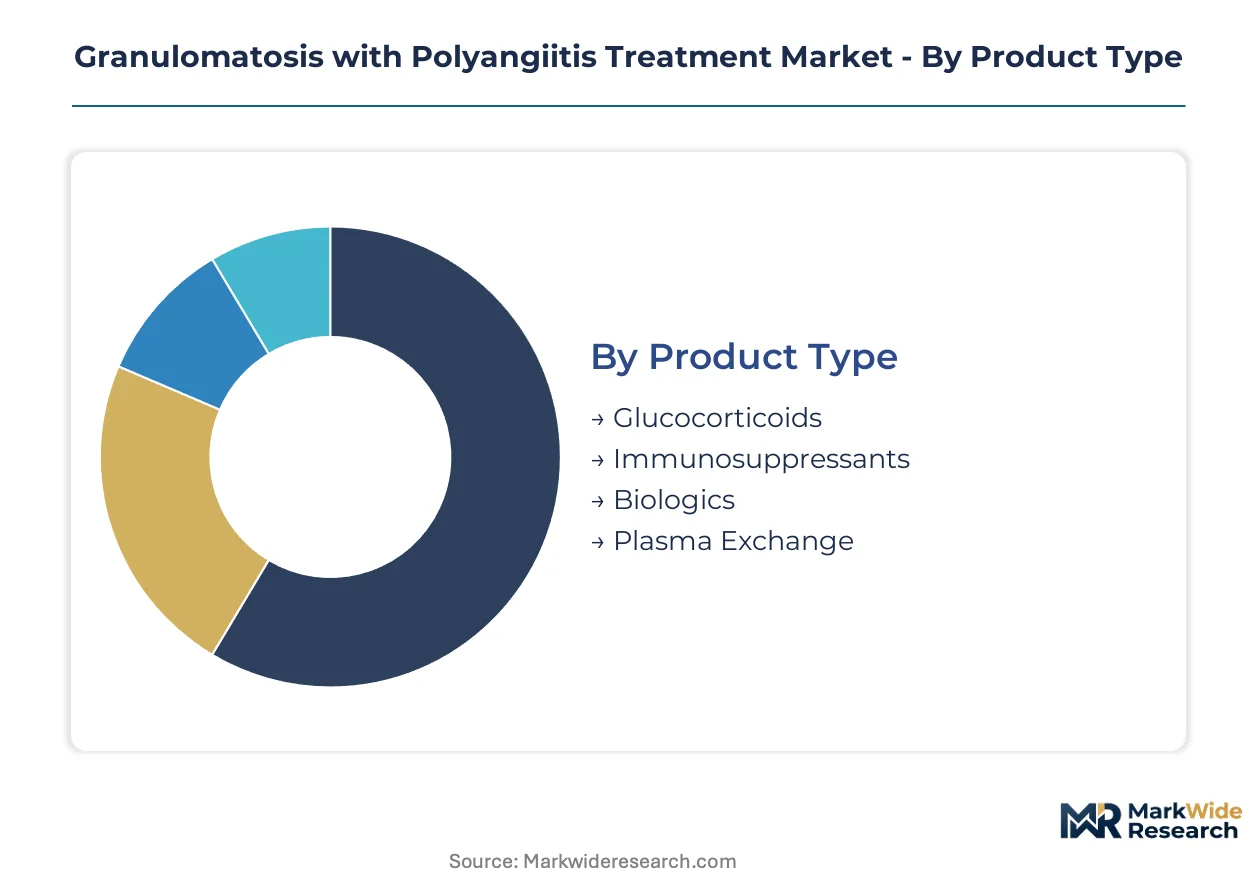
Granulomatosis with polyangiitis treatment segmentation reflects how payers, providers, and patients make distinct trade-offs between efficacy, convenience, and cost across the care continuum. Each category captures a different dimension of clinical decision-making that shapes procurement patterns and manufacturer positioning.
Product Type:
Buyers in this category differentiate primarily by therapeutic intensity required and tolerance for adverse event profiles.
- Biologics:Monoclonal antibodies targeting CD20-positive B cells deliver targeted immunosuppression with reduced off-target toxicity versus conventional agents. Demand concentrates in United States academic medical centers where FDA-accelerated approval pathways and favorable Medicare reimbursement for infused therapies sustain premium positioning.
- Glucocorticoids:High-dose corticosteroid protocols remain foundational for rapid remission induction despite metabolic complications. Rheumatology practices in Germany and France favor tapering regimens that minimize cumulative steroid exposure, driven by EMA guidance on long-term toxicity mitigation.
- Immunosuppressants:Cyclophosphamide and azathioprine provide cost-effective alternatives where biologic access is constrained by formulary restrictions or payer step-therapy requirements.
- Plasma Exchange:Apheresis protocols address severe renal or pulmonary manifestations refractory to pharmacologic intervention, typically reserved for intensive care settings.
Glucocorticoids lead volumes today; biologics are gaining share fastest.
Therapy Area:
Segmentation here tracks the clinical objective—whether acute crisis management or durable immune system recalibration.
- Remission Induction:Aggressive upfront protocols combining rituximab or cyclophosphamide with corticosteroids aim to extinguish active vasculitic inflammation. United States specialty clinics drive demand through dedicated infusion infrastructure and bundled payment models that reward rapid hospital discharge.
- Vasculitis Management:Long-term disease control requires sustained immunomodulation with relapse prevention as the primary endpoint. Japanese rheumatology centers emphasize maintenance regimens that preserve renal function, reflecting PMDA emphasis on organ-sparing outcomes in rare disease approvals.
- Immune Modulation:Tolerance-inducing approaches seek to retrain aberrant adaptive immune responses without persistent pharmacologic suppression.
- Anti-Inflammatory:Symptom-directed therapies address residual constitutional symptoms during convalescence from acute flares.
Remission induction commands the highest per-patient expenditure; vasculitis management delivers the most durable revenue streams.
End User:
Site-of-care economics and specialist availability determine procurement authority across this category.
- Specialty Clinics:Dedicated vasculitis centers employ fellowship-trained rheumatologists with protocolized treatment pathways and embedded clinical trial infrastructure. Cleveland Clinic and Mayo Clinic anchor United States demand through integrated diagnostics and longitudinal outcomes tracking.
- Rheumatology Centers:Community-based practices manage stable patients with standardized biologic administration, capturing volume through convenience and established referral relationships.
- Outpatient Facilities:Ambulatory surgery centers and hospital outpatient departments compete on facility fee structures and payer contract positioning.
- Research Institutions:Academic medical centers with NIH-funded vasculitis consortia drive off-label exploration and next-generation therapy validation.
Specialty clinics concentrate the most complex cases; rheumatology centers are expanding volume fastest.
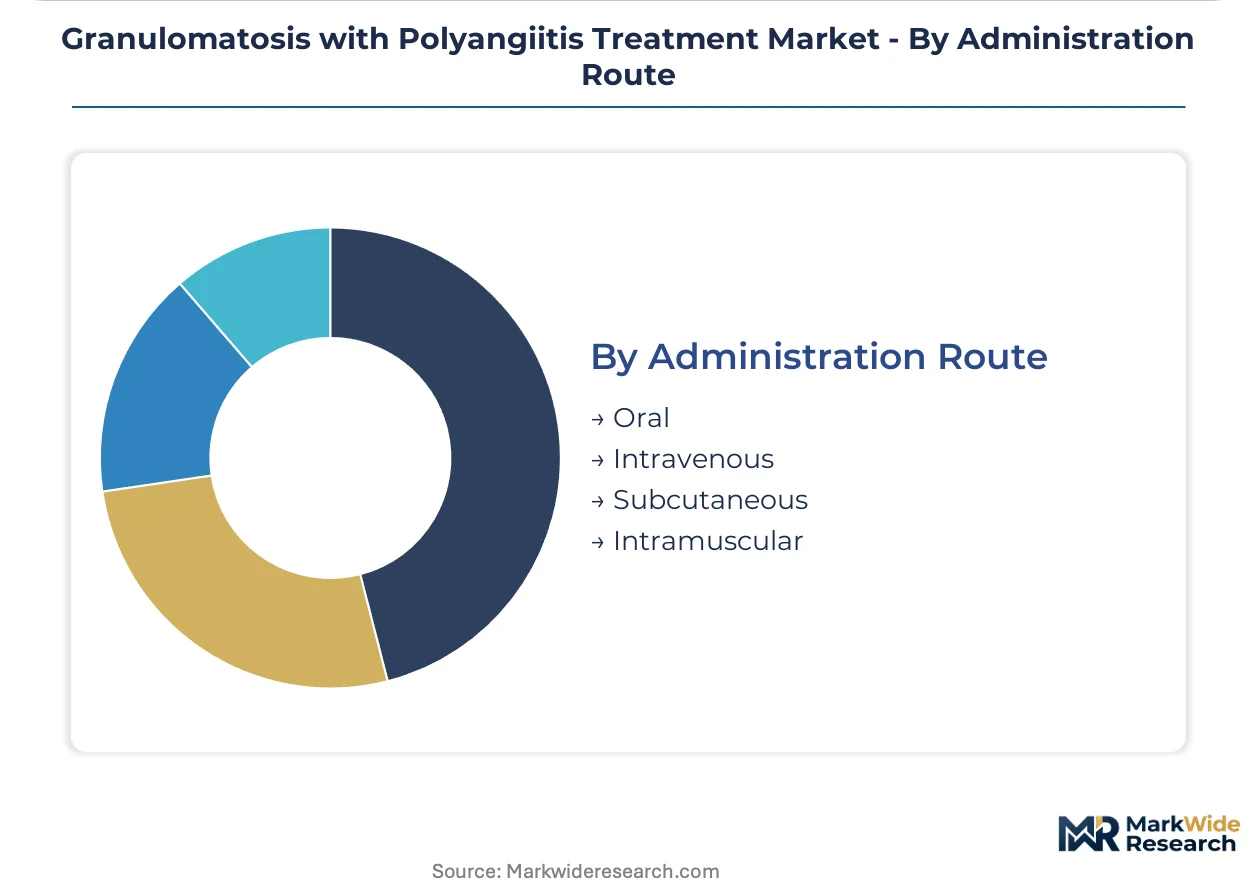
Administration Route:
Patient autonomy and total cost of care separate preferences across delivery modalities.
- Intravenous:Infusion-based delivery ensures complete bioavailability and enables supervised administration of high-potency biologics. Hospital systems in Switzerland and Ireland leverage concentration in contract manufacturing to secure preferential supply terms for infused therapies.
- Subcutaneous:Self-administered formulations reduce facility dependency and enable home-based maintenance therapy. Community practices in Bavaria and Texas are adopting subcutaneous rituximab to shift care from costly infusion suites.
- Oral:Tablet and capsule formulations maximize patient convenience for chronic immunosuppressant maintenance.
- Intramuscular:Depot injections provide sustained corticosteroid release for selected maintenance scenarios.
Intravenous administration retains the largest installed base; subcutaneous delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained vasculitis specialists cluster in academic medical centers across five countries, anchoring treatment demand and clinical trial infrastructure for ANCA-associated diseases.
United States
The Cleveland Clinic and Mayo Clinic anchor demand through integrated vasculitis centers with embedded biologic infusion infrastructure. The FDA orphan drug designation framework grants seven-year exclusivity and tax credits, accelerating rare disease pipeline investment. Boston's Longwood Medical Area concentrates NIH-funded research consortia validating next-generation B-cell depletion protocols.
Germany
Community rheumatology practices in Bavaria and North Rhine-Westphalia adopt subcutaneous rituximab formulations to shift maintenance therapy from hospital suites. EMA guidance on long-term glucocorticoid toxicity mitigation drives tapering protocols that minimize cumulative steroid exposure. Berlin's Charité university hospital anchors the European Vasculitis Society clinical network and outcomes registry.
Japan
PMDA's streamlined review pathway for rare diseases offers faster biologic approval timelines than standard regulatory tracks. Tokyo and Osaka academic centers emphasize organ-sparing maintenance regimens that preserve renal function in ANCA-positive patients. The Kanto region concentrates specialist rheumatologists trained in PMDA-mandated post-market surveillance protocols.
Switzerland
Contract manufacturing organizations in Basel and Zurich anchor monoclonal antibody production for European biologic supply. Swissmedic aligns marketing authorization timelines with EMA centralized procedures, reducing regulatory duplication for sponsors. The country's pharmaceutical manufacturing cluster leverages renewable-powered facilities to meet EU Green Deal procurement criteria.
United Kingdom
London's NHS Foundation Trusts deploy bundled payment models that reward rapid hospital discharge for remission induction therapy. The MHRA operates parallel scientific advice with FDA and EMA to streamline cross-Atlantic trial design for rare disease sponsors. Manchester and Birmingham rheumatology centers expand telemedicine-enabled monitoring into rural catchment areas.
Granulomatosis with Polyangiitis Treatment Market Key Industry Players
Capital-heavy biologic manufacturers compete with asset-light specialty pharmaceutical developers for positioning in rare disease immunology. The market structure concentrates around integrated immunology franchises with approved ANCA-associated vasculitis indications and hospital-based infusion infrastructure. Three archetypes dominate: diversified biopharmaceutical conglomerates with inflammation and immunology divisions, mid-cap immunology specialists with focused rare disease pipelines, and oncology players extending into autoimmune indications. Competitive moves center on subcutaneous formulation development to capture outpatient site-of-care shifts and companion diagnostic integration to enable precision dosing stratification.
Among Swiss and US-based biopharmaceutical conglomerates, F. Hoffmann-La Roche Ltd, Pfizer Inc., and Bristol-Myers Squibb occupy positions representing the integrated immunology archetype. Roche exemplifies deep pipeline investment in B-cell biology through its established CD20-targeted franchise. Pfizer anchors a position extending broad inflammation and immunology capabilities into niche autoimmune indications with high unmet need. Bristol-Myers Squibb sits within the tier leveraging specialized manufacturing scale across oncology and immunology to serve hospital-based infusion demand.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| Biogen |
| Bristol-Myers Squibb |
| GlaxoSmithKline |
| Sanofi |
| Takeda Pharmaceutical |
| Others |
Cost & Logistics Intelligence
Captive biologic manufacturing in Swiss and Irish contract manufacturing organizations anchors supply positions for monoclonal antibody producers while simultaneously preserving pricing power through controlled scarcity and quality certification tiers. This vertical integration pattern concentrates production know-how in Basel and Zurich facilities, enabling manufacturers to command premium positioning for rituximab and next-generation B-cell depletion therapies across European hospital systems subject to EU Green Deal procurement criteria.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy glucocorticoid protocols separates hospital-based infusion therapies from outpatient maintenance regimens. Price differentiation rests on FDA orphan drug exclusivity status and EMA centralized approval tier, with premium tiers capturing bundled payment models in United States academic medical centers. Cost compression in standard immunosuppressant tiers is intensifying because of generic cyclophosphamide entry and step-therapy mandates from United States pharmacy benefit managers. Community rheumatology practices exhibit highest price sensitivity due to thin facility fee margins, while specialty clinics with dedicated infusion infrastructure maintain lowest sensitivity through value-based contracting with integrated delivery networks.
Supply Chain Analysis
Single-source vulnerability sits with contract manufacturing organizations concentrated in Switzerland, Ireland, and Singapore for monoclonal antibody production. Raw material dependencies include Chinese-sourced cell culture media, German-engineered bioreactor systems, and United States-origin affinity chromatography resins. Supply chain risk centers on regulatory restriction exposure from EMA environmental risk assessment requirements affecting marketing authorization renewals. Distribution runs through specialty pharmacy consortiums in the United States and hospital-centric procurement networks in Germany and Japan, with direct manufacturer contracts increasingly bypassing traditional wholesale channels in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA orphan drug designation and EMA parallel scientific advice pathways compound development timelines into durable competitive moats. The seven-year exclusivity framework and tax credit incentives for rare disease trials create structural demand acceleration that rewards early pipeline positioning.
For Market Incumbents: Deepen backward integration into cell line development and bioreactor capacity in Basel and Zurich to defend against emerging biosimilar entrants targeting post-exclusivity rituximab formulations. Prioritize subcutaneous formulation R&D to capture site-of-care shifts from hospital infusion suites to community rheumatology practices, using manufacturing scale as the lever to compress per-dose costs below specialist clinic switching thresholds. For New Entrants and Emerging Players: Capture white-space in Japanese and Australian markets where PMDA and TGA streamlined rare disease pathways offer faster approval timelines than saturated United States and European corridors. Target community rheumatology centers in Texas and Bavaria with telemedicine-enabled monitoring bundles that reduce specialist scarcity constraints, deploying a direct-to-clinic go-to-market angle that bypasses hospital formulary gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap immunology specialists with focused ANCA-associated vasculitis pipelines because regulatory concentration and specialist scarcity limit competitive entry. Long-term viability favors asset-light developers with companion diagnostic integration capabilities and subcutaneous formulation platforms. Watch FDA breakthrough therapy designation grants to non-CD20 biologic mechanisms as the signal indicating inflection in B-cell depletion market share erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Shifts administration from hospital suites to community rheumatology practices in Germany and Texas. |
| Companion Diagnostic Integration | Enables PR3-ANCA versus MPO-ANCA stratification for precision dosing at Cleveland Clinic and Mayo Clinic. |
| EMA Parallel Scientific Advice Pathway | Streamlines cross-Atlantic regulatory alignment for rare disease sponsors seeking unified trial design. |
| Specialty Pharmacy Consortium Partnership | Bypasses pharmacy benefit managers through direct manufacturer contracts with United States integrated delivery networks. |
| Renewable-Powered Manufacturing Certification | Preserves European hospital formulary access under EU Green Deal procurement criteria for Swiss facilities. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors at major United States payers, and hospital procurement managers grounded this analysis in operational reality. Secondary validation drew from FDA orphan drug designation filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across the analysis window.
Bottom-up volume estimates tracked treatment initiation rates by therapy line and administration route, while top-down value calculations anchored in reported biologic pricing and immunosuppressant generic substitution patterns. Segmentation dimensions modeled include product type, therapy area objective, end-user site-of-care category, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to epidemiological prevalence projections and therapy penetration assumptions, with inputs from PMDA approval timelines and NIH-funded vasculitis consortium outcomes data.
Regulatory pathway delays, biosimilar launch acceleration, and glucocorticoid taper protocol revisions are the dominant revision risks that could shift trajectory materially from base-case assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market