
 Ovarian Cancer Diagnostics and Therapeutics Market | 2026-2036
Ovarian Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ovarian Cancer Diagnostics and Therapeutics Market Outlook
Companion diagnostic software licensing is repositioning how pharmaceutical and testing companies capture recurring value from ovarian cancer portfolios. F. Hoffmann-La Roche AG leverages its centralized laboratory platform to sustain high-throughput biomarker testing across European and North American markets. AstraZeneca Plc anchors its PARP inhibitor franchise with integrated diagnostic partnerships that align therapy selection to BRCA mutation status. Quest Diagnostics Incorporated competes on geographic density, operating one of the largest networks of CAP-accredited oncology laboratories in the United States.
Ovarian cancer diagnostics and therapeutics encompass molecular profiling tools, imaging modalities, and systemic treatments designed to detect epithelial ovarian tumors and guide platinum-based or targeted therapeutic intervention. CA-125 and HE4 biomarker assays, combined with transvaginal ultrasound and CT staging protocols, enable risk stratification and treatment response monitoring in gynecologic oncology practice. Biomarker segments command premium pricing due to their role in qualifying patients for PARP inhibitor therapy, while liquid biopsy technology attracts the fastest investment as non-invasive monitoring applications expand beyond recurrence surveillance into front-line screening protocols. Hospitals remain the dominant end-user channel, though outpatient clinics are gaining share where same-day molecular turnaround supports integrated care models.
FDA oversees premarket approval and breakthrough device designation for novel ovarian cancer diagnostics, while EMA coordinates centralized marketing authorization through its Committee for Medicinal Products for Human Use and companion diagnostic consultation procedures. HIPAA governs molecular data portability across United States healthcare networks, directly influencing how diagnostic platforms integrate with electronic health record systems and patient registries. Stakeholders must monitor evolving payer evidence requirements for companion diagnostic coverage, as reimbursement decisions increasingly precede rather than follow regulatory clearance for new testing platforms.
Market Dynamics
Liquid biopsy platforms are compressing diagnostic timelines from weeks to days, forcing hospital laboratories to retool workflows around circulating tumor DNA analysis while Medicare coverage determinations simultaneously reshape reimbursement access for molecular testing.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated premarket pathways compress commercialization timelines for novel biomarker panels, enabling faster patient access to PARP inhibitor companion diagnostics in United States oncology networks.
- Hospital Laboratory Consolidation:Centralized high-throughput molecular testing platforms drive economies of scale in CA-125 and HE4 assay processing, reducing per-test costs across integrated delivery networks.
- EMA Accelerated Assessment:Parallel scientific advice procedures align diagnostic and therapeutic development timelines, shortening the gap between biomarker validation and therapy approval in European markets.
Market Restraints
- Platinum Price Volatility:Fluctuations in platinum group metal costs directly impact the economics of platinum-based chemotherapy manufacturing, squeezing margin stability for systemic treatment portfolios.
- Reagent Supply Concentration:Polymerase chain reaction enzymes and next-generation sequencing chemistries concentrate among a handful of specialty chemical suppliers, creating single-source vulnerability for molecular diagnostic manufacturers.
- HIPAA Data Friction:Molecular data portability restrictions complicate cloud-based algorithm training for AI-assisted pathology platforms, slowing deployment of computational diagnostic tools.
Strategic Opportunities
- Front-Line Screening Protocols:Liquid biopsy technology convergence with proteomic profiling creates white space for asymptomatic population screening programs in Japanese metropolitan health systems.
- Outpatient Clinic Integration:Same-day molecular turnaround capabilities enable point-of-care testing models that capture patient volume migrating from inpatient surgical centers to ambulatory settings.
- IRA Price Negotiation Alignment:Medicare reimbursement restructuring for selected oncology drugs creates incentive for diagnostic-therapy bundling strategies that demonstrate total cost-of-care reduction.
Industry Challenges
- Computational Pathology Talent Scarcity:Shortage of dual-trained professionals fluent in both gynecologic oncology and machine learning model validation constrains AI diagnostic platform deployment.
- CAP Accreditation Timeline Compression:College of American Pathologists laboratory certification processes create bottlenecks for new molecular testing sites seeking to enter competitive United States markets.
- Multi-Omic Data Integration Complexity:Synthesis of genomic, transcriptomic, and imaging data streams requires substantial health information technology infrastructure investment that exceeds smaller laboratory capital capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovarian Cancer Diagnostics and Therapeutics Market |
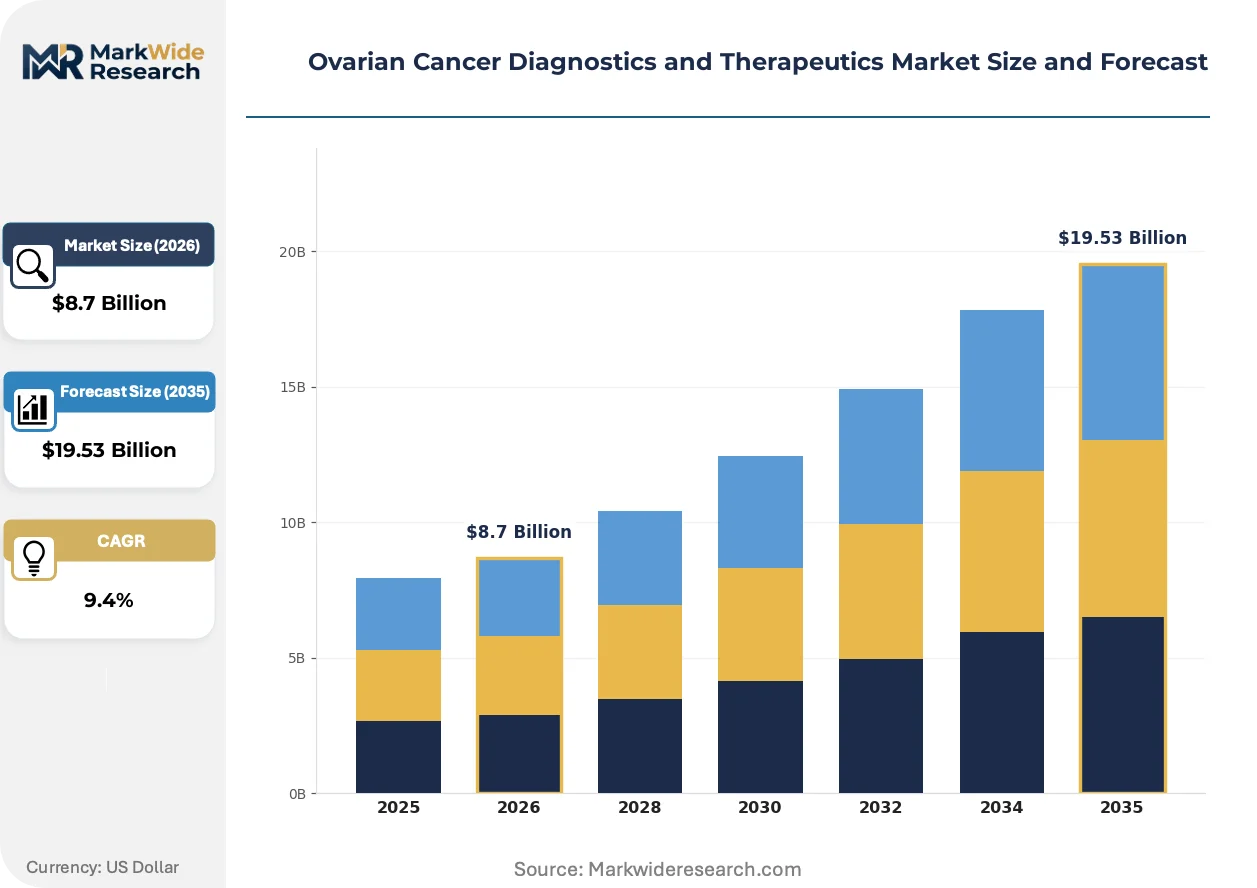
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging, Chemotherapy, Targeted Therapy End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Technology: Liquid Biopsy, MRI, CT Scan, Nano-Diagnostics Application: Screening, Monitoring, Treatment, Research |
| Companies Covered | AstraZeneca Plc, F. Hoffmann-La Roche AG, GlaxoSmithKline Plc, Merck & Co., Inc., Pfizer Inc., Abbott, Johnson & Johnson Services, Inc., Novartis AG, Quest Diagnostics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovarian Cancer Diagnostics and Therapeutics Market Strategic Shifts
Diagnostic modality boundaries are dissolving as imaging, liquid biopsy, and artificial intelligence converge into integrated decision-support systems that compress the interval between suspicion and molecular characterization.
Multi-cancer early detection panels incorporating ovarian cancer signals are expanding into routine wellness screening protocols, with large employer health plans and private payers in the United States piloting coverage for asymptomatic women over 50. Hospital systems are integrating these platforms into annual physical workflows, creating new demand channels outside traditional gynecologic oncology referral patterns. The technology is expanding into front-line primary care settings previously unreachable by specialty molecular diagnostics.
EMA's In Vitro Diagnostic Medical Devices Regulation is forcing European laboratories to recertify legacy CA-125 and HE4 assays under stricter clinical evidence requirements, accelerating consolidation among manufacturers unable to fund post-market surveillance studies. Medium-sized diagnostic firms are exiting the ovarian cancer biomarker segment rather than absorbing compliance costs. German and French hospital networks are prioritizing suppliers with established IVDR technical documentation, reshaping procurement shortlists.
Integrated care models are unbundling diagnostic testing from surgical episode reimbursement, with United States health systems experimenting with separate molecular pathology budgets that decouple biomarker testing from facility fees. Ambulatory surgery centers are capturing volume previously retained by academic medical centers by offering packaged pricing for transvaginal ultrasound plus same-day CA-125 processing. This shift is most visible in Texas and Florida markets where certificate-of-need restrictions on outpatient surgical capacity have loosened.
Ovarian Cancer Diagnostics and Therapeutics Market Segmentation
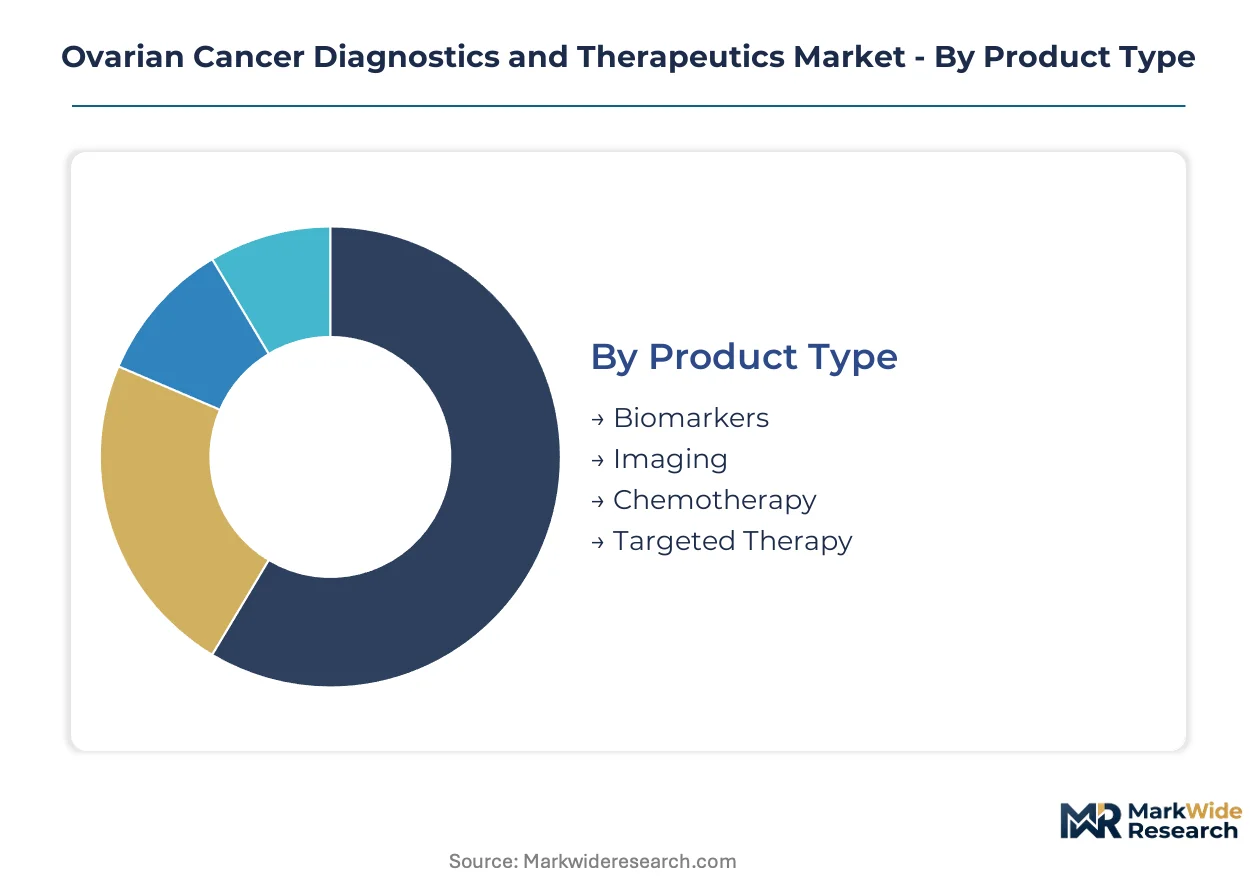
Segmentation in ovarian cancer diagnostics and therapeutics reveals how distinct buyer priorities—clinical urgency, reimbursement pathways, and technological sophistication—reshape procurement patterns across molecular testing, imaging hardware, and systemic therapy categories. Understanding these segment boundaries enables suppliers to align portfolio investments with the specific evidence requirements and workflow constraints that govern hospital laboratory, outpatient clinic, and research institute purchasing decisions.
Product Type:
Hospital procurement committees weigh upfront capital requirements against recurring assay revenue when allocating budgets across diagnostic platforms and therapeutic formularies.
- Biomarkers:CA-125 and HE4 protein assays combined with BRCA mutation testing panels qualify patients for PARP inhibitor therapy selection. United States oncology networks concentrate demand here as Medicare coverage determinations for companion diagnostics expand reimbursement access for molecular qualification testing.
- Targeted Therapy:PARP inhibitors and angiogenesis inhibitors require biomarker-matched patient selection, creating interdependence with diagnostic segments. Japanese metropolitan health systems show concentrated adoption where integrated diagnostic-therapeutic protocols compress time-to-treatment initiation.
- Imaging:Transvaginal ultrasound and CT staging protocols enable surgical planning and treatment response assessment.
- Chemotherapy:Platinum-based regimens remain foundational for first-line epithelial ovarian cancer management.
Biomarkers lead on scale; targeted therapy leads on momentum.
End User:
Workflow integration requirements and reimbursement complexity separate high-volume institutional purchasers from emerging ambulatory competitors.
- Hospitals:Academic medical centers and integrated delivery networks operate centralized CAP-accredited laboratories processing high-throughput CA-125 and HE4 testing. German hospital networks prioritize suppliers with established IVDR technical documentation, reshaping procurement shortlists toward compliant manufacturers.
- Outpatient Clinics:Ambulatory surgery centers in Texas and Florida capture volume from academic centers by offering packaged pricing for transvaginal ultrasound plus same-day biomarker processing. Same-day molecular turnaround capabilities enable point-of-care testing models that attract patient volume migrating from inpatient settings.
- Diagnostic Laboratories:Quest Diagnostics and similar networks compete on geographic density and CAP accreditation status.
- Research Institutes:Multi-omic data integration projects drive demand for advanced sequencing platforms and computational pathology tools.
Hospitals dominate current volume; outpatient clinics expand most rapidly.
Technology:
Speed of diagnostic confirmation and invasiveness of sample collection determine technology substitution patterns across detection and monitoring applications.
- Liquid Biopsy:Circulating tumor DNA analysis compresses diagnostic timelines from weeks to days, enabling non-invasive recurrence surveillance and emerging front-line screening applications. United States hospital laboratories are retooling workflows around ctDNA platforms as Medicare coverage determinations reshape molecular testing reimbursement.
- MRI:Magnetic resonance imaging provides superior soft-tissue contrast for pelvic mass characterization and treatment response assessment. Japanese health systems integrate advanced MRI protocols into standardized gynecologic oncology diagnostic pathways.
- CT Scan:Computed tomography staging protocols guide surgical planning and metastatic disease assessment.
- Nano-Diagnostics:Emerging platforms leverage nanoparticle-based detection for ultra-sensitive biomarker measurement.
CT scan maintains installed base dominance; liquid biopsy climbs the fastest.
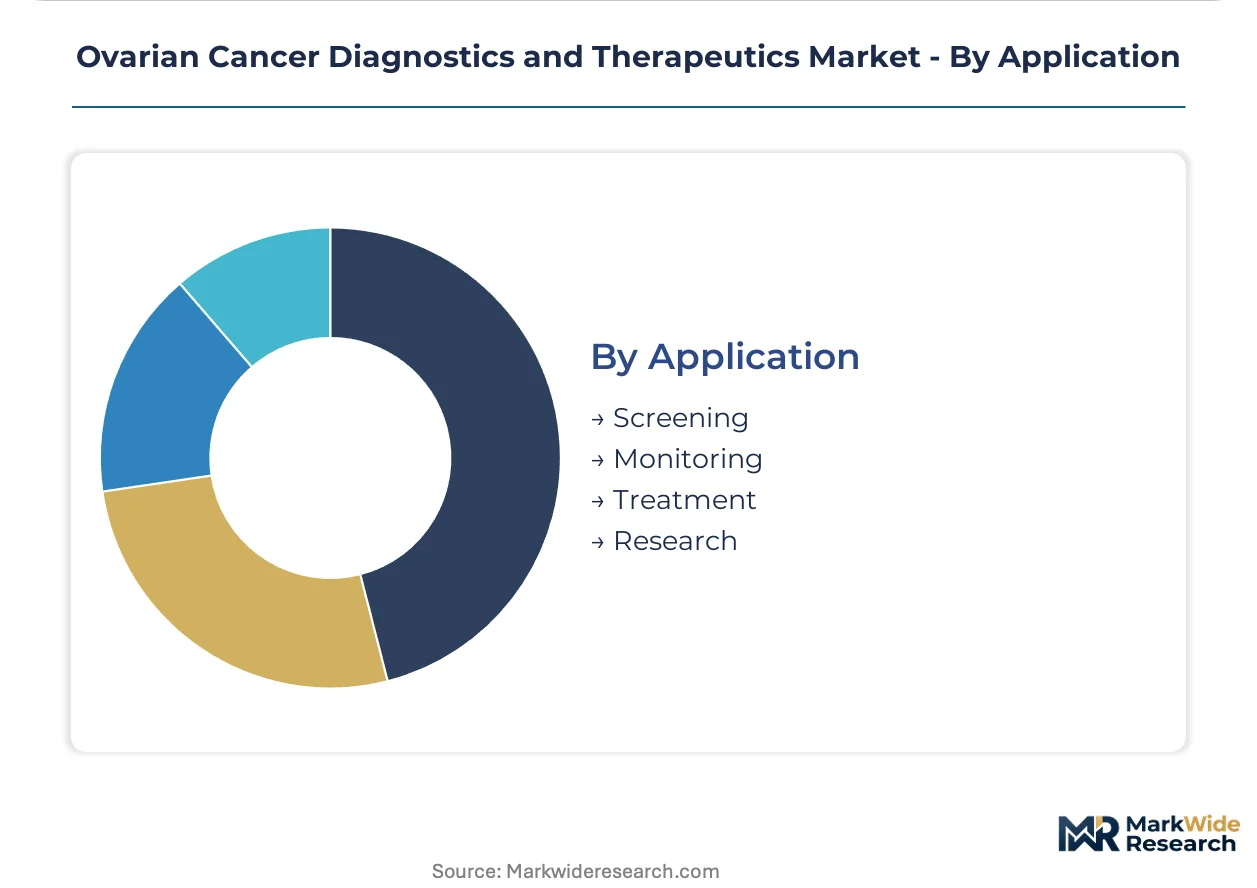
Application:
Regulatory evidence requirements and payer coverage policies create distinct commercialization pathways across detection, intervention, and knowledge-generation use cases.
- Screening:Multi-cancer early detection panels incorporating ovarian cancer signals are expanding into routine wellness protocols. Large employer health plans in the United States pilot coverage for asymptomatic women over 50, creating demand channels outside traditional gynecologic oncology referral patterns.
- Treatment:Therapy selection and response monitoring applications concentrate revenue in biomarker-matched intervention protocols. EMA accelerated assessment pathways align diagnostic and therapeutic development timelines, shortening gaps between biomarker validation and therapy approval in European markets.
- Monitoring:Recurrence surveillance drives repeat testing volume in post-treatment patient populations.
- Research:Clinical trial biomarker qualification and drug-diagnostic co-development projects support pipeline expansion.
Treatment captures current revenue concentration; screening offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's IVDR compliance deadlines are compressing procurement timelines faster than Japan's METI screening pilots are expanding reimbursement access, creating divergent regulatory pressures across developed oncology markets.
United States
Medicare coverage determinations for companion diagnostics are reshaping molecular testing reimbursement in hospital networks. FDA breakthrough device designations compress premarket pathways for novel biomarker panels. The Texas Medical Center cluster in Houston is consolidating liquid biopsy processing capacity across multiple CAP-accredited sites.
Germany
EMA accelerated assessment procedures align diagnostic and therapeutic development timelines for PARP inhibitor combinations. The In Vitro Diagnostic Medical Devices Regulation forces recertification of legacy CA-125 assays under stricter clinical evidence requirements. Bavarian hospital networks in Munich prioritize suppliers with established IVDR technical documentation.
Japan
METI screening pilots for multi-cancer early detection panels are creating reimbursement pathways for asymptomatic population programs. PMDA consultation procedures compress the gap between biomarker validation and therapy approval. Tokyo metropolitan health systems integrate advanced MRI protocols into standardized gynecologic oncology diagnostic pathways.
United Kingdom
NICE technology appraisals for companion diagnostics are reshaping NHS procurement criteria for BRCA mutation testing. The MHRA operates under retained EU law for medical device regulation while developing sovereign pathways. London's Royal Marsden Hospital cluster drives demand for integrated diagnostic-therapeutic protocols in academic medical centers.
India
CDSCO accelerated approval pathways for oncology diagnostics are expanding access to molecular testing in tier-1 cities. The PLI scheme for pharmaceuticals creates indirect demand for companion diagnostic infrastructure. Maharashtra's Mumbai-Pune corridor concentrates private hospital laboratory investment in high-throughput biomarker processing.
Ovarian Cancer Diagnostics and Therapeutics Market Competitive Environment
Top-tier vendors anchor integrated diagnostic-therapeutic platforms, while mid-scale specialists compete on geographic density and CAP accreditation status. The market exhibits tiered consolidation around pharmaceutical-affiliated testing networks and independent laboratory chains. Three archetypes dominate: centralized laboratory platform operators, PARP inhibitor franchise builders with companion diagnostic partnerships, and geographic density competitors with outpatient clinic integration. M&A activity concentrates on molecular testing capabilities, while strategic partnerships align therapy selection algorithms with biomarker qualification protocols.
Within the pharmaceutical-integrated tier, AstraZeneca Plc and F. Hoffmann-La Roche AG exemplify archetypes that bind diagnostic development to therapeutic franchise expansion. Among independent laboratory competitors, Quest Diagnostics Incorporated occupies a position representing geographic density strategies that compete on CAP-accredited network scale. These three entities anchor distinct competitive vectors without exhausting the market's structural diversity.
| Leading Market Players |
|---|
| AstraZeneca Plc |
| F. Hoffmann-La Roche AG |
| GlaxoSmithKline Plc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Abbott |
| Johnson & Johnson Services, Inc. |
| Novartis AG |
| Quest Diagnostics Incorporated |
| Others |
Value Chain & Pricing Dynamics
Captive production of next-generation sequencing chemistries by centralized laboratory platform operators anchors supply security while simultaneously supporting premium pricing for companion diagnostic panels in United States oncology networks. This integration pattern concentrates procurement leverage among manufacturers with in-house polymerase chain reaction enzyme production, insulating them from reagent spot-market volatility that squeezes mid-scale diagnostic firms.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for CA-125 and HE4 biomarker assays as IVDR-compliant manufacturers absorb post-market surveillance costs into premium-tier positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by CAP accreditation status and FDA breakthrough device designation, with academic medical centers least price-sensitive due to bundled reimbursement under Medicare coverage determinations. Cost compression in economy-tier unaccredited testing is intensifying because EMA accelerated assessment pathways favor validated suppliers.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceuticals are reshaping sourcing patterns for companion diagnostic infrastructure in the Mumbai-Pune corridor. Manufacturing concentrates in the United States, Germany, and Japan for high-throughput molecular platforms, while polymerase chain reaction enzymes and sequencing chemistries draw from a concentrated specialty chemical base. Single-source vulnerability in reagent supply creates exposure to export licensing restrictions. Distribution runs through CAP-accredited laboratory networks and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as Medicare coverage determinations for companion diagnostics institutionalize recurring revenue streams from molecular qualification testing. The interdependence between PARP inhibitor therapy expansion and biomarker-matched patient selection sustains durable demand growth.
For Market Incumbents: Acquire liquid biopsy platform capabilities to preempt substitution by non-invasive monitoring technologies. Consolidate CAP-accredited laboratory networks in Texas and Florida where certificate-of-need loosening enables outpatient clinic volume capture. Invest in IVDR technical documentation to defend procurement shortlist positioning as EMA compliance deadlines compress. For New Entrants and Emerging Players: AI-assisted pathology algorithms offer entry pathways where computational diagnostic talent scarcity constrains incumbent deployment. Target front-line screening protocols in Japanese metropolitan health systems where METI pilots expand reimbursement access for multi-cancer early detection panels. Partner with large employer health plans in the United States to bypass traditional gynecologic oncology referral channels. For Investors and Strategic Acquirers: Consolidation pressure builds where medium-sized diagnostic firms exit the ovarian cancer biomarker segment rather than absorbing IVDR compliance costs. The 5-10 year viability window favors platform operators with integrated diagnostic-therapeutic alignment and recurring software licensing revenue. Monitor FDA breakthrough device designation velocity as an inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket pathways compress timelines for novel biomarker panels in United States oncology networks. |
| Hospital System Partnership | Integrated delivery network procurement committees centralize high-throughput molecular testing volume. |
| Software Companion Development | Companion diagnostic software licensing captures recurring value from PARP inhibitor therapy selection algorithms. |
| CE Marking Pathway | IVDR technical documentation requirements reshape European procurement shortlists toward compliant manufacturers. |
| Reimbursement Strategy | Medicare coverage determinations for companion diagnostics reshape molecular testing access in hospital networks. |
Study Parameters
Direct dialogue with hospital laboratory directors, gynecologic oncology clinicians, payer access specialists, and CAP accreditation officers grounded qualitative insights in operational workflow realities. Secondary validation drew from FDA 510(k) filings, EMA centralized marketing authorization records, CMS Medicare coverage determinations, and ClinicalTrials.gov biomarker qualification studies. Bottom-up testing volume estimates and top-down therapeutic market sizing were triangulated to cross-validate segment allocations.
Bottom-up modeling anchored projections in hospital procurement database trends, outpatient clinic expansion patterns, and liquid biopsy platform installation trajectories across the analysis window. Segmentation dimensions included technology modality, end-user channel, biomarker panel complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to Medicare reimbursement restructuring timelines and EMA accelerated assessment pathway completion rates. Companion diagnostic co-development pipeline velocity and PARP inhibitor label expansion patterns informed therapeutic segment projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum group metal cost volatility, reagent supply concentration disruptions, and HIPAA data portability restriction evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Cancer API Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Bone Cancer Treatment Market
Oncology
Osteosarcoma Market
Oncology
Angiosarcomas Treatment Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Metastases Spinal Tumor Market
Oncology
Global Genomics in Cancer Care Market
Oncology
Bone Metastasis Market
Oncology
Radiation Therapy Software Market
Oncology
Particle Therapy Systems Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Precision Oncology Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market