
 Lung Cancer Therapeutics Market | 2026-2036
Lung Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Cancer Therapeutics Market Intelligence
Next-generation biomarker-driven therapy tiers are collapsing the traditional non-small cell lung cancer treatment hierarchy. F. Hoffmann-La Roche Ltd leverages companion diagnostic platforms to anchor its position in PD-L1 stratified care. Bristol-Myers Squibb Company sustains competitive intensity through dual immunotherapy combinations in first-line settings. Merck & Co., Inc. dominates the checkpoint inhibitor segment with extensive clinical trial networks across major academic medical centers.
Lung cancer therapeutics comprise pharmaceutical agents engineered to interrupt oncogenic signaling, modulate immune surveillance, or directly cytotoxic malignant pulmonary cells, typically formulated as small-molecule inhibitors exceeding 90% oral bioavailability or monoclonal antibodies requiring cold-chain intravenous distribution. These agents serve the primary commercial purpose of extending progression-free survival in histologically confirmed lung malignancies while reducing off-target toxicity profiles versus legacy platinum-doublet regimens. Immune checkpoint inhibitors now command the largest margin pool as first-line standards displace chemotherapy across PD-L1-positive populations. Tyrosine kinase inhibitors represent the fastest-growing product category, fueled by expanding EGFR, ALK, and ROS1 mutation testing penetration in community oncology practices.
FDA breakthrough therapy designation and EMA priority medicines pathways are reshaping market access timelines, compressing phase-to-launch intervals while demanding richer biomarker-defined patient subsets. The EU AI Act and FDA's evolving guidance on real-world evidence are converging to redefine post-market surveillance obligations for algorithm-informed treatment selection tools. Stakeholders must monitor how CMS coverage with evidence development frameworks and NICE technology appraisals diverge in their willingness to pay for combination regimens versus sequential monotherapy approaches.
Market Dynamics
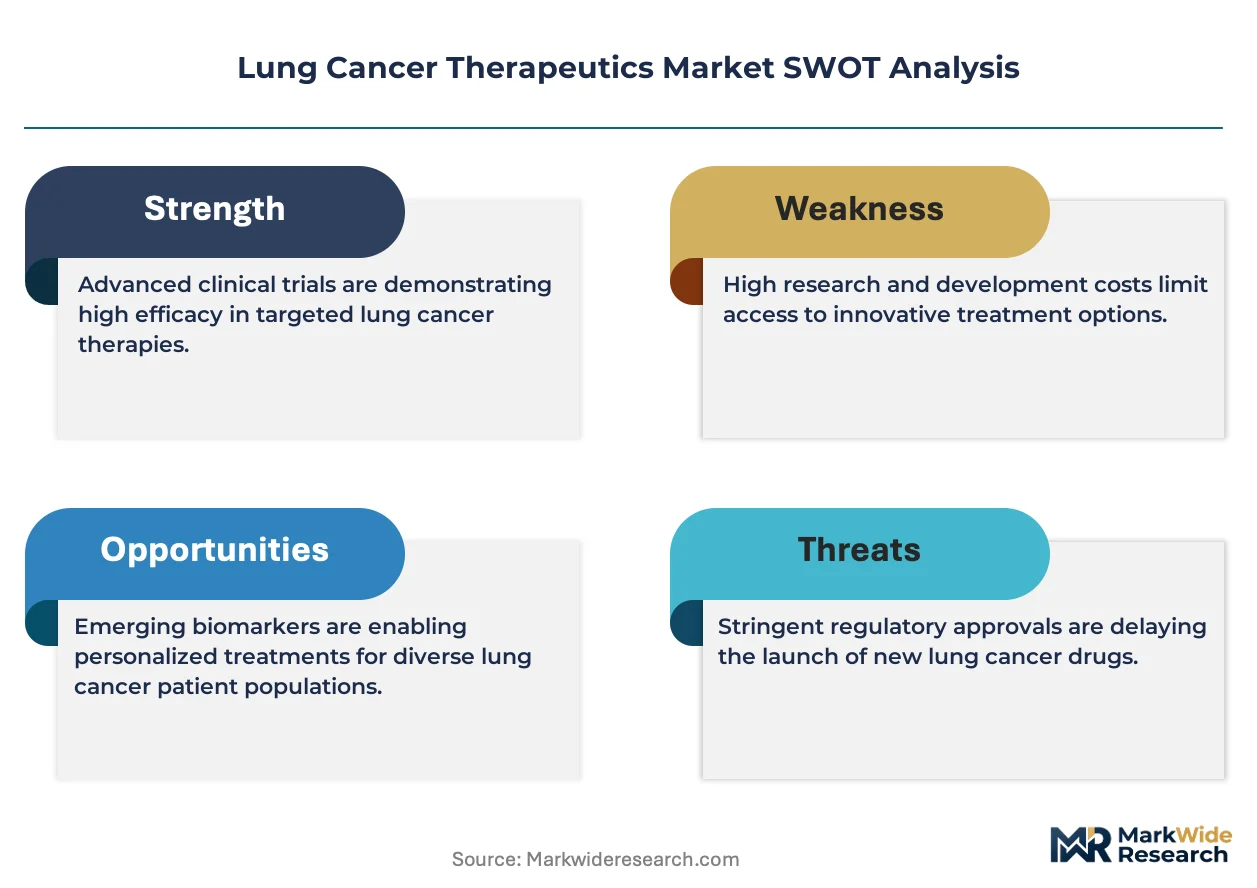
Biomarker-guided patient stratification is collapsing the traditional chemotherapy-first treatment paradigm, forcing rapid reconfiguration of clinical trial design and commercial deployment timelines across oncology networks.
Growth Catalysts
- Accelerated FDA Breakthrough Therapy Pathway:Compressed phase-to-launch timelines enable faster market entry for PD-L1 stratified immunotherapies. Academic medical centers now prioritize enrollment in biomarker-defined trials.
- Community Oncology Testing Penetration:Expanded EGFR, ALK, and ROS1 mutation screening in US regional practices drives targeted therapy demand. Liquid biopsy platforms reduce tissue acquisition barriers.
- Medicare Reimbursement Realignment:CMS coverage frameworks increasingly favor targeted biologics over platinum-doublet regimens. Hospital outpatient departments report favorable margin profiles on checkpoint inhibitors.
Market Restraints
- Cold-Chain Distribution Concentration:Monoclonal antibody therapies require specialized logistics networks dominated by three US specialty pharmacy distributors. Temperature excursion risks create supply vulnerability.
- Companion Diagnostic Fragmentation:Non-harmonized PD-L1 assay platforms across laboratories generate inconsistent patient stratification. Pathology departments face revalidation burdens when switching testing vendors.
- Patent Thicket Complexity:Dense intellectual property layering around checkpoint inhibitor formulations extends licensing negotiations. Biosimilar entry timelines remain uncertain for key reference products.
Strategic Opportunities
- Underserved Small-Cell Lung Cancer Segment:Immunotherapy penetration lags non-small cell categories, creating white space for novel combination regimens. US community oncology practices seek alternatives to etoposide-platinum standards.
- Real-World Evidence Integration:FDA's evolving guidance on post-market surveillance enables label expansion through electronic health record-derived outcomes. Flatiron Health and similar platforms aggregate treatment response data.
- Neoadjuvant Therapy Expansion:Pre-surgical immunotherapy protocols in resectable Stage III populations represent an emerging application. US thoracic surgery centers report rising protocol adoption.
Industry Challenges
- Biomarker Testing Workforce Gap:Molecular pathologist shortages delay turnaround times for mutation profiling. US training programs graduate insufficient specialists to match testing volume growth.
- Clinical Trial Site Competition:Patient recruitment intensifies across overlapping checkpoint inhibitor studies. Principal investigators report enrollment compression at major academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Cancer Therapeutics Market |
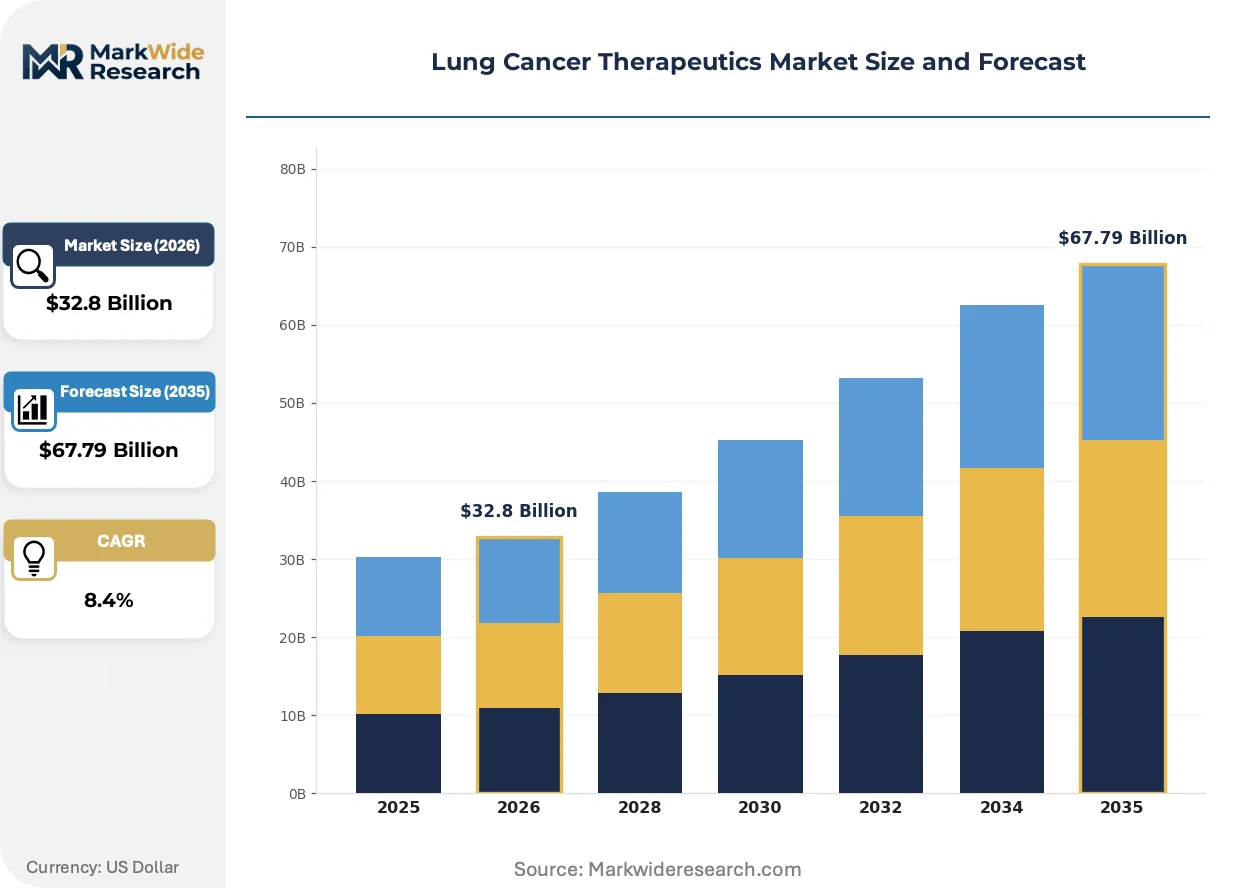
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyrosine Kinase Inhibitors, Immune Checkpoint Inhibitors, Chemotherapy Drugs, Monoclonal Antibodies, Angiogenesis Inhibitors Therapy Area: Non-small Cell Carcinoma, Small Cell Carcinoma, Mesothelioma, Carcinoid Tumors End User: Hospitals, Oncology Clinics, Research Institutes, Diagnostic Laboratories Mode of Administration: Oral, Intravenous, Intramuscular, Inhalation, Subcutaneous |
| Companies Covered | F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Merck & Co., Inc., AstraZeneca, Pfizer Inc., Eli Lilly and Company, Novartis AG, Boehringer Ingelheim, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Cancer Therapeutics Market Strategic Shifts & Innovations
Next-generation sequencing platforms and artificial intelligence-informed treatment selection tools are converging to reshape how oncologists match patients to precision therapies, compressing decision timelines while demanding richer data infrastructure.
Next-generation sequencing panels are miniaturizing from tissue-based to circulating tumor DNA platforms, enabling serial monitoring without repeat biopsies. US community oncology practices adopt liquid biopsy workflows at accelerating pace. This technology is miniaturizing the diagnostic footprint required for treatment selection, shifting molecular profiling from academic centers to regional clinics.
The EU AI Act's risk classification framework for algorithm-informed treatment selection tools imposes new conformity assessment obligations on decision-support software. European oncology networks must validate AI-driven patient matching against clinical outcome benchmarks. Multinational pharmaceutical sponsors face divergent evidentiary requirements across EMA member states for algorithm-integrated protocols.
Hospital and physician buying committees now unbundle clinical trial participation from formulary placement decisions, treating research access as a separate procurement category. US integrated delivery networks negotiate trial site fees independently from drug acquisition contracts. This behavioral shift concentrates investigator-initiated study sponsorship within select academic medical centers.
Lung Cancer Therapeutics Market Segmentation
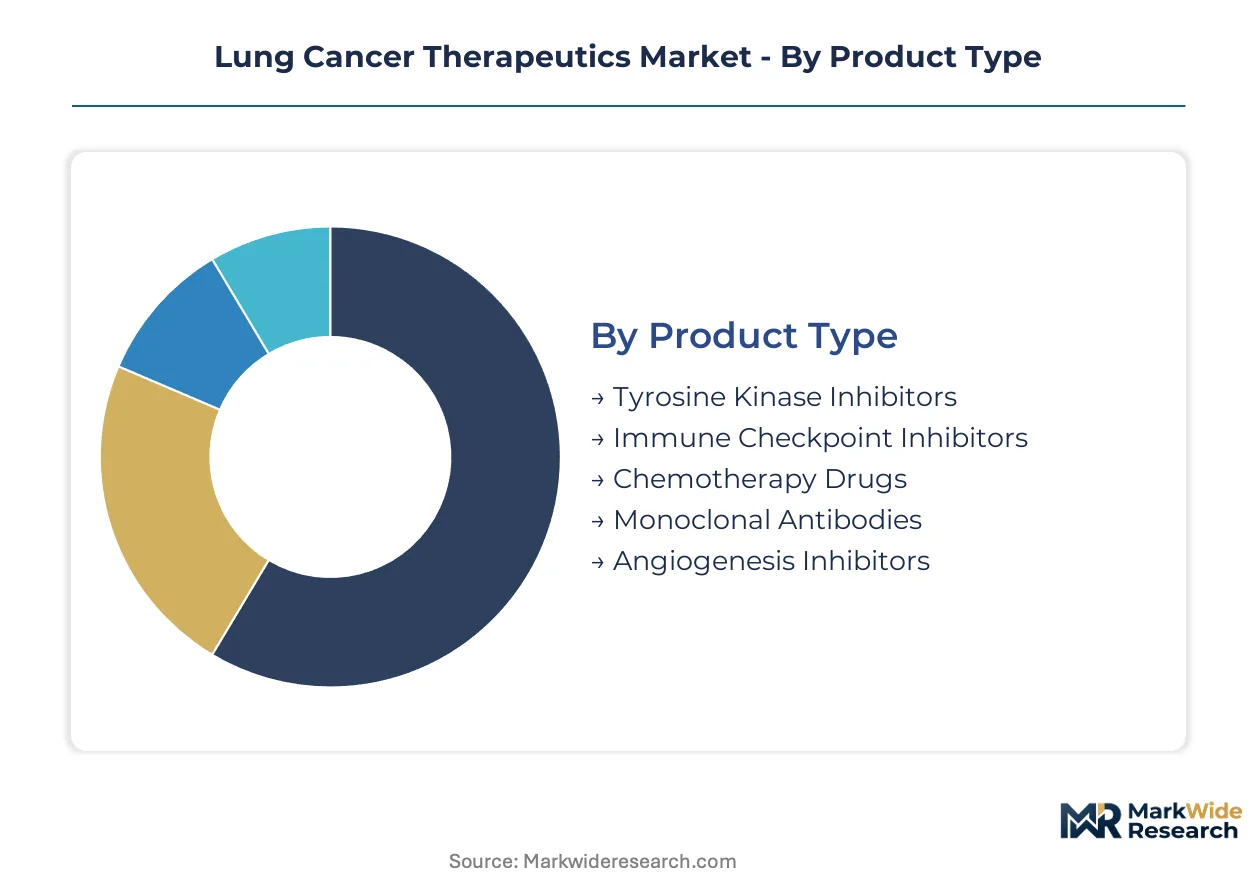
Lung cancer therapeutics flow through distinct commercial channels shaped by product characteristics, reimbursement pathways, and site-of-care economics. Each segment category carries specific margin profiles, cold-chain requirements, and prescriber access patterns that determine competitive positioning.
Product Type:
Channel distribution concentrates intravenous biologics through hospital outpatient departments, while oral small molecules flow through specialty pharmacy networks. Margin capture varies substantially across these pathways.
- Immune Checkpoint Inhibitors:PD-1 and PD-L1 monoclonal antibodies require cold-chain intravenous administration in hospital settings. Medicare reimbursement at ASP plus 4.3% anchors hospital margin structures for pembrolizumab and nivolumab regimens.
- Tyrosine Kinase Inhibitors:Oral EGFR and ALK inhibitors achieve 90%+ bioavailability with outpatient dispensing. Community oncology practices favor these agents for their favorable reimbursement under Medicare Part D and reduced chair time requirements.
- Chemotherapy Drugs:Platinum-doublet regimens remain embedded in bundled payment models despite margin compression.
- Monoclonal Antibodies:Bevacizumab and similar agents concentrate in academic medical center formularies.
- Angiogenesis Inhibitors:Ramucirumab and comparable therapies serve salvage settings with restricted access protocols.
By volume, chemotherapy drugs retain the largest patient exposure. By growth pace, tyrosine kinase inhibitors are expanding most quickly.
Therapy Area:
Cost tier stratification separates first-line immunotherapy-eligible populations from salvage chemotherapy segments, with biomarker testing penetration determining addressable market boundaries.
- Non-small Cell Carcinoma:Adenocarcinoma and squamous cell histologies command 85% of development investment. PD-L1 stratification now dictates first-line pembrolizumab eligibility across US community practices.
- Small Cell Carcinoma:Limited-stage and extensive-stage disease categories lag immunotherapy penetration. Durvalumab consolidation in limited-stage settings represents an emerging application with distinct trial infrastructure.
- Mesothelioma:Pleural and peritoneal variants require specialized thoracic surgery center referral patterns.
- Carcinoid Tumors:Neuroendocrine histologies occupy niche somatostatin analog treatment pathways.
Non-small cell carcinoma generates the highest revenue concentration. Small cell carcinoma offers the steepest expansion trajectory as immunotherapy protocols penetrate.
End User:
Customer type segmentation reveals divergent procurement authority, with integrated delivery networks consolidating purchasing for hospital systems while independent oncology practices retain formulary autonomy.
- Hospitals:Academic medical centers and community hospital systems administer intravenous biologics under 340B pricing advantages. Outpatient departments capture infusion fees alongside drug margins.
- Oncology Clinics:US community practices concentrate oral targeted therapy dispensing. Flatiron Health and similar platforms aggregate real-world evidence from these sites.
- Research Institutes:NCI-designated cancer centers anchor early-phase trial enrollment.
- Diagnostic Laboratories:Reference labs and hospital pathology departments execute companion diagnostic testing.
Hospitals dominate intravenous therapy volume. Oncology clinics are gaining share fastest in oral agent categories.
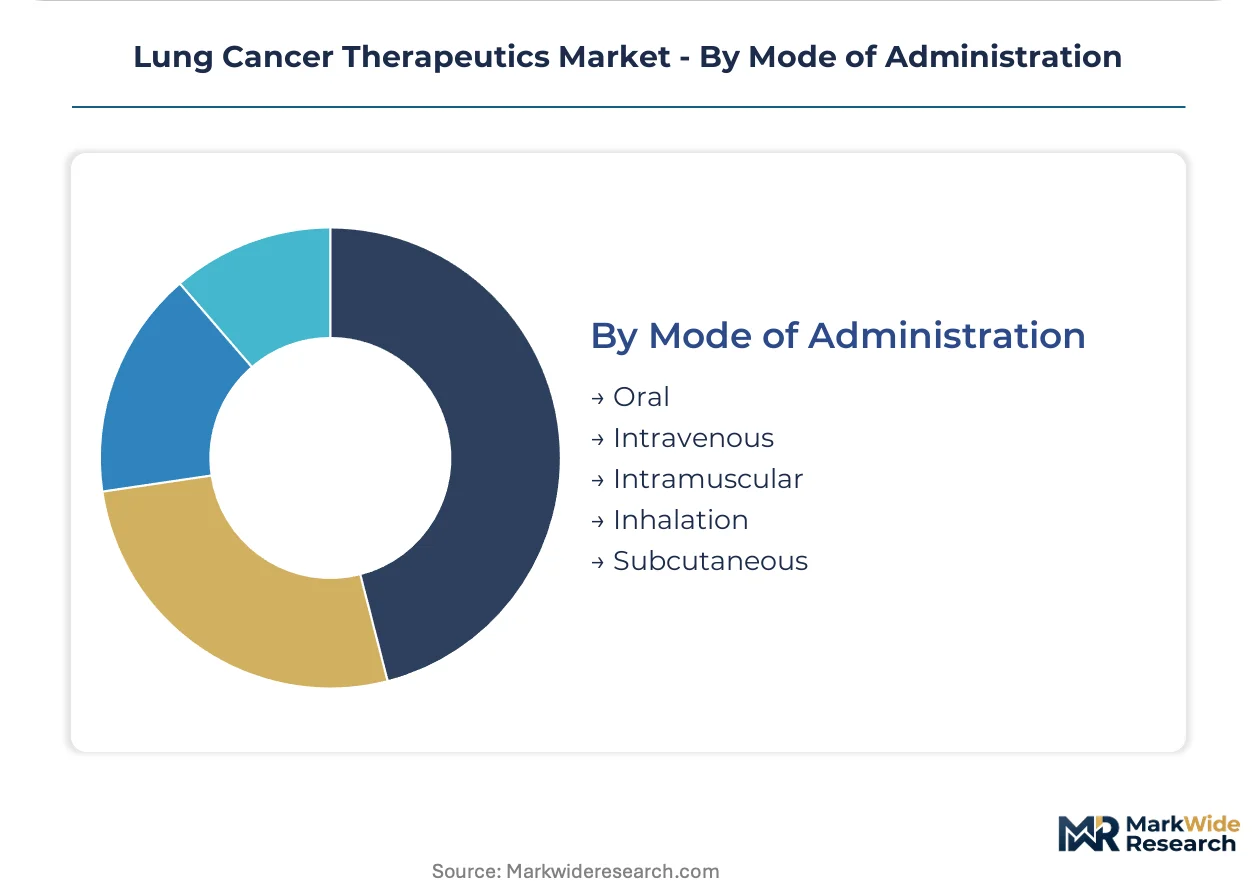
Mode of Administration:
Supply concentration aligns with administration complexity, with intravenous networks requiring three specialized US distributors while oral agents flow through conventional pharmaceutical wholesale.
- Intravenous:Cold-chain monoclonal antibodies and checkpoint inhibitors demand temperature-controlled logistics. McKesson, AmerisourceBergen, and Cardinal Health specialty divisions control distribution.
- Oral:Tyrosine kinase inhibitors and hormone therapies bypass infusion infrastructure. Patient assistance programs and hub services manage adherence.
- Intramuscular:Depot formulations serve limited maintenance applications.
- Inhalation:Localized delivery approaches remain investigational.
- Subcutaneous:Fixed-dose combination pens reduce chair time versus intravenous equivalents.
Intravenous administration retains the largest current volume. Subcutaneous formulations are climbing the fastest as developers seek site-of-care flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in lung cancer therapeutics tilt heavily toward net-importing markets, with the United States absorbing the largest share of biologic shipments while Switzerland and Ireland serve as primary export hubs for active pharmaceutical ingredients and finished monoclonal antibodies.
United States
Medicare reimbursement frameworks favoring checkpoint inhibitors over chemotherapy drive hospital outpatient department procurement. FDA breakthrough therapy designations compress phase-to-launch timelines for PD-L1 stratified protocols. The Boston-Cambridge corridor anchors early-phase trial enrollment across NCI-designated cancer centers.
Germany
EMA centralized marketing authorizations enable rapid adoption of immunotherapy combinations across statutory health insurance funds. The EU AI Act imposes conformity assessment obligations on algorithm-informed treatment selection tools deployed in Munich and Heidelberg oncology networks. Baden-Württemberg's pharmaceutical cluster concentrates companion diagnostic manufacturing.
Switzerland
Swissmedic's streamlined review procedures attract multinational sponsors seeking parallel EMA-FDA submissions. Basel's biopharma corridor hosts integrated R&D and manufacturing operations for monoclonal antibody exports. The country's bilateral trade agreements facilitate cold-chain distribution into EU member states.
Japan
PMDA's sakigake designation system accelerates access to novel tyrosine kinase inhibitors for EGFR-mutant populations. METI's healthcare technology assessment frameworks influence pricing negotiations for combination regimens. The Kanto region's academic medical centers concentrate real-world evidence collection for post-market surveillance.
China
NMPA's priority review pathways for innovative biologics expand domestic manufacturing capacity for PD-1 inhibitors. National reimbursement drug list updates determine market access for imported checkpoint inhibitors versus local alternatives. Shanghai's Zhangjiang Hi-Tech Park clusters contract development and manufacturing organizations serving multinational sponsors.
Lung Cancer Therapeutics Market Key Industry Players
Listed leaders compete with private specialists across R&D funding intensity and clinical trial network reach. The market structure concentrates around vertically integrated pharmaceutical conglomerates with companion diagnostic capabilities, mid-cap biotech firms pursuing single-asset strategies, and generic manufacturers awaiting biosimilar entry windows. Strategic moves center on biomarker platform acquisitions and neoadjuvant therapy indication expansions.
Within the integrated conglomerate tier, F. Hoffmann-La Roche Ltd and Bristol-Myers Squibb Company exemplify archetypes combining diagnostic and therapeutic assets. Merck & Co., Inc. occupies a position emphasizing extensive academic medical center trial networks. These three entities represent distinct approaches to PD-L1 stratified care: companion diagnostic anchoring, dual immunotherapy combination development, and first-line checkpoint inhibitor dominance respectively.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| AstraZeneca |
| Pfizer Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Boehringer Ingelheim |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
Scale economies in monoclonal antibody fermentation capacity anchor supply concentration among three US specialty pharmacy distributors, compressing price floors for checkpoint inhibitors while elevating margin capture for hospital outpatient departments under Medicare ASP plus 4.3% reimbursement frameworks. Cold-chain infrastructure investments in Switzerland and Ireland reinforce European supply security, yet temperature excursion risks during transatlantic shipment create pricing volatility for intravenous biologics.
Pricing Analysis
Hospital outpatient department buyers anchor pricing structures around Medicare reimbursement benchmarks, with ASP-based formulas favoring checkpoint inhibitors over platinum-doublet regimens. Price differentiation rests on PD-L1 assay platform certification tiers and companion diagnostic bundling arrangements, while volume scale discounts concentrate among integrated delivery networks. Pricing pressure stems from biosimilar entry anticipation for reference monoclonal antibodies, compressing net realized prices in salvage therapy segments. Community oncology practices exhibit highest price sensitivity due to Medicare Part D formulary constraints, whereas academic medical centers demonstrate lowest sensitivity given 340B pricing advantages and research subsidy flows.
Supply Chain Analysis
Just-in-time inventory strategies dominate intravenous biologic workflows, with hospital outpatient departments maintaining 7-14 day safety stocks given cold-chain reliability requirements. Geographic supply concentration centers on Switzerland, Ireland, and the United States for finished monoclonal antibody production, while active pharmaceutical ingredient sourcing draws from China and India for small-molecule kinase inhibitors. Raw material dependencies include cell culture media, single-use bioreactor components, and high-purity solvents for formulation. Single-source vulnerability pervades specialty distributor networks, with McKesson, AmerisourceBergen, and Cardinal Health controlling temperature-controlled logistics. Distribution runs through hospital-centric direct-to-site models for intravenous agents, contrasting with specialty pharmacy hub-and-spoke networks for oral tyrosine kinase inhibitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomarker testing fragmentation across community oncology practices creates structural white space for diagnostic-therapeutic bundling specialists, as molecular pathologist shortages delay patient stratification and extend treatment initiation timelines.
For Market Incumbents: Shield checkpoint inhibitor margin pools by deepening companion diagnostic platform control through pathology laboratory partnerships, countering biosimilar entry threats. Prioritize neoadjuvant therapy indication expansion in resectable Stage III populations to extend patent-protected revenue duration. Vertical integration into liquid biopsy manufacturing secures supply chain autonomy against CDx vendor switching costs. For New Entrants and Emerging Players: Post-market surveillance data aggregation services represent an under-served layer where incumbents under-serve community oncology practices lacking electronic health record integration capabilities. Target small-cell lung carcinoma immunotherapy combinations as the most penetrable segment, given durvalumab consolidation protocols still emerging in limited-stage settings. Pursue FDA breakthrough therapy designation pathways to compress phase-to-launch timelines and secure academic medical center trial sponsorship. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated diagnostic-therapeutic platforms with real-world evidence generation infrastructure over single-asset biotech specialists. Long-term viability across the analysis window hinges on algorithm-informed treatment selection tool validation against EU AI Act conformity assessment benchmarks. Acquisition target archetypes include liquid biopsy platform developers with Medicare coverage determination momentum. The signal to watch is CMS coverage with evidence development framework expansion for combination regimens versus sequential monotherapy approaches.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Platform Integration | Roche's PD-L1 assay anchoring cements pembrolizumab eligibility determination across community pathology networks. |
| Neoadjuvant Therapy Indication Expansion | Pre-surgical immunotherapy protocols in resectable Stage III populations unlock thoracic surgery center formulary placement. |
| Real-World Evidence Infrastructure Buildout | Flatiron Health platform aggregation enables FDA label expansion through electronic health record-derived outcomes validation. |
| Liquid Biopsy Workflow Adoption | Circulating tumor DNA miniaturization shifts molecular profiling from academic centers to regional clinics, expanding addressable testing volume. |
| Dual Immunotherapy Combination Development | Bristol-Myers Squibb's nivolumab plus ipilimumab regimens sustain competitive intensity in PD-L1 positive first-line settings. |
Research Approach
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchors the qualitative findings, with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling triangulates against top-down pharmaceutical revenue aggregation across therapy area and administration route segmentations.
Sensitivity analysis frameworks test forecast robustness across biomarker testing penetration scenarios, immunotherapy combination adoption curves, and biosimilar entry timing assumptions throughout the projection horizon. Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs derive from patient volume projections multiplied by net realized price estimates, incorporating Medicare reimbursement trajectory assumptions and pipeline asset probability-weighted revenue contributions.
Forecasts assume regulatory continuity in FDA breakthrough therapy designation pathways and EMA priority medicines frameworks; material policy shifts would require re-modeling. Revision becomes warranted when companion diagnostic harmonization standards cross implementation thresholds or when CMS coverage with evidence development frameworks materially expand combination regimen reimbursement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Cirrhosis Management Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market