
 Barotrauma Market | 2026-2036
Barotrauma Market Size, Share, and Industry Trends Forecast 2026-2036
Barotrauma Market Analysis
Silicone-based suction catheters and seals is shifting toward polymer composites in barotrauma surgical instruments, reducing device failure rates under extreme pressure differentials. Medtronic leverages its endoscopic platform expertise to anchor positions in aviation-related barotrauma diagnostics. Johnson & Johnson sustains competitive footing through broad surgical instrument portfolios serving trauma centers. Smith & Nephew specializes in advanced wound management adjacent to hyperbaric oxygen therapy protocols.
Barotrauma denotes tissue injury caused by pressure differential between gas-filled body cavities and surrounding environmental pressure, typically occurring at pressure changes exceeding 1-2 atmospheres in lungs, ears, sinuses, or gastrointestinal tract. Hyperbaric oxygen therapy devices deliver 100% oxygen at 2.0-3.0 atmospheres absolute to reverse gas embolism and accelerate tissue repair. Diagnostic equipment leads product type revenue owing to imaging-intensive emergency protocols, while suction devices represent the fastest-growing segment as pre-hospital and battlefield applications expand. Military end users command premium pricing for portable systems, whereas hospitals concentrate volume across underwater activity and aviation applications.
FDA 510(k) clearance requirements and CE marking under the EU Medical Device Regulation shape device commercialization timelines and clinical evidence standards for hyperbaric systems. ISO 13485 quality management certification governs manufacturing consistency across international supply chains. Stakeholders must monitor evolving reimbursement codes for hyperbaric oxygen therapy as payors recalibrate coverage for prophylactic versus emergent indications.
Market Dynamics
Polymer composite materials are displacing silicone in barotrauma surgical instruments, forcing manufacturers to retool production lines and recertify devices under tightened FDA 510(k) and EU MDR pathways. This materials transition concentrates capital expenditure among mid-tier suppliers lacking in-house polymer processing capabilities.
Growth Catalysts
- EU MDR compliance deadlines:Stricter CE marking requirements for hyperbaric oxygen therapy devices are filtering out marginal competitors and consolidating procurement toward certified manufacturers across German and French hospital networks.
- Military pre-hospital protocols:NATO standardization of portable suction systems for battlefield barotrauma is creating dedicated procurement channels for ruggedized diagnostic equipment.
- Recreational diving incident reporting:Mandatory decompression sickness documentation in Australia and the United States is expanding clinical data pools and justifying hyperbaric chamber installations at coastal trauma centers.
Market Restraints
- Specialized polymer feedstock concentration:Medical-grade polymer composite suppliers cluster in Germany and Switzerland, exposing device manufacturers to single-source risk and input price volatility.
- Hyperbaric chamber installation costs:Facility infrastructure requirements including reinforced flooring and specialized ventilation compress capital deployment timelines for hospital systems.
- Reimbursement code fragmentation:CMS and private payor misalignment on prophylactic versus emergent hyperbaric oxygen therapy indications creates revenue uncertainty for treatment centers.
Strategic Opportunities
- Indian coastal trauma network expansion:Underpenetrated decompression sickness treatment infrastructure along the Andaman Islands and Goa diving corridors offers first-mover positioning for chamber operators.
- Aviation telemedicine integration:Convergence of in-flight diagnostic sensors with ground-based hyperbaric consultation protocols enables real-time barotrauma triage for commercial airline medical kits.
- Brazilian ANVISA fast-track pathway:Emerging regulatory priority for critical care devices accelerates market entry timelines for portable suction systems serving offshore oil platform clinics.
Industry Challenges
- Hyperbaric technician certification scarcity:Limited training pipeline for chamber operators creates staffing bottlenecks at expanding treatment centers in the United States and Australia.
- Legacy silicone device obsolescence:FDA 510(k) substantial equivalence pathways for polymer-based successors require extensive biocompatibility testing, extending product development cycles.
- Multi-site quality system harmonization:ISO 13485 audit complexity escalates for manufacturers operating polymer molding in Asia alongside final assembly in North America or Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barotrauma Market |
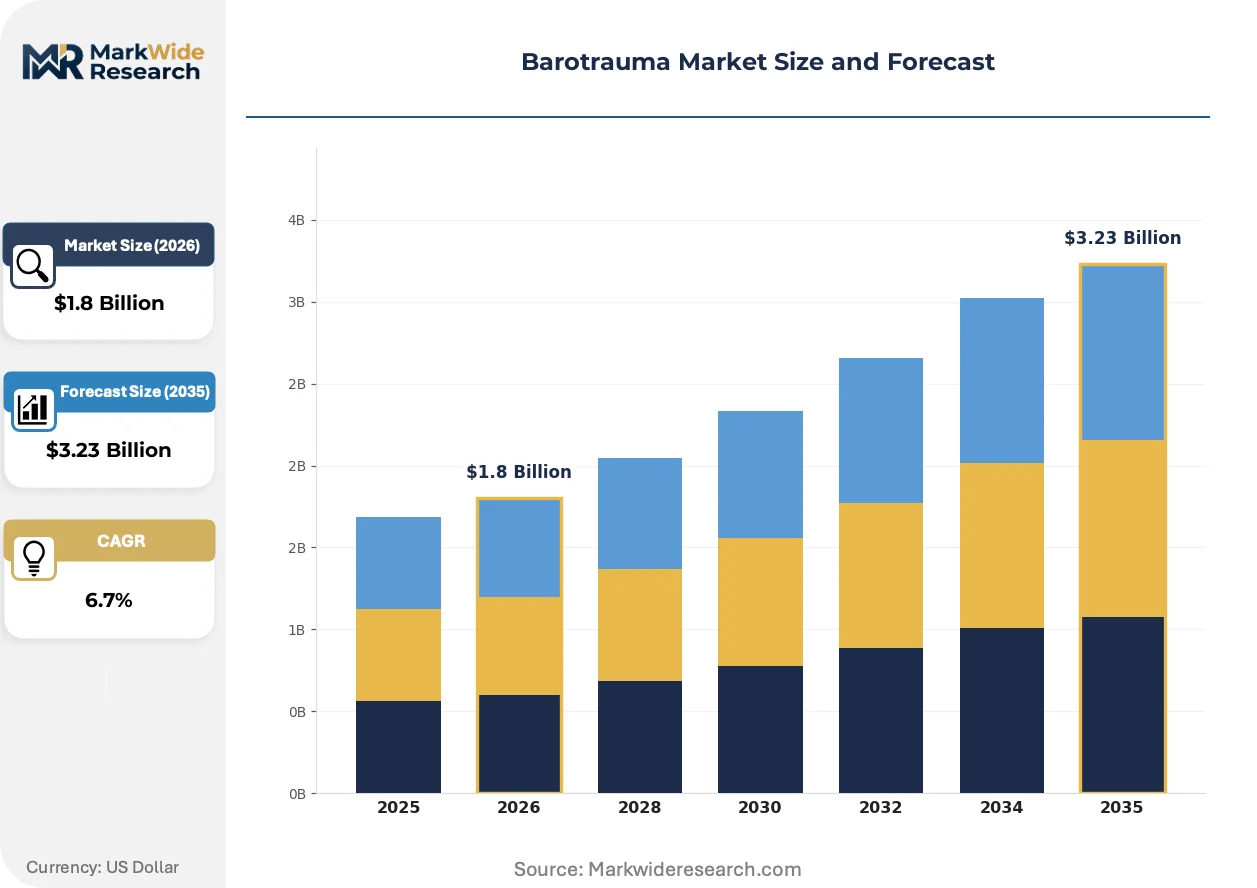
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyperbaric Oxygen Therapy Devices, Suction Devices, Diagnostic Equipment, Surgical Instruments End User: Hospitals, Rehabilitation Centers, Divers, Military Treatment Method: Oxygen Therapy, Surgery, Medication, Physical Therapy Application: Underwater Activities, Aviation, Medical Emergencies, Sports Injuries |
| Companies Covered | GlaxoSmithKline plc, Medtronic, Johnson & Johnson, Smith & Nephew Plc, 3M, Novartis AG, AstraZeneca plc, Olympus Corporation, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barotrauma Market Emerging Trajectories
Real-time pressure differential monitoring is migrating from hospital-based systems toward portable pre-hospital devices, compressing treatment initiation windows and reshaping competitive advantage around sensor miniaturization rather than chamber scale.
Polymer composite suction catheters deliver superior tensile strength under rapid decompression cycles compared to silicone predecessors. Military medical corps and commercial diving operators are adopting these devices at accelerated procurement rates. This materials shift is overtaking legacy silicone supply chains and concentrating manufacturing expertise among polymer processing specialists with medical device certification.
EU MDR technical documentation requirements for hyperbaric oxygen therapy devices now mandate clinical evidence from post-market surveillance studies. Device manufacturers face extended conformity assessment timelines and increased notified body audit frequency. Class III hyperbaric chambers and associated respiratory interfaces bear the heaviest compliance burden, driving consolidation among European manufacturers with dedicated regulatory affairs functions.
Hospital procurement departments are unbundling hyperbaric chamber acquisition from maintenance and training service contracts, treating these as separate competitive bids. This purchasing pattern disrupts traditional single-vendor relationships and elevates specialized service providers alongside equipment manufacturers. The United States exhibits the most pronounced unbundling behavior, with IDN procurement committees separating capital expenditure from operational service agreements.
Barotrauma Market Segmentation
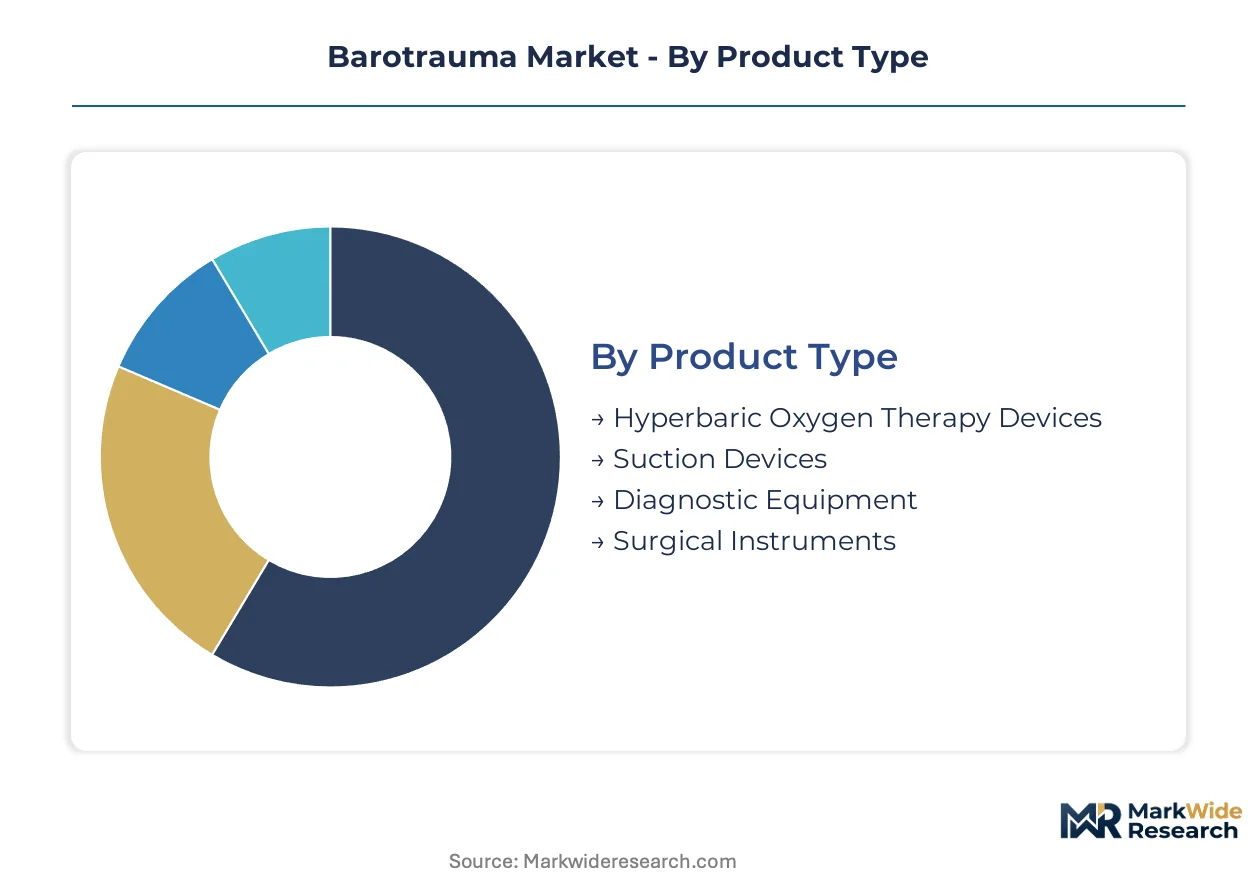
Barotrauma treatment pathways diverge sharply across clinical settings and pressure exposure scenarios. Manufacturers must align device specifications with distinct physiological injury mechanisms and emergency response timelines.
Product Type:
Supply concentration clusters around polymer composite processing capabilities, with certified medical device manufacturers in Germany and Switzerland dominating precision-molded components for pressure-resistant systems.
- Hyperbaric Oxygen Therapy Devices:These systems deliver 100% oxygen at 2.0-3.0 atmospheres absolute through sealed chambers. United States trauma centers anchor clinical volume as decompression sickness treatment networks expand along coastal diving corridors.
- Suction Devices:Polymer composite catheters withstand rapid decompression cycles with superior tensile strength. NATO battlefield medical protocols and commercial diving operators are accelerating procurement of these ruggedized portable units.
- Diagnostic Equipment:Imaging-intensive emergency protocols drive revenue concentration in hospital radiology departments.
- Surgical Instruments:Polymer composites displace silicone in pressure-differential instruments, forcing production line retooling.
Diagnostic equipment absorbs the bulk of installed capacity; suction devices are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive hospital installations from portable military field systems, with pricing diverging by an order of magnitude between fixed chambers and battlefield-ready units.
- Hospitals:These facilities concentrate treatment volume across underwater activity and aviation applications, anchoring procurement for multi-place hyperbaric chambers. United States IDNs are unbundling equipment acquisition from maintenance contracts, disrupting traditional single-vendor relationships.
- Military:NATO standardization of portable suction systems creates dedicated procurement channels with premium pricing for ruggedized diagnostic equipment. Battlefield barotrauma protocols demand sensor miniaturization over chamber scale.
- Rehabilitation Centers:Adjacent wound management services leverage hyperbaric protocols for tissue repair acceleration.
- Divers:Recreational and commercial diving operators drive demand for pre-hospital diagnostic sensors and rapid decompression intervention capabilities.
Hospitals command the dominant share of capital deployment; military procurement is climbing the fastest as pre-hospital protocols standardize.
Treatment Method:
Application context determines method selection, with emergent pressure differentials demanding immediate oxygen intervention while chronic injuries cycle through multi-modal rehabilitation.
- Oxygen Therapy:Hyperbaric delivery at elevated atmospheric pressure reverses gas embolism and accelerates tissue repair. FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape commercialization timelines for these systems.
- Surgery:Barotrauma surgical interventions address tissue damage from pressure differentials exceeding 1-2 atmospheres in lungs, ears, sinuses, or gastrointestinal tract.
- Medication:Adjunct pharmaceutical protocols support pressure injury management alongside mechanical interventions.
- Physical Therapy:Rehabilitation protocols restore function following barotrauma-induced tissue damage in sports and diving incidents.
Oxygen therapy carries the heaviest regulatory compliance burden; surgery is gaining share fastest as polymer instrument adoption accelerates.
Application:
Volume concentration reflects incident frequency, with underwater pressure exposure generating the highest acute case volume while aviation-related barotrauma commands specialized diagnostic premium.
- Underwater Activities:Decompression sickness and rapid ascent injuries dominate patient pools. Mandatory incident reporting in Australia and the United States expands clinical data pools and justifies hyperbaric chamber installations at coastal trauma centers.
- Aviation:Cabin pressure differentials at altitude create sinus, ear, and pulmonary barotrauma. Telemedicine integration enables real-time triage through in-flight diagnostic sensors linked to ground-based hyperbaric consultation.
- Medical Emergencies:Trauma centers handle acute pressure injury presentations requiring immediate intervention.
- Sports Injuries:Scuba diving and altitude sports generate recreational incident volume for treatment networks.
Underwater activities anchor the largest installed base; aviation applications are expanding most quickly through sensor-telemedicine convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones along coastal diving corridors concentrate hyperbaric chamber installations. Tax incentives for trauma center infrastructure in Australia and the United States accelerate capital deployment. Military procurement hubs in NATO member states anchor premium equipment demand.
United States
Decompression sickness treatment networks expand along Florida and California diving corridors. FDA 510(k) clearance requirements tighten quality benchmarks for hyperbaric oxygen therapy devices. Texas Medical Center in Houston anchors clinical volume for multi-place chamber installations.
Australia
Mandatory incident reporting for recreational diving injuries expands clinical data pools. TGA oversight governs medical device registration for hyperbaric systems. Coastal trauma centers along Queensland's Great Barrier Reef corridor justify new chamber installations.
Germany
Medical-grade polymer composite suppliers cluster in precision manufacturing zones. EU MDR technical documentation requirements filter marginal competitors from hyperbaric device markets. Munich and Stuttgart industrial basins concentrate certified polymer processing capabilities.
Switzerland
Swissmedic certification standards elevate quality thresholds for pressure-resistant surgical instruments. Alpine diving tourism and aviation medicine create dual demand streams. Basel and Zurich medical technology clusters specialize in polymer-based device manufacturing.
Brazil
Offshore oil platform clinics drive demand for portable suction systems. ANVISA fast-track pathways accelerate market entry for critical care devices. Rio de Janeiro and São Paulo coastal zones concentrate decompression sickness treatment infrastructure.
Barotrauma Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates among diversified medical technology conglomerates and wound management specialists. Three archetypes dominate: diversified conglomerates with endoscopic platforms, surgical instrument broad-liners, and hyperbaric-adjacent wound care specialists. Competitive moves center on polymer materials transition and regulatory compliance consolidation.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions shaped by endoscopic platform expertise and surgical instrument breadth. Smith & Nephew exemplifies the wound management specialist archetype adjacent to hyperbaric oxygen protocols. These three entities represent distinct competitive vectors without overlapping core specializations.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Medtronic |
| Johnson & Johnson |
| Smith & Nephew Plc |
| 3M |
| Novartis AG |
| AstraZeneca plc |
| Olympus Corporation |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
United States hospital procurement committees concentrate purchasing power for hyperbaric chambers and polymer-based surgical instruments, anchoring contract-based pricing with multi-year service unbundling. This buyer concentration forces manufacturers to absorb certification costs while competing on total cost of ownership rather than equipment margin alone.
Pricing Analysis
Short lead-time premiums of 15-25% apply to polymer composite suction catheters for NATO battlefield medical corps and commercial diving operators with emergency replacement needs. Contract-based long-term offtake dominates hospital IDN procurement, with FDA 510(k) clearance tier and ISO 13485 certification level driving price differentiation between German-Swiss suppliers and Asian assemblers. Cost compression in mid-tier diagnostic equipment is intensifying because EU MDR conformity assessment timelines extend working capital cycles. Military end users exhibit least price sensitivity due to mission-critical specifications, while Brazilian and Indian coastal trauma centers face acute budget constraints.
Supply Chain Analysis
Medical-grade polymer composite feedstock rests on specialty chemical producers concentrated in Germany, Switzerland, and select Japanese industrial zones. Precision-molded chamber components draw from certified processors in Stuttgart and Basel, while final assembly of portable suction systems sources from Malaysian and Mexican contract manufacturers. Single-source vulnerability concentrates in German polymer suppliers exposed to energy input volatility. Distribution runs through hospital GPOs in the United States, direct military procurement channels for NATO standardization, and regional medical device distributors serving coastal trauma networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with EU MDR technical documentation requirements and FDA 510(k) biocompatibility testing filtering out capital-constrained competitors.
For Market Incumbents: Hedge against polymer feedstock price volatility through backward integration into Swiss or German specialty chemical partnerships, or through long-term offtake agreements with certified suppliers. Defend market position by accelerating chamber operator training programs to address technician certification scarcity, creating sticky service revenue streams that resist procurement unbundling. For New Entrants and Emerging Players: Specialized service providers for hyperbaric chamber maintenance and training represent the most penetrable channel partner type, given hospital IDN unbundling behavior. Target Indian coastal trauma centers along the Andaman Islands corridor with portable diagnostic sensors, leveraging ANVISA fast-track precedents to compress regulatory timelines. Position through aviation telemedicine integration partnerships rather than capital-intensive chamber manufacturing. For Investors and Strategic Acquirers: The window for entry favors polymer processing specialists with existing medical device certification and EU MDR regulatory affairs infrastructure. Mid-tier manufacturers with captive polymer molding capabilities in Germany or Switzerland present acquisition targets with defensible input cost positions. Watch for reimbursement code alignment between CMS and private payors on prophylactic hyperbaric indications as the inflection signal for treatment center expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter marginal competitors from German and French hospital networks. |
| Hospital System Partnership | Unbundled procurement contracts with United States IDNs separate capital expenditure from operational service agreements. |
| Reimbursement Strategy | CMS and private payor alignment on hyperbaric oxygen therapy codes determines treatment center revenue stability. |
| Software Companion Development | Aviation telemedicine integration enables real-time barotrauma triage through in-flight diagnostic sensors. |
| FDA Submission | 510(k) clearance for polymer-based successors requires extensive biocompatibility testing extending development cycles. |
Methodological Framework
Multi-period observation of hyperbaric chamber installation rates, diving incident reporting volumes, and military procurement award patterns anchored the trend analysis, supplemented by interviews with clinicians at coastal trauma centers, hospital purchasing committee members, biomedical engineers specializing in pressure-resistant systems, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body audit records, CMS reimbursement code filings, and NATO standardization documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
The input-output matrix framed demand as a function of pressure exposure incident frequency, regulatory compliance cost burdens, and procurement unbundling penetration. Segmentation dimensions modeled included product type, end user archetype, treatment method, and application context alongside regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves applied to installed base expansion and replacement cycle timing. Forecast inputs incorporated polymer feedstock price elasticity and hyperbaric technician training pipeline capacity constraints.
Several conditions sit outside the modeled scope, including pandemic-related diving activity disruption, abrupt shifts in military medical procurement priorities, and radical sensor miniaturization breakthroughs. Forecasts reflect documented assumptions about reimbursement stability and polymer supply continuity. Regulatory timeline extensions and payor coverage recalibrations represent specific risk factors that could revise projections. A small set of named triggers—including NATO battlefield protocol revisions and Indian coastal infrastructure investment announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Scleritis Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Pigmented Villonodular Synovitis Treatment Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Vitiligo Treatment Market