
 Global Targeted Cancer Therapy Market | 2026-2036
Global Targeted Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Targeted Cancer Therapy Market Foresight
The gap between premium biologics and commoditized small-molecule inhibitors is restructuring competitive dynamics across the industry. Roche leverages its diagnostics-to-therapeutics integration to control patient identification workflows. Novartis anchors its position through sustained R&D intensity in radioligand therapy platforms.
Targeted cancer therapy encompasses pharmacological agents engineered to interfere with specific molecular pathways driving malignant proliferation, typically requiring companion diagnostic validation for patient stratification. Monoclonal antibodies command the largest revenue pool due to established manufacturing infrastructure and broad indication coverage, while tyrosine kinase inhibitors represent the fastest-expanding category fueled by oral bioavailability advantages and lower administration costs. Immunomodulators concentrate margin in specialized infusion centers where reimbursement complexity creates barriers to generic substitution.
FDA, EMA, and Japan's PMDA collectively shape market access through divergent evidentiary requirements for biomarker validation and post-market surveillance. The FDA's accelerated approval pathway compresses development timelines but demands confirmatory trials that strain smaller developers. Stakeholders must monitor evolving payer evidence requirements across these three jurisdictions to align clinical trial design with commercial viability.
Market Dynamics
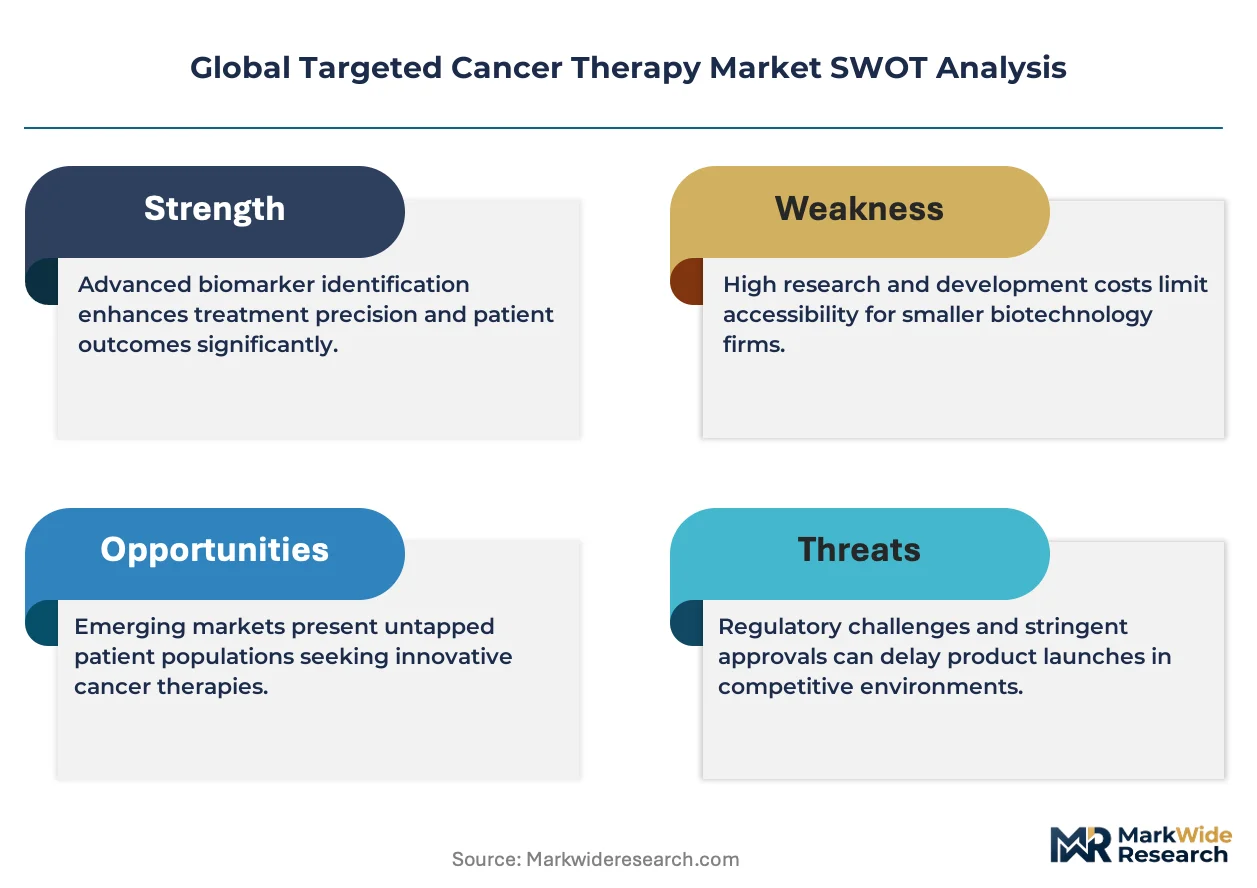
The convergence of companion diagnostics with therapeutic development is compressing clinical timelines while fragmenting commercialization pathways. Biomarker validation requirements now precede regulatory submission, reshaping how developers allocate capital across discovery and commercial infrastructure.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's streamlined evidentiary framework for breakthrough therapies reduces phase transition delays. Developers leverage this to compress time-to-market for novel molecular targets.
- Radioligand Platform Expansion:Theranostic pairing is creating new addressable populations in neuroendocrine and prostate malignancies. Manufacturing investments in isotope supply chains are scaling production capacity.
- Germany's Early Access Framework:The AMNOG process enables conditional reimbursement during evidence generation. This reduces commercialization risk for novel mechanisms entering European markets.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production concentrates at five aging research reactors globally. Disruptions at Petten in the Netherlands or Chalk River successors create radiopharmaceutical shortages.
- Companion Diagnostic Fragmentation:Biomarker assay variability across platforms complicates patient stratification. Laboratories face validation burdens that delay test availability.
- Specialized Infusion Infrastructure:Radioactive therapeutics require shielded handling facilities that concentrate in tertiary oncology centers. Geographic access gaps limit addressable populations.
Strategic Opportunities
- Japan's Sakigake Designation:PMDA's priority review system offers expedited consultations for first-in-class agents. Developers can front-load Japanese market entry ahead of European submissions.
- Minimal Residual Disease Monitoring:Circulating tumor DNA platforms are expanding indication scope beyond treatment selection into surveillance. This creates recurring revenue streams post-therapy.
- Artificial Intelligence in Patient Identification:Natural language processing of electronic health records is automating biomarker screening. Health systems deploy these tools to reduce manual chart review burden.
Industry Challenges
- Radiochemistry Workforce Scarcity:Cyclotron operation and radiopharmaceutical synthesis require specialized training pipelines. Academic programs graduate insufficient technicians to match facility expansion.
- Cross-Border Cold Chain Complexity:Temperature-sensitive biologics face customs delays that compromise viability. Logistics providers must navigate divergent national import requirements for biological specimens.
- Evidence Generation Cost Burden:Confirmatory trials for accelerated approvals demand substantial follow-up investment. Smaller developers face financing gaps between initial approval and completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Targeted Cancer Therapy Market |
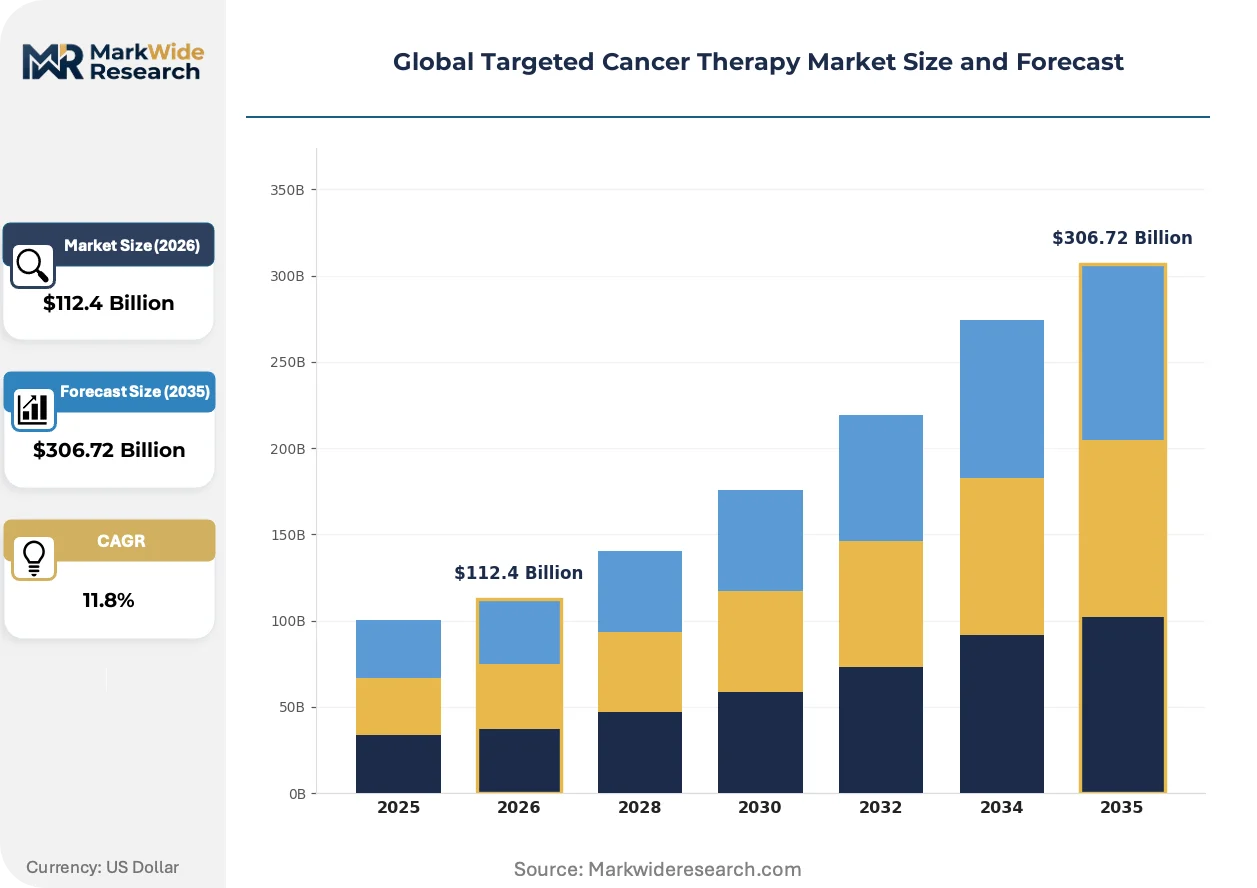
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $306.72 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Monoclonal Antibodies, Tyrosine Kinase Inhibitors, Proteasome Inhibitors, Immunomodulators Indication: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukemia, Lymphoma End User: Oncology Centers, Research Institutes, Specialized Clinics, Diagnostic Laboratories Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Roche, Novartis AG, Amgen Inc., Pfizer Inc., Bristol-Myers Squibb, AstraZeneca, Merck & Co., AbbVie, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Targeted Cancer Therapy Market Shifts & Advancements
Bioconjugate engineering is redefining therapeutic indices by expanding the addressable target space beyond conventional druggable proteins. This shift demands recalibration of manufacturing competencies and regulatory submission strategies.
Antibody-drug conjugates are integrating novel linker chemistries that enable homogeneous drug-to-antibody ratios. Oncology centers in the United States are adopting these agents for solid tumor indications previously resistant to naked antibody therapy. The technology is integrating payload delivery precision that reduces off-target toxicity and enables dose escalation.
The EU's In Vitro Diagnostic Regulation is mandating expanded clinical evidence for companion diagnostic claims. Manufacturers must generate prospective validation data that exceeds predecessor directive requirements. High-complexity molecular assays face the steepest compliance burden, with notified body backlogs extending certification timelines.
Hospital procurement committees are consolidating vendor relationships to simplify formulary management. Academic medical centers in Germany are negotiating enterprise-wide agreements spanning diagnostics and therapeutics. This concentration is displacing fragmented purchasing across individual disease centers and compressing supplier margins.
Global Targeted Cancer Therapy Market Segmentation
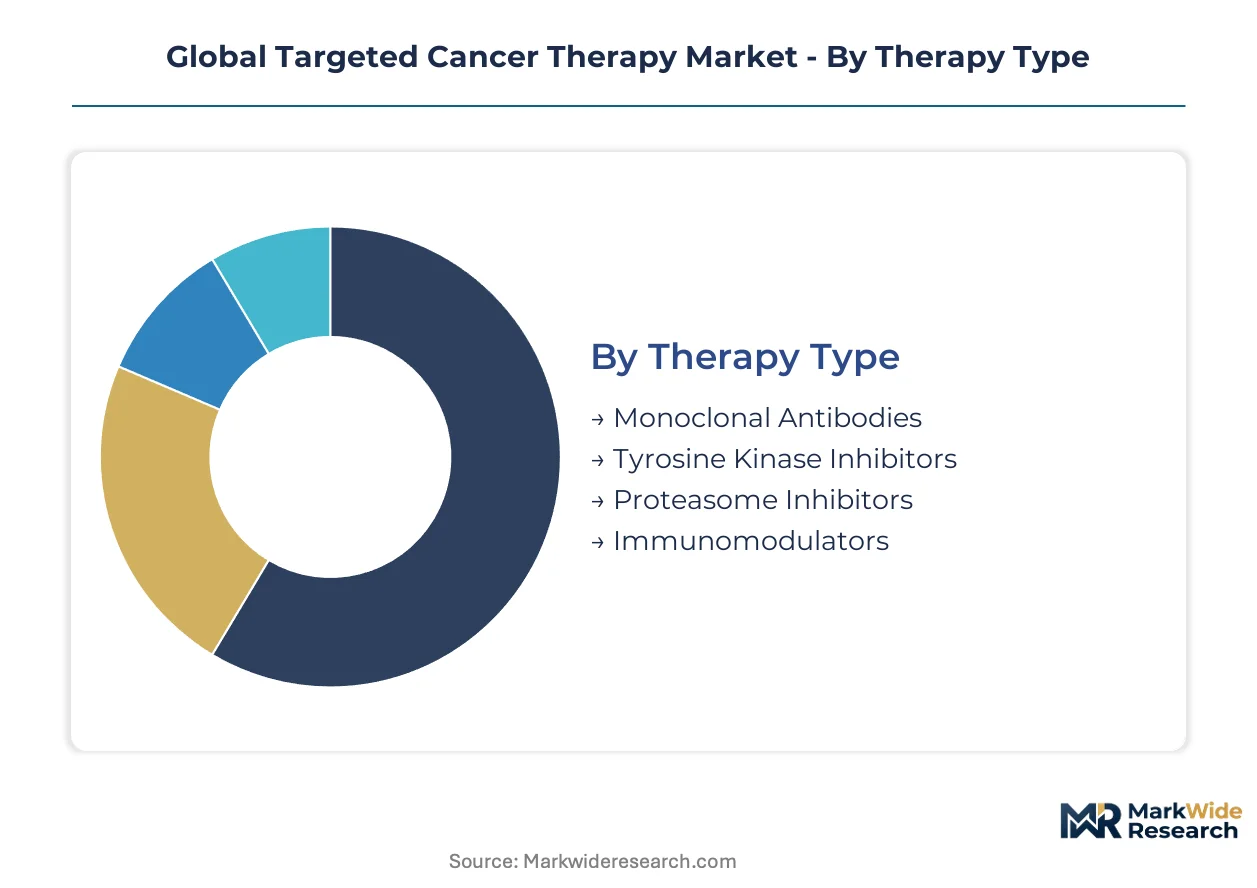
Therapy type determines manufacturing infrastructure requirements and reimbursement complexity across the targeted cancer therapy landscape. Indication-specific biomarker prevalence shapes clinical trial design and commercial addressability for developers.
Therapy Type:
Buyers in this category differentiate by administration setting requirements and companion diagnostic dependency.
- Monoclonal Antibodies:Large-molecule biologics manufactured in mammalian cell culture systems with established cold chain distribution networks. Demand concentrates in United States oncology centers where infusion reimbursement rates support premium pricing and shielded handling infrastructure.
- Tyrosine Kinase Inhibitors:Small-molecule agents with oral bioavailability enabling outpatient dispensing without specialized infusion facilities. Germany's community oncology practices favor these agents for reduced facility overhead and patient convenience advantages.
- Proteasome Inhibitors:Agents targeting protein degradation pathways in hematologic malignancies with specific handling protocols.
- Immunomodulators:Therapeutics modulating immune checkpoint pathways requiring biomarker stratification for patient selection.
Monoclonal antibodies lead volumes today; tyrosine kinase inhibitors are gaining share fastest.
Indication:
Commercial prioritization in this category follows biomarker prevalence and addressable patient pool density.
- Breast Cancer:HER2-targeted and hormone receptor-directed therapies dominate with well-validated companion diagnostic algorithms. United States academic medical centers drive demand for CDK4/6 inhibitor combinations in hormone-positive subtypes.
- Lung Cancer:EGFR, ALK, and ROS1 alterations create multiple addressable molecular subsets with rapid diagnostic adoption. Japan's high EGFR mutation rate in non-smoking populations concentrates demand for osimertinib-class agents.
- Colorectal Cancer:RAS and BRAF mutation profiling determines anti-EGFR eligibility with established testing pathways.
- Leukemia:BCR-ABL and FLT3-targeted therapies anchor chronic and acute myeloid treatment paradigms.
- Lymphoma:CD20-directed and BTK inhibitor therapies span indolent and aggressive subtypes with varying administration settings.
Breast cancer commands the largest revenue pool; lung cancer shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement capture determine customer value concentration across settings.
- Oncology Centers:Comprehensive cancer centers with integrated pathology and infusion infrastructure controlling high-complexity therapy administration. Germany's university hospitals consolidate purchasing across diagnostic and therapeutic portfolios.
- Research Institutes:Early-phase clinical trial sites with biomarker discovery capabilities and protocol-driven patient access.
- Specialized Clinics:Community-based practices focusing on specific malignancies with streamlined referral pathways.
- Diagnostic Laboratories:Independent and hospital-affiliated labs processing companion diagnostic assays for treatment selection.
Oncology centers capture the majority of therapy value; diagnostic laboratories are expanding fastest as test menu breadth increases.
Delivery Mode:
Patient convenience and healthcare system cost structure drive modality preference divergence.
- Intravenous:Infusion-dependent biologics requiring clinical supervision and adverse event monitoring capabilities. United States hospital outpatient departments bill these under distinct reimbursement codes favoring site-of-care economics.
- Oral:Self-administered small molecules with pharmacy benefit management pathways and adherence monitoring requirements. Japan's universal coverage system streamlines oral oncology drug access through designated pharmacy networks.
- Subcutaneous:Alternative administration reducing infusion chair time with specific formulation requirements.
- Intramuscular:Depot formulations enabling extended dosing intervals with localized injection site considerations.
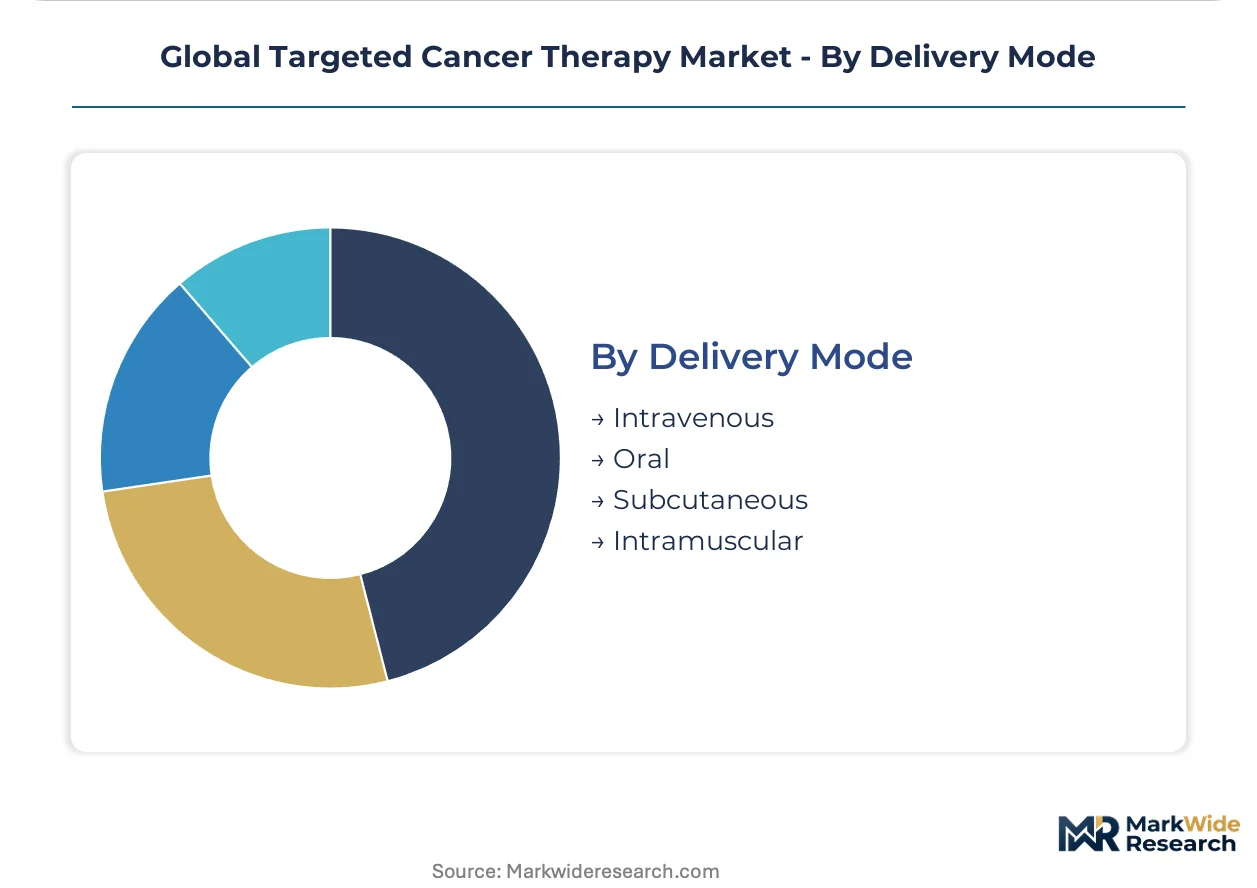
Intravenous administration retains volume leadership; oral delivery is climbing the fastest as patient preference shifts toward home-based care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oncologists and radiochemists concentrate in Boston, Basel, and Tokyo, anchoring precision medicine development clusters that attract multinational trial investment and manufacturing partnerships.
United States
Academic medical centers in Boston and Houston drive demand for radioligand therapies and companion diagnostic integration. FDA's accelerated approval pathway compresses development timelines for breakthrough-designated agents. The Research Triangle in North Carolina hosts contract manufacturing organizations scaling antibody-drug conjugate production capacity.
Germany
University hospitals in Munich and Heidelberg prioritize biomarker-driven treatment selection for solid tumor indications. The AMNOG early access framework enables conditional reimbursement during evidence generation. The Rhine-Main cluster around Frankfurt concentrates radiopharmaceutical manufacturing infrastructure serving European distribution networks.
Japan
High EGFR mutation prevalence in non-smoking populations concentrates demand for tyrosine kinase inhibitors in Tokyo and Osaka oncology centers. PMDA's Sakigake designation offers expedited consultation for first-in-class agents. The Kobe biomedical cluster hosts specialized cyclotron facilities producing isotopes for theranostic applications.
United Kingdom
The NHS Genomic Medicine Service drives standardized biomarker testing adoption across England's cancer centers. MHRA alignment with FDA evidentiary standards facilitates parallel submission strategies for developers. The Cambridge-London corridor concentrates immuno-oncology research institutes and early-phase trial sites.
Switzerland
Basel's pharmaceutical research workforce anchors integrated diagnostics-to-therapeutics development models. Swissmedic maintains streamlined review procedures for innovative oncology agents with companion diagnostic requirements. The Lake Geneva region hosts specialized manufacturing facilities for bioconjugate and antibody production.
Global Targeted Cancer Therapy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the targeted cancer therapy landscape. Integrated pharmaceutical conglomerates with captive diagnostic divisions face competition from specialized biotech developers outsourcing manufacturing to contract organizations. Three archetypes dominate: vertically integrated giants controlling patient identification workflows, radiopharmaceutical specialists mastering isotope supply chains, and precision medicine platforms combining AI-driven biomarker discovery with therapeutic development. Competitive intensity concentrates on M&A activity absorbing novel molecular targets and strategic partnerships securing manufacturing capacity.
Within the integrated pharmaceutical tier, Roche and Novartis AG exemplify divergent strategic positioning—Roche anchoring diagnostics-therapeutics convergence while Novartis AG concentrates radioligand platform expansion. Among specialized developers, Amgen Inc. occupies a position emphasizing biologics manufacturing scale. Bristol-Myers Squibb and AstraZeneca represent the immuno-oncology competitive vector, while Merck & Co. and Pfizer Inc. sit within the large-molecule diversification archetype. AbbVie and Bayer AG anchor positions in targeted small-molecule and radiopharmaceutical segments respectively.
| Leading Market Players |
|---|
| Roche |
| Novartis AG |
| Amgen Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb |
| AstraZeneca |
| Merck & Co. |
| AbbVie |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Radiochemistry workforce concentration in the Rhine-Main cluster and Boston corridor widens pricing-tier spreads between premium radioligand therapies and commoditized small-molecule inhibitors. Labor-cost differentials between specialized cyclotron technicians and standard pharmaceutical manufacturing personnel directly feed into three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Bundled companion diagnostic-therapeutic packages command premium positioning against unbundled small-molecule agents where testing and treatment procurement separate. Price differentiation rests on biomarker validation tier and infusion infrastructure requirements, with United States hospital outpatient departments showing lowest sensitivity due to site-of-care reimbursement advantages. Cost compression in oral oncology generics is intensifying because pharmacy benefit managers consolidate formularies. Community oncology practices in Germany exhibit highest price sensitivity, driving preference for self-administered tyrosine kinase inhibitors.
Supply Chain Analysis
Single-source vulnerability sits with molybdenum-99 production concentrated at aging research reactors in the Netherlands, Belgium, and South Africa. Isotope supply chains draw from limited academic reactor infrastructure, with lutetium-177 and actinium-225 dependencies creating critical path constraints. Regulatory restriction across FDA, EMA, and PMDA jurisdictions fragments cold chain compliance. Distribution runs through tertiary oncology centers with shielded handling capabilities, concentrating downstream access in metropolitan hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA accelerated approval pathway expansion continuously generates addressable patient populations ahead of traditional evidentiary timelines.
For Market Incumbents: Deploy diagnostics-to-therapeutics integration as the primary defensive lever. Roche's captive control over patient identification workflows creates switching costs that emerging biotech competitors cannot replicate. Backward integration into isotope production secures supply continuity against Petten reactor vulnerability. Capacity addition in Kobe and Basel radiochemistry clusters anchors regional manufacturing presence against tariff exposure. For New Entrants and Emerging Players: Capture minimal residual disease monitoring as the most penetrable white-space opportunity, where circulating tumor DNA platforms extend recurring revenue beyond acute treatment phases. Japan's Sakigake designation offers fastest regulatory entry for first-in-class agents ahead of European submissions. AI-driven patient identification partnerships with United States health systems provide lowest-friction go-to-market angle. For Investors and Strategic Acquirers: Radiopharmaceutical specialists with secured isotope contracts are the most active acquirer targets in this space. Five-to-ten year viability hinges on theranostic platform breadth and manufacturing regulatory approvals. Pipeline-stage radioligand assets with validated cyclotron partnerships signal inflection readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough therapy designation requires validated biomarker stratification from phase one. |
| Radiopharmaceutical Manufacturing Scale-Up | Isotope supply agreements with Petten or Chalk River successors secure production continuity. |
| AI Patient Identification Partnership | Natural language processing deployment at United States academic medical centers automates screening. |
| AMNOG Early Access Filing | Germany's conditional reimbursement during evidence generation reduces European commercialization risk. |
| Radiochemistry Workforce Pipeline | Specialized training programs at Basel and Boston academic centers address technician scarcity. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Drug development executives, regulatory affairs leads, formulary directors, and payer access specialists contributed primary perspectives. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases supplied secondary verification. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored value estimates.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the analysis window. Segmentation dimensions include therapy type, indication, biomarker prevalence tier, administration route, and regional regulatory cluster. CAGRs derive from patient population epidemiology, approval probability-weighted pipeline valuation, and reimbursement trajectory modeling. Forecast inputs incorporate companion diagnostic adoption curves and radiopharmaceutical manufacturing capacity buildout schedules.
Regulatory approval delays, isotope supply disruptions, and payer evidence requirement tightening are the dominant revision risks to modeled assumptions. Forecasts reflect documented assumptions about biomarker test penetration and therapy pricing sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market