
 Prostate Cancer Diagnostics Market | 2026-2036
Prostate Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Prostate Cancer Diagnostics Market Intelligence
North American molecular diagnostics manufacturers is repositioning their production networks toward higher-margin genomic platforms. F. Hoffmann-La Roche anchors European distribution through its centralized laboratory services network. Siemens Healthineers leverages its installed imaging base to cross-sell integrated prostate MRI workflows. MDxHealth specializes in epigenetic urinary assays that reduce unnecessary biopsy procedures.
Prostate cancer diagnostics encompasses laboratory assays, imaging modalities, and tissue analysis systems designed to detect malignancy, stratify risk, and guide treatment selection in glandular tissue. PSA testing remains the most frequently ordered blood-based screen, while multiparametric MRI reduces false-positive rates by visualizing suspicious lesions before invasive sampling. Liquid biopsy and genomic testing represent the fastest-expanding technology segments as payers increasingly cover non-invasive molecular profiling. Digital pathology occupies a maturing but margin-rich position where AI-assisted slide reading compresses turnaround times for busy hospital pathology departments.
FDA breakthrough device pathways and EMA's in vitro diagnostic regulation shape product development timelines and evidence requirements for market authorization. The Centers for Medicare & Medicaid Services coverage determinations directly influence adoption velocity for novel assays in US hospital systems. Stakeholders must monitor evolving reimbursement codes for multiparametric MRI and liquid biopsy to align capital deployment with payment infrastructure readiness.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing commercialization timelines for liquid biopsy assays, while hospital procurement committees consolidate vendor relationships around integrated diagnostic platforms that span imaging, laboratory testing, and digital pathology.
Growth Catalysts
- EMA's In Vitro Diagnostic Regulation:The MDR framework mandates higher clinical evidence standards that favor established manufacturers with robust quality systems, accelerating consolidation around compliant platforms.
- University hospital networks:Germany's integrated diagnostic pathways are standardizing multiparametric MRI-to-biopsy workflows, creating template adoption models for adjacent European markets.
- Epigenetic urinary assays:Non-invasive methylation-based testing reduces unnecessary tissue sampling, aligning with payer cost-containment objectives and patient preference for blood-free screening.
Market Restraints
- Reimbursement code lag:CMS coverage determinations for novel liquid biopsy assays trail FDA clearance by 18-24 months, constraining hospital capital allocation.
- Isotope supply concentration:Molybdenum-99 production for PET imaging concentrates in aging reactors across Canada and the Netherlands, creating vulnerability in radiotracer availability.
- Pathologist workforce density:The American Society for Clinical Pathology reports declining fellowship enrollment, limiting throughput for AI-augmented digital pathology deployment.
Strategic Opportunities
- Community oncology networks:Freestanding cancer centers in Texas and Florida lack integrated imaging-pathology workflows, creating whitespace for platform vendors offering turnkey installation.
- AI-enabled Gleason grading:Machine learning algorithms that automate prostate tissue scoring converge with digital slide scanners to compress diagnostic turnaround from days to hours.
- India's Ayushman Bharat:The national health insurance expansion mandates cancer screening coverage, opening reimbursement pathways for PSA testing and imaging in tier-2 cities.
Industry Challenges
- Liquid biopsy assay validation:Cross-platform concordance studies require prospective clinical trials that strain R&D budgets and extend time-to-market for multi-cancer early detection panels.
- PACS integration complexity:Multiparametric MRI workstations must interface with legacy hospital imaging archives, demanding custom HL7-FHIR middleware that prolongs implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostate Cancer Diagnostics Market |
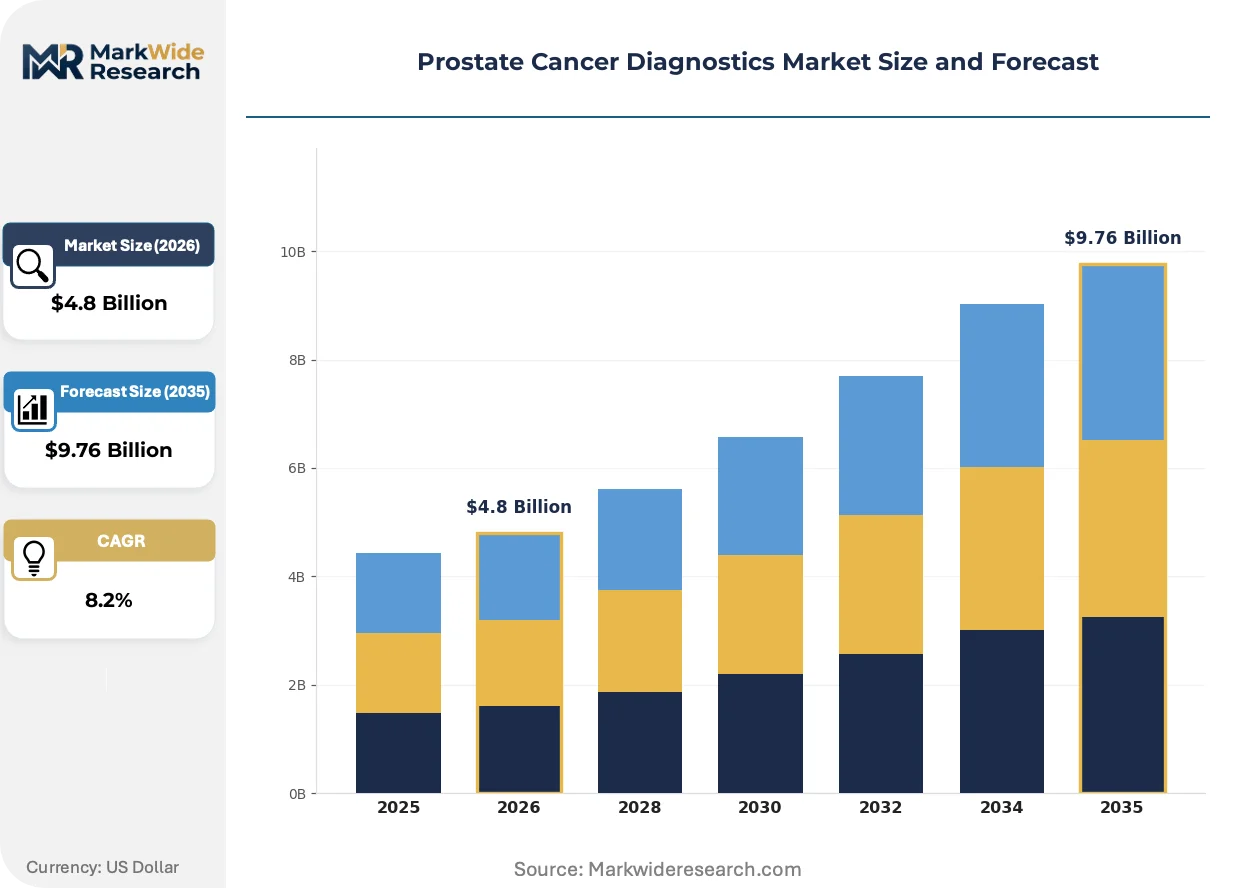
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: PSA Test, MRI, Biopsy, Urinary Test Technology: Molecular Imaging, Genomic Testing, Digital Pathology, Liquid Biopsy End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Delivery Mode: In-Person, Online, Mobile Health Units, Laboratory Services |
| Companies Covered | MDxHealth, Myriad Genetics, Abbott Laboratories, F. Hoffmann-La Roche, Siemens Healthineers, OPKO Health, Genomic Health, GE HealthCare, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostate Cancer Diagnostics Market Strategic Shifts & Innovations
Artificial intelligence is rewiring diagnostic workflows from image acquisition through final pathology reporting, compressing decision timelines while raising the bar for algorithmic transparency and clinical validation.
Multiparametric MRI with AI-assisted lesion detection is electrifying radiology department throughput. Community hospital systems in the southeastern United States are deploying these platforms to reduce inter-reader variability and standardize PI-RADS scoring. The technology is electrifying referral patterns as urology practices direct patients toward imaging-capable centers rather than defaulting to blind biopsy.
The FDA's streamlined breakthrough device designation creates parallel review tracks that compress premarket timelines for diagnostics demonstrating substantial superiority over approved alternatives. Manufacturers now front-load clinical validation studies to align with CMS parallel evidence development programs. Molecular diagnostic startups targeting Medicare populations structure pivotal trials around coverage with evidence development frameworks.
Hospital procurement committees are consolidating vendor relationships around single-source diagnostic platforms that bundle imaging hardware, AI software, and laboratory services. Independent pathology groups face exclusion from integrated delivery networks unless they adopt vendor-neutral digital workflows. This concentration is most visible in the mid-Atlantic hospital systems where Epic-centric electronic health record deployments favor API-integrated diagnostic modules over standalone solutions.
Prostate Cancer Diagnostics Market Segmentation
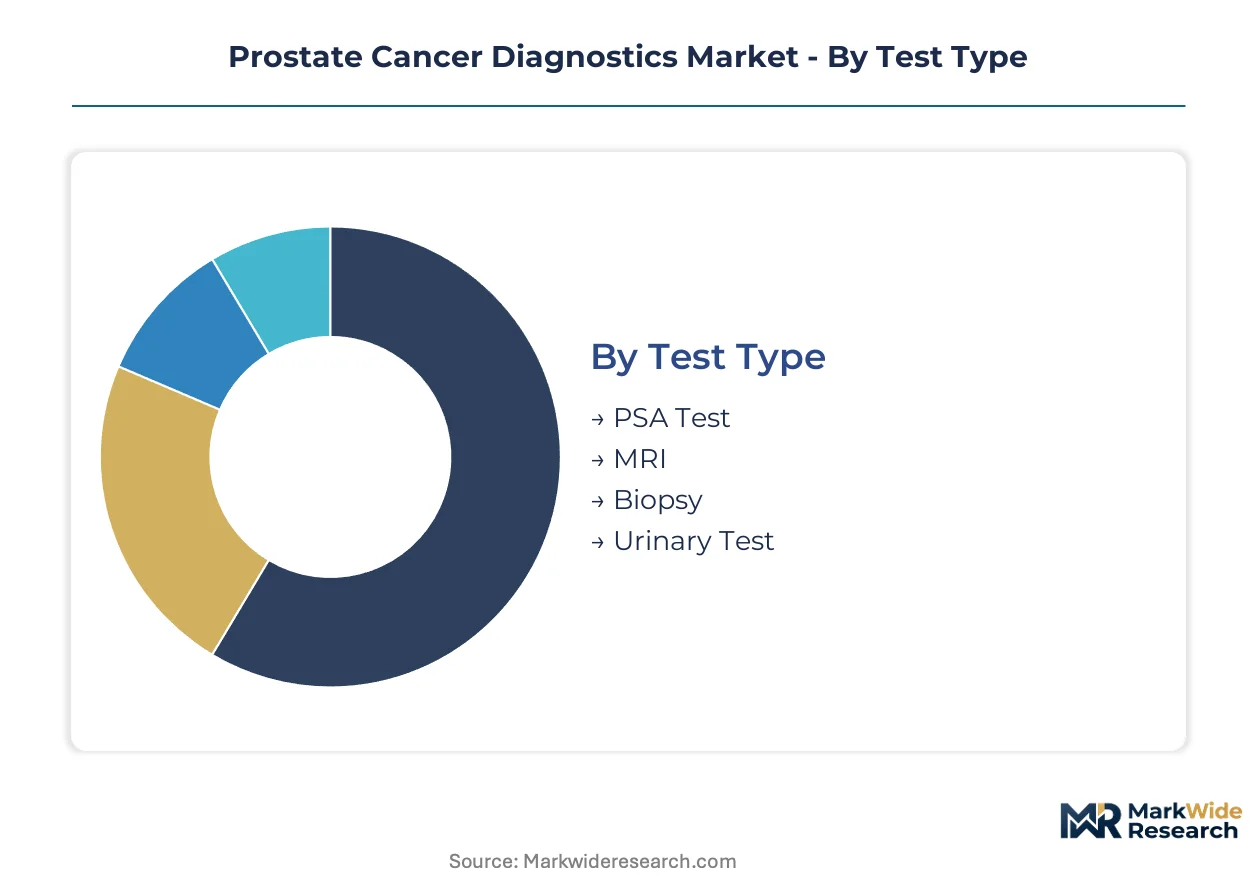
Prostate cancer diagnostics segment heterogeneity reflects divergent capital requirements across imaging hardware, laboratory automation, and point-of-care platforms. Procurement committees weight total cost of ownership against throughput scalability when allocating budget across test modalities.
Test Type:
Capital intensity peaks with MRI installations requiring shielded suites and cryogen systems, while urinary assays demand minimal fixed infrastructure.
- PSA Test:Enzyme-linked immunosorbent assays and chemiluminescent immunoassays dominate high-throughput laboratory workflows. Demand concentrates in US health systems where CMS reimbursement codes support serial monitoring for active surveillance protocols, though sensitivity limitations drive adjunctive testing adoption.
- MRI:Multiparametric sequences combining T2-weighted, diffusion-weighted, and dynamic contrast-enhanced imaging require 3 Tesla magnets and specialized radiologist training. Germany's university hospital networks anchor European installed base expansion, with procurement committees favoring vendors offering integrated biopsy guidance platforms.
- Biopsy:Transrectal ultrasound-guided tissue sampling remains the definitive malignancy confirmation method despite infectious complication risks.
- Urinary Test:Epigenetic and protein biomarker panels enable home collection models with central laboratory processing.
Most installed capacity flows through PSA Test. Expansion is steepest in MRI.
Technology:
Margin profiles separate platform-based recurring revenue models from capital equipment sales with extended depreciation schedules.
- Molecular Imaging:PET radiotracers targeting prostate-specific membrane antigen demand cyclotron or generator infrastructure for isotope production. FDA breakthrough designations for novel radiopharmaceuticals are compressing premarket timelines, with US hospital systems prioritizing theranostic platforms that pair diagnostic and therapeutic isotopes.
- Liquid Biopsy:Circulating tumor DNA and circulating tumor cell assays enable serial monitoring without tissue invasion. Payer coverage determinations trail regulatory clearance, constraining community oncology adoption despite strong clinical validation data.
- Genomic Testing:Gene expression signatures stratify active surveillance eligibility from immediate intervention.
- Digital Pathology:Whole-slide imaging with AI-assisted Gleason grading compresses turnaround times for high-volume pathology departments.
Revenue concentration sits with Molecular Imaging. Volume expansion is climbing fastest in Liquid Biopsy.
End User:
Integration requirements vary from enterprise health system EHR connectivity to independent laboratory LIS interoperability.
- Hospitals:Integrated diagnostic pathways combining imaging, biopsy, and genomic analysis require PACS-LIS-EHR interoperability. Epic-centric deployments in US mid-Atlantic systems favor API-integrated modules over standalone solutions, consolidating vendor relationships around platform ecosystems.
- Diagnostic Laboratories:Centralized processing hubs achieve scale economies for molecular assays but face margin pressure from reference pricing.
- Clinics:Urology practices in Texas and Florida lack imaging infrastructure, creating whitespace for turnkey platform vendors.
- Research Institutions:Academic medical centers drive biomarker discovery with CLIA-waived validation pathways.
Procedure volume concentrates in Hospitals. Growth is most rapid in Diagnostic Laboratories.
Delivery Mode:
Patient access models range from traditional facility-based encounters to decentralized collection with centralized interpretation.
- Laboratory Services:Reference laboratories and health system outreach programs handle high-complexity molecular testing requiring specialized equipment. India's Ayushman Bharat expansion is mandating cancer screening coverage that opens reimbursement for centralized PSA and genomic processing in tier-2 cities.
- Mobile Health Units:Screening vans equipped with portable ultrasound extend access to rural and underserved populations.
- In-Person:Facility-based encounters dominate biopsy and imaging procedures requiring sterile environments.
- Online:Telemedicine-ordered home collection kits with digital results portals reduce geographic barriers to initial screening.
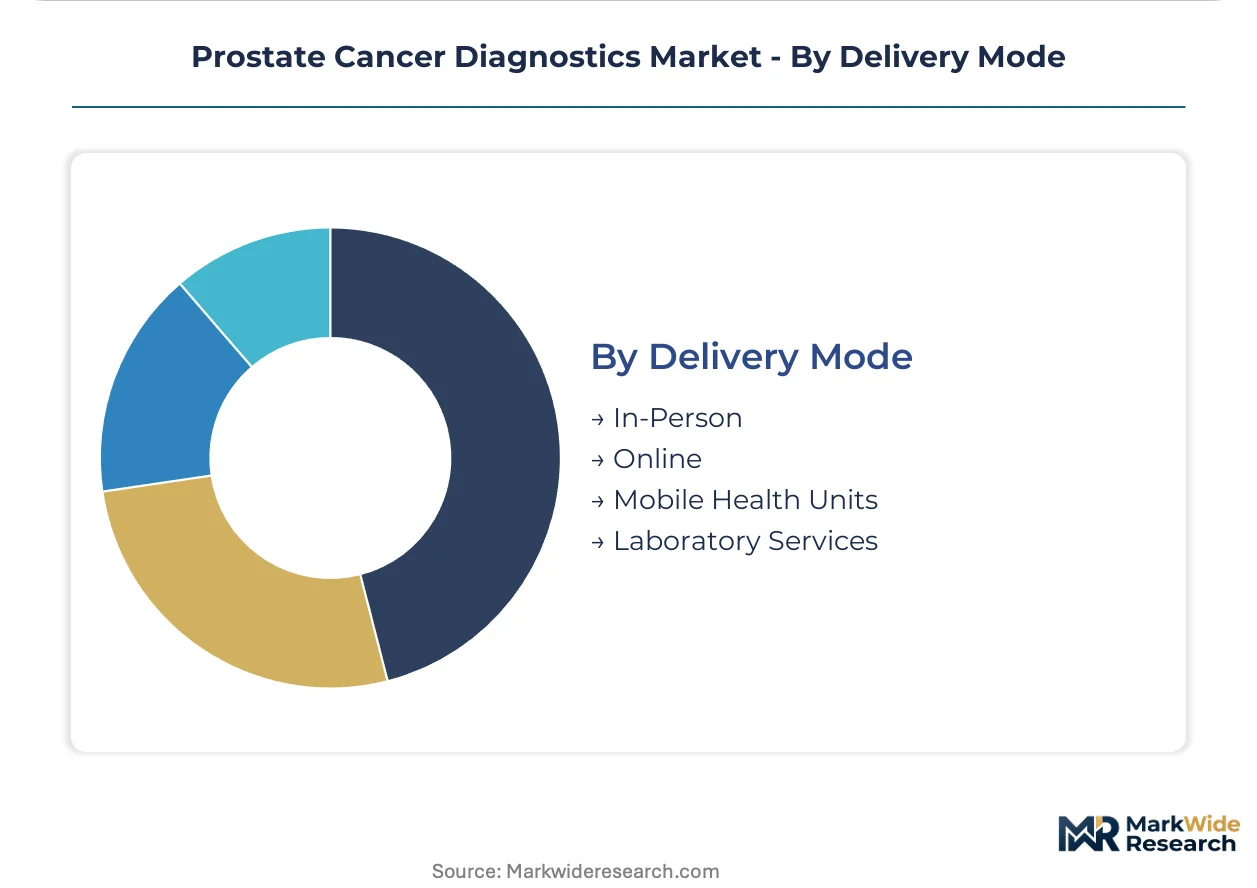
Sample throughput concentrates in Laboratory Services. Access expansion is broadest through Mobile Health Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting diagnostic platform manufacturing toward jurisdictions with streamlined quality system requirements. EMA's MDR implementation has compressed European approval timelines for compliant manufacturers while raising barriers for smaller entrants. Production networks are consolidating around countries offering parallel FDA-EMA regulatory pathways.
United States
Hospital procurement committees in the mid-Atlantic region are consolidating vendor relationships around Epic-integrated diagnostic platforms. FDA breakthrough device designations for liquid biopsy assays are compressing premarket timelines by 12-18 months. The Texas Medical Center in Houston anchors community oncology network expansion, with freestanding cancer centers lacking integrated imaging-pathology workflows.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia are standardizing multiparametric MRI-to-biopsy diagnostic pathways. EMA's In Vitro Diagnostic Regulation mandates higher clinical evidence standards that favor established manufacturers with robust quality management systems. Heidelberg and Munich medical centers are creating template adoption models for adjacent European markets through integrated diagnostic platform rollouts.
India
Ayushman Bharat's national health insurance expansion is mandating cancer screening coverage in tier-2 cities including Pune, Jaipur, and Lucknow. CDSCO streamlined medical device registration pathways are accelerating market entry for PSA testing and imaging platforms. Diagnostic laboratory chains in Maharashtra and Karnataka are scaling centralized processing capacity for molecular assays.
Japan
PMDA's Sakigake designation system is accelerating review timelines for AI-assisted diagnostic software. METI funding for digital health infrastructure is driving hospital adoption of integrated pathology workflows. The Kansai region around Osaka anchors manufacturing concentration for MRI-compatible biopsy guidance systems.
United Kingdom
NHS England's rapid diagnostic centre program is consolidating prostate cancer pathways around multiparametric MRI-first protocols. MHRA post-Brexit regulatory autonomy is enabling accelerated approval timelines for devices with prior FDA clearance. The Cambridge-Oxford-London golden triangle anchors genomic testing platform development and clinical validation studies.
Prostate Cancer Diagnostics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-augmented workflow integration and liquid biopsy specialization. The vendor base stratifies across three tiers: integrated diagnostic conglomerates with imaging-laboratory-platform bundles; molecular diagnostic specialists with assay-specific regulatory expertise; and digital pathology software vendors seeking hardware partnerships. Dominant competitive moves include strategic partnerships between imaging OEMs and AI software developers, plus vertical integration into laboratory services through reference laboratory acquisitions.
Among European-headquartered conglomerates, F. Hoffmann-La Roche and Siemens Healthineers exemplify the integrated platform archetype, anchoring distribution through centralized laboratory services and installed imaging base cross-sell opportunities. MDxHealth represents the molecular specialist tier, occupying a position within epigenetic urinary assay development. These three entities illustrate how competitive positioning diverges between scale-driven platform bundling and assay-specific clinical validation depth.
| Leading Market Players |
|---|
| MDxHealth |
| Myriad Genetics |
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Siemens Healthineers |
| OPKO Health |
| Genomic Health |
| GE HealthCare |
| bioMérieux |
| Others |
Cost & Logistics Intelligence
Molybdenum-99 isotope production costs cascade through PET radiotracer pricing tiers, with aging reactor infrastructure in Canada and the Netherlands concentrating supply leverage among cyclotron-equipped hospital systems that command premium diagnostic service rates.
Pricing Analysis
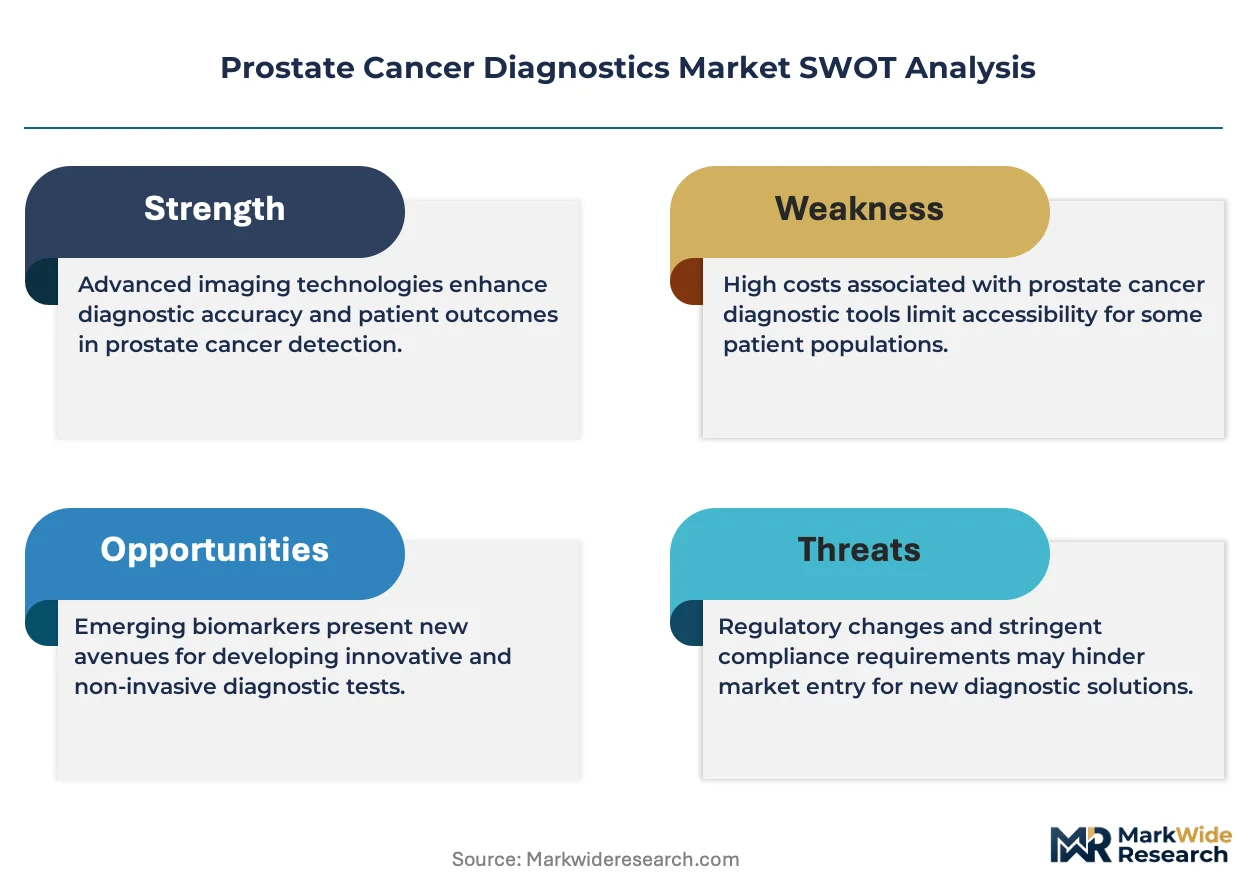
Distributor margins on liquid biopsy assays compress as reference laboratories negotiate volume-based contracts directly with molecular diagnostic manufacturers. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough designation status and integrated platform bundling. Cost compression in community oncology segments intensifies because CMS reimbursement code lag forces hospitals to absorb upfront assay costs. Independent pathology groups exhibit highest price sensitivity; integrated delivery networks with captive laboratory services demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing patterns for PSA testing reagents, pushing multinational manufacturers toward local formulation partnerships. Supply concentrates in the United States for AI-assisted imaging software, Germany for MRI-compatible biopsy guidance hardware, and China for contrast agent precursor chemicals. Raw material dependencies include superconducting niobium-titanium wire, gadolinium-based contrast media, and specialized polymer microfluidic cartridges. Single-source vulnerability sits with molybdenum-99 generator production. Distribution runs through centralized laboratory networks with regional hub-and-spoke specimen logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through AI-enabled workflow automation that reduces pathologist labor intensity while supporting premium-tier pricing for integrated diagnostic platforms.
For Market Incumbents: Acquire digital pathology software assets to complete imaging-to-reporting platform bundles. Defensive consolidation should prioritize AI-assisted Gleason grading algorithms that community hospitals lack internal capability to develop. Threat from liquid biopsy specialists demands backward integration into circulating tumor DNA assay development. Channel control through Epic API-integrated modules anchors hospital procurement relationships against standalone competitors. For New Entrants and Emerging Players: Launch via telemedicine-ordered home collection kits targeting urology practices in Texas and Florida that lack imaging infrastructure. Most penetrable whitespace sits in community oncology networks without integrated MRI-to-biopsy workflows. Go-to-market angle should emphasize turnkey installation with bundled AI software and training to offset capital equipment hesitation among freestanding cancer centers. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR compliance costs exceed smaller IVD manufacturers' quality system investment capacity. Long-term viability favors platform vendors with recurring revenue from laboratory services rather than capital equipment depreciation exposure. Acquisition target archetype: molecular diagnostic specialists with FDA breakthrough-designated assays and stalled commercialization due to reimbursement code lag. Signal to watch is CMS parallel evidence development program enrollment as inflection indicator for coverage velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Gleason Grading Development | Machine learning algorithms compress diagnostic turnaround from days to hours for high-volume pathology departments. |
| Hospital System Partnership | Epic-centric EHR deployments favor API-integrated diagnostic modules over standalone solutions in mid-Atlantic systems. |
| Reimbursement Strategy | CMS coverage with evidence development frameworks align pivotal trial design with Medicare population access. |
| CE Marking Pathway | EMA MDR compliance accelerates consolidation around manufacturers with robust quality management systems. |
| Software Companion Development | PACS-integrated multiparametric MRI workstations reduce inter-reader variability and standardize PI-RADS scoring. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down molecular diagnostic manufacturing tracking forms the analytical core. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and urology practice administrators combined with secondary validation against FDA 510(k) filings, CMS Medicare coverage determinations, hospital procurement databases, and EMA MDR compliance registries. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map test volume flows across PSA testing, multiparametric MRI, liquid biopsy, and digital pathology segments through the projection horizon. Segmentation dimensions modeled include test type, technology platform, end-user facility class, and delivery mode. CAGRs derive from regression analysis of historical procedure volume trends against reimbursement code expansion timelines. Industry-specific forecast inputs incorporate radiotracer isotope supply constraints and pathologist workforce density projections.
Several conditions sit outside the modeled scope, including novel therapeutic radiopharmaceutical approval timelines that could shift theranostic platform investment priorities and unforeseen supply disruptions in molybdenum-99 reactor operations. Forecasts reflect documented assumptions regarding CMS coverage determination velocity and EMA MDR implementation consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Global Rubella Diagnostic Testing Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Antigen Skin Test Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market