
 Germany Ultrasound Devices Market | 2026-2036
Germany Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Ultrasound Devices Market Foresight
Aftermarket service revenue is reshaping profit pools across the Germany ultrasound devices landscape. Siemens Healthineers AG leverages its domestic installed base to dominate preventive maintenance contracts. GE HealthCare anchors its position through remote diagnostic platforms that reduce equipment downtime.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies between 2 and 18 megahertz, with beamforming algorithms processing reflected echoes into real-time anatomical visualizations for non-invasive clinical assessment. Diagnostic ultrasound systems command the largest revenue share among product types due to their ubiquity across German hospital departments. Portable ultrasound is gaining share fastest as emergency and anesthesia departments adopt handheld systems for bedside imaging.
The EU Medical Device Regulation (MDR) and Germany's national implementation through the Federal Institute for Drugs and Medical Devices (BfArM) enforce stricter clinical evaluation and post-market surveillance protocols. CE marking under MDR Annex IX now demands extended clinical data for higher-risk diagnostic equipment, extending approval timelines and elevating compliance costs. Stakeholders must weigh the trade-off between MDR compliance investment and the strategic value of maintaining direct access to Europe's largest medical device procurement market.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing certification timelines and elevating compliance costs, forcing manufacturers to restructure clinical evidence portfolios while German university hospitals accelerate point-of-care ultrasound adoption.
Growth Catalysts
- EU MDR Annex IX compliance pathways:The Federal Institute for Drugs and Medical Devices (BfArM) mandates extended clinical data for higher-risk diagnostic equipment, creating competitive moats for firms with robust post-market surveillance infrastructure.
- Handheld system penetration in emergency departments:Anesthesia and critical care units across Bavarian medical centers are deploying portable ultrasound for bedside imaging, expanding addressable use cases beyond traditional radiology workflows.
- Preventive maintenance contract expansion:German hospital procurement offices are consolidating service agreements with domestic installed-base leaders, locking in multi-year revenue streams for technical support and software updates.
Market Restraints
- Piezoelectric crystal supply concentration:Advanced transducer materials depend on specialized ceramic supply chains concentrated in East Asian manufacturing clusters, exposing German OEMs to input volatility and logistics disruption.
- Extended MDR approval timelines:CE marking under stricter clinical evaluation protocols now demands 18-24 additional months for Class IIa and IIb diagnostic devices, delaying product launches and freezing R&D amortization schedules.
- Computed tomography and MRI substitution:High-resolution cross-sectional imaging modalities continue capturing complex diagnostic cases where ultrasound faces acoustic window limitations or operator dependency constraints.
Strategic Opportunities
- North Rhine-Westphalia university hospital networks:Uncontracted point-of-care ultrasound programs in Essen and Düsseldorf teaching hospitals present first-mover advantages for integrated hardware-software-service bundles.
- Artificial intelligence-enhanced beamforming:Convergence of deep learning algorithms with real-time image reconstruction is creating automated measurement protocols that reduce operator training requirements and expand deployment to non-specialist clinicians.
- Remote diagnostic platform adoption:Cloud-connected predictive maintenance systems are enabling proactive equipment intervention, reducing unplanned downtime and creating subscription-based revenue alternatives to transactional service calls.
Industry Challenges
- Sonographer workforce constraints:German medical technical assistant training programs are producing insufficient certified ultrasound operators to match expanded point-of-care deployment targets, forcing hospitals to rely on physician-performed imaging with variable quality consistency.
- Legacy PACS integration complexity:New ultrasound systems must interface with heterogeneous hospital information architectures dating to the 1990s, requiring costly custom middleware development and extended implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Ultrasound Devices Market |
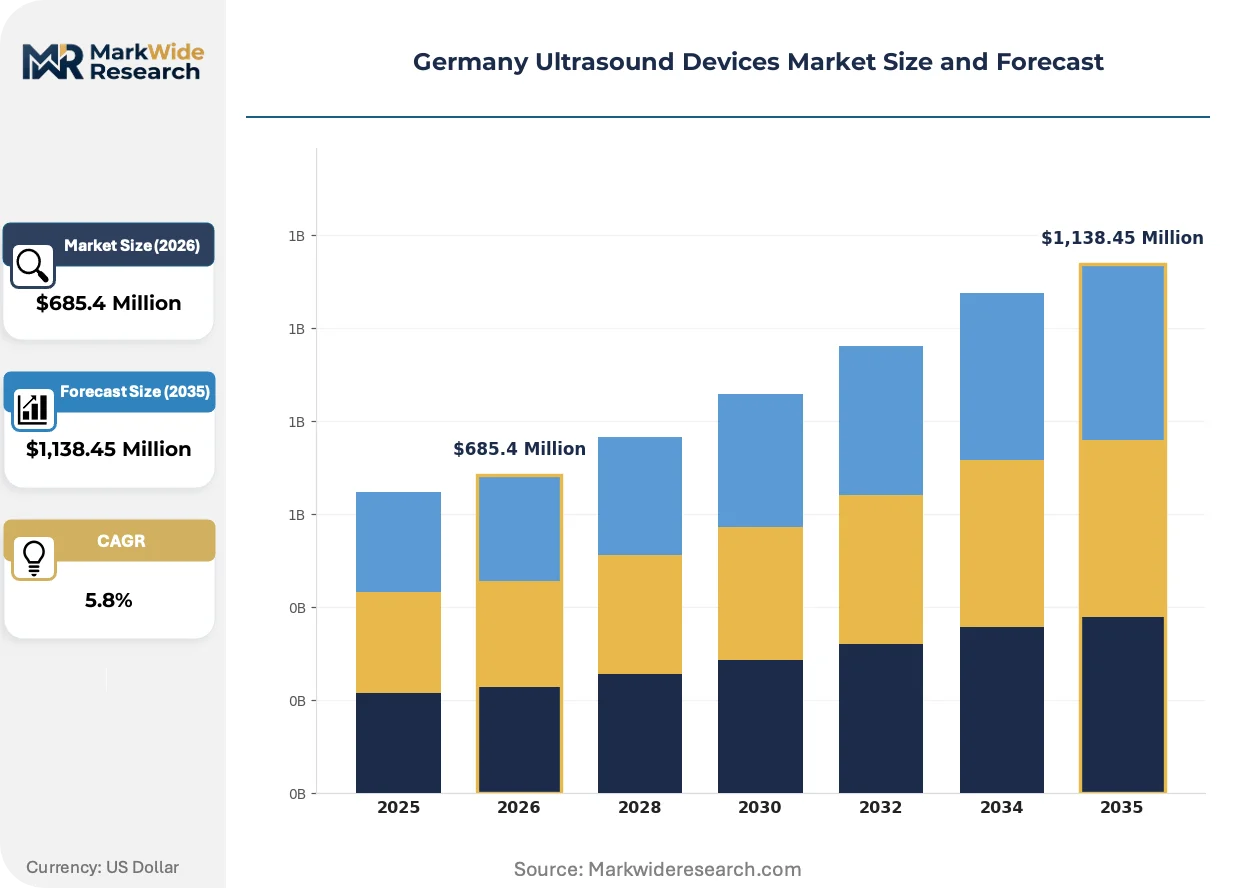
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Cardiovascular Ultrasound, Portable Ultrasound, 3D & 4D Ultrasound Technology: Doppler Ultrasound, B-Mode Ultrasound, Contrast-Enhanced Ultrasound, Elastography, Harmonic Imaging Application: Obstetrics & Gynecology, Cardiovascular Assessment, Musculoskeletal Imaging, Abdominal Imaging, Urology Scanning End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Rehabilitation Facilities, Specialty Laboratories |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips NV, Canon Medical Systems Corporation, Samsung Medison, FUJIFILM Holdings Corp, Mindray Medical International, Esaote, CHISON Medical Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Ultrasound Devices Market Shifts & Advancements
Artificial intelligence integration and portable form-factor miniaturization are restructuring competitive differentiation in German ultrasound markets, compressing the traditional hierarchy between premium cart-based systems and handheld alternatives.
Shear wave elastography is migrating from specialized hepatology applications toward broader abdominal and musculoskeletal assessment. Gastroenterology departments in Munich and Berlin university hospitals are adopting the technique for liver fibrosis staging at expanding volumes. The technology is migrating from high-end cart-based platforms toward mid-range systems, compressing price stratification across diagnostic tiers.
BfArM enforcement of MDR post-market surveillance requirements is mandating systematic clinical follow-up data collection from deployed devices. Manufacturers must now maintain active safety monitoring systems with direct adverse event reporting channels to federal regulators. Higher-risk diagnostic equipment categories face the steepest documentation burdens, with some firms withdrawing legacy product lines rather than absorbing compliance costs.
Hospital procurement offices are consolidating vendor relationships through framework agreements that bundle equipment, software licenses, and preventive maintenance into single-contract structures. Traditional discrete purchasing of hardware with separate service negotiations is yielding to multi-year total-cost-of-ownership models. This concentration is most visible in North Rhine-Westphalia, where regional hospital associations are negotiating collective purchasing terms for point-of-care ultrasound fleets.
Germany Ultrasound Devices Market Segmentation
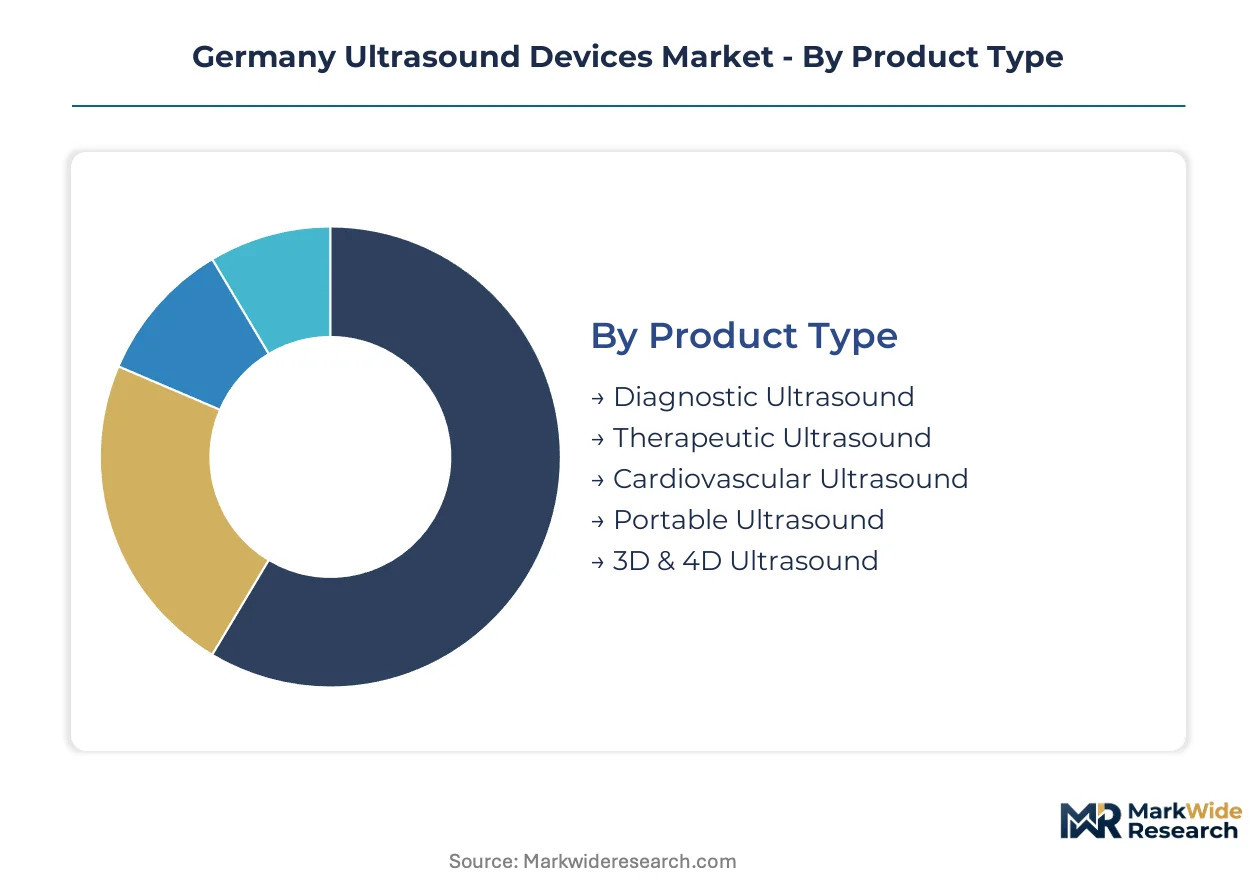
Segmentation reveals how equipment replacement cycles, regulatory risk tiers, and procurement consolidation reshape competitive positioning across German ultrasound markets. Understanding these fault lines exposes where vendors can extract premium pricing versus where volume commoditization accelerates.
Product Type:
Replacement cycles diverge sharply across product categories, with portable systems turning over every 3-4 years while cart-based platforms persist for 7-10 years in German hospital fleets.
- Diagnostic Ultrasound:Cart-based systems with multi-frequency transducer arrays and advanced beamforming processors serve radiology departments as departmental workhorses. Bavarian university medical centers in Munich and Erlangen are consolidating procurement around single-vendor diagnostic fleets to streamline training and service contracts.
- Portable Ultrasound:Handheld and laptop-sized systems with battery-operated probes enable bedside imaging in emergency and anesthesia workflows. North Rhine-Westphalia teaching hospitals in Essen and Düsseldorf are deploying portable fleets for point-of-care programs, bypassing traditional radiology queues.
- Therapeutic Ultrasound:Focused acoustic energy devices for physiotherapy and lithotripsy applications deliver mechanical tissue effects rather than diagnostic imaging.
- Cardiovascular Ultrasound:Dedicated echocardiography systems with phased-array transducers and spectral Doppler for hemodynamic assessment.
- 3D & 4D Ultrasound:Real-time volumetric imaging systems reconstructing fetal and cardiac anatomy from multi-planar data acquisition.
Diagnostic Ultrasound anchors the volume base while Portable Ultrasound gains share at the steepest rate.
Technology:
Technology tiers stratify by margin profile, with premium modalities commanding three-to-four-fold price multiples over standard B-mode configurations in German procurement frameworks.
- Doppler Ultrasound:Frequency-shift detection algorithms measuring blood flow velocity and direction in vascular and cardiac assessment. BfArM's MDR enforcement is extending clinical evidence requirements for quantitative Doppler applications, elevating documentation burdens for color flow mapping systems.
- Elastography:Shear wave propagation analysis quantifying tissue stiffness for liver fibrosis staging and lesion characterization. Gastroenterology departments at Berlin Charité and Munich Klinikum are expanding elastography protocols beyond hepatology into thyroid and breast applications.
- B-Mode Ultrasound:Two-dimensional grayscale anatomical imaging forming the foundational display mode across all diagnostic systems.
- Contrast-Enhanced Ultrasound:Microbubble-based perfusion imaging for lesion characterization and vascular assessment.
- Harmonic Imaging:Frequency-doubled echo processing reducing artifacts and improving resolution in technically difficult patients.
B-Mode Ultrasound generates the broadest installed base while Elastography climbs the fastest as clinical evidence accumulates for expanded indications.
Application:
Application segments map directly to departmental budget autonomy, with obstetrics maintaining independent capital allocation while musculoskeletal imaging depends on orthopedic surgery sponsorship.
- Obstetrics & Gynecology:Fetal biometry, anomaly screening, and gynecologic pelvic assessment protocols. University hospitals in North Rhine-Westphalia are centralizing high-risk obstetric ultrasound into perinatal centers, concentrating advanced 3D/4D volume acquisition capabilities.
- Cardiovascular Assessment:Echocardiography, vascular duplex, and hemodynamic monitoring across inpatient and outpatient settings. German cardiology societies are pushing for structured reporting standardization, favoring platforms with integrated measurement packages and PACS connectivity.
- Musculoskeletal Imaging:Tendon, ligament, and joint assessment in sports medicine and rheumatology workflows.
- Abdominal Imaging:Hepatobiliary, renal, and gastrointestinal tract evaluation in general radiology practice.
- Urology Scanning:Prostate, bladder, and scrotal assessment with transrectal and suprapubic approaches.
Obstetrics & Gynecology commands the deepest historical installed base while Cardiovascular Assessment expands most quickly through outpatient clinic network development.
End User:
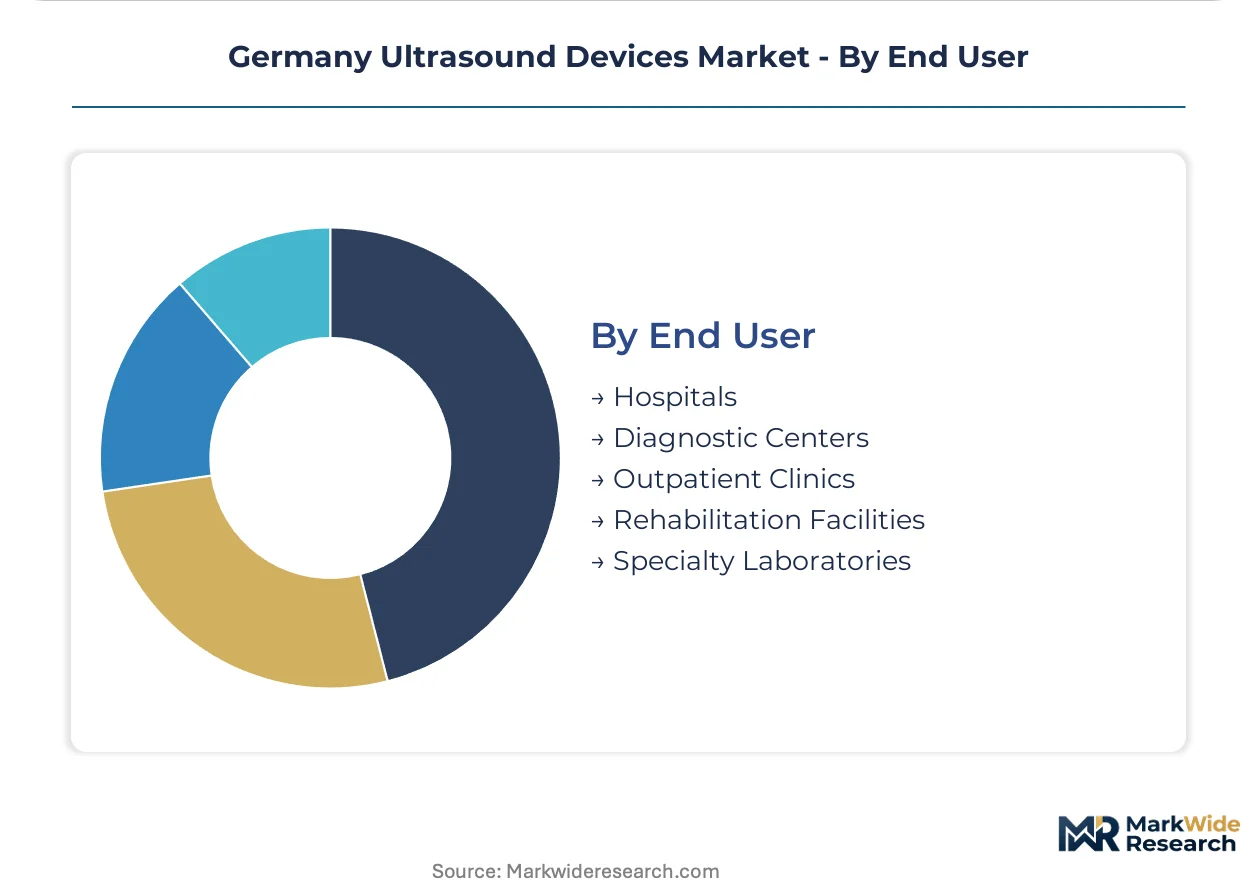
End-user concentration determines contract structure, with hospital procurement offices demanding multi-year bundled agreements while outpatient clinics negotiate transactional equipment purchases.
- Hospitals:Acute care facilities with radiology departments, emergency units, and intensive care pods requiring tiered system configurations. Regional hospital associations in North Rhine-Westphalia are negotiating collective framework agreements covering point-of-care ultrasound fleets across multiple institutions.
- Diagnostic Centers:Dedicated imaging facilities performing high-volume outpatient procedures with throughput-optimized workflows.
- Outpatient Clinics:Physician office practices with limited space and capital budgets favoring compact or handheld systems.
- Rehabilitation Facilities:Physiotherapy-focused settings deploying therapeutic ultrasound for tissue heating and mechanical stimulation.
- Specialty Laboratories:Research and reference laboratories employing high-resolution systems for protocol development and clinical trials.
Hospitals dominate absolute equipment volume while Diagnostic Centers pursue the most aggressive fleet refresh rates to maintain competitive throughput positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ultrasound consumption patterns diverge sharply from neighboring European markets through tighter integration of point-of-care deployment in university hospital networks and stricter BfArM enforcement of MDR post-market surveillance protocols.
Bavaria
Munich and Erlangen university medical centers drive demand for cart-based diagnostic fleets with multi-frequency transducer arrays. BfArM's MDR Annex IX implementation extends clinical evidence timelines for higher-risk equipment. The Erlangen-Nuremberg medical technology cluster concentrates procurement around single-vendor agreements to streamline training standardization.
North Rhine-Westphalia
Essen and Düsseldorf teaching hospitals accelerate portable ultrasound adoption for emergency and anesthesia bedside workflows. Regional hospital associations negotiate collective framework agreements covering point-of-care fleets across multiple institutions. The Rhine-Ruhr metropolitan corridor leads procurement consolidation toward multi-year total-cost-of-ownership contracts.
Baden-Württemberg
Stuttgart and Heidelberg medical centers prioritize AI-enhanced beamforming systems for automated measurement protocols. EU MDR compliance costs elevate barriers for mid-tier diagnostic equipment entrants. The Karlsruhe technology region hosts concentrated service infrastructure for preventive maintenance contract expansion.
Berlin-Brandenburg
Charité Berlin expands shear wave elastography protocols from hepatology into thyroid and breast applications. Germany's national implementation of MDR post-market surveillance mandates systematic clinical follow-up data collection. The capital region's research hospitals drive early adoption of 3D/4D volumetric imaging for high-risk obstetric screening.
Hesse
Frankfurt university hospitals integrate remote diagnostic platforms to reduce equipment downtime across distributed campuses. BfArM enforcement of extended clinical data requirements for Class IIa and IIb devices delays product launches. The Frankfurt-Rhine-Main logistics hub supports spare parts distribution for domestic installed-base service networks.
Germany Ultrasound Devices Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The Germany ultrasound devices landscape organizes around a consolidated core of diversified medical technology conglomerates with deep installed-base relationships, while specialized mid-tier players compete on targeted application expertise. Three archetypes dominate: domestic installed-base leaders leveraging service contract lock-in, multinational imaging platforms pursuing AI-enhanced differentiation, and Asian manufacturers penetrating on portable system cost efficiency. Competitive dynamics center on M&A activity to acquire beamforming algorithm capabilities and strategic partnerships for cloud-connected predictive maintenance infrastructure.
Among diversified medical technology conglomerates, Siemens Healthineers AG anchors the domestic installed-base tier through its AG corporate structure and German origin, while GE HealthCare represents the multinational imaging platform archetype with remote diagnostic positioning. Koninklijke Philips NV occupies a position bridging European heritage with global scale. These three exemplify how market position flows from service infrastructure depth rather than hardware specifications alone.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Samsung Medison |
| FUJIFILM Holdings Corp |
| Mindray Medical International |
| Esaote |
| CHISON Medical Technologies |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr metropolitan corridor's freight logistics costs shape competitive positioning across German ultrasound markets, concentrating pricing power with domestic installed-base leaders while elevating landed costs for Asian portable system imports. MDR compliance investments and piezoelectric crystal supply constraints feed directly into three-tier pricing stratification across premium diagnostic fleets, mid-range elastography platforms, and handheld economy units.
Pricing Analysis
Long-term preventive maintenance contracts dominate procurement structures, with North Rhine-Westphalia hospital associations negotiating multi-year total-cost-of-ownership agreements that bundle hardware, software licenses, and technical support. Price differentiation rests on BfArM certification tier and installed-base service depth, with domestic OEMs commanding premiums for MDR Annex IX compliance infrastructure. Cost compression in portable ultrasound intensifies as Mindray and Samsung Medison penetrate on manufacturing scale, while cart-based diagnostic systems retain pricing resilience through sonographer training lock-in. Outpatient clinics exhibit highest price sensitivity, deferring replacement cycles to match reimbursement schedules.
Supply Chain Analysis
EU dual-use export controls on advanced piezoelectric ceramics and beamforming processors limit technology flows from German OEMs to non-aligned manufacturing jurisdictions. Component sourcing draws from Japanese ceramic substrate suppliers, South Korean semiconductor foundries, and Chinese transducer assembly operations, creating tariff exposure through diversified but concentrated input channels. Single-source vulnerability concentrates in specialized lead zirconate titanate crystal production for high-frequency transducers. Distribution runs through regional hospital procurement offices consolidating vendor relationships, with spare parts logistics anchored at Frankfurt-Rhine-Main distribution hubs serving domestic preventive maintenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German ultrasound markets are recovering from MDR implementation cyclicality, with hospital capital expenditure normalization following extended approval timeline disruptions. Equipment replacement backlogs and point-of-care expansion programs now drive procurement momentum.
For Market Incumbents: Build post-market surveillance infrastructure moats by investing in BfArM-compliant clinical follow-up systems that emerging entrants cannot replicate. Siemens Healthineers and GE HealthCare should deepen backward integration into beamforming algorithm development to defend against AI-native diagnostic platforms. Consolidate service contract density in Bavarian university medical centers before portable system commoditization accelerates. For New Entrants and Emerging Players: Build out uncontracted point-of-care ultrasound programs in Essen and Düsseldorf teaching hospitals, where regional procurement consolidation has lagged single-vendor framework adoption. Target anesthesia and critical care departments with AI-enhanced handheld systems that reduce physician training requirements. Pursue software-as-a-service pricing models to bypass capital expenditure approval bottlenecks in hospital procurement offices. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enhanced beamforming specialists over legacy hardware platforms, with automated measurement protocols representing the highest-margin expansion vector. Five-to-ten year viability hinges on MDR compliance infrastructure amortization across expanding European installed bases. Watch BfArM adverse event reporting volume as inflection indicator for regulatory enforcement intensity and compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Annex IX Compliance Investment | BfArM clinical evidence requirements create sustainable competitive barriers for certified device portfolios. |
| AI-Enhanced Beamforming Development | Deep learning integration at Munich university hospitals reduces operator dependency and expands addressable clinician base. |
| Preventive Maintenance Contract Expansion | Multi-year service agreements with North Rhine-Westphalia hospital associations lock in recurring revenue streams. |
| Point-of-Care Fleet Deployment | Emergency department handheld adoption in Bavarian medical centers bypasses traditional radiology workflow constraints. |
| Remote Diagnostic Platform Integration | Cloud-connected predictive maintenance systems at Frankfurt university hospitals reduce unplanned equipment downtime. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, incorporating perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and ultrasound device manufacturers. Secondary validation drew from BfArM regulatory filings, EU MDR implementation guidance documents, hospital procurement databases, and medical technology trade association reports. Bottom-up segmentation modeling triangulated against top-down market sizing from equipment shipment tracking and service contract value analysis.
Calibration across historical replacement cycle data, MDR approval timeline extensions, and regional procurement consolidation patterns anchored the analytical framework. Segmentation dimensions modeled include product type tier, technology modality, application specialty, and end-user facility class across the projection horizon. CAGRs were derived from equipment unit growth trajectories and average selling price evolution by diagnostic versus portable system categories, with elastography penetration rates and AI software attach rates serving as key forecast sensitivity inputs.
Stress conditions across MDR enforcement intensity, piezoelectric supply disruption scenarios, and hospital budget freeze durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding procurement normalization timelines and technology substitution thresholds. Material shifts in BfArM post-market surveillance requirements or EU medical device reimbursement classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global Transradial Access Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Inversion Table Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Global Oxygen Conservation Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Intermittent Catheters Market
Medical Devices
Global Cardiac Holter Monitor Market