
 Global Artificial Intelligence (AI) in Diagnostics Market | 2026-2036
Global Artificial Intelligence (AI) in Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence (AI) in Diagnostics Market Foresight
Cloud infrastructure is shifting from on-premise hospital servers to GPU-enabled distributed computing, collapsing per-scan processing costs for AI diagnostic workloads. NVIDIA Corporation leverages its CUDA ecosystem to anchor hardware-software bundles across imaging networks. Siemens Healthineers sustains R&D intensity in deep learning reconstruction for MRI and CT modalities. Aidoc specializes in FDA-cleared triage algorithms for intracranial hemorrhage and pulmonary embolism, occupying the acute care notification segment.
Artificial Intelligence in Diagnostics encompasses computational systems that analyze medical data—radiological images, pathology slides, electronic health records, and genomic sequences—using trained statistical models to identify patterns indicative of disease presence, progression, or treatment response, with typical inference latency under thirty seconds per study and sensitivity thresholds exceeding ninety percent in validated cohorts. These systems primarily reduce diagnostic error rates, compress radiologist reading times, and enable population-scale screening programs. Deep learning architectures dominate imaging analysis software development, while machine learning retains primacy in predictive analytics platforms for cardiovascular risk stratification. Diagnostic decision support systems command premium pricing due to integration complexity with legacy hospital information systems.
The FDA's software-as-a-medical-device framework and the EU AI Act's high-risk system classification jointly determine market access requirements for diagnostic algorithms across North America and Europe. Japan's PMDA operates an accelerated review pathway for AI-enabled medical devices with comparable predicate approvals. China's NMPA mandates local clinical trials for deep learning diagnostic software, creating distinct regulatory moats for domestic versus foreign developers. Stakeholders must monitor evolving reimbursement parity between AI-assisted and conventional diagnostic reads as the decisive factor for enterprise procurement decisions.
Market Dynamics
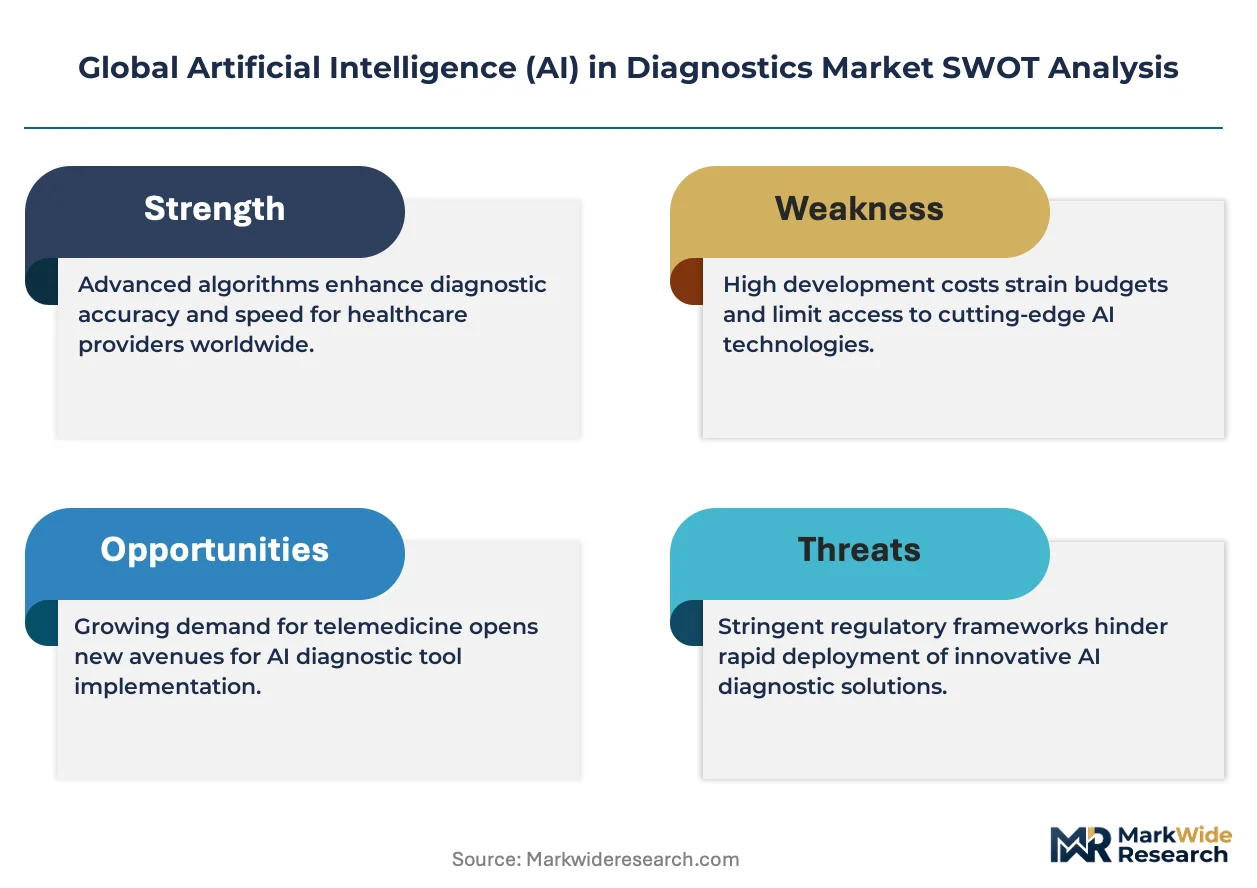
Cloud GPU infrastructure is collapsing per-scan processing economics while FDA de novo clearances accelerate algorithm deployment timelines for radiology networks.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The FDA's streamlined de novo pathway reduces clearance timelines for diagnostic algorithms, enabling faster commercialization of AI-enabled lesion detection tools in US tertiary hospitals.
- GPU-Enabled Distributed Computing:NVIDIA's CUDA ecosystem anchors hardware-software bundles that slash inference costs for high-resolution imaging workloads across multi-site radiology networks.
- Japan PMDA Accelerated Review:Japan's Pharmaceuticals and Medical Devices Agency operates fast-track approvals for AI devices with predicate clearances, concentrating demand in Tokyo and Osaka metropolitan hospital clusters.
Market Restraints
- EU AI Act High-Risk Classification:The EU AI Act's stringent conformity requirements for diagnostic algorithms impose documentation burdens and CE marking delays that compress margins for European market entry.
- NMPA Local Clinical Trial Mandate:China's National Medical Products Administration requires domestic validation studies for deep learning diagnostic software, creating regulatory moats favoring indigenous developers.
- Legacy HIS Integration Complexity:Hospital information system interoperability gaps force costly custom engineering for AI diagnostic deployment, particularly in mid-tier German and Japanese facilities with heterogeneous IT estates.
Strategic Opportunities
- Pathology Slide Analysis Convergence:Digital pathology platforms integrating whole-slide imaging with deep learning represent underpenetrated white space beyond radiology's current AI saturation.
- India CDSCO Emerging Pathway:India's Central Drugs Standard Control Organization is formalizing AI medical device guidelines, opening reimbursement negotiations for algorithm-assisted reads in Mumbai and Delhi NCR hospital chains.
- Federated Learning Architectures:Privacy-preserving distributed training across hospital networks without centralizing patient data is unifying multi-site algorithm development while satisfying HIPAA and GDPR constraints.
Industry Challenges
- Radiologist-AI Workflow Integration:Clinical validation requires prospective studies measuring diagnostic accuracy gains and reading time compression, extending sales cycles by twelve to eighteen months in academic medical centers.
- Algorithm Drift Monitoring:Post-market surveillance obligations under FDA 510(k) and EU MDR demand continuous performance tracking across diverse patient populations and scanner modalities, straining quality infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence (AI) in Diagnostics Market |
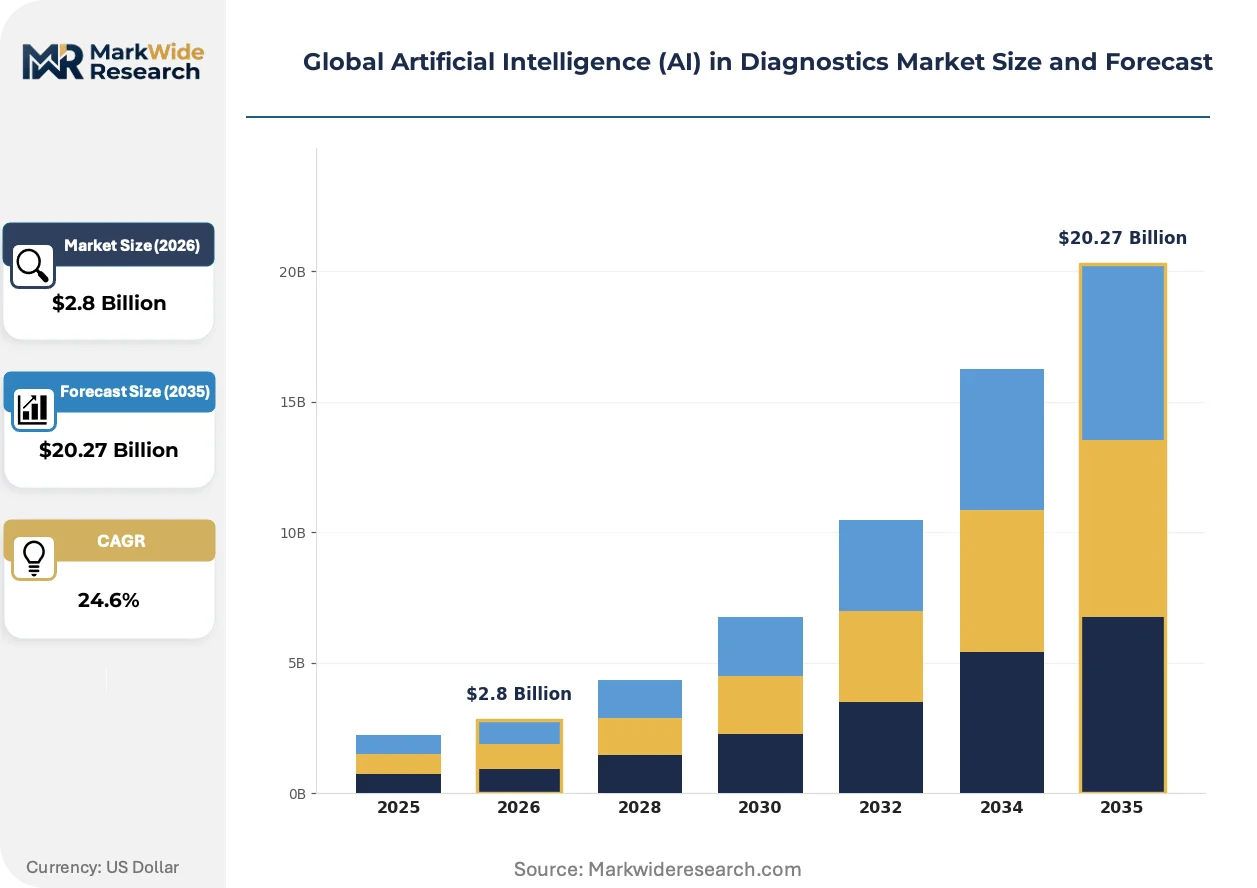
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Analysis Software, Predictive Analytics Platforms, Natural Language Processing Tools, Diagnostic Decision Support Systems Technology: Machine Learning, Deep Learning, Computer Vision, Neural Networks, Reinforcement Learning Application: Oncology Screening, Cardiovascular Risk Assessment, Neurological Disorder Detection, Infectious Disease Identification End User: Diagnostic Laboratories, Research Institutes, Specialized Clinics, Medical Imaging Centers |
| Companies Covered | Microsoft, Aidoc, Siemens Healthineers, Koninklijke Philips N.V., Vuno, Inc., GE Healthcare, Digital Diagnostics, Inc., Google Health, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence (AI) in Diagnostics Market Shifts & Advancements
Foundation models trained on multi-modal medical data are compressing development timelines while regulatory sandboxes in major economies test adaptive approval mechanisms for continuously learning algorithms.
Vision transformers applied to radiological imaging are unifying detection, segmentation, and reporting tasks within single architectures. Tertiary hospitals in the United States and Germany are piloting these unified pipelines for chest X-ray and CT interpretation. This convergence is collapsing the vendor landscape for point-solution algorithms into comprehensive diagnostic platforms.
The EU AI Act's high-risk system classification mandates conformity assessments, technical documentation, and human oversight protocols for diagnostic algorithms deployed in European clinical settings. Device manufacturers must maintain quality management systems and post-market monitoring infrastructure that satisfy notified body scrutiny. German and French hospital procurement committees now require AI Act compliance certification as a gate criterion for tender participation.
Hospital purchasing committees are consolidating vendor relationships around enterprise-wide AI contracts rather than modality-specific point solutions. Radiology departments in Japan and the United States are negotiating multi-year platform agreements that bundle imaging AI with pathology and clinical decision support tools. This concentration is visible most acutely in US integrated delivery networks and Japanese university hospital alliances seeking unified data governance across subspecialties.
Global Artificial Intelligence (AI) in Diagnostics Market Segmentation
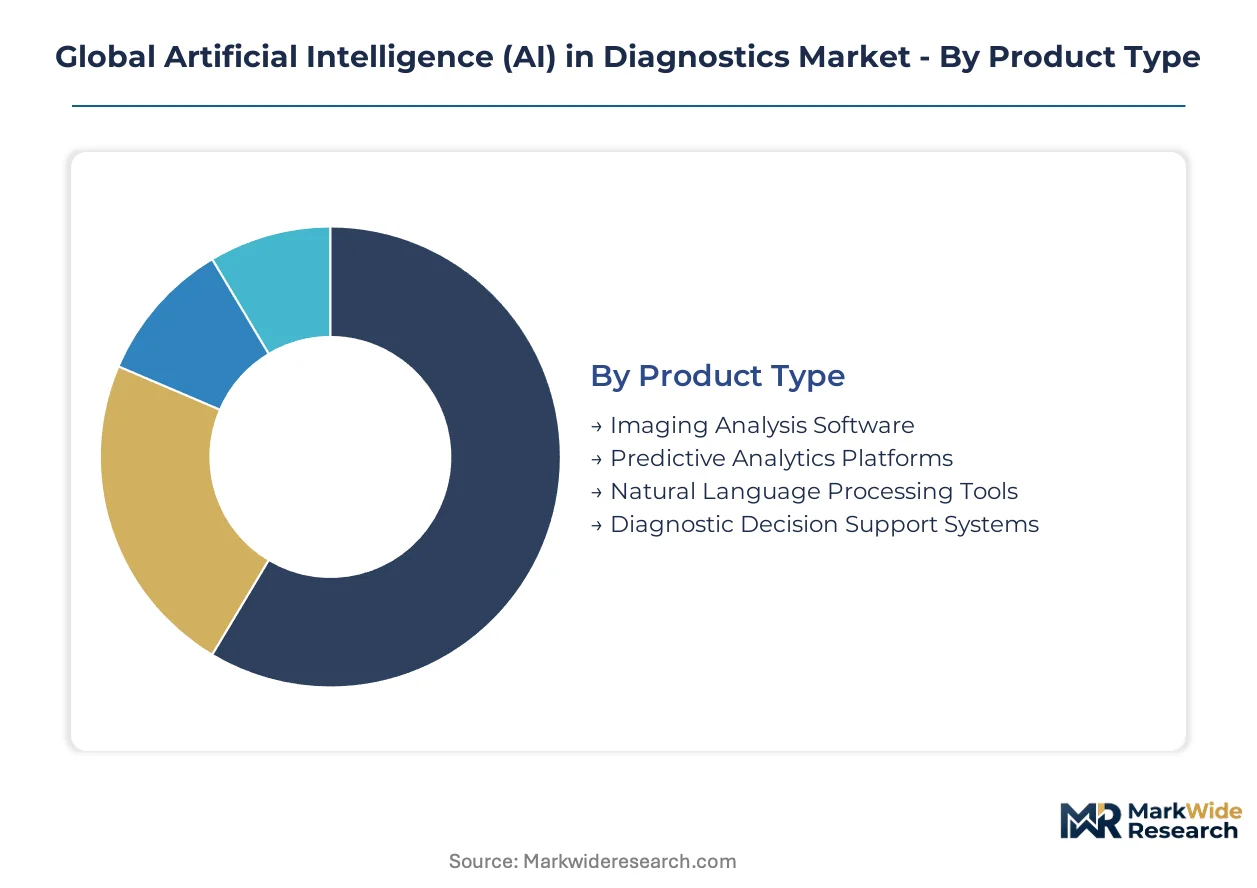
Segmentation reveals where capital deployment concentrates and which technology layers command premium valuation multiples. Product architecture, algorithmic approach, clinical use case, and procurement channel each shape vendor strategy and margin structure differently.
Product Type:
Imaging analysis software demands the heaviest upfront investment in regulatory clearance and clinical validation studies.
- Imaging Analysis Software:Deep learning architectures process radiological images, pathology slides, and dermatological photographs with sub-thirty-second inference latency. United States tertiary hospitals concentrate procurement around FDA-cleared lesion detection tools, driven by formalizing reimbursement codes for AI-assisted reads.
- Predictive Analytics Platforms:Machine learning models stratify cardiovascular risk and predict disease progression from electronic health record data. German hospital networks prioritize these platforms for population health management, constrained by legacy HIS integration complexity.
- Natural Language Processing Tools:Computational linguistics extract diagnostic insights from unstructured clinical notes and genomic reports.
- Diagnostic Decision Support Systems:Integrated platforms combine multiple AI modalities with workflow orchestration layers.
Most installed capacity flows through Imaging Analysis Software. Expansion is steepest in Predictive Analytics Platforms.
Technology:
Deep learning and computer vision attract the majority of venture funding and GPU infrastructure allocation.
- Deep Learning:Convolutional and transformer architectures dominate medical imaging with superior pattern recognition in radiological studies. Japanese university hospital alliances deploy these systems for chest X-ray and CT interpretation, accelerating under PMDA fast-track approvals.
- Computer Vision:Specialized pipelines for segmentation, registration, and three-dimensional reconstruction enable quantitative biomarker extraction. United States integrated delivery networks invest here for multi-site standardization, pressured by algorithm drift monitoring obligations.
- Machine Learning:Traditional statistical methods retain primacy in structured data analysis and risk scoring.
- Neural Networks:Architectures spanning feedforward, recurrent, and graph neural network variants address specific diagnostic tasks.
- Reinforcement Learning:Adaptive systems optimize diagnostic pathways and resource allocation in dynamic clinical environments.
Deep learning absorbs the largest share of R&D expenditure. Computer vision is climbing the fastest as vision transformers unify detection and reporting tasks.
Application:
Oncology screening commands the highest per-patient lifetime value and justifies premium platform pricing.
- Oncology Screening:Multi-cancer early detection algorithms analyze liquid biopsy data and cross-sectional imaging for tumor signatures. Diagnostic laboratories in Germany and Japan concentrate demand here, propelled by formalizing reimbursement for algorithm-assisted reads.
- Cardiovascular Risk Assessment:Predictive models integrate echocardiography, CT angiography, and ECG signals for event prediction. Research institutes in the United States prioritize these tools, limited by prospective clinical validation requirements.
- Neurological Disorder Detection:AI triage systems flag intracranial hemorrhage and stroke patterns for accelerated intervention.
- Infectious Disease Identification:Algorithms classify pathogen signatures from imaging and molecular diagnostic inputs.
Oncology screening captures the greatest revenue concentration. Cardiovascular risk assessment is expanding most quickly as payors recognize prevention economics.
End User:
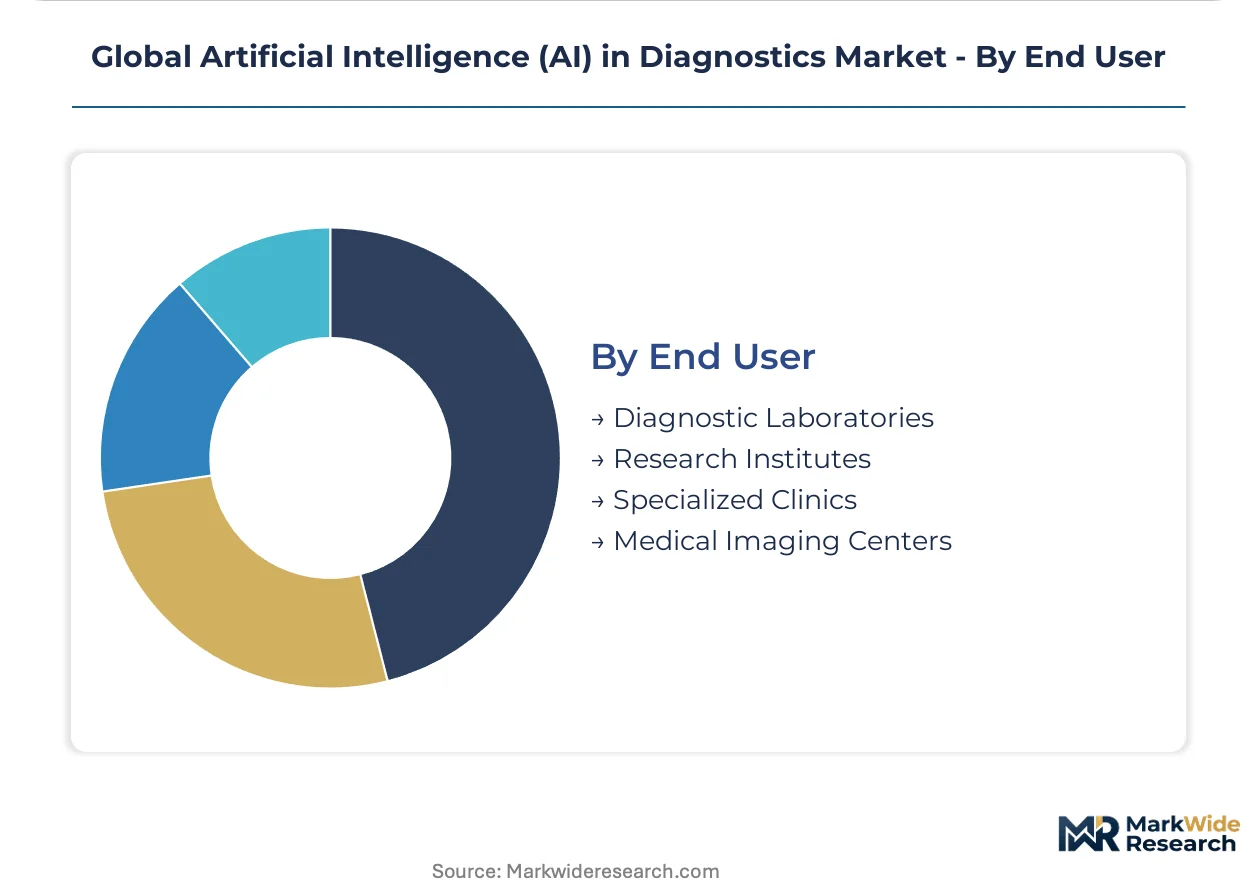
Diagnostic laboratories scale fastest due to centralized infrastructure and high-throughput workflows.
- Diagnostic Laboratories:High-volume processing centers deploy AI for pathology slide analysis and molecular diagnostic interpretation. Medical imaging centers in Tokyo and Osaka metropolitan clusters drive procurement, supported by Japan's PMDA accelerated review pathway.
- Medical Imaging Centers:Dedicated radiology facilities integrate AI for workflow prioritization and quality assurance. United States outpatient imaging networks concentrate investment here, navigating FDA software-as-a-medical-device clearance timelines.
- Research Institutes:Academic medical centers validate algorithms and train foundation models on multi-modal data.
- Specialized Clinics:Focused practices in cardiology, dermatology, and ophthalmology deploy point-solution algorithms.
Diagnostic laboratories host the greatest installed base. Medical imaging centers are gaining share fastest as federated learning enables multi-site deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo-Osaka metropolitan clusters anchor diagnostic AI deployment through Japan's PMDA accelerated review pathway. Hospital procurement committees in Germany and the United States formalize reimbursement codes for AI-assisted reads. China's NMPA mandates local clinical trials, creating regulatory moats for indigenous developers.
United States
FDA software-as-a-medical-device clearances concentrate in tertiary hospital radiology departments. Reimbursement parity negotiations between CMS and private payors determine enterprise procurement timelines. Academic medical centers in Boston and Stanford anchor clinical validation studies for lesion detection algorithms.
Germany
EU AI Act high-risk classification imposes conformity documentation burdens on diagnostic algorithm vendors. Hospital information system integration complexity strains mid-tier facility deployments. Munich and Berlin university hospital alliances negotiate multi-year platform agreements bundling imaging AI with pathology tools.
Japan
PMDA fast-track approvals for predicate-cleared AI devices accelerate Tokyo metropolitan hospital adoption. Deep learning reconstruction for CT and MRI modalities dominates R&D investment. Osaka medical imaging centers pilot federated learning architectures across multi-site networks.
China
NMPA domestic clinical trial requirements favor indigenous developers of deep learning diagnostic software. Yangtze River Delta hospital chains concentrate procurement of pathology slide analysis platforms. Beijing-Tianjin-Hebei corridor anchors regulatory sandbox testing for continuously learning algorithms.
India
CDSCO emerging guidelines for AI medical devices open reimbursement negotiations in Mumbai and Delhi NCR hospital chains. Diagnostic laboratories scale fastest due to centralized infrastructure and high-throughput workflows. Karnataka's Bangalore tech corridor supplies engineering talent for algorithm development.
Global Artificial Intelligence (AI) in Diagnostics Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance velocity and hospital network penetration. The vendor base stratifies into three tiers: cloud infrastructure providers anchoring hardware-software bundles, diversified medical technology conglomerates sustaining R&D intensity across modalities, and specialized algorithm developers occupying acute care notification segments. Strategic moves concentrate on federated learning partnerships and enterprise-wide platform consolidation.
Within the specialized algorithm tier, Aidoc and Digital Diagnostics, Inc. exemplify FDA-cleared point-solution developers. Among diversified medical technology conglomerates, Siemens Healthineers and Koninklijke Philips N.V. occupy positions spanning imaging hardware and AI software integration. NVIDIA Corporation anchors the cloud infrastructure layer through GPU-enabled distributed computing ecosystems.
| Leading Market Players |
|---|
| Microsoft |
| Aidoc |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Vuno, Inc. |
| GE Healthcare |
| Digital Diagnostics, Inc. |
| Google Health |
| NVIDIA Corporation |
| Others |
Supply & Pricing Matrix
United States integrated delivery networks and Japanese university hospital alliances concentrate procurement authority, anchoring enterprise-wide platform contracts that bundle imaging AI with pathology tools under multi-year subscription frameworks.
Pricing Analysis
GPU compute costs and regulatory clearance expenses pass through to end-users via tiered SaaS licensing structures. Pricing stratifies across FDA-cleared premium tiers, CE-marked standard tiers, and emerging economy tiers for pilot deployments. Price differentiation hinges on validation cohort size and integration complexity with legacy hospital information systems. Cost compression in mid-tier German and Japanese facilities is intensifying because legacy HIS interoperability gaps force custom engineering surcharges. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while mid-tier community hospitals in India demonstrate highest sensitivity to per-scan transaction fees.
Supply Chain Analysis
Cloud GPU supply rests on NVIDIA's foundry partnerships in Taiwan and TSMC's advanced node capacity, with secondary sourcing from Samsung's South Korean fabrication complexes. Specialized AI accelerators, high-bandwidth memory modules, and precision cooling systems constitute critical component dependencies. Single-source vulnerability in Taiwan Strait logistics corridors threatens inference cost stability for distributed radiology networks. Distribution runs through hyperscaler marketplaces and direct hospital procurement committees, bypassing traditional medical device distributors for software-as-a-medical-device deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement committees are consolidating vendor relationships around quality-validated platforms, shifting demand toward algorithms with multi-site clinical validation and continuous performance monitoring infrastructure.
For Market Incumbents: Anticipate margin compression from federated learning architectures that enable hospital networks to develop in-house algorithms without centralizing patient data. Defensive positioning requires deepening CUDA ecosystem lock-in through hardware-software bundles and accelerating FDA 510(k) pathway submissions for continuously learning algorithms. Priority levers include backward integration into pathology slide imaging hardware and exclusive GPO contracts with United States integrated delivery networks. For New Entrants and Emerging Players: The price-point gap between premium FDA-cleared platforms and economy-tier pilot deployments offers entry traction. White-space targets include digital pathology platforms beyond radiology's current saturation and India's CDSCO-emerging reimbursement corridors. The most penetrable segment comprises diagnostic laboratories in Mumbai and Delhi NCR seeking high-throughput slide analysis tools. Go-to-market execution should anchor on federated learning partnerships that satisfy HIPAA and GDPR constraints without upfront infrastructure investment. For Investors and Strategic Acquirers: Cloud infrastructure providers are the most active acquirer in this space, seeking algorithm developers to anchor hardware-software bundles. Long-term viability favors platforms with regulatory clearance velocity across multiple jurisdictions and recurring revenue concentration in enterprise contracts. Acquisition target archetypes include specialized developers with FDA-cleared triage algorithms and established hospital network penetration. The signal to watch is CMS reimbursement parity decisions for AI-assisted diagnostic reads as the decisive inflection for enterprise procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Clearance Acceleration | FDA de novo submissions compress commercialization timelines for lesion detection algorithms in tertiary hospitals. |
| Federated Learning Partnership | Multi-site algorithm development satisfies HIPAA constraints while preserving data sovereignty across hospital networks. |
| Enterprise Platform Consolidation | Bundled imaging-pathology contracts reduce vendor fragmentation for United States integrated delivery networks. |
| GPU Ecosystem Lock-in | CUDA-anchored hardware-software bundles raise switching costs for radiology departments deploying inference workloads. |
| Reimbursement Strategy Execution | CMS parity negotiations determine procurement timelines for AI-assisted reads in outpatient imaging networks. |
Research Methodology
Direct dialogue with hospital purchasing committee chairs, biomedical engineering directors, regulatory affairs leads at algorithm developers, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) and de novo clearance databases, EU MDR notified body documentation, CMS reimbursement coding bulletins, and hospital procurement records. Bottom-up and top-down triangulation reconciled installed base estimates with revenue concentration patterns across vendor tiers.
Bottom-up modeling segmented the analysis window by product architecture, algorithmic approach, clinical application, and procurement channel. Deep learning imaging software, predictive analytics platforms, and diagnostic decision support systems constituted primary product dimensions. Oncology screening, cardiovascular risk assessment, and neurological disorder detection anchored application-level granularity. CAGRs derived from regression analysis of regulatory clearance velocity, reimbursement formalization trajectories, and GPU infrastructure cost curves.
Caveats apply where EU AI Act conformity delays, NMPA domestic trial mandates, or algorithm drift monitoring obligations could materially shift the outlook. Forecasts reflect assumptions regarding reimbursement parity negotiation timelines and hyperscaler capex commitments to healthcare GPU clusters. A small set of named triggers warrants ongoing watch: CMS coding decisions, PMDA accelerated review pathway expansions, and federated learning standardization across multi-site hospital networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Sperm Count Test Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
HDL Cholesterol Kits Market