
 Global Bladder Cancer Therapeutics and Diagnostics Market | 2026-2036
Global Bladder Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bladder Cancer Therapeutics and Diagnostics Market Foresight
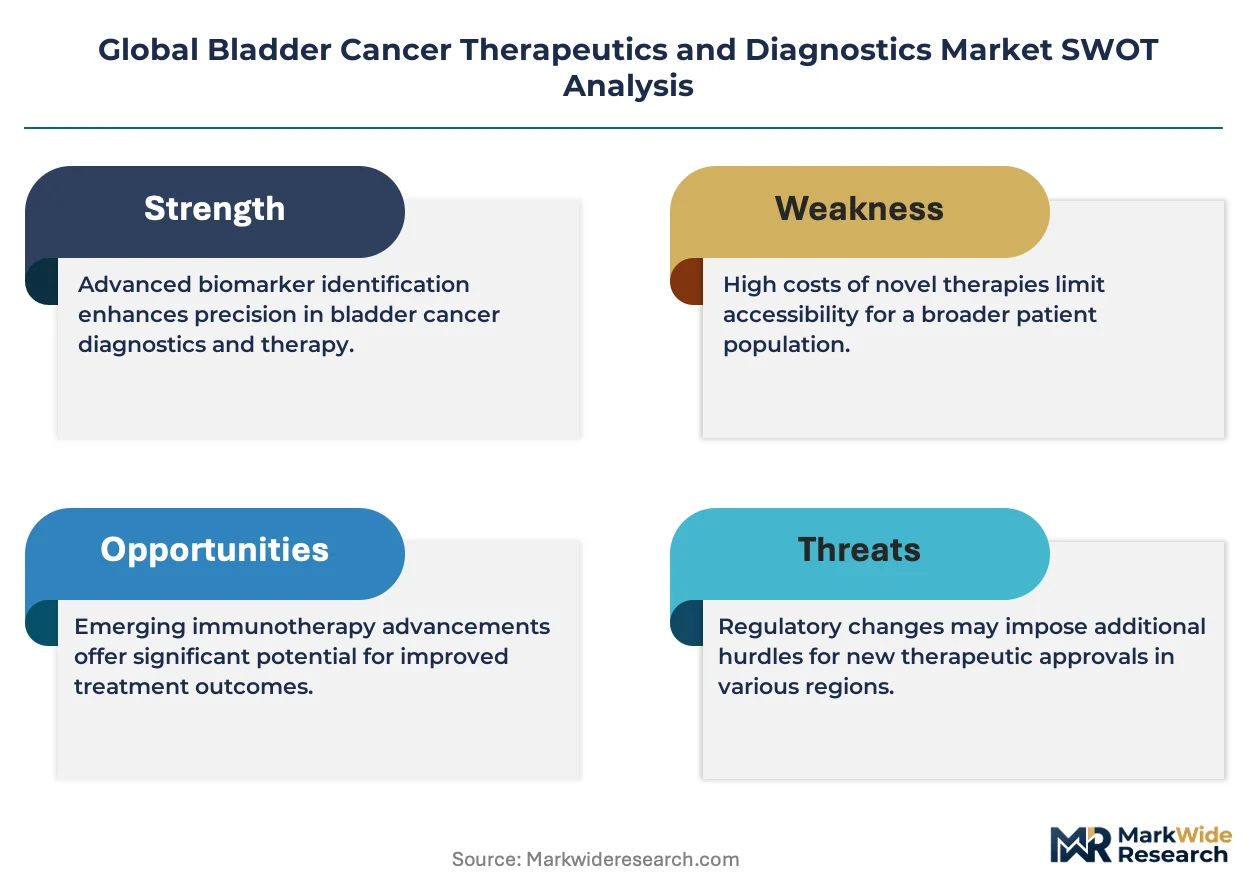
Hospital procurement is rotating toward ambulatory surgical centers as the preferred site for diagnostic cystoscopies and intravesical instillations. Roche Holding AG leverages its dominance in companion diagnostics to anchor molecular profiling workflows across European and North American accounts. Pfizer Inc sustains manufacturing scale in chemotherapy supply chains that feed both inpatient and outpatient channels. Bristol-Myers Squibb Company differentiates through checkpoint inhibitor portfolios that compete directly in muscle-invasive and metastatic settings.
Bladder cancer therapeutics and diagnostics encompasses pharmaceutical interventions, minimally invasive delivery systems, and molecular detection platforms designed to treat or identify urothelial malignancies across disease stages. Intravesical bacillus Calmette-Guérin remains the functional standard for carcinoma in situ, while next-generation sequencing panels now guide targeted therapy selection in metastatic disease. Immunotherapy commands the largest margin pool among product types, though urine biomarkers represent the fastest-expanding segment as laboratories replace repeat cystoscopy with non-invasive surveillance protocols. Diagnostic imaging maintains structural importance in staging workflows despite slower growth, anchored by CT urography and MRI protocols that define muscle-invasive progression.
FDA breakthrough therapy designation and EMA conditional approval pathways compress development timelines for novel biologics, while Japan's PMDA sakigake framework accelerates domestic access to innovative diagnostics. WHO classification revisions for urothelial neoplasia directly shape reimbursement criteria for histopathology and molecular testing across multiple jurisdictions. Stakeholders must monitor evolving payer evidence requirements for liquid biopsy platforms as these assays challenge tissue-based standards in post-treatment surveillance.
Market Dynamics
The migration of diagnostic workflows from hospital-based cystoscopy suites to ambulatory surgical centers is compressing capital deployment cycles and reshaping vendor contracting structures across the United States, Germany, and Japan.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses clinical development timelines for novel checkpoint inhibitors targeting muscle-invasive disease, enabling earlier commercial access.
- Urine Biomarker Surveillance:Non-invasive molecular testing protocols are replacing repeat cystoscopy in post-treatment monitoring, expanding laboratory service volumes and reducing procedural costs.
- Japan's PMDA Sakigake Framework:The expedited review system accelerates domestic market entry for innovative diagnostics, incentivizing manufacturers to prioritize regulatory submissions in Tokyo.
Market Restraints
- Platinum-Based Chemotherapy Supply Concentration:Manufacturing capacity for cisplatin and gemcitabine concentrates among a limited supplier base in India and China, exposing procurement to geopolitical disruption.
- Tissue Biopsy Dependency:Histopathological confirmation remains mandatory for reimbursement eligibility under most national health technology assessment frameworks, limiting liquid biopsy penetration.
- BCG Manufacturing Bottlenecks:Production of intravesical bacillus Calmette-Guérin relies on a single global supplier, creating persistent allocation shortages that delay induction therapy initiation.
Strategic Opportunities
- Companion Diagnostic Convergence:Integration of next-generation sequencing panels with PD-1/PD-L1 inhibitor prescribing creates integrated testing-treatment bundles for oncology clinics.
- Ambulatory Site Expansion:Freestanding surgical centers in the United States and Germany are deploying flexible cystoscopy suites with same-day discharge protocols, opening capital equipment procurement channels.
- EMA Conditional Approval Pathways:The early access scheme enables revenue recognition prior to completion of confirmatory trials, improving cash flow for developers of novel antibody-drug conjugates.
Industry Challenges
- Pathologist Workforce Constraints:Specialized uropathology expertise concentrates in academic medical centers, creating diagnostic backlogs that delay treatment initiation in community settings.
- Interoperability Fragmentation:Electronic health record systems lack standardized interfaces for molecular profiling results, forcing manual data entry that introduces staging errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bladder Cancer Therapeutics and Diagnostics Market |
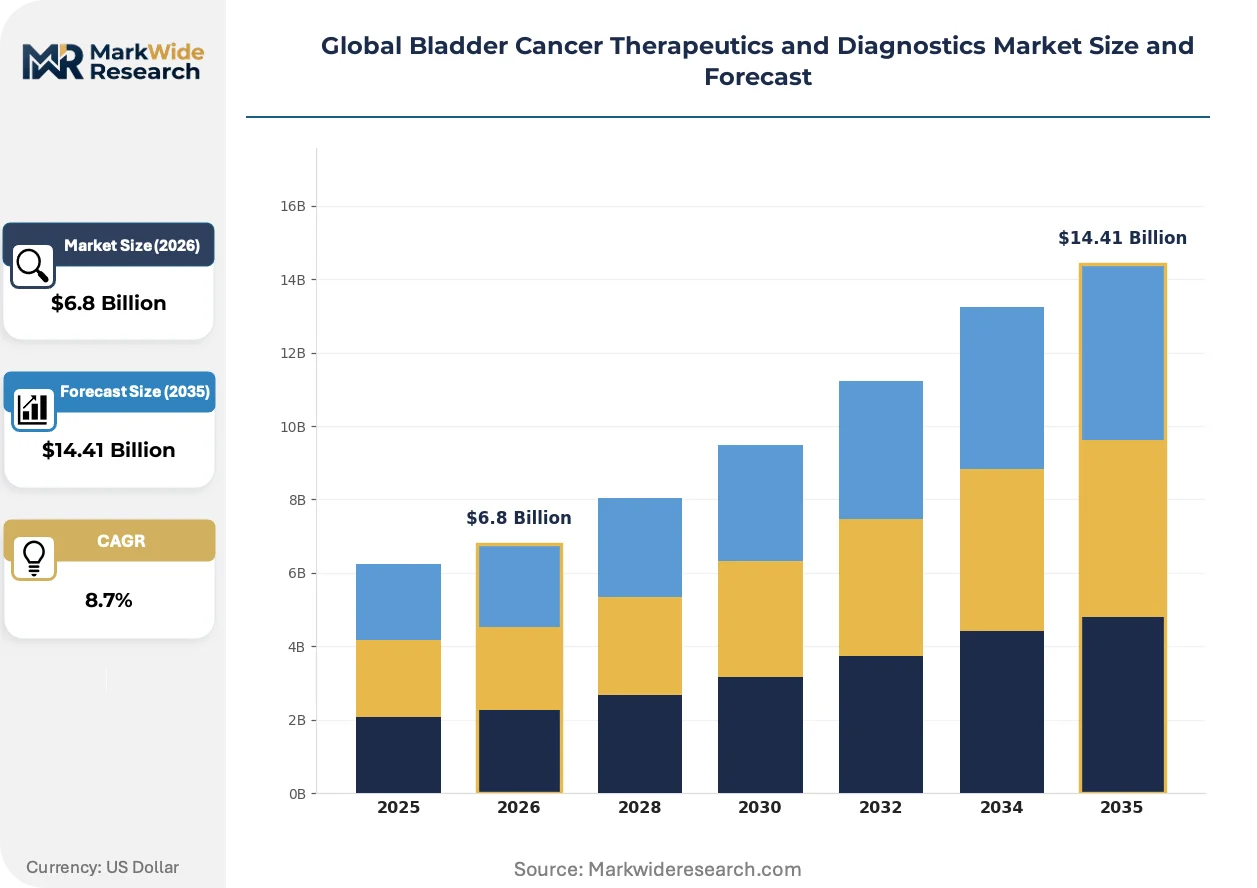
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Chemotherapy, Targeted Therapy, Diagnostic Imaging, Urine Biomarkers, Surgical Procedures Therapy Area: Non-Muscle Invasive, Muscle Invasive, Metastatic, Recurrent, Superficial, Carcinoma In Situ End User: Oncology Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Cancer Research Institutes Delivery Mode: Intravesical, Intravenous, Oral, Cystoscopy, Imaging Techniques, Biomarker Assays |
| Companies Covered | Roche Holding AG, Pfizer Inc, Merck & Co Inc, AstraZeneca PLC, Bristol-Myers Squibb Company, Novartis AG, Bayer AG, Johnson & Johnson, GlaxoSmithKline PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bladder Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Digital pathology platforms and artificial intelligence-assisted cytology are compressing diagnostic turnaround times while simultaneously enabling decentralized interpretation workflows that challenge traditional laboratory hierarchies.
Artificial intelligence algorithms trained on whole-slide imaging datasets are displacing manual cytology review in high-volume screening laboratories. European pathology networks in the Netherlands and Sweden have deployed these systems for preliminary urothelial carcinoma detection, reducing pathologist review burden by flagging negative cases for automated exclusion. The technology is displacing tier-one diagnostic outsourcing contracts as hospital systems bring interpretation capabilities in-house.
EMA's Medical Device Regulation (MDR) recertification requirements are forcing molecular diagnostic manufacturers to generate expanded clinical evidence for existing in vitro diagnostic platforms. The regulatory burden disproportionately affects mid-sized European laboratories lacking dedicated regulatory affairs functions, consolidating market share toward larger manufacturers with established quality management systems. German and French notified bodies have extended review timelines by eight to fourteen months for novel biomarker assays.
Oncology clinics are unbundling surveillance testing from bundled payment contracts, creating direct purchasing relationships with specialized molecular laboratories. This channel disintermediation bypasses hospital central laboratory markups and enables price negotiation based on test volume commitments. The shift is most pronounced in the United States, where Medicare Advantage plans in Florida and Texas have introduced preferred laboratory networks with tiered reimbursement differentials.
Global Bladder Cancer Therapeutics and Diagnostics Market Segmentation
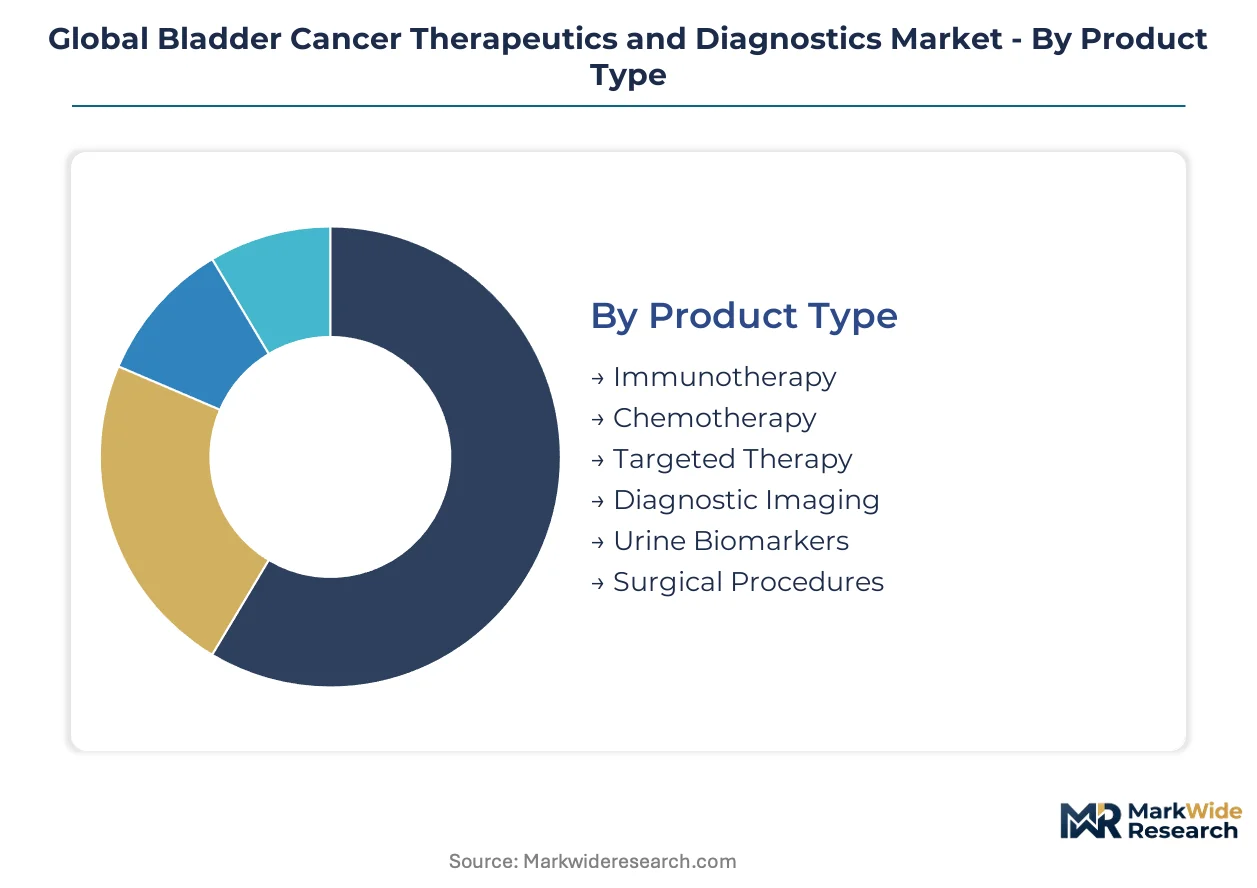
Segmentation in bladder cancer markets follows distinct procurement and reimbursement pathways. Product categories map to separate provider budgets, while therapy areas trigger different site-of-care requirements. Understanding these channel dynamics clarifies where commercial resources concentrate.
Product Type:
Channel mix varies sharply across product categories, with hospital outpatient departments dominating intravenous immunotherapy while ambulatory surgical centers capture diagnostic imaging and urine biomarker volumes.
- Immunotherapy:Checkpoint inhibitors and antibody-drug conjugates administered via infusion protocols. Oncology clinics in the United States and Germany command the largest prescription volumes, driven by PD-1/PD-L1 inhibitor reimbursement under Medicare Part B and German statutory health insurance.
- Chemotherapy:Platinum-based regimens including cisplatin and gemcitabine combinations. Hospital inpatient pharmacies in Japan and the United States maintain the dominant procurement channels, constrained by cold-chain logistics and cytotoxic handling requirements.
- Targeted Therapy:FGFR inhibitors and other molecularly directed agents. Academic medical centers with integrated molecular profiling laboratories concentrate demand, as therapy selection requires next-generation sequencing confirmation.
- Diagnostic Imaging:CT urography, MRI, and PET-CT protocols for staging and surveillance. Radiology departments in German university hospitals and Japanese cancer centers generate the highest scan volumes per capita.
- Urine Biomarkers:Non-invasive molecular assays for post-treatment monitoring. Reference laboratories in the United States and specialized pathology networks in the Netherlands are displacing hospital-based cystoscopy suites.
- Surgical Procedures:Transurethral resection of bladder tumor and radical cystectomy. Ambulatory surgical centers in Florida and Texas are capturing low-risk resection cases from academic medical center networks.
By volume, Chemotherapy leads due to broad first-line eligibility. By growth pace, Urine Biomarkers is climbing the fastest as surveillance protocols shift toward non-invasive alternatives.
Therapy Area:
Cost tiers stratify across disease stages, with metastatic therapy commanding premium pricing per patient while non-muscle invasive disease generates volume through repeat intervention cycles.
- Non-Muscle Invasive:Ta, T1, and carcinoma in situ lesions managed with transurethral resection and intravesical therapy. Community urology practices in the United States perform the majority of initial resections, with BCG induction concentrated in academic centers due to shortage allocation protocols.
- Muscle Invasive:T2-T4a disease requiring neoadjuvant chemotherapy and radical cystectomy. High-volume cystectomy centers in Germany, Japan, and the United States achieve superior perioperative outcomes and attract regional referral networks.
- Metastatic:Advanced disease with distant organ involvement. Comprehensive cancer centers with phase I trial portfolios dominate care delivery, as patients seek access to investigational antibody-drug conjugates.
- Recurrent:Disease relapse after complete response. Surveillance intensity varies by geography, with German statutory insurance mandating stricter follow-up protocols than United States commercial plans.
- Superficial:Low-grade papillary lesions with favorable prognosis. Ambulatory surgical centers capture resection volume due to same-day discharge eligibility.
- Carcinoma In Situ:High-grade flat lesions requiring intravesical BCG or alternative immunotherapy. Manufacturing bottlenecks have forced substitution with pembrolizumab in BCG-unresponsive cases.
Muscle Invasive commands the highest per-patient expenditure. Non-Muscle Invasive generates the greatest absolute procedure count.
End User:
Customer type determines contract structure, with integrated delivery networks negotiating enterprise pricing while independent laboratories compete on turnaround time and biomarker menu breadth.
- Oncology Clinics:Physician offices and infusion centers administering systemic therapy. United States-based community oncology practices are consolidating into platform networks to enhance payer contracting leverage.
- Diagnostic Laboratories:Central hospital labs and independent reference laboratories processing histopathology and molecular assays. European networks in the Netherlands and Sweden have deployed artificial intelligence-assisted cytology platforms.
- Ambulatory Surgical Centers:Freestanding facilities performing diagnostic cystoscopy and intravesical instillation. Medicare site-of-service differentials are accelerating volume migration from hospital outpatient departments in the United States.
- Cancer Research Institutes:Academic medical centers and dedicated oncology hospitals conducting clinical trials. Japan's National Cancer Center and Germany's DKTK network anchor early-phase development programs.
Diagnostic Laboratories handle the highest test throughput. Ambulatory Surgical Centers are expanding capacity most aggressively.
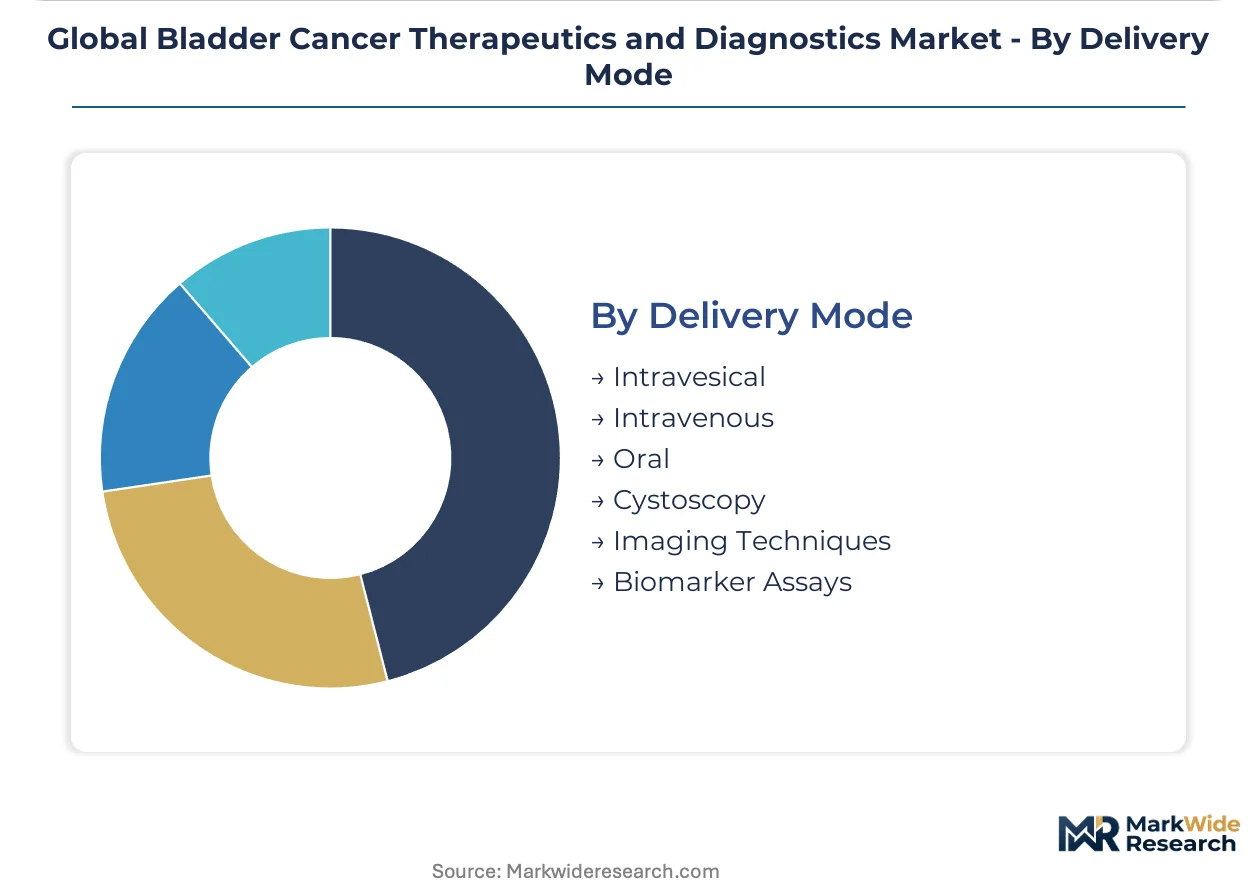
Delivery Mode:
Supply concentration shapes availability risk, with intravesical BCG dependent on single-source manufacturing while intravenous generics distribute through diversified wholesale networks.
- Intravesical:Direct bladder instillation of BCG or chemotherapy agents. Compounding pharmacies in the United States and hospital pharmacy preparation units in Germany manage the sterile preparation workflow.
- Intravenous:Systemic chemotherapy and immunotherapy infusion. Hospital outpatient departments in Japan and the United States require specialized cytotoxic handling infrastructure.
- Oral:Limited current availability, with FGFR inhibitors representing the primary oral option. Patient assistance programs in the United States manage access barriers for Medicare beneficiaries.
- Cystoscopy:Endoscopic visualization and tissue acquisition. Flexible cystoscope manufacturers supply ambulatory surgical centers through equipment leasing arrangements.
- Imaging Techniques:Radiologic staging and surveillance protocols. Radiology information systems in German university hospitals are integrating artificial intelligence-assisted lesion detection.
- Biomarker Assays:Laboratory-developed and FDA-cleared molecular tests. United States reference laboratories are unbundling surveillance testing from hospital central laboratory contracts.
Intravenous dominates current therapeutic delivery. Biomarker Assays are gaining share fastest in post-treatment surveillance protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology clinics and hospital systems in the United States, Germany, and Japan concentrate procurement authority for bladder cancer therapeutics and diagnostics. Academic medical centers in these markets anchor clinical trial recruitment and shape reimbursement precedents that cascade into adjacent geographies.
United States
Medicare site-of-service differentials accelerate volume migration toward ambulatory surgical centers in Florida and Texas. FDA breakthrough therapy designation compresses development timelines for novel checkpoint inhibitors. The MD Anderson Cancer Center in Houston anchors muscle-invasive disease referral networks across the Southwest.
Germany
German statutory health insurance mandates stricter post-treatment surveillance protocols than commercial plans in other markets. EMA conditional approval pathways enable early revenue recognition for antibody-drug conjugate developers. The DKTK network concentrates phase I trial portfolios in Heidelberg and Berlin.
Japan
PMDA sakigake framework accelerates domestic market entry for innovative diagnostics, incentivizing Tokyo-prioritized regulatory submissions. National Cancer Center hospitals anchor early-phase development programs. Osaka-based urology practices drive adoption of urine biomarker surveillance protocols.
United Kingdom
NICE technology appraisals shape reimbursement eligibility for molecular profiling platforms across NHS trusts. Genomic England's cancer program concentrates next-generation sequencing capacity in Cambridge and London. Manchester cancer centers expand clinical trial access for BCG-unresponsive carcinoma in situ.
Netherlands
Pathology networks deploy artificial intelligence-assisted cytology platforms for preliminary urothelial carcinoma detection. EMA Medical Device Regulation recertification consolidates market share toward larger manufacturers with established quality systems. Rotterdam laboratories pioneer decentralized interpretation workflows.
Global Bladder Cancer Therapeutics and Diagnostics Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with oncology franchises and specialized diagnostic manufacturers with companion testing platforms. Market structure concentrates among ten to fifteen entities controlling checkpoint inhibitor, antibody-drug conjugate, and molecular assay portfolios. Three archetypes dominate: integrated pharma-diagnostic conglomerates, pure-play immuno-oncology developers, and reference laboratory networks. Competitive moves center on companion diagnostic convergence bundles and ambulatory site contracting relationships.
Within the integrated conglomerate tier, Roche Holding AG and Pfizer Inc exemplify archetypes combining therapeutic manufacturing with diagnostic platform control. Bristol-Myers Squibb Company occupies a distinct position in checkpoint inhibitor development. These entities anchor procurement relationships across United States oncology clinics and European hospital networks, representing the scale-driven end of competitive positioning.
| Leading Market Players |
|---|
| Roche Holding AG |
| Pfizer Inc |
| Merck & Co Inc |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Bayer AG |
| Johnson & Johnson |
| GlaxoSmithKline PLC |
| Others |
Supply & Pricing Matrix
Urine biomarker substitution for repeat cystoscopy is redrawing procurement geography and compressing price premiums across ambulatory surgical centers in Florida and Texas. This shift from procedural reimbursement to laboratory fee schedules simultaneously fragments buyer concentration and intensifies cost scrutiny on molecular assay manufacturers.
Pricing Analysis
Cost-plus contracts with platinum-based chemotherapy indexation to Indian and Chinese API benchmarks dominate hospital procurement in Japan and Germany. Price differentiation rests on FDA breakthrough therapy designation tiering and companion diagnostic bundling with PD-1/PD-L1 inhibitors. Pricing pressure stems from Medicare site-of-service payment differentials favoring ambulatory settings. Community oncology practices exhibit highest price sensitivity; academic medical centers with trial portfolios demonstrate lowest.
Supply Chain Analysis
Single-source BCG manufacturing through Merck's Connaught strain facility creates a chokepoint affecting induction therapy allocation across United States academic centers. Active pharmaceutical ingredients for cisplatin and gemcitabine concentrate in India and China, with cold-chain logistics resting on specialized cytotoxic handling infrastructure. Single-source vulnerability in BCG production exposes supply to regulatory inspection disruption. Distribution runs through hospital pharmacy compounding units and oncology clinic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as interoperability standards for molecular profiling results force consolidation among electronic health record vendors and diagnostic laboratories. The FHIR-enabled data exchange ecosystem in United States oncology networks exemplifies this shift.
For Market Incumbents: Fortify companion diagnostic convergence bundles by anchoring next-generation sequencing panels to pembrolizumab prescribing workflows. Deepen vertical integration into urine biomarker assay manufacturing to offset reference laboratory disintermediation. Secure ambulatory surgical center contracting relationships before Medicare site-of-service differentials fully mature.
For New Entrants and Emerging Players: Differentiate on artificial intelligence-assisted cytology platforms targeting European pathology network procurement in the Netherlands and Sweden. Penetrate BCG-unresponsive carcinoma in situ segments where manufacturing shortages have forced therapeutic substitution. Pursue direct-to-oncology-clinic laboratory service models bypassing hospital central laboratory markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed reference laboratory networks holding Medicare Advantage preferred provider status. Five-to-ten year viability hinges on reimbursement durability for liquid biopsy surveillance protocols. Monitor FDA breakthrough therapy designation grants to antibody-drug conjugate developers as inflection signals for platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Convergence | Integrates Roche's sequencing platforms with checkpoint inhibitor prescribing across German oncology networks. |
| Ambulatory Site Expansion | Captures Medicare payment differentials through Florida and Texas freestanding surgical center deployment. |
| EMA Conditional Approval Pathway | Enables revenue recognition for antibody-drug conjugates prior to confirmatory trial completion. |
| Artificial Intelligence Cytology Deployment | Reduces pathologist review burden through Netherlands and Sweden laboratory network implementation. |
| Urine Biomarker Surveillance Unbundling | Bypasses hospital central laboratory markups via direct oncology clinic contracting relationships. |
Research Methodology
Operator-level perspectives from oncology clinic administrators, hospital procurement managers, formulary directors, and pathology laboratory directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA CHMP opinions, ClinicalTrials.gov protocols, and CMS Medicare claims data. Bottom-up test volume modeling and top-down pharmaceutical revenue triangulation converged on segment estimates.
Sensitivity analysis examined biomarker assay adoption curves and immunotherapy penetration rates across the projection horizon. Segmentation dimensions included product type, therapy area, end user archetype, and delivery mode, with regional regulatory clusters as an overlay. CAGRs derived from logistic diffusion modeling of urine biomarker substitution rates and platinum-based chemotherapy volume trends.
Decision-makers should treat outputs as directional under stable reimbursement and regulatory approval assumptions; material deviation would warrant model refresh. Forecasts assume continued BCG shortage conditions and EMA MDR recertification timelines. Practitioners should keep alternative scenarios live as FDA breakthrough therapy designation patterns and Medicare site-of-service policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market