
 South Korea in Vitro Diagnostics Market | 2026-2036
South Korea in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea in Vitro Diagnostics Market Analytics
Software-defined assay protocols and cloud-connected instrument maintenance is decoupling instrument hardware from recurring revenue streams in the South Korea in vitro diagnostics sector. Roche Diagnostics leverages its installed base of cobas platforms to sustain long-term service contracts across Seoul's tertiary hospitals. Abbott Laboratories anchors its competitive position through vertically integrated immunoassay manufacturing. Sysmex Corporation dominates hematology automation with dedicated technical service teams embedded at major laboratory customers.
In vitro diagnostics encompasses clinical testing performed on blood, tissue, or other biological specimens outside the living organism, typically requiring reagent-based biochemical reactions with sensitivity thresholds measured in picograms per milliliter. These systems enable disease screening, therapeutic monitoring, and infection detection for hospital and laboratory decision-making. Reagents capture the largest margin pool given their recurring purchase cycles tied to instrument placements. Molecular diagnostics represents the fastest-expanding technology segment as Korean hospitals adopt PCR and next-generation sequencing platforms for oncology and infectious disease applications. Instruments remain concentrated among a handful of vendors due to high capital requirements and MFDS certification barriers.
The Ministry of Food and Drug Safety (MFDS) governs IVD registration through risk-based classification pathways that extend approval timelines for novel molecular assays. The Korean Ministry of Health and Welfare shapes reimbursement rates under the National Health Insurance Service, directly influencing hospital procurement priorities for high-cost diagnostic platforms. The Korean Agency for Technology and Standards (KATS) administers quality management system certifications that manufacturers must maintain for market access. Stakeholders must track how MFDS digital health integration guidelines and NHIS reimbursement band adjustments reshape the economic viability of automated versus manual testing modalities.
Market Dynamics
Automated testing line expansion across Seoul's metropolitan hospital network is compressing turnaround times while fragmenting procurement authority between laboratory directors and centralized supply chains.
Growth Catalysts
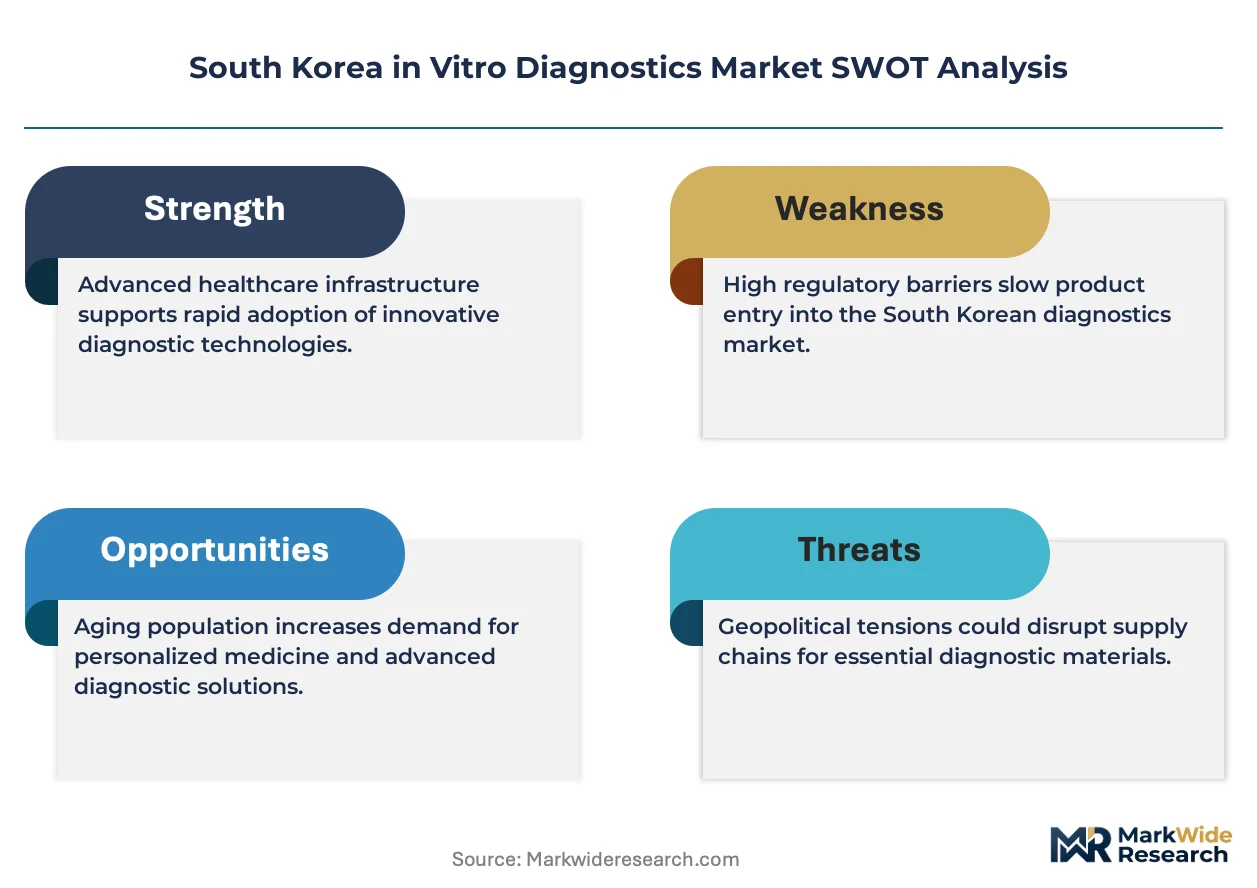
- MFDS Risk-Based Classification:Tightened premarket review pathways for novel molecular assays are accelerating quality benchmarks across domestic manufacturers.
- Seoul Tertiary Hospital Concentration:High-complexity reference testing demand clusters in the capital region, creating density economies for platform vendors.
- PCR and NGS Platform Adoption:Oncology and infectious disease applications are pulling capital investment into molecular diagnostics infrastructure.
Market Restraints
- Reagent Margin Concentration:Recurring purchase cycles tied to instrument placements lock laboratories into single-vendor ecosystems.
- Capital Requirements:High instrument costs and MFDS certification barriers prevent mid-tier domestic manufacturers from scaling production.
- Technical Service Embedding:Dedicated technical teams at major customers create switching costs that freeze competitive entry.
Strategic Opportunities
- Cloud-Connected Maintenance:Software-defined assay protocols are decoupling hardware from service revenue streams.
- Beyond-Seoul Laboratory Networks:Regional hospital systems outside the capital corridor remain underpenetrated for automated hematology lines.
- NHIS Reimbursement Band Adjustments:National Health Insurance Service rate revisions for automated versus manual testing modalities create procurement timing windows.
Industry Challenges
- Molecular Assay Validation Timelines:MFDS approval pathways for novel diagnostics extend commercialization cycles beyond capital recovery horizons.
- Platform Integration Complexity:Legacy cobas and Sysmex installations resist interoperability with cloud-native protocol management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea in Vitro Diagnostics Market |
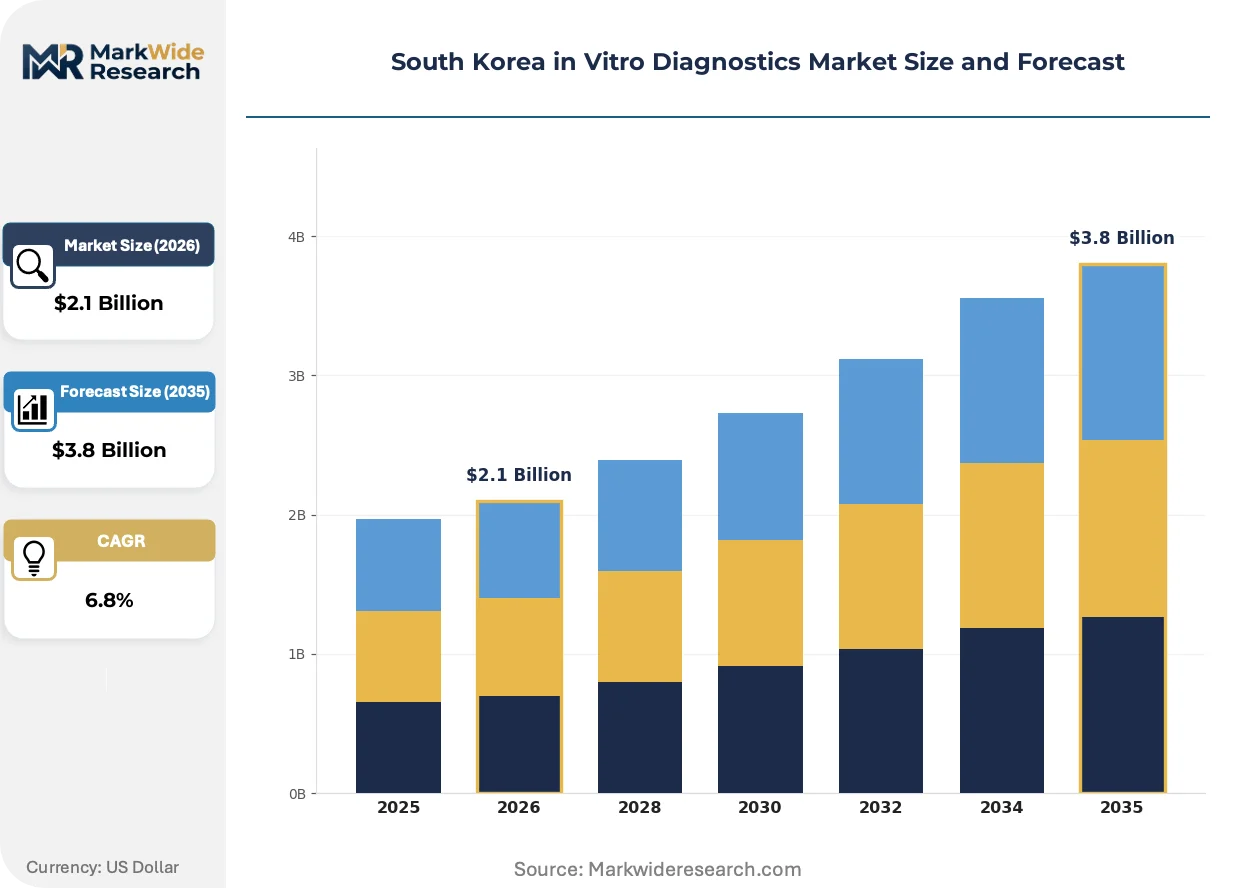
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables End User: Hospitals, Laboratories, Clinics, Research Centers Technology: Molecular Diagnostics, Immunoassays, Microbiology, Hematology Application: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiovascular Diseases |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific, Becton Dickinson, Bio-Rad Laboratories, Sysmex Corporation, SD Biosensor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea in Vitro Diagnostics Market Evolving Landscape
Digital health integration guidelines from Korean regulators are rewriting how diagnostic platforms connect to hospital information systems and external quality networks.
Software-defined assay protocols are unifying instrument control, reagent tracking, and result reporting into single cloud-native layers. Seoul's tertiary hospitals are adopting these systems fastest, consolidating previously fragmented laboratory information management. This convergence is unifying maintenance contracts and consumable procurement under single-vendor digital ecosystems.
MFDS digital health integration guidelines now mandate interoperability standards for connected diagnostic devices. The regulation forces manufacturers to open application programming interfaces for hospital system integration. Molecular diagnostics vendors face the steepest compliance burden as real-time data transmission becomes a certification requirement.
After-sales service unbundling is separating hardware warranties from reagent supply agreements and technical support contracts. Laboratory procurement teams in the National Health Insurance Service network are negotiating these elements independently, compressing vendor margins on standalone maintenance. This pattern is most visible in Seoul's metropolitan hospital network where purchasing authority has shifted from clinical departments to centralized supply chain functions.
South Korea in Vitro Diagnostics Market Segmentation
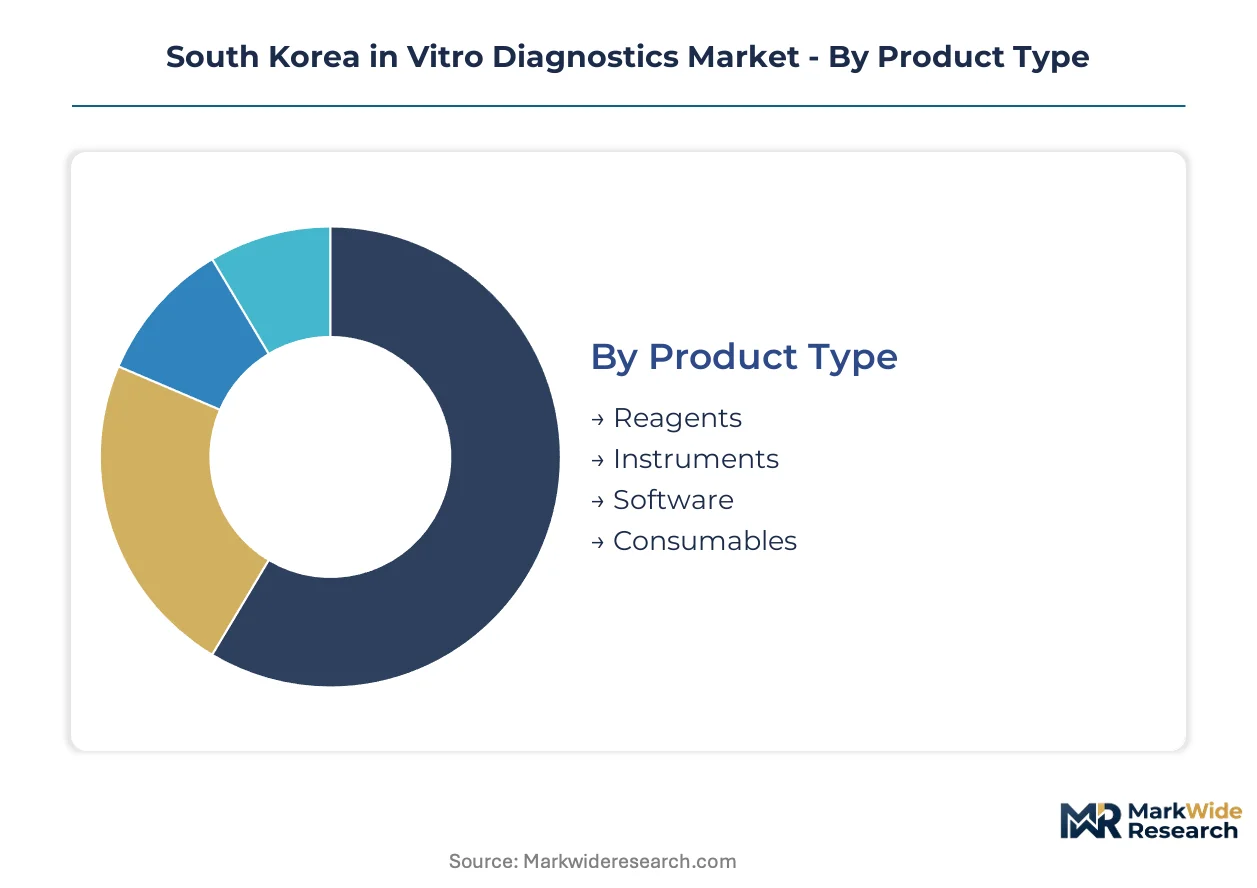
IVD market segmentation in South Korea reflects divergent procurement behaviors between capital-intensive tertiary hospitals and cost-sensitive regional clinics. Understanding these buyer profiles enables vendors to align platform configurations with reimbursement constraints under the National Health Insurance Service.
Product Type:
Reagent contracts lock laboratories into multi-year purchasing commitments that outlast instrument depreciation cycles.
- Reagents:Biochemical and immunological reaction media with picogram-per-milliliter sensitivity thresholds. Seoul's metropolitan hospital network concentrates demand for high-volume reagent contracts tied to automated cobas and Sysmex platforms. Recurring purchase cycles generate the largest margin pool and create substantial vendor lock-in effects.
- Instruments:Analytical hardware platforms requiring MFDS certification and substantial capital deployment. Regional hospital systems outside the capital corridor face procurement barriers due to high upfront costs and extended MFDS approval timelines for novel molecular configurations.
- Software:Laboratory information management and assay protocol control systems. MFDS digital health integration guidelines mandate interoperability standards that reshape competitive positioning for cloud-native vendors.
- Consumables:Disposable pipettes, reaction vessels, and specimen collection devices. Procurement concentrates through centralized supply chain functions at National Health Insurance Service network hospitals.
Reagents lead volumes today; software is gaining share fastest as cloud-connected maintenance decouples hardware from service revenue.
End User:
Testing complexity and reimbursement band eligibility fragment procurement authority across South Korea's healthcare delivery system.
- Hospitals:High-throughput tertiary facilities performing complex reference testing. Seoul's metropolitan hospital network anchors demand for automated testing lines handling rising patient volumes.
- Laboratories:Dedicated diagnostic facilities serving multiple clinical sites. Independent laboratories in the capital region exploit density economies to negotiate consolidated reagent contracts.
- Clinics:Primary care facilities with limited on-site testing capacity. Point-of-care molecular diagnostics adoption remains constrained by NHIS reimbursement band restrictions.
- Research Centers:Academic and pharmaceutical research institutions. Next-generation sequencing platform procurement concentrates at Seoul-based oncology research institutes.
Hospitals dominate absolute spending; research centers are climbing the fastest as precision medicine initiatives expand.
Technology:
Detection methodology determines capital requirements, regulatory pathway complexity, and technical service embedding intensity.
- Molecular Diagnostics:PCR and next-generation sequencing platforms for nucleic acid detection. Oncology and infectious disease applications at Korean tertiary hospitals are pulling capital investment despite extended MFDS validation timelines for novel assays.
- Immunoassays:Antibody-antigen binding reactions for protein and hormone quantification. Vertically integrated manufacturing capabilities anchor competitive positioning for multinational vendors serving Seoul's hospital network.
- Microbiology:Culture-based and rapid pathogen identification systems. Demand concentrates at infectious disease reference laboratories within the National Health Insurance Service network.
- Hematology:Automated cell counting and morphology analysis. Dedicated technical service teams embedded at major laboratory customers create switching costs that freeze competitive entry.
Immunoassays anchor current revenue; molecular diagnostics shows the steepest expansion trajectory as PCR and NGS platform adoption accelerates.
Application:
Disease prevalence patterns and screening program mandates shape test volume distribution across South Korea's diagnostic infrastructure.
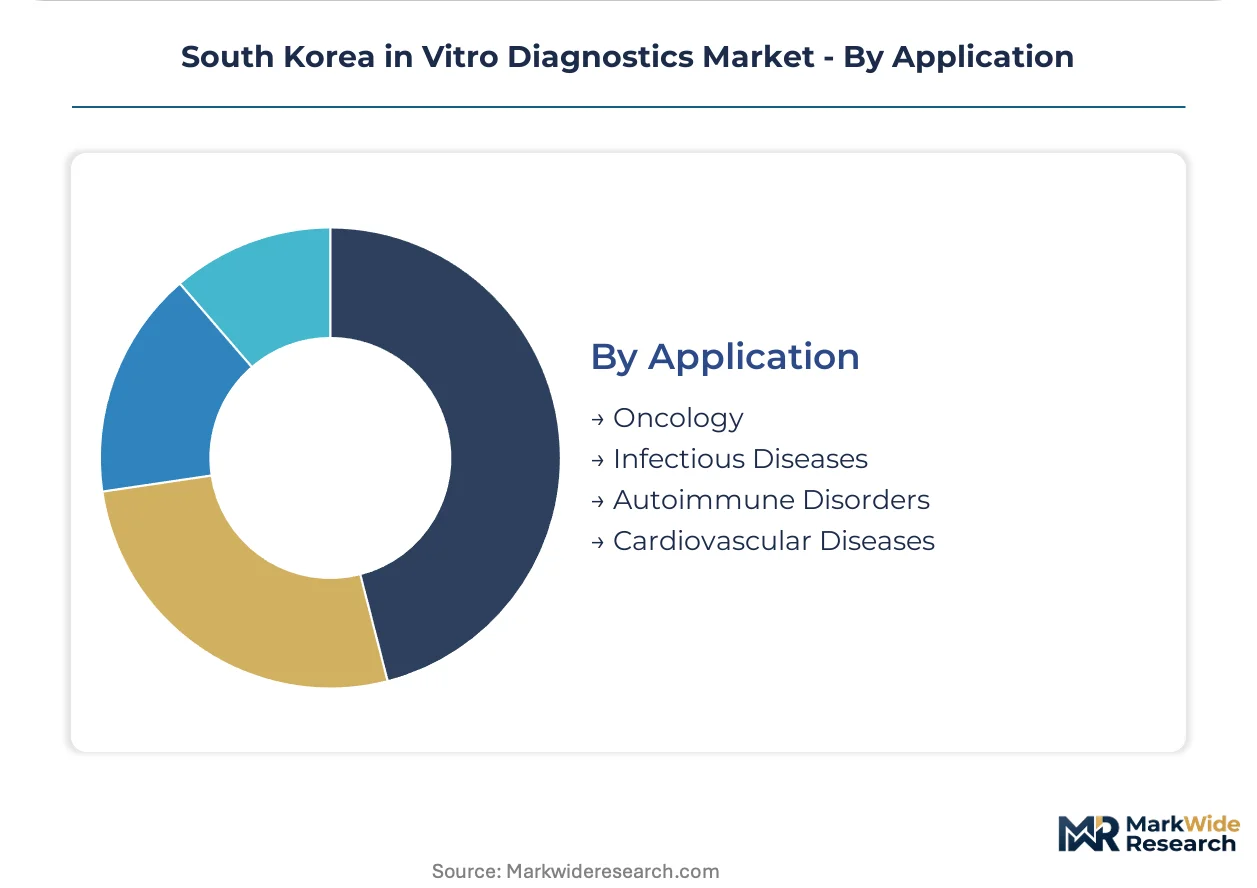
- Oncology:Biomarker detection and minimal residual disease monitoring. Liquid biopsy applications at Seoul's tertiary hospitals are driving next-generation sequencing platform procurement despite high capital requirements.
- Infectious Diseases:Pathogen detection and antimicrobial resistance profiling. MFDS tightened premarket review pathways for novel molecular assays targeting emerging infectious threats.
- Autoimmune Disorders:Autoantibody panels and inflammatory marker quantification. Testing volumes concentrate at rheumatology specialty clinics within the National Health Insurance Service reimbursement framework.
- Cardiovascular Diseases:Cardiac troponin and lipid panel analysis. High-throughput automated lines at metropolitan hospitals compress turnaround times for emergency department decision-making.
Infectious diseases command the largest test volumes today; oncology is expanding most quickly as precision medicine programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's diagnostic infrastructure outpaces regional peers in automation density, while Japan maintains tighter regulatory control over novel molecular assay approvals. Both markets concentrate procurement authority in metropolitan hospital networks, though reimbursement frameworks diverge significantly.
Seoul Capital Area
High-complexity reference testing demand clusters in Seoul's tertiary hospital network, driving automated testing line expansion. The Ministry of Food and Drug Safety governs IVD registration through risk-based classification pathways that extend approval timelines. Seoul National University Hospital and Samsung Medical Center anchor procurement for Roche cobas and Sysmex hematology platforms.
Busan-Ulsan
Port-city logistics infrastructure supports reagent distribution to regional hospital systems facing capital constraints. MFDS certification requirements for novel molecular configurations limit mid-tier domestic manufacturer participation. Ulsan University Hospital concentrates infectious disease reference testing for the southeastern coastal corridor.
Daegu-Gyeongbuk
Textile and manufacturing heritage has diversified into biomedical device component supply chains. The Korean Agency for Technology and Standards administers quality management system certifications for regional producers. Kyungpook National University Hospital anchors oncology diagnostics demand in this northeastern manufacturing belt.
Daejeon-Sejong
Government research institutes drive next-generation sequencing platform adoption for precision medicine initiatives. National Health Insurance Service reimbursement band adjustments directly influence procurement timing for automated versus manual testing. Korea University Guro Hospital exemplifies the capital-region migration of high-complexity testing demand.
Gwangju-Honam
Regional hospital systems remain underpenetrated for automated hematology lines compared to Seoul metropolitan benchmarks. MFDS digital health integration guidelines mandate interoperability standards that reshape competitive positioning for cloud-native vendors. Chonnam National University Hospital serves as the southwestern hub for reference testing referrals.
South Korea in Vitro Diagnostics Market Competitive Landscape
Top-tier vendors anchor Seoul's tertiary hospital network through installed base expansion, while mid-tier domestic manufacturers struggle against MFDS certification barriers and capital requirements. The market structure concentrates instrument placements among a handful of multinational platforms, with reagent contracts generating recurring revenue streams that outlast hardware depreciation. Three strategic archetypes dominate: vertically integrated immunoassay manufacturers, hematology automation specialists with embedded technical service teams, and molecular diagnostics vendors navigating extended validation timelines. Competitive moves center on software-defined assay protocols that decouple hardware from service revenue, alongside cloud-connected maintenance contracts that unify previously fragmented procurement elements.
Among Switzerland-based diagnostic conglomerates, Roche Diagnostics occupies a position exemplifying platform ecosystem lock-in through long-term service contracts. Abbott Laboratories, an American corporation, represents vertically integrated manufacturing capabilities that anchor competitive positioning in immunoassay segments. Sysmex Corporation, a Japanese entity, exemplifies the hematology automation archetype through dedicated technical service embedding at major laboratory customers. These three companies illustrate how geographic origin and organizational structure correlate with divergent strategic approaches to the South Korean market's regulatory and reimbursement complexities.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Bio-Rad Laboratories |
| Sysmex Corporation |
| SD Biosensor |
| Others |
Value Network & Pricing Analysis
Biomedical engineering talent clusters in Seoul's Gangnam and Songdo districts compress salary differentials between premium instrument manufacturers and mid-tier reagent suppliers, narrowing pricing-tier spreads for automated testing platforms versus manual alternatives.
Pricing Analysis
Capacity additions in Gyeonggi Province are reshaping price floors for consumable reagents as domestic manufacturers scale polymerase chain reaction kit production. Pricing stratifies across premium, standard, and economy tiers based on MFDS certification grade and after-sales service bundling. Price differentiation hinges on cloud-connected maintenance contracts versus standalone hardware warranties. Regional hospital systems outside Seoul exhibit highest price sensitivity due to NHIS reimbursement band constraints, while tertiary hospitals in the capital prioritize turnaround time over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese optical component suppliers for hematology automation systems. The supply chain draws from South Korea for electronic subassemblies, the United States for molecular diagnostic enzymes, and China for plastic consumables. Tariff exposure on precision optical parts creates procurement timing risk for platform vendors. Distribution runs through centralized supply chain functions at National Health Insurance Service network hospitals, consolidating reagent procurement authority away from individual laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's IVD market functions as a geographic-arbitrage play where MFDS regulatory stringency exceeds ASEAN neighbors but trails Japan's PMDA timelines, creating a mid-tier compliance cost zone attractive to multinational platform vendors.
For Market Incumbents: Acquire cloud-native assay protocol management capabilities to defend against software-defined diagnostic entrants threatening hardware-revenue decoupling. Lock in multi-year reagent supply agreements with Seoul's tertiary hospital network before NHIS reimbursement band adjustments favor manual testing modalities. Priority rests on embedding technical service teams at regional hospital systems outside the capital corridor.
For New Entrants and Emerging Players: MFDS digital health integration guidelines open a window for interoperability-first molecular diagnostics vendors to penetrate Busan-Ulsan regional hospital systems underserved by embedded incumbent service teams. Target point-of-care infectious disease testing at primary care clinics constrained by current NHIS reimbursement restrictions. Lead with subscription-based reagent pricing to circumvent capital barrier objections from mid-tier laboratories.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic consumables manufacturers lacking backward integration into instrument platforms. Long-term viability over the next decade hinges on regulatory navigation capabilities and cloud-connected maintenance revenue streams. Watch for MFDS approval timeline compression for novel oncology assays as the inflection signal for molecular diagnostics platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Certification Investment | Accelerates market entry timelines for novel molecular assay vendors competing against entrenched incumbents. |
| Cloud-Native Protocol Development | Decouples hardware revenue from recurring service contracts at Seoul's tertiary hospital network. |
| Regional Hospital System Partnership | Captures underpenetrated demand for automated hematology lines in Gwangju-Honam corridors. |
| Reimbursement Strategy Alignment | Positions platforms for NHIS rate adjustments favoring automated versus manual testing modalities. |
| Technical Service Team Embedding | Creates switching costs that freeze competitive entry from mid-tier domestic manufacturers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, biomedical engineers, GPO contracts managers, and MFDS regulatory affairs specialists with secondary validation from hospital procurement databases, GPO contract filings, and MFDS registration records. Bottom-up instrument placement tracking and top-down reagent consumption estimates were triangulated against NHIS reimbursement data.
Historical reference periods anchored the projection horizon through trend extrapolation and scenario-weighted probability assessments. Segmentation dimensions modeled include product type, end-user facility tier, technology platform, and application area alongside regional adoption patterns across South Korea's five major hospital networks. CAGRs were derived from instrument replacement cycles, reagent consumption trajectories, and molecular diagnostics platform penetration curves.
Revisions become necessary when MFDS regulatory pathway modifications, NHIS reimbursement band restructuring, or cloud-native diagnostic platform disruptions materialize. Forecasts reflect documented assumptions about instrument interoperability standards and regional hospital capital allocation priorities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Glucose Biosensors Market
Diagnostics
Viral Antigens Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Middle East and Africa Thyroid Cancer Diagnostics Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Global Chromoendoscopy Agents Market
Diagnostics
Respiratory Pathogen Testing Kits Market
Diagnostics
Europe Womens Health Diagnostics Market
Diagnostics
Singleplex Immunoassay Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market