
 Europe Antinuclear Antibody Test Market | 2026-2036
Europe Antinuclear Antibody Test Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Antinuclear Antibody Test Market Analytics
The Europe antinuclear antibody test market is consolidating around a widening split between premium immunofluorescence systems and commoditized rapid assay kits. EUROIMMUN Medizinische Labordiagnostika AG leverages its dominance in automated immunofluorescence platforms to anchor high-margin contracts with university hospital networks. Thermo Fisher Scientific Inc. competes through extensive R&D intensity in multiplex ELISA development. Trinity Biotech Ireland specializes in niche Western blot confirmatory panels that sustain pricing power amid reimbursement pressure.
An antinuclear antibody test detects autoantibodies directed against cellular nuclear components, typically employing indirect immunofluorescence on HEp-2 cell substrates with titer reporting or solid-phase immunoassay formats for quantitative screening. The primary commercial purpose is diagnosing systemic autoimmune disorders, particularly systemic lupus erythematosus and mixed connective tissue disease, while supporting rheumatology treatment monitoring. Immunofluorescence remains the clinical gold standard segment where margin pools concentrate due to skilled technician requirements and subjective pattern interpretation. Point-of-care testing represents the fastest-growing delivery mode as decentralized rheumatology clinics seek same-day screening capability. Hospitals constitute the most mature end-user channel with established laboratory infrastructure and long-term vendor relationships.
The European Medicines Agency (EMA) and EU In Vitro Diagnostic Regulation (IVDR) frameworks are elevating clinical evidence requirements for ANA test kits, forcing manufacturers to invest in expanded performance studies for CE marking renewal. REACH compliance additionally governs chemical reagent components, influencing supplier selection and production location decisions within the European Economic Area. Stakeholders must monitor IVDR transition timelines and national reimbursement recalibrations to anticipate which product tiers will retain market access.
Market Dynamics
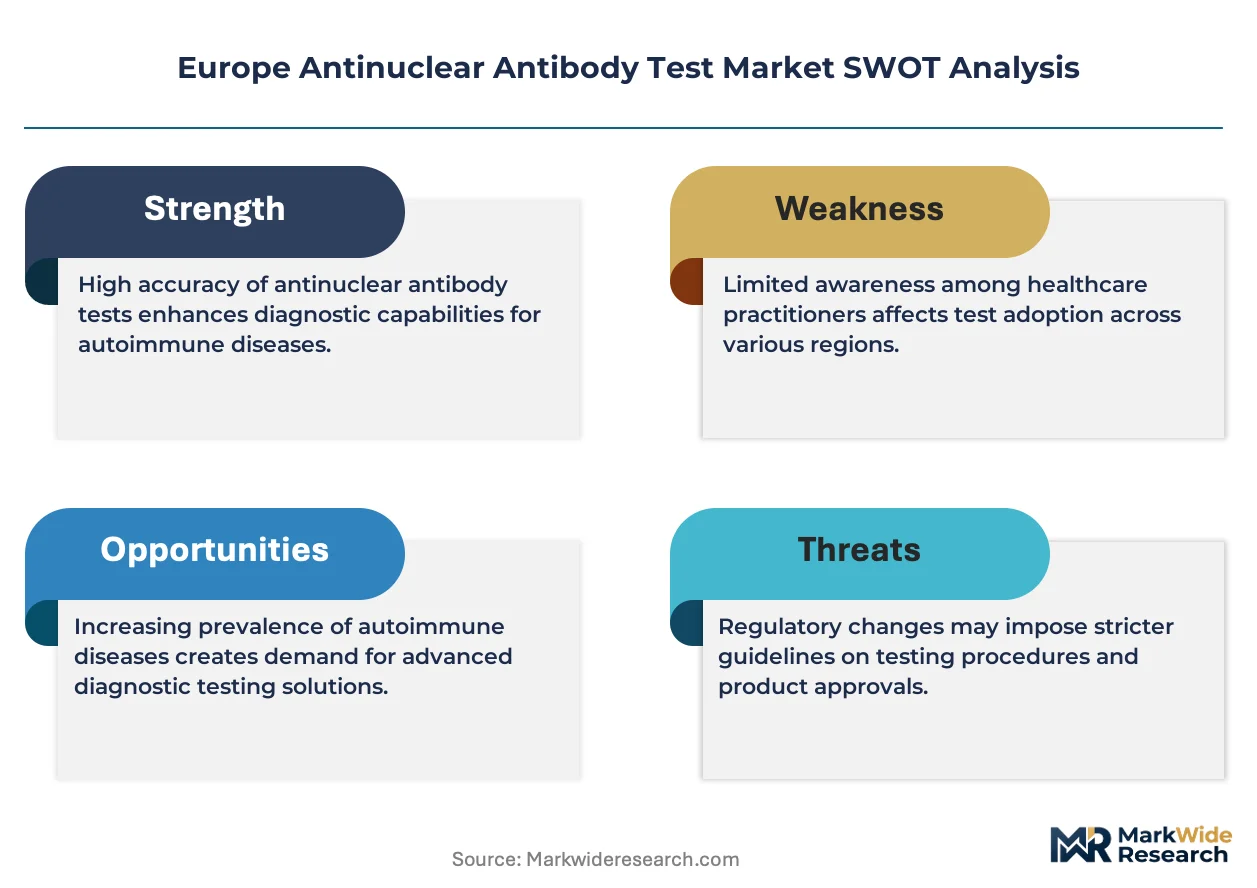
EU In Vitro Diagnostic Regulation (IVDR) compliance deadlines are compressing product registration timelines and forcing manufacturers to restructure clinical evidence portfolios for ANA test kits across European Economic Area markets.
Growth Catalysts
- Automated Immunofluorescence Platforms:Diagnostic laboratories in Germany and France are installing high-throughput screening systems to reduce technician labor intensity and standardize pattern interpretation.
- REACH Chemical Compliance:Reagent suppliers achieving full substance registration are securing preferred vendor status with major hospital networks seeking supply chain stability.
- Digital Pathology Integration:Western European university hospitals are connecting ANA workstations to enterprise imaging systems for remote consultation and AI-assisted pattern classification.
Market Restraints
- Skilled Technician Scarcity:Indirect immunofluorescence requires trained personnel for HEp-2 cell substrate preparation and subjective pattern recognition, limiting expansion in peripheral laboratories.
- Reagent Import Concentration:Fluorochrome-conjugated secondary antibodies and specialized HEp-2 cell substrates concentrate sourcing from a limited supplier base in Germany and the United States.
- IVDR Transition Costs:Performance study requirements for CE marking renewal under the 2017/746 regulation are elevating compliance expenditures for legacy product portfolios.
Strategic Opportunities
- Point-of-Care Decentralization:Rheumatology clinics in Spain and Italy are adopting rapid assay formats for same-day screening, bypassing centralized laboratory queues.
- Multiplex ELISA Expansion:Solid-phase immunoassay technology convergence with automated liquid handling is enabling antibody specificity profiling in medium-volume settings.
- EU Green Deal Alignment:Reagent manufacturers developing reduced-hazard preservative formulations can access sustainability-weighted procurement frameworks in Scandinavian hospital systems.
Industry Challenges
- Pattern Standardization Delays:Subjective immunofluorescence interpretation creates inter-laboratory variability that complicates multi-site clinical trial data pooling for IVDR technical documentation.
- Legacy System Integration:Digital pathology connectivity requires middleware development to bridge proprietary instrument data formats with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Antinuclear Antibody Test Market |
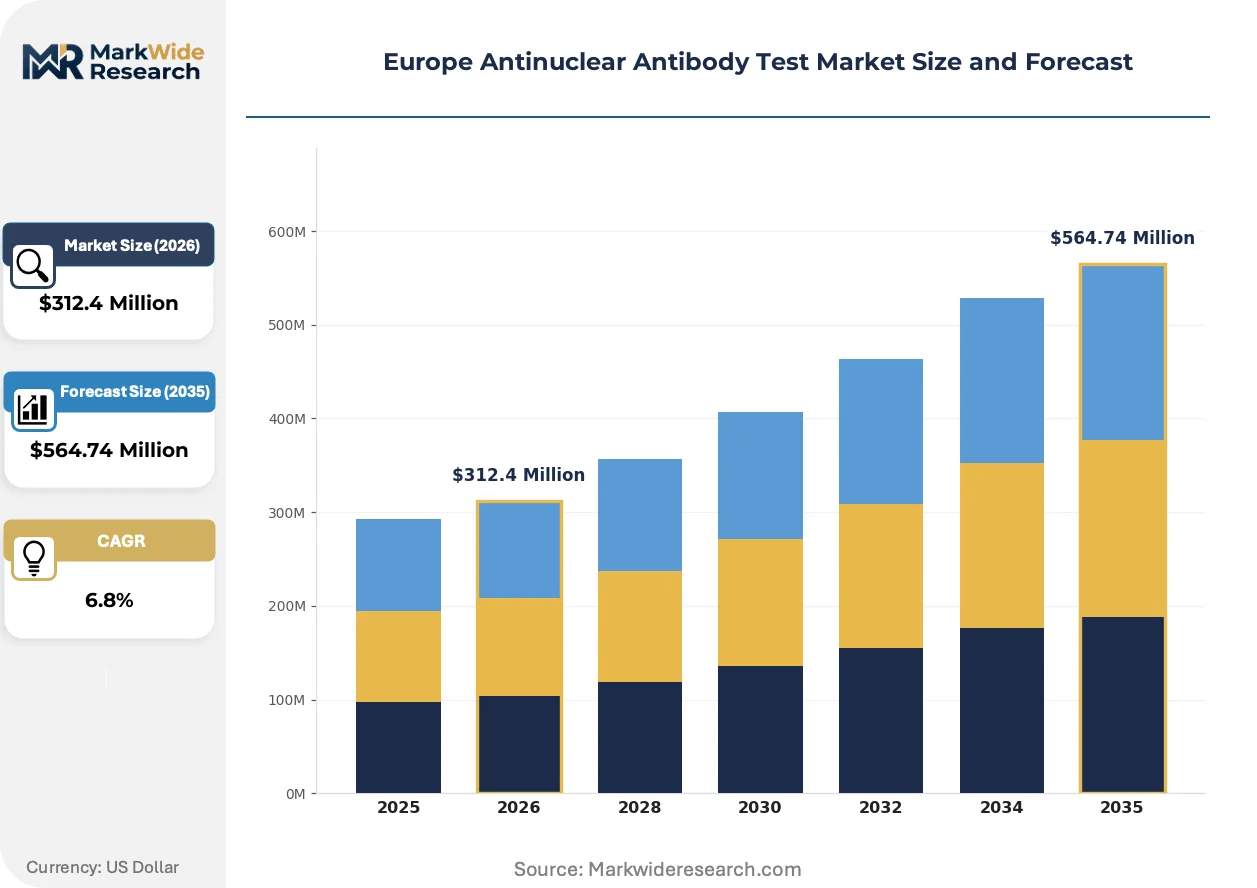
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Immunofluorescence, Western Blot, Rapid Test End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Delivery Mode: Lab-based Testing, Point-of-Care Testing, At-home Testing, Telemedicine Application: Autoimmune Disorders, Infectious Diseases, Rheumatology, Chronic Fatigue Syndrome |
| Companies Covered | Thermo Fisher Scientific Inc., Trinity Biotech Ireland, EUROIMMUN Medizinische Labordiagnostika AG, Bio-Rad Laboratories, Inc., Grifols S.A., Erba Diagnostics, Inova Diagnostics, Inc., ZEUS Scientific, Inc., Immuno Concepts, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Antinuclear Antibody Test Market Evolving Landscape
Artificial intelligence pattern recognition algorithms are penetrating immunofluorescence interpretation workflows, compressing the traditional reliance on experienced morphologists for ANA screening across European diagnostic networks.
Digital immunofluorescence imaging is modularizing laboratory infrastructure by separating image acquisition hardware from analysis software licenses. Medium-sized diagnostic laboratories in the Netherlands and Belgium are adopting camera-agnostic platforms that permit hardware upgrades without vendor lock-in. This modularity is fragmenting the traditional integrated-system procurement model and enabling third-party algorithm developers to enter pattern classification services.
EU IVDR Article 56 clinical evidence requirements are elevating post-market surveillance obligations for ANA test kit manufacturers. Performance study protocols must now demonstrate diagnostic sensitivity and specificity across defined autoimmune disease populations, not just healthy controls. Manufacturers serving French and German hospital networks are restructuring quality management systems to accommodate notified body scrutiny of real-world performance data.
Consolidated procurement by regional hospital groups is compressing vendor negotiation cycles and unbundling service contracts from instrument placements. Purchasing consortia in the United Kingdom National Health Service are separating reagent supply agreements from maintenance provisions, forcing manufacturers to compete on consumable pricing transparency rather than capital equipment subsidies. This disintermediation is most visible in England's Academic Health Science Networks.
Europe Antinuclear Antibody Test Market Segmentation
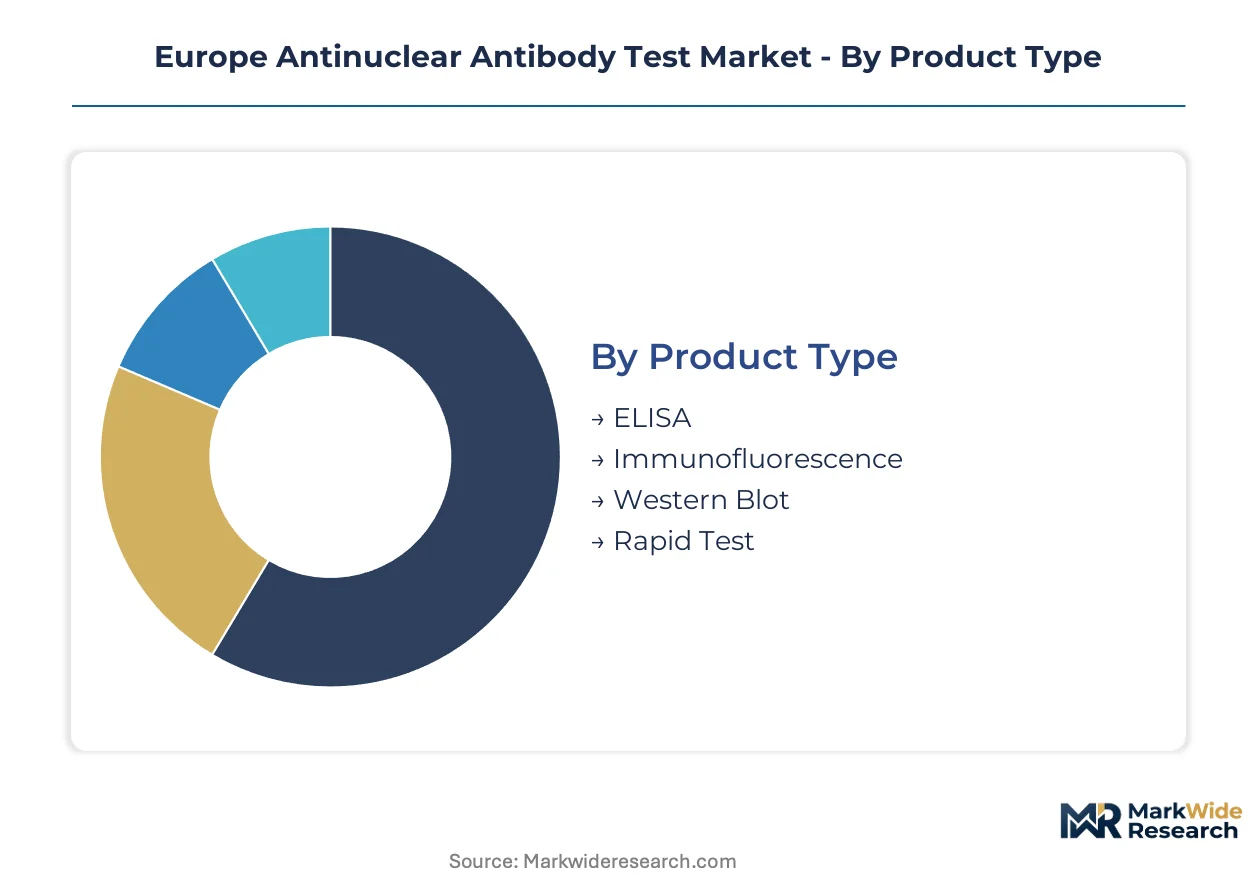
Segmentation in the Europe antinuclear antibody test market reveals how capital deployment, regulatory exposure, and reimbursement pathways concentrate value capture across distinct technology tiers and delivery settings. Understanding these divides clarifies where margin pools form versus where volume commoditization accelerates.
Product Type:
Capital-intensity varies sharply across assay formats, with automated immunofluorescence platforms demanding the heaviest upfront investment in imaging hardware and skilled technician training.
- Immunofluorescence:Indirect immunofluorescence on HEp-2 cell substrates remains the clinical gold standard, requiring fluorescence microscopes, specialized slide processors, and trained morphologists for pattern interpretation. German university hospital networks anchor demand here, driven by EMA diagnostic guidelines mandating titer-based reporting for systemic lupus erythematosus confirmation. The IVDR's elevated clinical evidence requirements reinforce this segment's insulation from rapid assay displacement.
- ELISA:Enzyme-linked immunosorbent assays offer quantitative antibody specificity profiling through solid-phase immunoassay technology, with lower capital barriers than immunofluorescence but higher per-test reagent costs. French diagnostic laboratories are expanding automated ELISA lines for medium-volume autoimmune screening, balancing throughput against the pattern detail that immunofluorescence provides.
- Western Blot:Confirmatory panels for antibody specificity identification, positioned downstream of positive screening results in rheumatology workflows.
- Rapid Test:Lateral flow and similar formats for decentralized screening, gaining traction in Italian and Spanish rheumatology clinics seeking same-day results.
Most installed capacity flows through Immunofluorescence. Expansion is steepest in Rapid Test formats.
End User:
Customer type determines procurement sophistication, with hospital networks leveraging consolidated purchasing power against fragmented diagnostic laboratory negotiation positions.
- Hospitals:Integrated health systems with established laboratory infrastructure, long-term vendor relationships, and enterprise imaging system connectivity requirements. United Kingdom National Health Service trusts are unbundling service contracts from instrument placements, forcing reagent pricing transparency.
- Diagnostic Laboratories:Independent and hospital-affiliated testing facilities processing high ANA volumes, concentrated in Germany and France where regional laboratory consolidation is compressing vendor margins.
- Research Institutes:Academic and translational research settings driving assay development and biomarker discovery, with procurement timelines tied to grant funding cycles.
- Home Care:Patient-directed testing emerging through telemedicine-integrated sampling models, constrained by IVDR self-test classification requirements and limited rheumatology reimbursement for unsupervised screening.
Procurement concentration is tightest in Hospitals. Research Institutes show the most variable demand timing.
Delivery Mode:
Physical distribution of testing capability shapes competitive dynamics, with centralized laboratory infrastructure competing against decentralized point-of-care deployment.
- Lab-based Testing:Centralized processing in hospital and independent laboratories, capturing the majority of autoimmune disorder diagnostic volume through standardized workflows and quality-controlled environments. Netherlands and Belgian laboratories are adopting camera-agnostic imaging platforms to modularize infrastructure.
- Point-of-Care Testing:Clinic-based rapid screening bypassing centralized queues, expanding fastest in Spain and Italy where rheumatology practices seek patient throughput advantages.
- At-home Testing:Self-sampling with remote laboratory processing, emerging through digital health platforms but limited by IVDR performance documentation requirements for lay-user devices.
- Telemedicine:Virtual consultation-integrated testing pathways, combining remote physician assessment with distributed sample collection and centralized analysis.
Volume concentration sits with Lab-based Testing. Regulatory complexity is highest for At-home Testing.
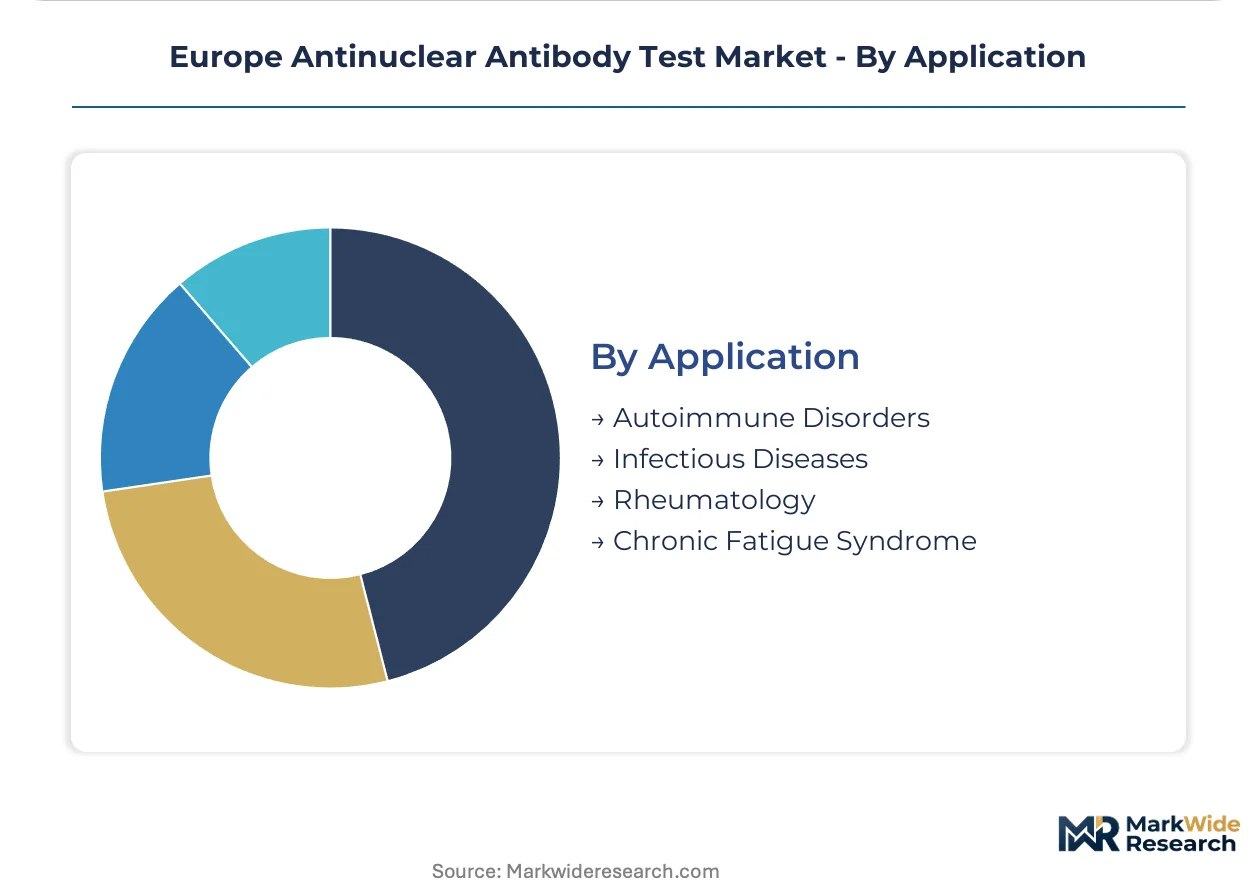
Application:
Clinical indication determines reimbursement tier and testing frequency, with autoimmune disorders commanding premium diagnostic pathways against lower-intensity screening applications.
- Autoimmune Disorders:Systemic lupus erythematosus, mixed connective tissue disease, and related conditions where ANA testing is guideline-mandated for diagnosis and disease activity monitoring. Scandinavian hospital systems are integrating sustainability-weighted procurement for reagent sourcing in this high-volume indication.
- Rheumatology:Specialized clinical setting encompassing autoimmune and inflammatory joint disease management, with treatment monitoring driving repeat testing demand across Western European specialist networks.
- Infectious Diseases:Secondary ANA elevation detection in viral and bacterial infection workups, representing lower-margin opportunistic screening.
- Chronic Fatigue Syndrome:Research and exploratory diagnostic application with limited established reimbursement pathways and variable clinical guideline endorsement.
Revenue concentration aligns with Autoimmune Disorders. Clinical evidence requirements are most stringent for Chronic Fatigue Syndrome applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled immunofluorescence technicians concentrate in German university hospital networks and French diagnostic laboratory clusters, anchoring the regional talent base that sustains premium assay workflows across Western Europe.
Germany
University hospital networks in Heidelberg and Berlin drive automated immunofluorescence platform installations to reduce technician labor intensity. REACH compliance deadlines for chemical reagent registration are compressing supplier qualification timelines. The Baden-Württemberg laboratory cluster is integrating digital pathology connectivity for remote pattern consultation.
France
Diagnostic laboratories in Lyon and Paris are expanding automated ELISA lines for medium-volume autoimmune screening workflows. ANSM oversight of IVDR technical documentation is elevating clinical evidence requirements for CE marking renewal. The Île-de-France hospital network is unbundling service contracts from instrument placements to force reagent pricing transparency.
United Kingdom
NHS trusts in England's Academic Health Science Networks are consolidating procurement through regional purchasing consortia. MHRA post-Brexit regulatory alignment with IVDR frameworks is reshaping product registration pathways for legacy test kits. Greater Manchester hospital laboratories are adopting camera-agnostic imaging platforms to modularize infrastructure investments.
Italy
Rheumatology clinics in Milan and Rome are adopting rapid assay formats for same-day patient screening. National reimbursement recalibrations for decentralized testing are expanding point-of-care access outside centralized laboratory queues. The Lombardy diagnostic network is piloting telemedicine-integrated sampling models for remote patient monitoring.
Spain
Private rheumatology practices in Madrid and Barcelona are deploying point-of-care testing to bypass public laboratory wait times. Regional health authority procurement frameworks are weighting sustainability criteria for reagent sourcing under EU Green Deal alignment. The Catalonia hospital system is connecting ANA workstations to enterprise imaging systems for AI-assisted pattern classification.
Europe Antinuclear Antibody Test Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European ANA test landscape, with automated platform manufacturers absorbing heavy imaging hardware investments while rapid assay developers outsource manufacturing to contract reagent facilities. The market structure tilts toward consolidation around immunofluorescence system vendors with established hospital network relationships. Three archetypes dominate: integrated platform manufacturers, specialty confirmatory panel suppliers, and multiplex assay developers. Competitive moves concentrate on IVDR compliance portfolio restructuring and digital pathology middleware partnerships to secure enterprise imaging contracts.
Among Germany-based diagnostics specialists, EUROIMMUN Medizinische Labordiagnostika AG anchors the automated immunofluorescence tier through university hospital network relationships. Thermo Fisher Scientific Inc. occupies a position exemplifying the multiplex ELISA development archetype with extensive R&D intensity. Trinity Biotech Ireland represents the specialty confirmatory panel segment, sustaining pricing power through niche Western blot applications amid reimbursement pressure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Trinity Biotech Ireland |
| EUROIMMUN Medizinische Labordiagnostika AG |
| Bio-Rad Laboratories, Inc. |
| Grifols S.A. |
| Erba Diagnostics |
| Inova Diagnostics, Inc. |
| ZEUS Scientific, Inc. |
| Immuno Concepts |
| Others |
Value Network & Pricing Analysis
Fluorochrome-conjugated secondary antibody pricing indices in Germany and the United States cascade through three distinct procurement tiers, with REACH-registered reagent suppliers commanding premium positioning against non-compliant competitors facing exclusion from EEA hospital networks.
Pricing Analysis
Bundled instrument-service contracts are unbundling across United Kingdom NHS trusts and French hospital networks, forcing manufacturers to compete on transparent reagent pricing rather than capital equipment subsidies. Three-tier pricing structure across premium immunofluorescence systems, standard ELISA platforms, and economy rapid assay kits reflects certification grade and automation level differentiation. Cost compression in economy rapid test tiers is intensifying because Italian and Spanish rheumatology clinics are consolidating volume through regional purchasing cooperatives. Diagnostic laboratories in Germany exhibit lowest price sensitivity due to university hospital network insulation, while independent laboratories in France face acute margin pressure from regional consolidation.
Supply Chain Analysis
HEp-2 cell substrate supply rests on German and United States specialty biotechnology manufacturers, with fluorochrome-conjugated secondary antibodies drawing from a concentrated base of chemical reagent producers in Germany. Critical dependencies include purified nuclear antigen preparations, stabilized cell culture media, and precision-manufactured slide substrates. Single-source vulnerability concentrates in HEp-2 substrate manufacturing, where qualified alternative suppliers require 18-24 month validation cycles under IVDR Article 56 performance documentation. Distribution runs through regional laboratory consortia in Germany and France, with direct manufacturer relationships dominating hospital network procurement and third-party distributors serving fragmented diagnostic laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe antinuclear antibody test market functions as a regulatory compounder where IVDR compliance deadlines are accelerating replacement demand for legacy test kits across EEA markets.
For Market Incumbents: Anticipate notified body capacity constraints compressing CE marking renewal timelines by securing early technical documentation submissions for immunofluorescence platform portfolios. Consolidate service contract recapture through digital pathology middleware partnerships that lock hospital networks into proprietary imaging ecosystems. IVDR performance study cost escalation threatens smaller competitors with portfolio rationalization, creating acquisition opportunities for well-capitalized platform manufacturers.
For New Entrants and Emerging Players: Decentralized rheumatology clinics in Spain and Italy represent the most penetrable buyer archetype, underserved by incumbent focus on centralized laboratory automation. Rapid assay formats with same-day result capability bypass established vendor relationships in these markets. Go-to-market execution should prioritize telemedicine-integrated sampling models that align with Lombardy diagnostic network pilots and emerging remote patient monitoring reimbursement frameworks.
For Investors and Strategic Acquirers: Consolidation pressure builds where IVDR compliance expenditures exceed 15% of revenue for specialty confirmatory panel suppliers with limited product diversification. Long-term viability favors automated platform manufacturers with installed base expansion capability and recurring reagent revenue streams. Acquisition target archetype: niche Western blot confirmatory panel developers with established rheumatology specialist relationships but subscale quality management systems. The signal to watch is ANSM and BfArM enforcement discretion on legacy kit market withdrawal timelines, which will determine competitive clearing speed.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Restructuring | CE marking renewal pathways under EMA oversight require expanded autoimmune disease population performance studies. |
| Digital Pathology Middleware Development | Camera-agnostic platform integration with hospital information systems secures enterprise imaging contracts in Netherlands and Belgium. |
| Point-of-Care Rapid Assay Launch | Decentralized rheumatology clinic penetration in Spain and Italy bypasses centralized laboratory queue constraints. |
| REACH-Compliant Reagent Sourcing | Full substance registration secures preferred vendor status with Scandinavian sustainability-weighted procurement frameworks. |
| AI-Assisted Pattern Classification Partnership | Algorithm licensing agreements with university hospital networks reduce skilled technician dependency in German diagnostic laboratories. |
Research Methodology
Direct dialogue with diagnostic laboratory directors, hospital procurement committee chairs, rheumatology clinic operators, and IVD regulatory affairs specialists grounded qualitative insights, validated against EMA IVDR guidance documents, ANSM technical documentation requirements, REACH substance registration databases, and hospital procurement contract disclosures. Bottom-up and top-down triangulation cross-checked manufacturer shipment data with laboratory instrument installation records and regional health authority reimbursement filings.
Bottom-up modeling segmented volume and value across immunofluorescence, ELISA, Western blot, and rapid test product types, further disaggregated by hospital, diagnostic laboratory, research institute, and home care end-user channels. CAGRs were derived from installed base expansion rates, replacement demand cycles, and reimbursement trajectory assumptions across the projection horizon. Industry-specific forecast inputs included IVDR transition timeline enforcement patterns and digital pathology adoption curves in German university hospital networks.
Inputs from notified body technical documentation review schedules and regional purchasing consortium contract awards were available through the study window; gaps in real-time laboratory capacity utilization data introduce uncertainty bands around point-of-care testing penetration assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement discretion and reimbursement recalibration timing. Regulatory deadline delays, supply chain disruptions in fluorochrome reagent sourcing, or accelerated AI pattern recognition adoption could materially revise trajectory projections. A small set of triggers—ANSM legacy kit withdrawal enforcement, NHS England procurement framework unbundling completion, and German university hospital digital pathology tender awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Global Rapid Diagnostic Kits Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
D-Dimer Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market