
 Cancer Diagnostics Market | 2026-2036
Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Diagnostics Market Analysis
Buyer concentration among hospital networks is expanding as integrated delivery systems consolidate oncology service line procurement across multiple sites. Thermo Fisher Scientific leverages its end-to-end workflow solutions to anchor molecular diagnostics contracts with large health systems. Illumina competes through proprietary NGS platform ecosystems that lock in sequencing volume commitments. QIAGEN specializes in sample preparation automation that sustains recurring consumable revenue streams.
Cancer diagnostics encompasses laboratory and imaging methodologies that detect malignant cellular changes through biomarker analysis, histopathological examination, or radiological visualization, with sensitivity thresholds often measured at the picogram-per-milliliter level for circulating tumor DNA assays. The primary commercial purpose centers on enabling stage-appropriate therapeutic intervention decisions while monitoring treatment response and recurrence risk. Molecular diagnostics captures expanding margin pools as payers gradually accept genomic profiling for therapy selection, while imaging tests retain volume dominance in initial staging workflows. Blood tests represent the fastest-expanding category as liquid biopsy platforms displace tissue-dependent workflows in monitoring applications.
FDA premarket approval pathways and EMA CE marking requirements under the In Vitro Diagnostic Medical Devices Regulation shape product development timelines and commercial access conditions for novel assay platforms. The country's national pharmaceutical regulator in China accelerates local approval reviews for companion diagnostics tied to domestically manufactured oncology therapies. Stakeholders must monitor reimbursement coding decisions for multi-cancer early detection tests as these determinations will dictate accessible addressable market boundaries.
Market Dynamics
Hospital network consolidation is compressing vendor negotiation cycles and favoring platform suppliers capable of anchoring multi-site molecular diagnostics contracts through integrated workflow solutions rather than standalone assay sales.
Growth Catalysts
- Population-based screening mandates:Germany, China, and the United States are expanding reimbursement coverage for multi-cancer early detection tests, creating volume commitments that de-risk platform investments for diagnostic manufacturers.
- FDA Breakthrough Device designation:Accelerated review pathways for liquid biopsy technologies are compressing commercialization timelines from validation to reimbursement coding by twelve to eighteen months.
- NGS platform standardization:Sequencing volume commitments locked into proprietary ecosystems are generating predictable consumable revenue streams that fund R&D for next-generation assay panels.
Market Restraints
- Reagent supply concentration:Polymerase enzymes and fluorescent dyes for PCR-based assays depend on a narrow base of contract manufacturers clustered in South Korea and Germany, exposing production schedules to single-source failure risk.
- EMA MDR compliance burden:The In Vitro Diagnostic Medical Devices Regulation's enhanced clinical evidence requirements are extending CE marking timelines for novel biomarker assays by twenty-four to thirty-six months.
- Technical sensitivity floors:Circulating tumor DNA detection at picogram-per-milliliter thresholds remains vulnerable to pre-analytical variables including collection tube chemistry and transport temperature excursions.
Strategic Opportunities
- Companion diagnostic localization:China's NMPA is fast-tracking approval reviews for assays tied to domestically manufactured oncology therapies, creating first-mover advantages for localized manufacturing partnerships.
- AI-augmented pathology:Machine learning classification of histopathological images is converging with digital slide scanning infrastructure to automate routine case triage in high-volume hospital networks.
- Direct-to-physician distribution:Specialty oncology practices are bypassing traditional laboratory service intermediaries through direct platform placement models that capture margin previously allocated to reference lab networks.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation pipelines require computational biologists trained in both oncology genomics and regulatory submission standards, a skill intersection with limited supply in European and North American labor markets.
- Legacy LIS integration friction:Hospital information systems built on decades-old architectures resist API-based connectivity with cloud-native sequencing platforms, forcing expensive middleware development or manual workflow workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Diagnostics Market |
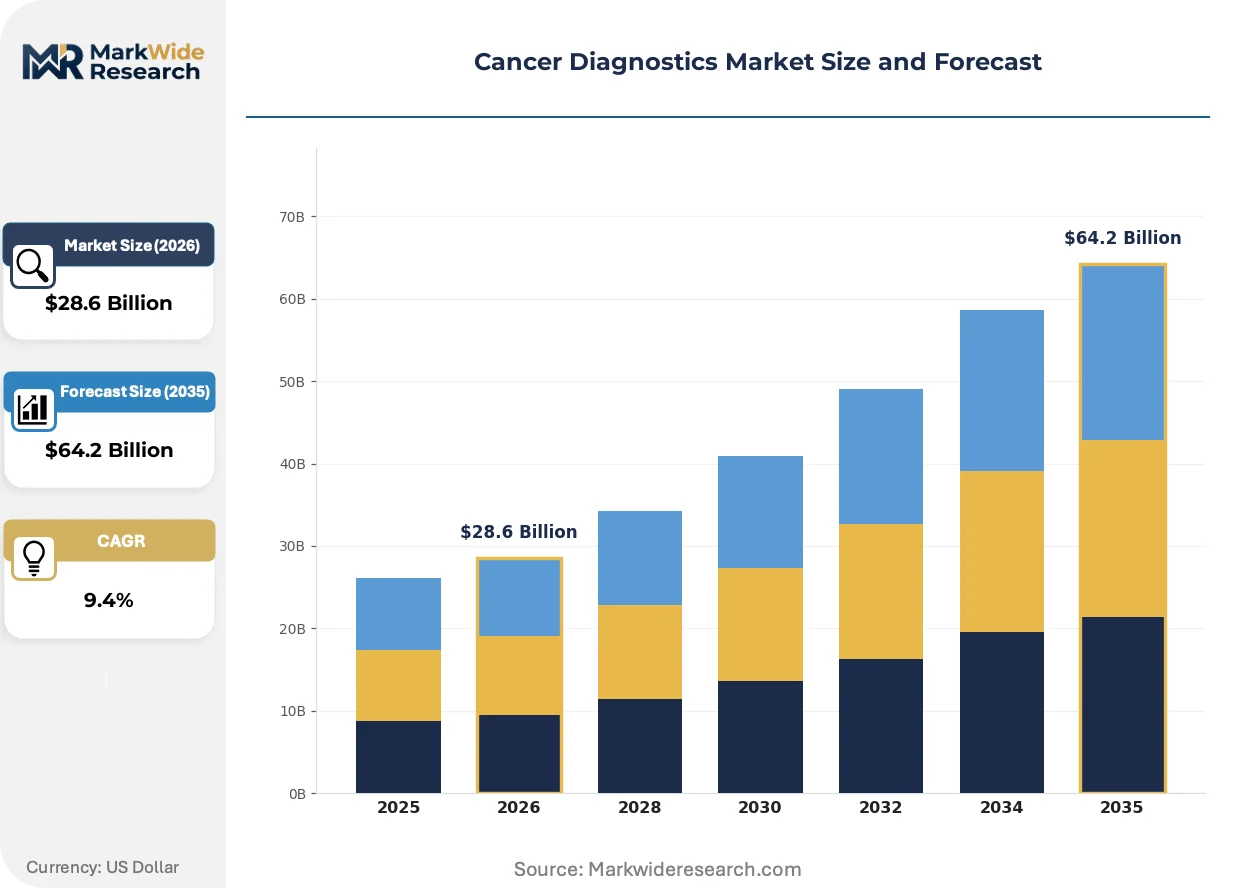
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Tests, Biopsy, Blood Tests, Molecular Diagnostics Technology: CT Scan, MRI, PET Scan, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Abbott Laboratories, Illumina, Inc., Bio-Rad Laboratories, Inc., QIAGEN N.V., Agilent Technologies Inc., Becton, Dickinson and Company, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Diagnostics Market Emerging Trajectories
Liquid biopsy platforms are rewriting competitive boundaries by enabling serial monitoring without tissue re-biopsy, while regulatory frameworks race to catch up with analytical performance claims.
Next-generation sequencing-based minimal residual disease testing is overtaking flow cytometry and allele-specific PCR in post-treatment surveillance protocols for hematologic malignancies. Major academic medical centers in the United States and Germany are adopting these platforms for routine clinical use. The technology is overtaking established monitoring modalities by detecting relapse signals six to twelve months earlier than imaging or protein biomarker elevation.
The EMA's In Vitro Diagnostic Medical Devices Regulation is imposing clinical performance study requirements that exceed FDA premarket approval evidentiary standards for novel biomarker categories. Manufacturers must now generate prospective diagnostic accuracy data across multiple independent clinical sites before CE marking. Oncology assay developers are responding by front-loading European clinical trials and delaying commercial launches to synchronize regulatory submissions.
Integrated delivery systems are consolidating oncology service line procurement under centralized value analysis committees rather than allowing individual hospital laboratories to negotiate standalone contracts. Specialty distributors and manufacturer direct sales teams are displacing independent laboratory supply intermediaries in high-volume accounts. This concentration is most visible in United States metropolitan markets where three-hospital systems control referral networks exceeding five hundred thousand covered lives.
Cancer Diagnostics Market Segmentation
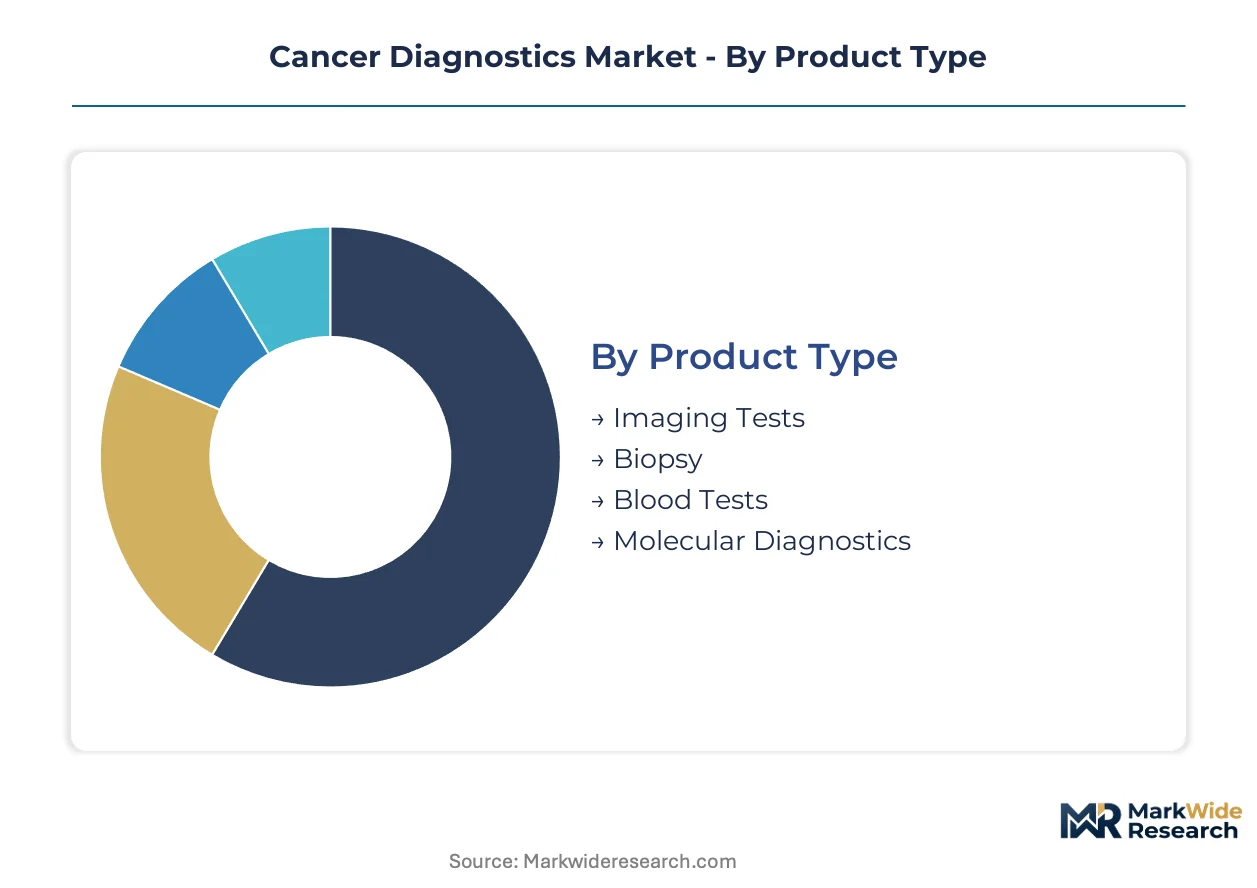
Segmentation in cancer diagnostics reveals divergent margin structures and procurement patterns across product categories. Hospital networks prioritize platform consolidation while specialty laboratories chase assay specialization, creating distinct competitive arenas within the same therapeutic domain.
Product Type:
Buyers in this category differentiate by workflow integration requirements versus standalone test flexibility.
- Imaging Tests:Radiological visualization systems including CT, MRI, and PET modalities generate the highest procedure volumes in initial cancer staging protocols. United States hospital networks dominate procurement, driven by Medicare reimbursement stability for anatomical tumor characterization and treatment planning.
- Blood Tests:Liquid biopsy platforms detect circulating tumor DNA and protein biomarkers at picogram-per-milliliter sensitivity thresholds. China and Germany are expanding population-based screening programs, creating volume commitments that de-risk manufacturer platform investments.
- Biopsy:Tissue acquisition and histopathological examination remains the diagnostic gold standard for definitive malignancy confirmation.
- Molecular Diagnostics:Genomic profiling assays command premium pricing as payers gradually accept therapy selection applications.
Imaging tests lead volumes today; blood tests are gaining share fastest.
Technology:
Procurement decisions here hinge on capital intensity tolerance versus consumable revenue predictability.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable comprehensive genomic profiling from minimal nucleic acid inputs. Academic medical centers in the United States and Germany lock in sequencing volume commitments through proprietary ecosystem contracts that generate predictable consumable revenue streams.
- CT Scan:Computed tomography systems deliver rapid anatomical imaging with sub-millimeter spatial resolution for tumor localization and metastasis detection. Hospital networks in China prioritize CT platform standardization across consolidated procurement contracts.
- MRI:Magnetic resonance imaging provides superior soft-tissue contrast without ionizing radiation exposure.
- PET Scan:Positron emission tomography functional imaging quantifies metabolic activity for treatment response assessment.
CT scan installations dominate current infrastructure; NGS is climbing the fastest.
End User:
Site-of-care preferences separate centralized laboratory efficiency from point-of-care speed requirements.
- Hospitals:Integrated delivery systems consolidate oncology service line procurement under centralized value analysis committees rather than allowing individual laboratories to negotiate standalone contracts. United States metropolitan three-hospital systems control referral networks exceeding five hundred thousand covered lives.
- Diagnostic Laboratories:Reference lab networks process high-throughput screening volumes with automated sample preparation workflows. Germany's statutory health insurance system reimburses centralized laboratory testing at standardized tariff rates.
- Research Institutions:Academic medical centers validate novel biomarker assays before clinical translation.
- Outpatient Clinics:Specialty oncology practices bypass traditional laboratory intermediaries through direct platform placement models.
Hospitals anchor current demand; outpatient clinics show the steepest expansion trajectory.
Application:
Disease-specific testing volumes correlate with population screening program maturity and therapeutic pipeline activity.
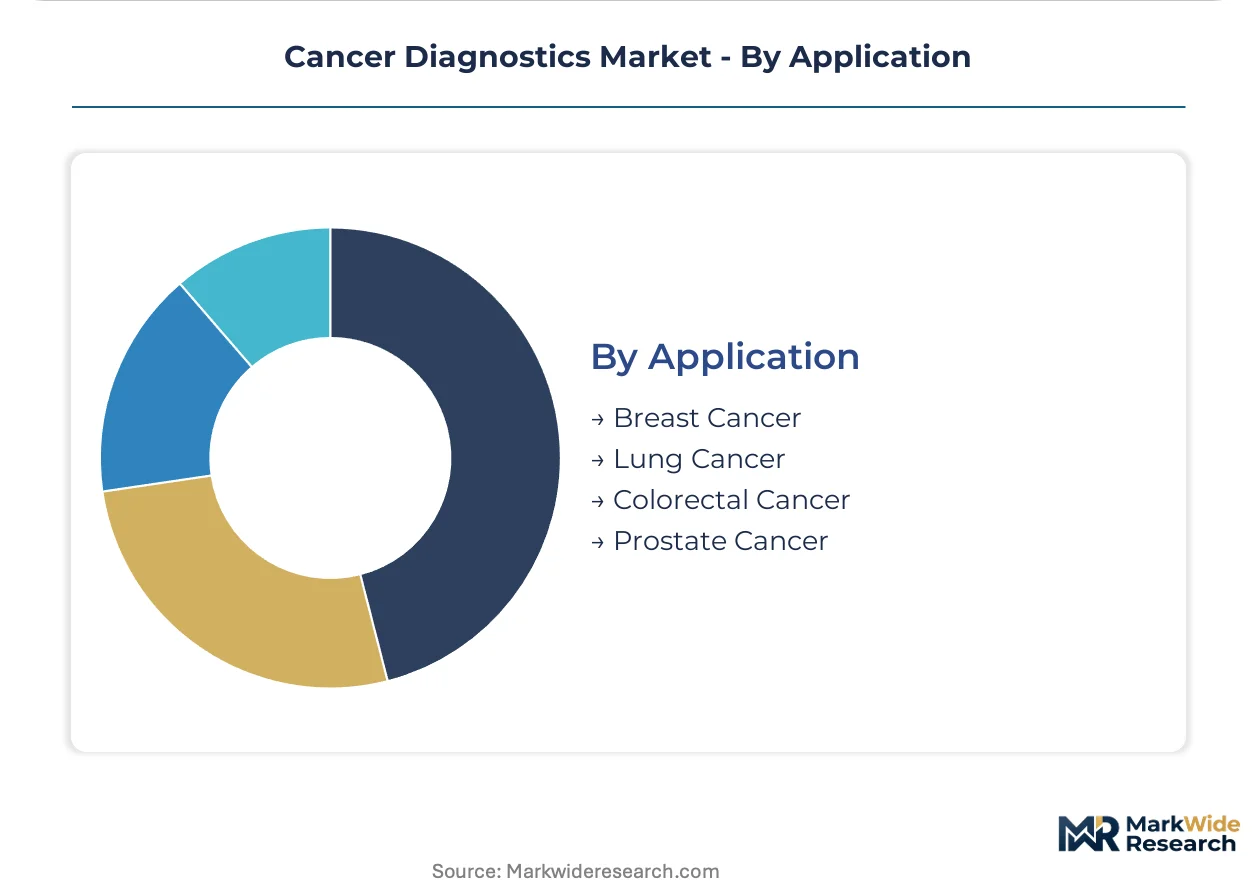
- Breast Cancer:Mammography and supplemental MRI screening programs drive the highest annual procedure volumes among solid tumor applications. The United States Preventive Services Task Force mandates biennial screening for women aged 50-74, creating guaranteed demand baselines.
- Lung Cancer:Low-dose CT screening for high-risk smokers and liquid biopsy monitoring for targeted therapy resistance are displacing traditional cytology workflows. China's national cancer control program prioritizes lung cancer early detection in urban populations with heavy tobacco exposure histories.
- Colorectal Cancer:Fecal immunochemical testing and colonoscopy surveillance generate substantial screening volumes in insured populations.
- Prostate Cancer:PSA testing controversies have shifted demand toward multiparametric MRI and genomic risk stratification assays.
Breast cancer applications command the largest installed base; lung cancer is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's population-based screening programs generate volume commitments that outpace Germany's statutory reimbursement expansion, while the United States anchors premium-priced molecular diagnostics adoption through Medicare coverage stability.
United States
Integrated hospital networks in metropolitan markets consolidate procurement for oncology service lines exceeding five hundred thousand covered lives. FDA Breakthrough Device designation compresses liquid biopsy commercialization timelines by twelve to eighteen months. The Greater Boston and San Francisco Bay Area clusters anchor NGS platform development and companion diagnostic validation.
Germany
Statutory health insurance reimbursement for multi-cancer early detection tests creates predictable demand baselines for molecular diagnostics manufacturers. EMA MDR compliance requirements extend CE marking timelines by twenty-four to thirty-six months for novel biomarker assays. The Rhine-Ruhr and Munich metropolitan regions concentrate reference laboratory processing capacity and digital pathology infrastructure deployment.
China
Urban populations with heavy tobacco exposure histories drive lung cancer early detection program expansion through low-dose CT and liquid biopsy monitoring. NMPA fast-tracks approval reviews for companion diagnostics tied to domestically manufactured oncology therapies. The Yangtze River Delta and Pearl River Delta clusters concentrate in-vitro diagnostic manufacturing and NGS platform assembly operations.
Japan
Aging demographics and universal health coverage sustain high procedure volumes for gastric and colorectal cancer screening protocols. PMDA regulatory frameworks emphasize clinical performance validation for genomic profiling assays prior to reimbursement listing. The Kanto region around Tokyo anchors centralized laboratory networks processing high-throughput screening volumes.
United Kingdom
NHS England's targeted screening program expansion creates procurement opportunities for AI-augmented pathology platforms. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for innovative diagnostic technologies. The London-Oxford-Cambridge triangle concentrates academic medical center validation studies and digital health startup formation.
Cancer Diagnostics Market Vendor Landscape
United States producers anchor the premium instrumentation tier; European specialists hold consumables and sample preparation automation. The vendor base organizes around three strategic archetypes: end-to-end workflow integrators, proprietary platform ecosystem builders, and consumable-focused automation suppliers. Consolidation pressures favor suppliers capable of anchoring multi-site contracts through integrated solutions rather than standalone assay sales. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic licensing arrangements for regulatory pathway acceleration.
Within the end-to-end workflow tier, Thermo Fisher Scientific Inc. and Illumina, Inc. exemplify contrasting ecosystem strategies. Thermo Fisher Scientific anchors molecular diagnostics contracts through integrated workflow solutions spanning sample preparation to data analysis. Illumina occupies a position within proprietary NGS platform ecosystems that lock in sequencing volume commitments through consumable revenue predictability. QIAGEN N.V. sits within the consumable automation archetype, specializing in sample preparation technologies that sustain recurring revenue streams independent of capital equipment refresh cycles.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Illumina, Inc. |
| Bio-Rad Laboratories, Inc. |
| QIAGEN N.V. |
| Agilent Technologies Inc. |
| Becton, Dickinson and Company |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
NGS platform premiumization versus consumable commoditization bifurcates procurement economics across hospital networks and reference laboratories, with proprietary ecosystem lock-in sustaining margin capture in the United States while standardized reagent sourcing compresses price floors in China and Germany. This divergence manifests in divergent supply chain configurations: premium tier vendors anchor multi-site contracts through integrated workflow solutions, whereas economy tier suppliers compete on polymerase enzyme spot pricing and fluorescent dye bulk procurement efficiency.
Pricing Analysis
Capacity additions in South Korea and Germany are reshaping price floors for PCR reagents and fluorescent dyes as contract manufacturers expand polymerase enzyme fermentation capacity. Three-tier pricing structure across premium, standard, and economy levels separates Illumina's proprietary consumable ecosystem from QIAGEN's sample preparation automation and commodity-grade assay components. Cost compression in economy-grade reagents is intensifying because Chinese manufacturers are scaling nucleic acid extraction kit production for domestic screening programs. Academic medical centers in the United States and Germany exhibit lowest price sensitivity due to locked-in sequencing volume commitments, while outpatient clinics in China demonstrate highest sensitivity to per-test consumable costs.
Supply Chain Analysis
CE marking and FDA premarket approval requirements gate upstream supplier qualification, with polymerase enzymes and fluorescent dyes for PCR-based assays drawing from concentrated contract manufacturing bases in South Korea, Germany, and select Chinese provinces. Raw material dependencies center on recombinant Taq polymerase, fluorescent reporter dyes, and specialized collection tube chemistries preserving circulating tumor DNA integrity. Single-source vulnerability persists for high-fidelity polymerase formulations protected by narrow patent estates. Distribution runs through specialty laboratory supply intermediaries in fragmented European markets, whereas direct manufacturer-to-hospital contracting dominates consolidated United States metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Breakthrough Device designation and EMA MDR compliance timelines directly determine commercialization velocity and platform adoption curves.
For Market Incumbents: To counter liquid biopsy platform commoditization by emerging Chinese manufacturers, anchor multi-site molecular diagnostics contracts through end-to-end workflow integration spanning sample preparation to bioinformatics interpretation. Deepen backward integration into polymerase enzyme production to insulate consumable margins from South Korean supplier concentration risk. Prioritize companion diagnostic co-development partnerships with oncology therapy developers to secure regulatory exclusivity windows. For New Entrants and Emerging Players: The premium-economy price-point gap in AI-augmented pathology platforms creates white-space entry opportunity for machine learning classification tools targeting high-volume hospital networks in Germany and the United Kingdom. Target outpatient oncology clinics bypassing traditional laboratory intermediaries through direct platform placement models. Pursue NMPA fast-track approval pathways for companion diagnostics tied to domestically manufactured Chinese oncology therapies as the most penetrable regulatory entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital network procurement centralization exceeds five hundred thousand covered lives and demands integrated workflow solutions beyond standalone assay capabilities. Long-term viability centers on platform suppliers with locked-in consumable revenue streams and proprietary bioinformatics ecosystems. Acquisition target archetype: consumable automation specialists with sample preparation technologies sustaining recurring revenue independent of capital equipment refresh cycles. Watch FDA reimbursement coding decisions for multi-cancer early detection tests as the critical inflection signal dictating accessible addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Secures regulatory exclusivity with FDA Breakthrough Device designation for liquid biopsy platforms. |
| AI-Augmented Pathology Platform Launch | Automates histopathological triage in NHS England screening programs requiring digital infrastructure. |
| CE Marking Pathway Acceleration | Front-loads European clinical trials to synchronize EMA MDR submissions with FDA premarket approvals. |
| Hospital System Partnership | Locks in sequencing volume commitments across integrated delivery networks exceeding five hundred thousand lives. |
| Reimbursement Strategy Execution | Captures Medicare coding decisions for multi-cancer early detection tests in United States metropolitan markets. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down reagent manufacturer tracking forms the analytical core, combining primary interviews with hospital laboratory directors, GPO contracts managers, regulatory affairs leads at assay developers, and biomedical engineers with secondary validation through FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement databases. This triangulation approach cross-references platform installation data against consumable shipment records to reconcile reported instrument placements with inferred test volume throughput.
The input-output matrix structures volume projections across technology platform type, end-user site classification, application disease indication, and regional regulatory cluster without prescribing specific annual milestones. Compound annual growth rates derive from elasticity modeling of screening program expansion, reimbursement policy shifts, and platform replacement cycles. Forecast inputs incorporate NGS platform standardization trajectories, liquid biopsy analytical sensitivity improvements, and EMA MDR compliance timeline extensions.
Caveats apply where FDA reimbursement coding decisions for multi-cancer early detection tests or NMPA approval velocity for companion diagnostics could materially shift the outlook. Deviation in hospital network consolidation pace or polymerase enzyme supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market