
 Global Respiratory Diagnostics Market | 2026-2036
Global Respiratory Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Diagnostics Market Foresight
South Korea is tilting toward domestic manufacturing of spirometry and capnography systems through government-backed medical device clusters near Seoul. Koninklijke Philips N.V. leverages its installed base of hospital ventilators to cross-sell connected diagnostic peripherals across European accounts. Thermo Fisher Scientific Inc. anchors its respiratory portfolio on multiplex molecular panels that integrate with existing laboratory automation lines. Abbott Laboratories competes in point-of-care settings with handheld devices that reduce dependence on centralized pulmonary function laboratories.
Respiratory diagnostics encompasses instruments, assays, and software systems that measure lung function, gas exchange efficiency, and pathogen presence in airway specimens. Spirometers quantify forced expiratory volume and forced vital capacity through pressure transducers or ultrasonic flow sensors, generating numerical outputs that pulmonologists use to stage obstructive and restrictive disease. Molecular diagnostics and immunoassays lead technology-based revenue generation due to their specificity for Mycobacterium tuberculosis and emerging viral pathogens, while telemonitoring represents the fastest-expanding modality as home healthcare providers adopt cloud-connected pulse oximeters and peak flow meters. Digital radiography occupies a mature position with stable replacement demand, though margin pools concentrate in software upgrades that embed AI-assisted nodule detection for lung cancer screening workflows.
The FDA's breakthrough device program and the EU Medical Device Regulation reshape product development timelines, with the former compressing premarket review for novel diagnostics and the latter imposing stricter clinical evidence requirements for Class IIa and above respiratory instruments. The WHO's End TB Strategy indirectly stimulates demand for molecular tuberculosis detection by setting country-level targets that require laboratory capacity expansion. Stakeholders must monitor reimbursement parity between laboratory-based and home-based respiratory testing, as payer decisions on remote patient monitoring codes will determine which end user segment captures volume growth.
Market Dynamics
The respiratory diagnostics market is compressing around molecular multiplexing and point-of-care decentralization, as laboratory automation lines and handheld peripherals compete for the same clinical workflow. Pulmonary function testing is fragmenting between hospital-based laboratories and home telemonitoring networks.
Growth Catalysts
- FDA Breakthrough Device Pathway:Compressed premarket review timelines accelerate novel diagnostic platform commercialization in the United States, particularly for tuberculosis and lung cancer screening assays.
- WHO End TB Strategy:Country-level detection targets mandate laboratory capacity expansion across high-burden nations, directly stimulating molecular tuberculosis test procurement.
- Home Healthcare Networks:Cloud-connected pulse oximeters and peak flow meters are capturing chronic disease management volumes previously concentrated in hospital pulmonary function laboratories.
Market Restraints
- EU MDR Clinical Evidence Requirements:Stricter documentation demands for Class IIa and above respiratory instruments extend development timelines and inflate regulatory compliance costs.
- Reimbursement Parity Gaps:Divergent payer coverage between laboratory-based and home-based respiratory testing creates volume uncertainty for device manufacturers.
- Input Concentration in Sensor Supply:Ultrasonic flow sensors and pressure transducers for spirometry face concentrated sourcing from East Asian component suppliers.
Strategic Opportunities
- South Korean Manufacturing Clusters:Government-backed medical device hubs near Seoul offer domestic production incentives for spirometry and capnography systems serving Asian markets.
- AI-Assisted Nodule Detection:Software upgrades embedding machine learning into digital radiography workstations command premium pricing in lung cancer screening workflows.
- Telemonitoring Code Expansion:Emerging remote patient monitoring reimbursement categories in the United States and Germany create channel arbitrage for cloud-connected diagnostic peripherals.
Industry Challenges
- Cross-Platform Integration Complexity:Molecular diagnostic panels must interface with heterogeneous laboratory information systems and automation lines, extending validation cycles.
- Specialized Respiratory Pathologist Shortage:Interpretation of complex pulmonary function test outputs and molecular assay results faces workforce constraints in secondary care settings.
- Legacy Equipment Retrofit Costs:Hospital pulmonary function laboratories face capital-intensive upgrades to accommodate connected diagnostic peripherals and cloud data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Diagnostics Market |
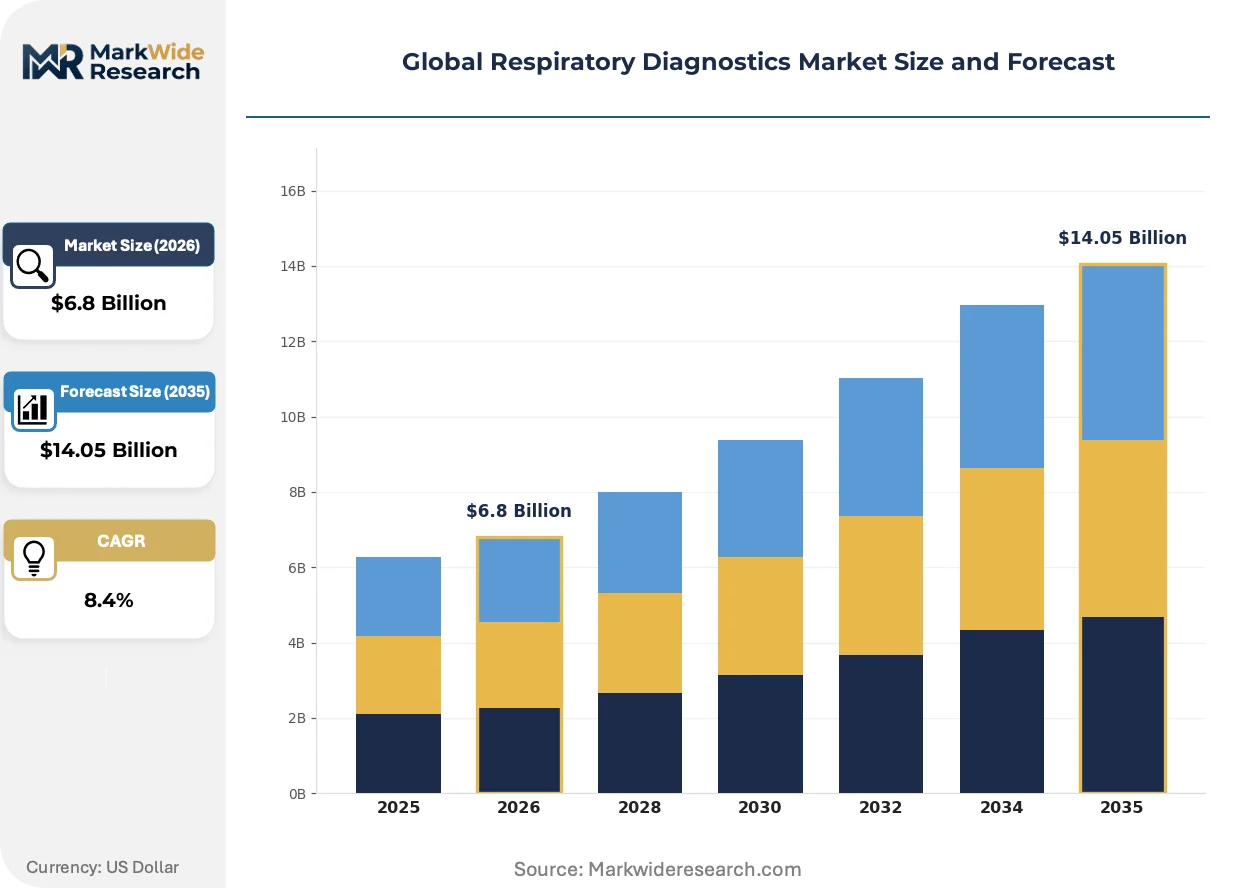
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirometers, Pulse Oximeters, Gas Analyzers, Peak Flow Meters, Bronchial Challenge Testers Technology: Molecular Diagnostics, Immunoassays, Digital Radiography, Capnography, Telemonitoring Application Area: Chronic Obstructive Pulmonary Disease, Asthma Monitoring, Tuberculosis Detection, Pulmonary Fibrosis Evaluation, Lung Cancer Screening End User Segment: Clinical Laboratories, Diagnostic Centers, Research Institutes, Home Healthcare Providers, Occupational Health Facilities |
| Companies Covered | Koninklijke Philips N.V., Becton, Dickinson and Company, Abbott Laboratories, Thermo Fisher Scientific Inc., GE HealthCare, Bio-Rad Laboratories, Inc., Medtronic, Nihon Kohden Corporation, COSMED srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Diagnostics Market Shifts & Advancements
Respiratory diagnostics is bifurcating between high-complexity molecular platforms and simplified point-of-care devices, with software-defined functionality displacing hardware-centric product architectures. Connectivity standards and AI-assisted interpretation are becoming primary differentiation vectors.
Multiplex molecular panels are hybridizing tuberculosis detection with viral respiratory pathogen identification on single-instrument workflows. Hospital core laboratories in the United States and Germany are consolidating previously separate assay menus onto automated sample-to-answer platforms. This convergence is compressing capital equipment footprints while expanding reimbursable test per-patient yields.
The EU Medical Device Regulation is recalibrating clinical evidence requirements for Class IIa respiratory instruments, with notified bodies demanding expanded patient cohort data for spirometry and capnography clearances. Manufacturers are responding by front-loading clinical studies in European multi-site trials. Pulmonary function testing devices face the steepest compliance cost escalation among respiratory diagnostic categories.
Home healthcare providers are unbundling after-sales service from device procurement, contracting remote technical support and calibration separately from hardware acquisition. This procurement model is displacing traditional capital-plus-service bundled contracts in the United States and Japan. Chronic obstructive pulmonary disease management programs represent the most visible adoption vertical for this purchasing shift.
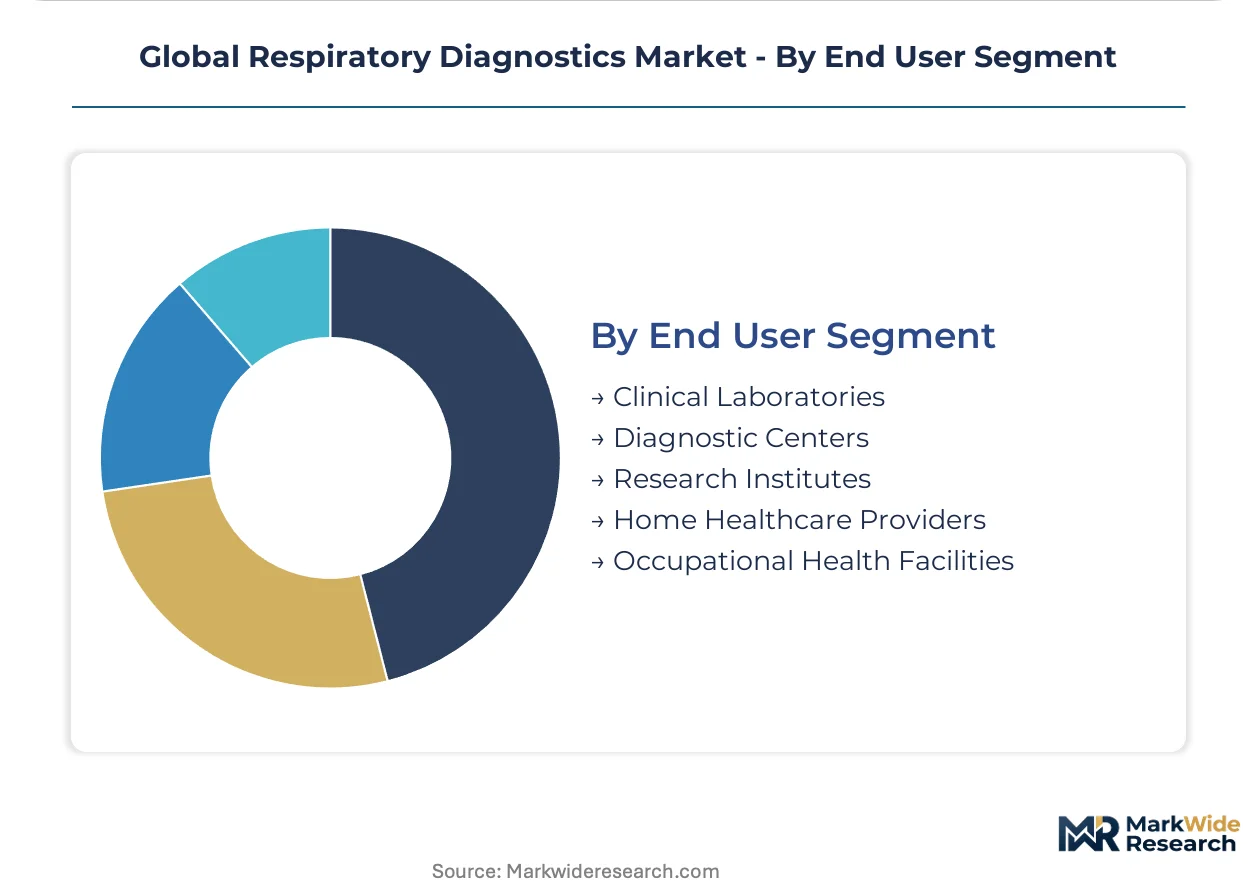
Global Respiratory Diagnostics Market Segmentation
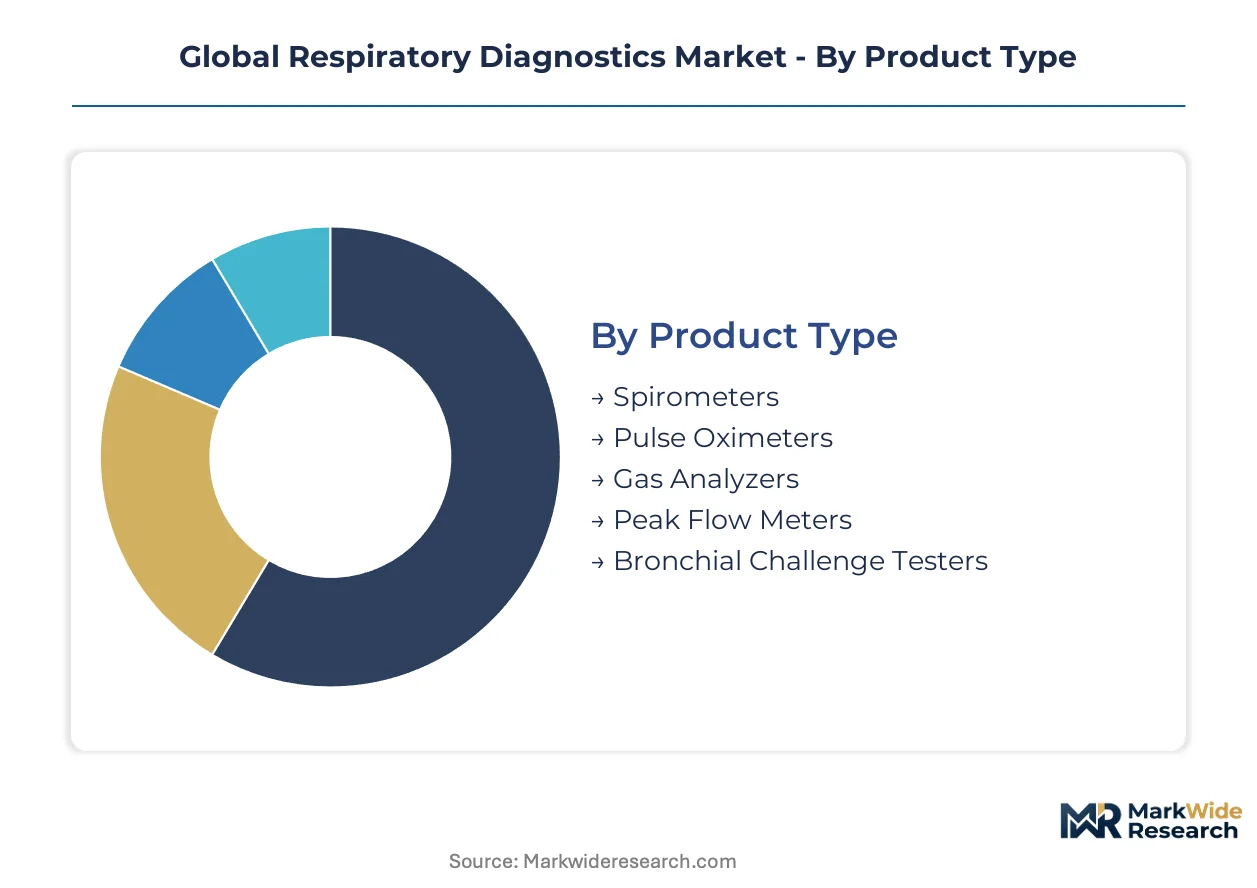
Segmentation in respiratory diagnostics reveals how procurement patterns diverge between capital-intensive hospital laboratories and decentralized home care networks. Understanding these splits exposes where after-sales service contracts concentrate versus where hardware margins compress.
Product Type:
After-sales service intensity varies dramatically across device categories, with hospital-grade spirometers generating recurring calibration revenue while home-use pulse oximeters operate on minimal service attachment.
- Spirometers:Pressure transducer and ultrasonic flow sensor configurations measure forced expiratory volume and forced vital capacity. Pulmonary function laboratories in the United States and Germany anchor replacement demand as aging installed bases require connectivity upgrades for cloud data architectures.
- Pulse Oximeters:Photoplethysmography-based devices measure arterial oxygen saturation non-invasively. Home healthcare providers in Japan capture volume growth as remote patient monitoring reimbursement codes expand, though service revenue per unit remains minimal compared to clinical-grade alternatives.
- Gas Analyzers:Electrochemical and infrared absorption systems quantify blood gas parameters and respiratory gas composition in critical care settings.
- Peak Flow Meters:Mechanical and digital variants track maximum expiratory flow rates for asthma self-management programs.
- Bronchial Challenge Testers:Methacholine and mannitol delivery systems assess airway hyperresponsiveness in specialized pulmonary function laboratories.
Spirometers hold the largest share; momentum sits with pulse oximeters.
Technology:
Cost tier stratification separates high-complexity molecular platforms requiring substantial laboratory infrastructure from handheld point-of-care devices suited to decentralized deployment.
- Molecular Diagnostics:Nucleic acid amplification and hybridization techniques detect Mycobacterium tuberculosis and viral respiratory pathogens with high specificity. Automated sample-to-answer platforms in United States hospital core laboratories consolidate previously separate assay menus, expanding reimbursable test per-patient yields while compressing capital equipment footprints.
- Telemonitoring:Cloud-connected peripherals transmit pulmonary function data and oxygen saturation readings to centralized monitoring centers. German home healthcare networks adopt these systems fastest as statutory health insurance funds expand remote patient monitoring coverage for chronic obstructive pulmonary disease management.
- Immunoassays:Antibody-based detection methods identify respiratory antigens in lateral flow and enzyme-linked formats.
- Digital Radiography:Computed and direct radiography systems capture chest imaging for structural lung assessment.
- Capnography:Infrared spectroscopy measures end-tidal carbon dioxide for procedural sedation and respiratory monitoring.
Molecular diagnostics commands premium pricing; telemonitoring is expanding most quickly.
Application Area:
Application segmentation tracks how diagnostic workflows align with disease-specific reimbursement pathways and screening program mandates across healthcare systems.
- Chronic Obstructive Pulmonary Disease:Spirometry-based diagnosis and monitoring dominate clinical workflows. United States pulmonology practices drive volume as Medicare reimbursement for annual lung function testing stabilizes, though home telemonitoring networks increasingly capture longitudinal monitoring.
- Tuberculosis Detection:Molecular and immunoassay-based screening targets high-burden populations. WHO End TB Strategy targets directly stimulate procurement in South Africa and India as national tuberculosis programs expand laboratory capacity to meet country-level detection benchmarks.
- Asthma Monitoring:Peak flow measurement and fractional exhaled nitric oxide testing support inflammatory assessment.
- Pulmonary Fibrosis Evaluation:High-resolution computed tomography correlation with pulmonary function testing guides interstitial lung disease classification.
- Lung Cancer Screening:Low-dose computed tomography and molecular biomarker testing target high-risk smoking histories.
Chronic obstructive pulmonary disease holds the largest share; tuberculosis detection climbs the fastest.
End User Segment:
Customer type determines purchasing authority complexity, with clinical laboratories consolidating vendor relationships while home healthcare providers fragment procurement across multiple device categories.
- Clinical Laboratories:Hospital-based pulmonary function laboratories and core molecular diagnostics facilities centralize high-complexity testing. United States health system consolidation pushes these sites toward multi-year service contracts with integrated device vendors, embedding calibration and connectivity support into capital agreements.
- Home Healthcare Providers:Durable medical equipment suppliers and chronic disease management programs distribute point-of-care devices. Japanese insurers now reimburse remote monitoring separately from device acquisition, forcing providers to unbundle service contracts and source technical support through independent channels.
- Diagnostic Centers:Independent imaging and respiratory testing facilities operate between hospital and home settings.
- Research Institutes:Academic medical centers and contract research organizations utilize specialized pulmonary function equipment for protocol-driven studies.
- Occupational Health Facilities:Workplace screening programs mandate spirometry for regulatory compliance in hazardous exposure settings.
Clinical laboratories hold the largest share; home healthcare providers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough device designations anchor the United States as the dominant geography, while reimbursement alignment and manufacturing clusters shape competitive positioning across Germany, Japan, and South Korea.
United States
Medicare reimbursement stability for annual lung function testing sustains hospital pulmonary function laboratory demand. The FDA's breakthrough device pathway compresses premarket review timelines for tuberculosis and lung cancer screening assays. Boston and San Francisco anchor molecular diagnostics R&D clusters where automated sample-to-answer platforms consolidate previously separate assay menus.
Germany
Statutory health insurance funds expand remote patient monitoring coverage for chronic obstructive pulmonary disease management. The EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa respiratory instruments. The MedTech cluster around Munich and Erlangen concentrates spirometry and capnography manufacturing serving European hospital accounts.
Japan
Aging demographics drive demand for home-based respiratory monitoring as insurers unbundle device acquisition from technical support contracts. METI standards govern connected medical device cybersecurity and data interoperability. The Osaka-Kobe corridor hosts durable medical equipment suppliers distributing cloud-connected pulse oximeters to chronic disease management programs.
South Korea
Government-backed medical device clusters near Seoul incentivize domestic manufacturing of spirometry and capnography systems. MFDS regulatory harmonization with international standards accelerates market access for locally produced diagnostic peripherals. The Songdo biomedical cluster attracts component suppliers for ultrasonic flow sensors serving Asian markets.
India
The WHO End TB Strategy stimulates procurement as national tuberculosis programs expand laboratory capacity to meet country-level detection benchmarks. CDSCO regulatory pathways for molecular diagnostics face backlog pressures amid import dependency for high-complexity platforms. Hyderabad and Bengaluru concentrate contract research organizations conducting clinical validation studies for multinational device manufacturers.
Global Respiratory Diagnostics Market Competitive Landscape
Capability concentration sits with integrated diagnostics conglomerates; scale advantage sits with diversified medical technology holding companies. The market structures around three tiers: multinational laboratory equipment suppliers, specialized respiratory device manufacturers, and emerging point-of-care platform developers. Strategic moves center on cross-selling connected peripherals into installed ventilator bases and consolidating molecular assay menus onto automated workflows.
Among Netherlands-based diversified health technology conglomerates, Koninklijke Philips N.V. exemplifies the installed-base leverage archetype. United States-based laboratory equipment suppliers Thermo Fisher Scientific Inc. and Abbott Laboratories occupy positions spanning molecular diagnostics and point-of-care decentralization. These three anchors represent distinct competitive vectors: hardware-software integration, high-complexity laboratory automation, and handheld peripheral miniaturization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| GE HealthCare |
| Bio-Rad Laboratories, Inc. |
| Medtronic |
| Nihon Kohden Corporation |
| COSMED srl |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries ultrasonic flow sensors and pressure transducers from East Asian component hubs to European spirometry manufacturers, with freight cost volatility transmitting directly into device pricing tiers and procurement decisions across hospital pulmonary function laboratories.
Pricing Analysis
Geographic price spreads of 15-25% separate United States hospital procurement from Indian national tuberculosis program tenders, with premium-mid-economy pricing differentiation driven by FDA breakthrough device certification and after-sales service bundling. Pricing pressure stems from unbundled procurement models in Japan and Germany where home healthcare providers source technical support independently. Clinical laboratories exhibit lowest price sensitivity due to multi-year capital-plus-service contracts, while emerging market public health programs face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for photoplethysmography sensors and electrochemical gas detection elements centers on semiconductor-grade silicon wafers and specialty polymers from Japan, Germany, and South Korea. Ultrasonic flow sensors for spirometry draw from concentrated MEMS fabrication capacity in Taiwan and South Korea. Single-source vulnerability in infrared spectroscopy components for capnography creates exposure to export licensing delays. Distribution runs through hospital group purchasing organizations in the United States and statutory health insurance tender processes in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of specialized respiratory pathologists capable of interpreting complex pulmonary function test outputs and molecular assay results constrain market expansion more than capital availability or manufacturing capacity.
For Market Incumbents: Pre-empt home telemonitoring network capture by embedding cloud connectivity into legacy spirometer installed bases before unbundled procurement models displace bundled service contracts. Secure backward integration into ultrasonic flow sensor supply through partnerships with Taiwanese MEMS fabricators to defend margin position against component cost volatility. For New Entrants and Emerging Players: Build out AI-assisted nodule detection software modules for digital radiography workstations as the most penetrable white-space target, with lung cancer screening workflows in United States hospital systems offering direct go-to-market access through radiology information system integration partnerships. For Investors and Strategic Acquirers: Point-of-care molecular platform developers with FDA breakthrough device designations and automated sample-to-answer architectures represent the highest-conviction acquisition archetype for long-term viability. Watch reimbursement code expansion for remote patient monitoring in Germany and the United States as the critical inflection signal for home healthcare provider segment profitability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance for Class IIa spirometry compresses development timelines for European market access. |
| Hospital System Partnership | Multi-year service contracts with United States health systems lock in replacement demand and calibration revenue. |
| Software Companion Development | AI-assisted interpretation modules for pulmonary function testing address workforce scarcity in secondary care settings. |
| Reimbursement Strategy | Remote patient monitoring code expansion in German statutory health insurance funds accelerates telemonitoring adoption. |
| Backward Integration | In-house production of ultrasonic flow sensors reduces exposure to East Asian component supply concentration. |
Research Methodology
Initial hypotheses were tested against primary input from hospital pulmonary function laboratory directors, biomedical equipment procurement managers, and molecular diagnostics platform engineers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, and WHO End TB Strategy procurement databases. Bottom-up demand modeling from individual country tuberculosis program expansion targets was triangulated against top-down market sizing from installed base analysis of hospital ventilator and spirometer units.
Demand-supply balance framing anchored the forecast framework, with segmentation across product type, technology tier, application area, and end user segment modeled throughout the projection horizon. CAGRs were derived from regression analysis of historical procurement volumes against reimbursement policy shifts and regulatory pathway acceleration effects. Forecast inputs incorporated WHO country-level detection benchmarks and Medicare remote patient monitoring code expansion timelines.
Stress conditions across EU MDR clinical evidence requirement stringency, East Asian component supply disruption scenarios, and reimbursement parity gap persistence were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CMS Medicare reimbursement rate publications and MFDS medical device approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
Global Immunoassay Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Neglected Tropical Diseases Diagnosis Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Australia in-Vitro Diagnostics Market
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Microdialysis Market
Diagnostics
Europe Molecular Diagnostics Market